
 Secondary Reforming Catalyst Market | 2026-2036
Secondary Reforming Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Reforming Catalyst Market Analytics
Buyer concentration in ammonia and methanol production is decoupling from traditional refinery-centric procurement patterns. Johnson Matthey leverages its hydrogen technology heritage to sustain long-term supply relationships with blue ammonia developers. Haldor Topsoe anchors its position through proprietary reforming technology bundled with catalyst supply. BASF SE competes on manufacturing scale across nickel-based and cobalt-based formulations for steam reforming units.
Secondary reforming catalysts are heterogeneous materials—typically nickel oxide on alumina or magnesium aluminate supports—engineered to convert methane and higher hydrocarbons into synthesis gas at temperatures exceeding 800°C in the presence of steam and oxygen. These catalysts serve the critical function of maximizing hydrogen and carbon monoxide yields while resisting thermal degradation and sulfur poisoning in downstream ammonia, methanol, and Fischer-Tropsch operations. Nickel-based formulations occupy the largest volume share due to their cost-performance balance in high-duty steam reforming service, though platinum-based variants command premium positioning where ultra-low carbon intensity targets apply. Pellet and tablet forms dominate installed capacity, but powder formulations are gaining traction in slurry-phase autothermal reforming pilot units where enhanced surface-area contact improves conversion efficiency.
EPA emissions standards in the United States and REACH registration requirements in Europe are tightening permissible limits on catalyst manufacturing effluents and spent catalyst disposal pathways, directly elevating compliance costs for producers serving these jurisdictions. China's MEE enforces dual carbon goals that compel domestic refiners and chemical producers to select higher-activity, longer-life catalyst systems to reduce regeneration frequency and associated energy consumption. Stakeholders must monitor regulatory divergence between jurisdictions and align product certification strategies accordingly.
Market Dynamics
Blue ammonia project pipelines in the Middle East and North America are recalibrating procurement specifications toward higher-activity, sulfur-resistant catalyst formulations that can sustain extended duty cycles under variable feedstock conditions.
Growth Catalysts
- EPA emissions standards:US refiners face tightening NOx and particulate limits that mandate catalyst upgrades with enhanced thermal stability and lower regeneration frequency.
- China's dual carbon goals:MEE enforcement compels domestic ammonia producers to select longer-life nickel-alumina systems that reduce energy consumption per ton of hydrogen output.
- Hydrogen economy buildout:Fischer-Tropsch synthesis expansions in Saudi Arabia and the United Arab Emirates drive demand for cobalt-promoted formulations optimized for syngas ratio control.
Market Restraints
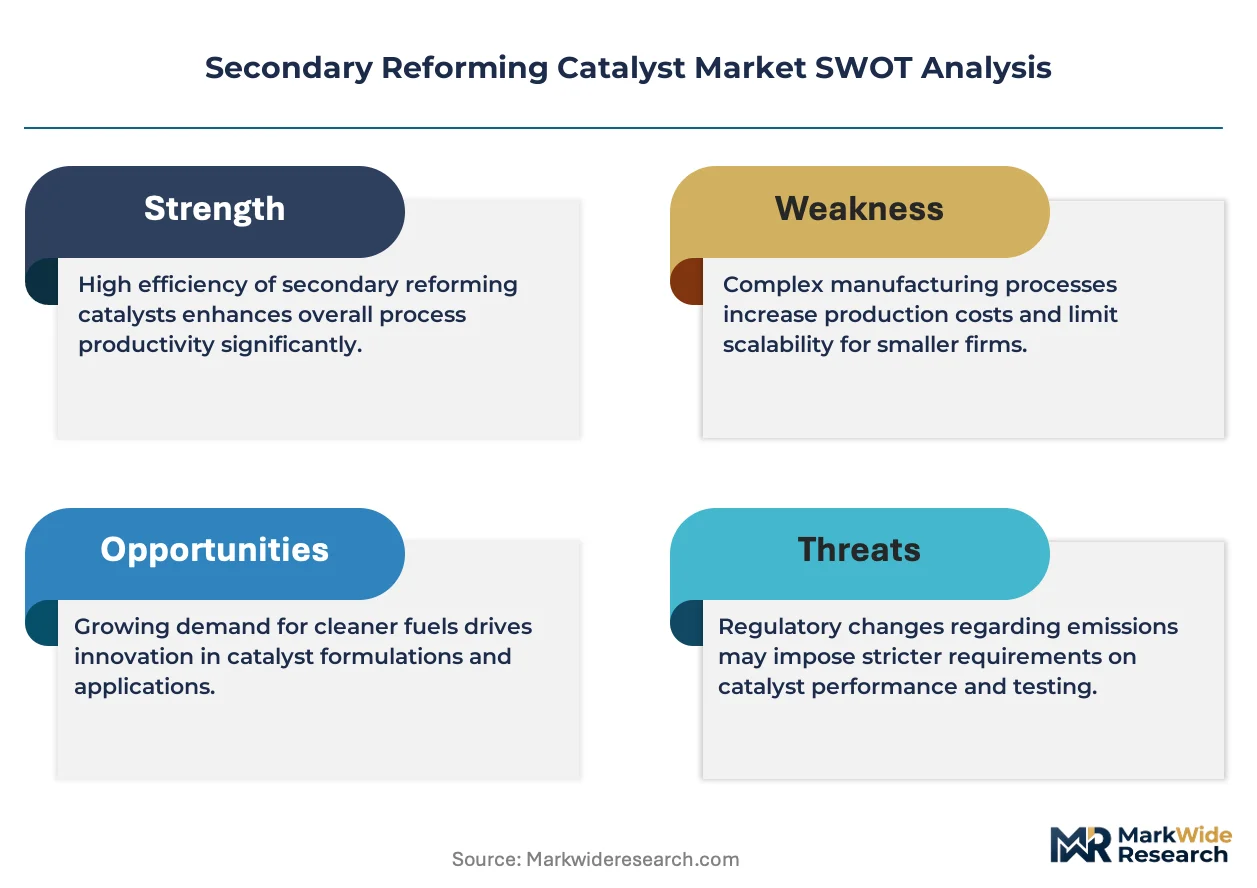
- Nickel price volatility:Primary metal cost swings of 30-40% within single quarters compress margin predictability for catalyst manufacturers locked into fixed-price supply contracts.
- Spent catalyst disposal:REACH registration requirements in Europe impose hazardous waste classification on nickel-laden spent materials, elevating end-of-life handling costs by 15-25% versus other jurisdictions.
- Platinum substitution ceiling:Precious metal formulations remain economically prohibitive for steam methane reforming at scale, capping penetration in cost-sensitive ammonia and methanol units.
Strategic Opportunities
- India's PLI scheme:Domestic manufacturing incentives for urea and complex fertilizers are accelerating greenfield ammonia plant construction requiring full catalyst loadings.
- Autothermal reforming pilots:Slurry-phase powder catalyst configurations are gaining validation in demonstration units where enhanced gas-liquid contact improves methane conversion efficiency.
- Carbon border adjustment:EU CBAM implementation creates preference for EU-certified catalyst suppliers among export-oriented ammonia producers seeking embedded emissions documentation.
Industry Challenges
- High-temperature materials engineering:Scarce expertise in magnesium aluminate spinel support optimization limits domestic catalyst development capabilities outside established manufacturing clusters.
- Proprietary reactor integration:Bundled technology-catalyst supply relationships create switching friction for buyers seeking to unbundle catalyst procurement from process licensing agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Reforming Catalyst Market |
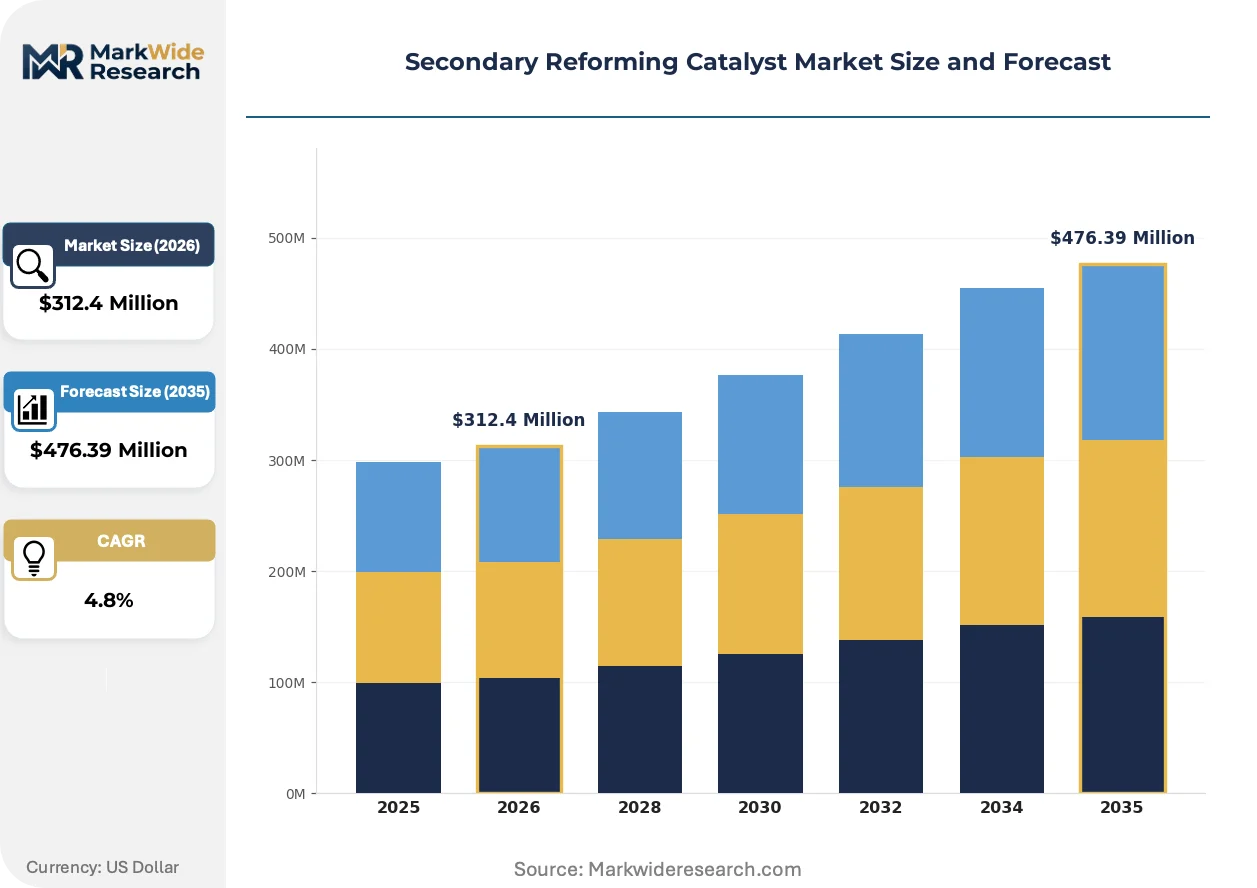
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nickel-based, Cobalt-based, Platinum-based, Others End User: Refining, Chemical Production, Power Generation, Industrial Applications Technology: Steam Reforming, Autothermal Reforming, Catalytic Reforming, Non-catalytic Reforming Form: Pellets, Powder, Granules, Tablets |
| Companies Covered | Johnson Matthey, Haldor Topsoe, Honeywell International Inc., Clariant, Tanaka Holdings Co., Ltd., thyssenkrupp AG, China Petroleum & Chemical Corporation, BASF SE, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Reforming Catalyst Market Evolving Landscape
Reforming catalyst development is pivoting from incremental activity improvements toward integrated system designs that align thermal performance with carbon intensity accounting requirements.
Structured ceramic foam supports with engineered porosity gradients are rewriting heat transfer efficiency benchmarks in secondary reforming service. Ammonia producers in the US Gulf Coast and Rotterdam corridor are piloting these configurations to reduce pressure drop and extend catalyst bed life. The technology is compressing the traditional trade-off between mechanical strength and surface area utilization that has constrained pellet geometry optimization for decades.
REACH registration requirements are tightening disclosure obligations for nickel oxide content and manufacturing effluent pathways across European catalyst supply chains. Formulators serving EU-based ammonia and methanol producers must now document full substance volume tracking from precursor sourcing through spent catalyst reclamation. German and Dutch chemical clusters are responding by consolidating procurement with suppliers holding certified closed-loop recycling partnerships.
Long-term catalyst leasing arrangements with performance-guaranteed regeneration cycles are displacing traditional spot purchase models among large integrated ammonia producers. Middle Eastern petrochemical complexes and North American blue hydrogen developers are leading this contractual evolution, transferring technical risk to suppliers in exchange for predictable per-ton hydrogen production costs. The shift is most pronounced in Qatar and Alberta project pipelines where capital discipline favors operational expenditure structures.
Secondary Reforming Catalyst Market Segmentation
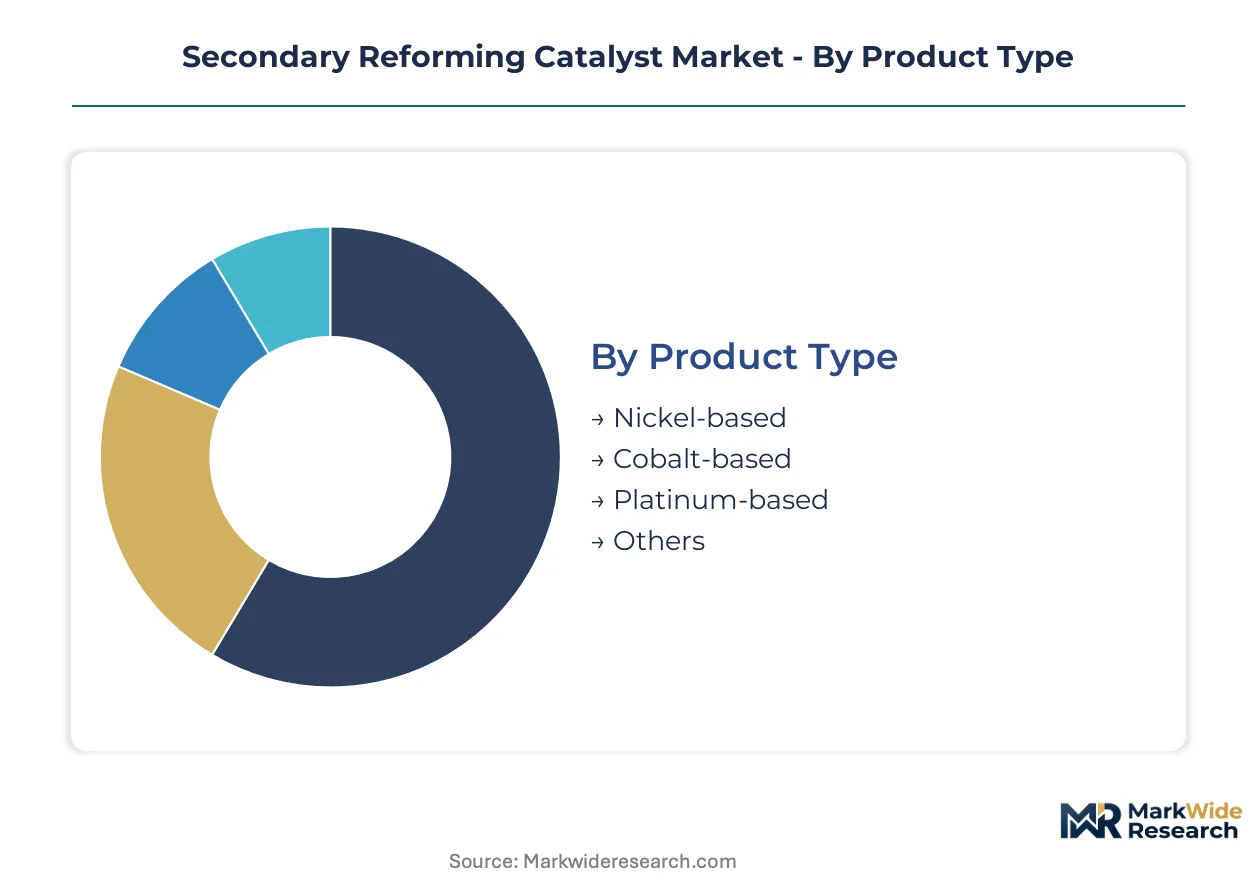
Secondary reforming catalyst procurement patterns diverge sharply across product chemistry, end-use severity, and reactor configuration. Buyers in ammonia synthesis and refinery hydrogen units prioritize fundamentally different performance envelopes, forcing suppliers to maintain parallel formulation portfolios.
Product Type:
Volume concentration favors nickel-based systems, while premium positioning attaches to platinum formulations serving carbon-intensity-sensitive applications.
- Nickel-based:Nickel oxide supported on alumina or magnesium aluminate spinel dominates installed capacity across steam methane reforming trains. Ammonia producers in India and China specify these formulations for their cost-performance balance under high-duty, sulfur-tolerant operating conditions.
- Platinum-based:Precious metal catalysts command specialized deployment in autothermal reforming pilot units and blue hydrogen demonstration projects where ultra-low methane slip is mandatory. Middle Eastern petrochemical complexes absorb these materials despite 8-12x cost premiums over nickel alternatives.
- Cobalt-based:Cobalt-promoted variants optimize syngas ratio control in Fischer-Tropsch synthesis loops.
- Others:Ruthenium and mixed-metal oxide formulations serve niche high-temperature partial oxidation duties.
Mature deployment sits with nickel-based systems. Newer deployment is concentrated in platinum-based configurations.
End User:
Application severity determines regeneration frequency and catalyst replacement economics across buyer categories.
- Chemical Production:Ammonia and methanol synthesis units impose the most demanding duty cycles, with catalyst beds operating above 800°C under high steam-to-carbon ratios. China's state-backed fertilizer expansions and India's PLI-scheme urea projects are accelerating full-load procurement of nickel-alumina systems.
- Refining:Hydrogen generation for hydrocracker and hydrotreater feedstock upgrading requires sulfur-resistant formulations capable of processing variable natural gas and naphtha blends. US Gulf Coast refiners facing EPA NOx limits are retrofitting secondary reformers with enhanced thermal stability catalysts.
- Power Generation:Integrated gasification combined cycle plants utilize reforming catalysts in pre-combustion carbon capture configurations.
- Industrial Applications:Steel and glass manufacturing sectors deploy smaller-scale reforming units for on-site hydrogen generation.
Procurement scale concentrates in chemical production. Technology validation is advancing fastest in power generation.
Technology:
Reactor architecture dictates catalyst geometry, support porosity, and active metal loading requirements.
- Steam Reforming:Conventional tubular reforming in fired heaters remains the dominant configuration, requiring pellet or tablet catalysts engineered for low pressure drop and high crush strength. Indian and Chinese ammonia producers specify these systems for greenfield capacity additions.
- Autothermal Reforming:Oxygen-blown reactors operating at higher temperatures favor powder or structured foam catalyst configurations where enhanced gas-phase contact improves conversion efficiency. Saudi Arabian and UAE blue hydrogen developers are piloting slurry-phase powder systems.
- Catalytic Reforming:Refinery naphtha upgrading employs bifunctional catalysts with reforming and isomerization activity.
- Non-catalytic Reforming:Partial oxidation reactors operate without heterogeneous catalysts in specific syngas applications.
Installed base dominance belongs to steam reforming. Steepest expansion trajectory is occurring in autothermal reforming.
Form:
Physical configuration governs pressure drop, heat transfer, and mechanical integrity trade-offs in reactor design.
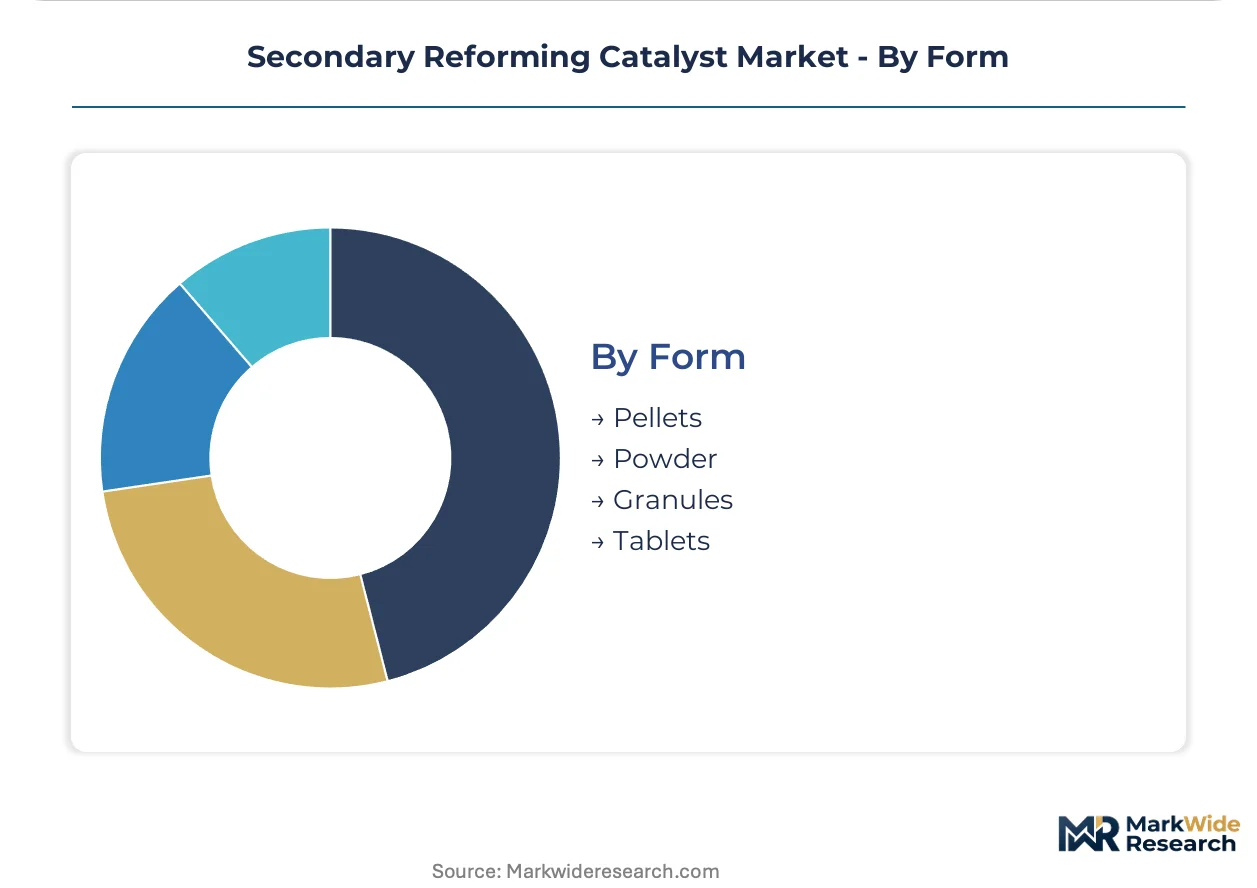
- Pellets:Extruded cylindrical forms with engineered aspect ratios balance surface area exposure against bed compaction in high-velocity gas flows. These dominate ammonia plant secondary reformers in India, China, and the US Gulf Coast.
- Tablets:Compressed ring or spherical shapes offer superior crush strength for deep-bed applications in large-scale methanol synthesis units. Rotterdam corridor chemical clusters specify these for extended duty cycles.
- Powder:Fine particulate configurations enable slurry-phase operation in autothermal reforming demonstration units.
- Granules:Irregular crushed supports serve specialty applications requiring rapid replacement protocols.
Conventional deployment favors pellets. Experimental deployment is clustering in powder formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India concentrate procurement for secondary reforming catalysts through state-backed ammonia expansions, while Middle Eastern blue hydrogen projects and US refinery retrofits drive premium-tier demand. Regulatory divergence between EPA emissions frameworks and China's MEE dual carbon enforcement creates distinct procurement specifications across major markets.
China
State-backed petrochemical expansions in fertilizer and methanol production dominate catalyst procurement volumes. MEE dual carbon goals compel domestic producers to select longer-life nickel-alumina systems that reduce regeneration frequency and energy intensity. The Yangtze River Delta chemical clusters around Shanghai and Ningbo anchor manufacturing capacity for both catalyst consumption and domestic supply chain development.
India
PLI scheme incentives for urea and complex fertilizers accelerate greenfield ammonia plant construction requiring full catalyst loadings. BIS certification requirements and domestic manufacturing mandates reshape procurement toward local supply partnerships. The Gujarat and Maharashtra industrial corridors concentrate new capacity additions, with Hazira and Mundra emerging as critical procurement nodes for secondary reforming units.
United States
EPA NOx and particulate emissions standards drive refinery hydrogen unit retrofits with enhanced thermal stability catalysts. Blue hydrogen demonstration projects in the Gulf Coast corridor test platinum-based formulations for ultra-low methane slip applications. The Texas-Louisiana petrochemical belt anchors demand concentration, with Houston and Lake Charles serving as procurement decision centers for integrated producers.
Saudi Arabia
Fischer-Tropsch synthesis expansions and blue ammonia project pipelines recalibrate specifications toward sulfur-resistant, high-activity formulations. SFDA chemical registration requirements align with broader GCC regulatory harmonization efforts. The Jubail and Yanbu industrial cities concentrate downstream petrochemical capacity, with Saudi Aramco-led developments driving cobalt-promoted catalyst procurement for syngas ratio control.
Germany
REACH registration requirements and EU Green Deal carbon intensity targets elevate compliance costs for nickel-laden spent catalyst disposal. The Rotterdam-Antwerp-German chemical corridor consolidates procurement with suppliers holding certified closed-loop recycling partnerships. BASF's Ludwigshafen complex and the North Rhine-Westphalia chemical cluster anchor demand for tablet-form catalysts optimized for extended duty cycles in methanol synthesis.
Secondary Reforming Catalyst Market Competitive Landscape
European producers anchor the premium technology tier; Chinese state-affiliated suppliers and Middle Eastern project developers hold volume-scale positions. The market structures around three to five integrated technology-catalyst bundlers and a fragmented tier of regional formulation specialists. Strategic archetypes include integrated process licensors, captive refinery suppliers, and independent catalyst formulators. Capacity expansion in magnesium aluminate support manufacturing and strategic partnerships for spent catalyst reclamation networks represent dominant competitive moves.
Among European-integrated technology providers, Johnson Matthey and Haldor Topsoe occupy positions exemplifying the bundled supply archetype where process licensing and catalyst procurement remain coupled. BASF SE anchors the manufacturing-scale tier with broad formulation portfolios spanning nickel-based and cobalt-based systems. These three entities represent distinct strategic postures: technology heritage leverage, proprietary reforming process integration, and manufacturing scale across multiple active metal chemistries.
| Leading Market Players |
|---|
| Johnson Matthey |
| Haldor Topsoe |
| Honeywell International Inc. |
| Clariant |
| Tanaka Holdings Co., Ltd. |
| thyssenkrupp AG |
| China Petroleum & Chemical Corporation |
| BASF SE |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
London Metal Exchange nickel price volatility cascades through secondary reforming catalyst supply chains, compressing margin buffers for formulators locked into fixed-price contracts with ammonia producers while amplifying procurement risk for buyers exposed to quarterly metal cost swings.
Pricing Analysis
Volume concentration in nickel-alumina formulations splits from margin capture in platinum-based tiers serving carbon-intensity-sensitive blue hydrogen projects. Three-tier pricing structure across premium, standard, and economy levels differentiates by active metal loading density and regeneration guarantee terms. Cost compression in standard-grade nickel systems is intensifying because Chinese state-backed producers are absorbing margin erosion to secure long-term offtake agreements. Ammonia synthesis operators in India and Southeast Asia exhibit highest price sensitivity, while Middle Eastern petrochemical complexes absorb premium tiers for sulfur-resistant, extended-duty formulations.
Supply Chain Analysis
Specialized ceramics engineering expertise concentrates in Germany's North Rhine-Westphalia cluster and Japan's Nagoya industrial corridor, constraining rapid capacity scaling for magnesium aluminate spinel support manufacturing. Catalyst production draws from nickel oxide precursors sourced through Indonesian nickel processing hubs, alumina from Australian bauxite refining operations, and cobalt from Central African copper-belt concentrates. Single-source vulnerability in high-purity alumina supply creates exposure to export licensing disruptions. Distribution runs through integrated technology licensors bundling catalyst supply with process licensing agreements, limiting direct procurement channels for independent formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secondary reforming catalyst procurement operates as a cost-of-compliance market where REACH registration requirements and EPA emissions standards erect regulatory moats favoring established suppliers with certified closed-loop recycling infrastructure and documented substance volume tracking capabilities.
For Market Incumbents: Anticipate margin compression from nickel price volatility by securing backward integration into precursor supply through offtake agreements with Indonesian nickel processing operations. Defend market position by investing in magnesium aluminate spinel support optimization capabilities, as scarce high-temperature materials engineering expertise limits domestic development outside established manufacturing clusters in Germany and Japan. For New Entrants and Emerging Players: Enter via India's PLI-scheme fertilizer expansions, where domestic manufacturing mandates and BIS certification requirements create procurement openings for local supply partnerships. Target autothermal reforming pilot deployments in Saudi Arabia and the United Arab Emirates, where slurry-phase powder catalyst configurations remain undersupplied relative to validation demand. Lead with performance-guaranteed regeneration cycle contracting to transfer technical risk from capital-constrained project developers. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent catalyst formulators with certified EU recycling partnerships in the Rotterdam-Antwerp-German chemical corridor, where REACH compliance costs are elevating end-of-life handling expenses for non-compliant competitors. Long-term viability across the analysis window hinges on positioning for hydrogen economy buildout and carbon border adjustment documentation capabilities. Monitor cobalt price trajectories as the inflection signal for Fischer-Tropsch synthesis loop expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Precursor Supply | Secures margin stability against LME price volatility for ammonia plant offtake contracts. |
| Long-term Catalyst Leasing Arrangements | Transfers technical risk to suppliers for Qatari and Albertan blue hydrogen project pipelines. |
| Closed-loop Spent Catalyst Recycling Partnerships | Meets REACH hazardous waste classification requirements for German and Dutch chemical clusters. |
| Structured Ceramic Foam Support Development | Rewrites heat transfer benchmarks for US Gulf Coast and Rotterdam corridor ammonia producers. |
| Autothermal Reforming Powder Catalyst Scale-up | Captures validation demand from Saudi Aramco-led syngas ratio control expansions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with ammonia plant engineering directors, refinery hydrogen unit procurement leads, catalyst formulator technical R&D heads, and spent catalyst reclamation facility operators. Secondary sources encompassed EPA emissions compliance databases, ECHA REACH registration disclosures, China MEE dual carbon enforcement bulletins, and Indian BIS certification records. Bottom-up unit economics for catalyst loading requirements were triangulated against top-down market sizing from petrochemical capacity expansion trackers.
Data-stream reconciliation across supply-side capacity announcements, demand-side project development pipelines, and trade flow records enabled segmentation modeling by active metal chemistry, reactor configuration, and end-use severity. The analytical framework projected volume and value trajectories across product type, technology, form, and application dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating nickel price volatility assumptions and regulatory compliance cost escalators specific to EU and North American jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained nickel price spikes exceeding historical quarterly volatility bands or accelerated regulatory divergence between EPA and MEE emissions frameworks. Forecasts reflect assumptions regarding state-backed fertilizer expansion continuity in China and India, blue hydrogen project financing availability in the Middle East, and REACH registration timeline adherence for nickel oxide content disclosure. Material deviation in cobalt supply chain disruptions or autothermal reforming technology validation failures warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
CO2 Reforming Catalysts Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Global Zeolites Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
North America Zeolite Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Hydrotreating Catalyst Market