
 Hydrodeoxygenation [HDO] Catalysts Market | 2026-2036
Hydrodeoxygenation [HDO] Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrodeoxygenation [HDO] Catalysts Market Foresight
Refinery operators seeking renewable diesel integration are rotating procurement toward biofuel-dedicated catalyst suppliers. BASF leverages its integrated precious metals trading arm to secure ruthenium supply chains for high-activity HDO formulations. Johnson Matthey sustains technology leadership through continuous regeneration protocols that extend catalyst cycle lengths in fixed-bed hydrotreaters. Topsoe anchors Nordic demand through long-term supply agreements with Scandinavian refiners converting forestry residues into paraffinic fuels.
Hydrodeoxygenation catalysts are heterogeneous materials—typically nickel, cobalt, palladium, or ruthenium supported on alumina or carbon carriers—that selectively cleave carbon-oxygen bonds in bio-oils under hydrogen pressure at temperatures between 250°C and 400°C, producing water and deoxygenated hydrocarbons suitable for drop-in fuel blending. Fixed bed reactor configurations dominate commercial deployment due to their compatibility with existing hydrotreating infrastructure and lower capital retrofit requirements, though continuous flow systems are gaining traction in modular green chemistry installations where batch flexibility outweighs throughput optimization. Pd-based formulations command premium positioning in applications demanding minimal aromatic saturation alongside deoxygenation, while Ni-based variants occupy volume-driven biodiesel pretreatment segments where sulfur tolerance and cost efficiency outweigh noble metal activity advantages.
EPA Renewable Fuel Standard obligations and California Air Resources Board LCFS carbon intensity scoring collectively shape North American product specifications by rewarding deeper deoxygenation that maximizes greenhouse gas reduction values. In Europe, REACH registration requirements for imported catalyst precursors and the EU Green Deal's sustainable carbon cycle objectives are tightening supply chain disclosure standards for biofuel producers. Stakeholders must monitor how evolving lifecycle assessment methodologies redefine premium catalyst performance benchmarks across jurisdictions.
Market Dynamics
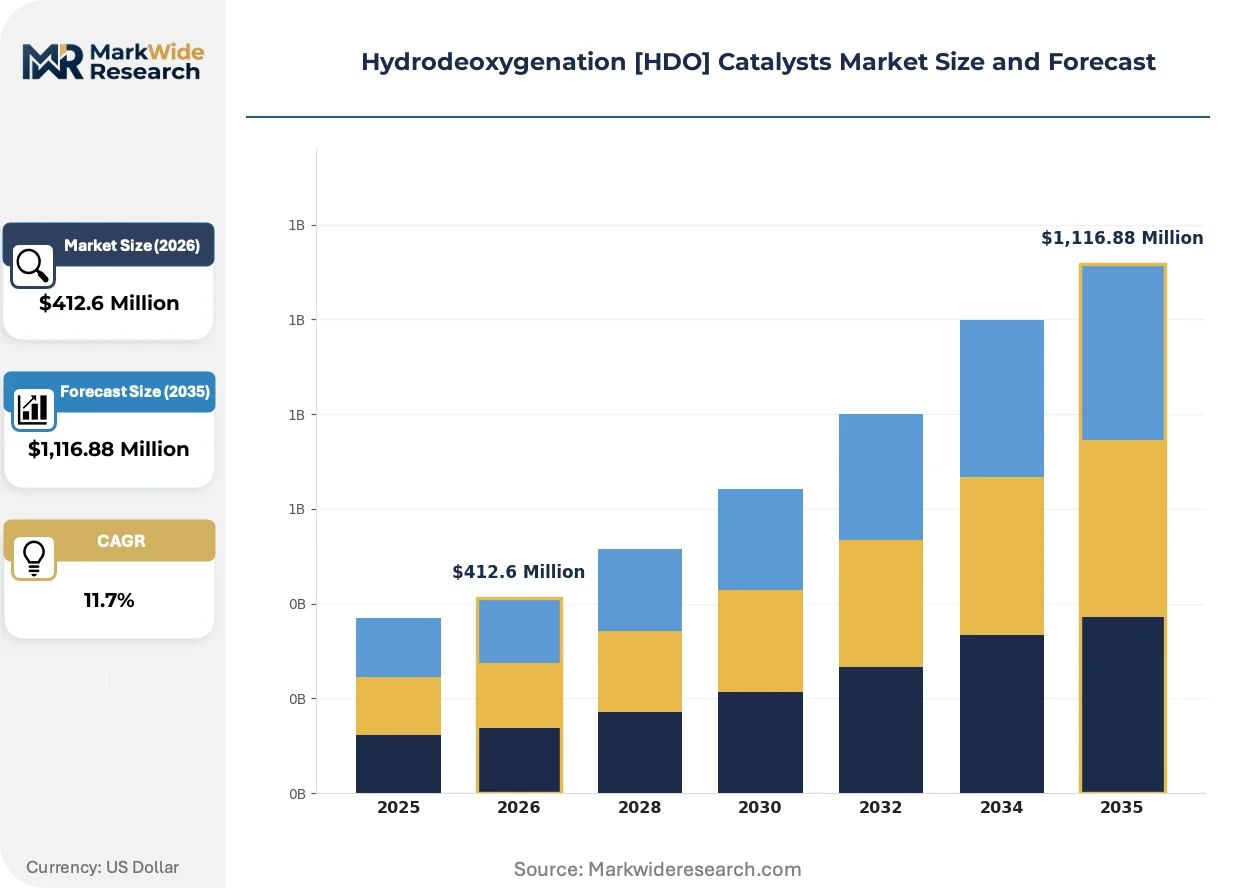
Refinery retrofit economics are compressing catalyst procurement cycles as renewable diesel capacity additions accelerate faster than greenfield construction permits allow. Hydrogen supply constraints and carbon intensity accounting rules now determine formulation selection more than unit throughput optimization.
Growth Catalysts
- EU Green Deal carbon cycle mandates:Scandinavian refiners converting forestry residues into paraffinic fuels require specialized HDO formulations that maximize greenhouse gas reduction values in lifecycle assessments.
- California LCFS carbon intensity scoring:The program rewards deeper deoxygenation, pushing renewable diesel producers toward high-activity noble metal catalysts that optimize CI scores.
- Co-processing infrastructure:US Gulf Coast petroleum facilities are repurposing existing hydrotreaters for bio-oil feeds, creating demand for sulfur-tolerant HDO formulations compatible with legacy reactor metallurgy.
Market Restraints
- Ruthenium supply concentration:Over seventy percent of primary ruthenium extraction occurs in South African platinum group metal operations, exposing catalyst manufacturers to geopolitical and labor disruption risks.
- REACH registration friction:European ECHA requirements for imported catalyst precursors impose eighteen-month compliance timelines that delay new formulation commercialization.
- Hydrogen cost volatility:Green hydrogen premiums of three to five times steam methane reforming prices erode project returns for biofuel producers running HDO units at design severity.
Strategic Opportunities
- Forestry residue valorization:Nordic countries with abundant lignocellulosic waste streams offer untapped feedstock for second-generation biofuel facilities requiring tailored HDO catalysts.
- Modular green chemistry installations:Continuous flow reactor systems are gaining traction where batch flexibility outweighs throughput optimization, opening channel opportunities outside traditional refinery procurement.
- IRA clean fuel production credits:US tax incentives for sustainable aviation fuel create pull-through demand for HDO catalysts capable of meeting stringent jet fuel aromatic specifications.
Industry Challenges
- Catalyst regeneration expertise scarcity:Fixed-bed hydrotreater operators lack technical personnel trained in continuous regeneration protocols that extend cycle lengths and reduce precious metal losses.
- Feedstock variability management:Pyrolysis oil composition swings between hardwood, softwood, and agricultural residues force real-time HDO severity adjustments that stress catalyst stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrodeoxygenation [HDO] Catalysts Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,116.88 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ni-Based, Co-Based, Pd-Based, Ru-Based Application: Biodiesel Production, Biofuel Refinery, Renewable Diesel, Green Chemistry End User: Oil & Gas Industry, Chemical Manufacturers, Research Institutions, Environmental Agencies Technology: Fixed Bed Reactors, Fluidized Bed Reactors, Batch Processing, Continuous Flow Systems |
| Companies Covered | BASF, Evonik Industries, Clariant International, Umicore, Axens, Criterion Catalysts & Technologies, Johnson Matthey, W.R. Grace, Topsoe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrodeoxygenation [HDO] Catalysts Market Shifts & Advancements
Formulation development is splitting along performance-versus-cost fault lines as biofuel producers face divergent carbon accounting regimes. Catalyst architecture choices now anticipate regulatory arbitrage rather than pure technical optimization.
Palladium-based HDO formulations is bifurcating the market between premium applications demanding minimal aromatic saturation alongside deoxygenation and volume-driven segments where nickel variants dominate. Renewable diesel producers in California and the Netherlands are adopting Pd catalysts for maximum CI score optimization. This technology split is compressing mid-tier formulation margins as buyers polarize toward performance extremes.
REACH registration requirements are tightening supply chain disclosure standards for biofuel producers importing catalyst precursors into Europe. ECHA mandates now require full substance characterization down to 0.1 percent concentration thresholds. Nordic refiners are responding by consolidating procurement through EU-registered suppliers with established registration dossiers.
Refinery procurement teams are unbundling catalyst supply from technical service contracts that previously bundled regeneration expertise. Large renewable diesel producers now source formulations directly while contracting regeneration separately with specialized service providers. This pattern is most visible along the US Gulf Coast where independent catalyst regeneration facilities are expanding capacity.
Hydrodeoxygenation [HDO] Catalysts Market Segmentation
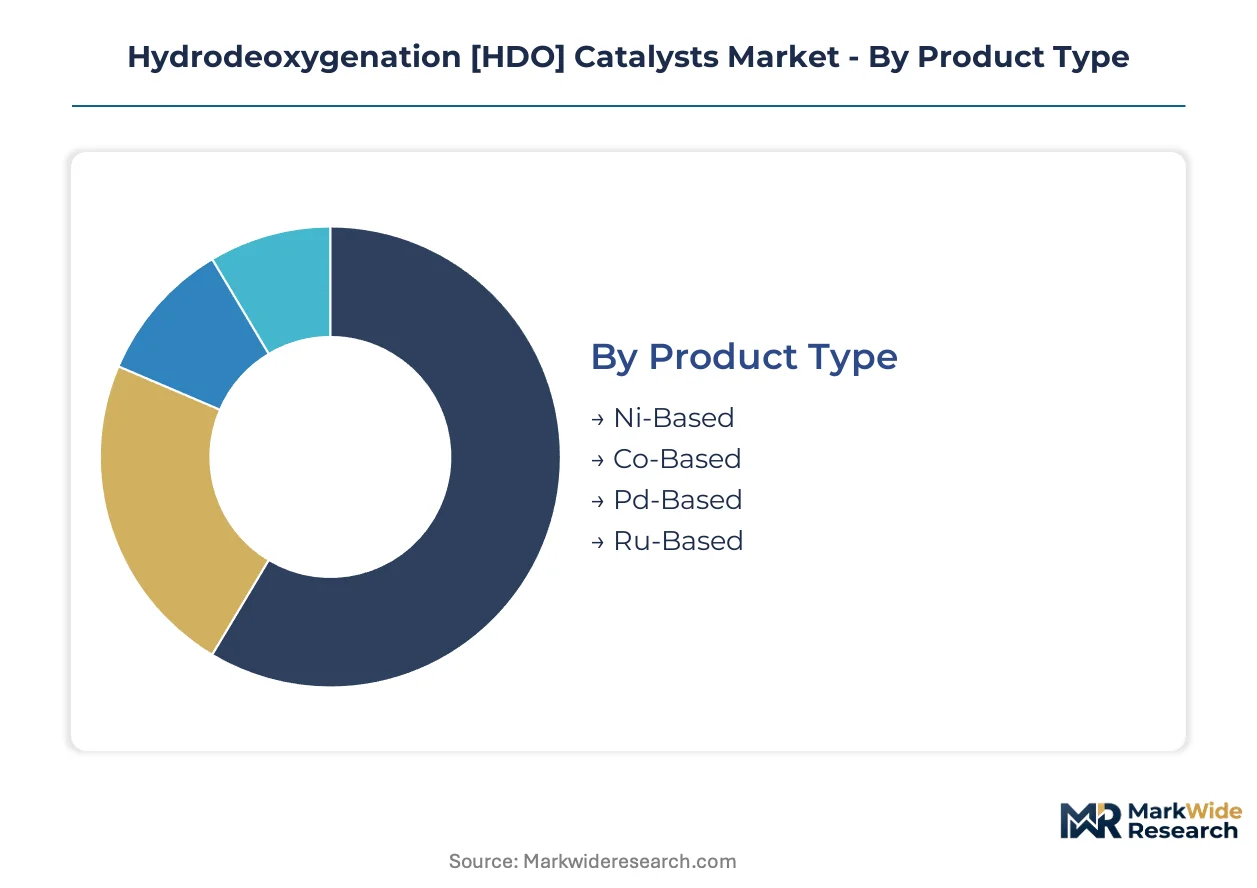
HDO catalyst segmentation reflects divergent pressure points across metal economics, reactor engineering, and regulatory compliance. Procurement teams now select formulations based on hydrogen availability and carbon intensity accounting rather than unit throughput alone.
Product Type:
Ruthenium and palladium formulations face acute substitution pressure from nickel variants as precious metal volatility compresses project returns.
- Ni-Based:Nickel supported on alumina or carbon carriers delivers sulfur tolerance and cost efficiency for volume biodiesel pretreatment. Demand concentrates in US Gulf Coast co-processing units where renewable diesel producers prioritize capital discipline over noble metal activity advantages.
- Pd-Based:Palladium formulations enable minimal aromatic saturation alongside deoxygenation, critical for California LCFS carbon intensity optimization. Renewable diesel producers in Rotterdam and Los Angeles anchor procurement volumes as CI scoring rewards deeper deoxygenation.
- Co-Based:Cobalt variants occupy mid-tier hydrotreating applications requiring moderate hydrogen consumption.
- Ru-Based:Ruthenium catalysts command premium positioning where maximum deoxygenation activity justifies supply chain risk exposure.
Ni-Based formulations anchor the volume base while Pd-Based variants gain share at the steepest rate.
Application:
Cost tier stratification separates commodity biodiesel pretreatment from premium renewable diesel and sustainable aviation fuel specifications.
- Renewable Diesel:Drop-in paraffinic fuel production demands HDO severity that maximizes greenhouse gas reduction values in lifecycle assessments. EU Green Deal mandates and California LCFS scoring drive procurement toward high-activity noble metal catalysts at facilities in Rotterdam, Houston, and Singapore.
- Biodiesel Production:Fatty acid methyl ester pretreatment tolerates lower-activity nickel formulations where sulfur management and feedstock flexibility outweigh deoxygenation depth. Volume demand clusters in Indonesian and Malaysian palm oil processing corridors.
- Biofuel Refinery:Integrated biorefinery operations require catalyst systems balancing pyrolysis oil variability with hydrotreater compatibility.
- Green Chemistry:Modular installations for specialty chemical intermediates favor batch-flexible catalyst architectures.
Biodiesel Production anchors the volume base while Renewable Diesel climbs the fastest.
End User:
Customer type determines procurement sophistication, with oil majors demanding bundled technical service contracts that research institutions bypass.
- Oil & Gas Industry:Petroleum refiners repurposing existing hydrotreaters for bio-oil feeds require sulfur-tolerant HDO formulations compatible with legacy reactor metallurgy. US Gulf Coast operators now unbundle catalyst supply from regeneration services, sourcing formulations directly while contracting cycle extension separately.
- Chemical Manufacturers:Specialty chemical producers prioritize catalyst stability across variable pyrolysis oil compositions from hardwood, softwood, and agricultural residue streams.
- Research Institutions:Academic and national laboratory users drive formulation innovation through pilot-scale continuous flow system validation.
- Environmental Agencies:Regulatory bodies influence procurement indirectly through lifecycle assessment methodology updates and carbon intensity benchmarking.
Oil & Gas Industry anchors the volume base while Chemical Manufacturers expand most quickly.
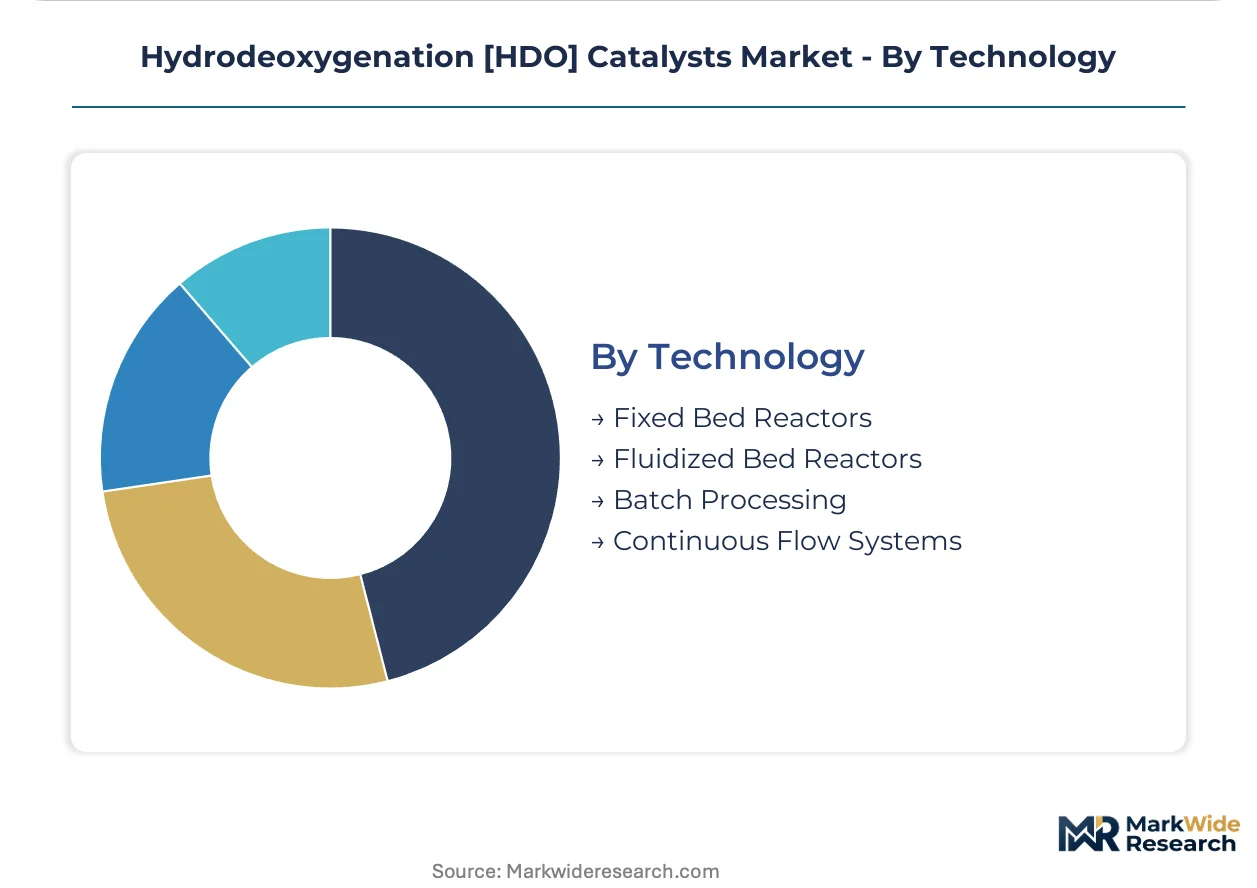
Technology:
Reactor configuration maturity splits between established fixed-bed infrastructure and emerging continuous flow architectures for distributed processing.
- Fixed Bed Reactors:Dominant commercial deployment leverages existing petroleum hydrotreater infrastructure with lower capital retrofit requirements. Johnson Matthey and Topsoe anchor technology leadership through continuous regeneration protocols extending cycle lengths.
- Continuous Flow Systems:Modular green chemistry installations gain traction where batch flexibility outweighs throughput optimization. Nordic forestry residue valorization projects and US sustainable aviation fuel demonstration units drive pilot demand.
- Fluidized Bed Reactors:Emerging configurations address heat transfer limitations in high-exothermic deoxygenation reactions.
- Batch Processing:Limited to research-scale validation and specialty chemical intermediate production.
Fixed Bed Reactors anchors the volume base while Continuous Flow Systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel pipeline network and Rotterdam-Botlek tank terminal complex anchor Atlantic basin renewable diesel trade flows, concentrating HDO catalyst demand at coastal refining clusters where bio-oil imports meet hydrogen infrastructure.
United States
Gulf Coast co-processing retrofits drive procurement volumes as Marathon Petroleum and Valero repurpose existing hydrotreaters for renewable diesel. EPA Renewable Fuel Standard obligations tighten annually, pushing producers toward high-activity formulations that maximize greenhouse gas reduction values. The Houston-Beaumont-Port Arthur corridor hosts the densest concentration of HDO unit installations outside Europe.
Germany
Industrial biorefinery development in the Rhineland chemical cluster creates demand for sulfur-tolerant catalysts compatible with legacy reactor metallurgy. REACH registration requirements impose eighteen-month compliance timelines for imported precursors, favoring EU-registered suppliers with established dossiers. The Leuna and Ludwigshafen sites anchor Central European formulation demand.
Netherlands
Rotterdam's status as Europe's largest biofuel import hub concentrates procurement for paraffinic fuel production serving Northwest European markets. EU Green Deal sustainable carbon cycle objectives reward deeper deoxygenation in lifecycle assessments, pulling demand toward noble metal catalysts. The Port of Rotterdam's dedicated biofuels terminal handles pyrolysis oil shipments from Baltic and Nordic origins.
Singapore
Jurong Island's integrated petrochemical complex hosts emerging renewable diesel capacity targeting Asia-Pacific aviation fuel demand. The country's national environmental regulator enforces carbon intensity benchmarks for imported biofuels that favor high-performance HDO severity. Neste's Singapore refinery expansion anchors regional procurement for sustainable aviation fuel specifications.
Sweden
Forestry residue valorization projects in the Norrland region require specialized catalysts for lignocellulosic feedstock processing. EU Green Deal mandates on sustainable carbon cycles align with domestic policy supporting second-generation biofuel commercialization. The St1 Gothenburg biorefinery and Preem Lysekil facility anchor Nordic HDO formulation demand.
Hydrodeoxygenation [HDO] Catalysts Market Competitive Landscape
Listed leaders compete with private specialists across precious metals trading and regeneration service capabilities. The vendor base stratifies between integrated chemical conglomerates with captive precious metals desks and independent catalyst fabricators focused on formulation optimization. Three archetypes dominate: diversified materials giants with metals trading arms, dedicated catalyst specialists with regeneration expertise, and regional chemical manufacturers serving adjacent hydrotreating markets. Capacity expansion and backward integration into precious metals sourcing represent the dominant competitive moves.
Among diversified materials leaders, BASF and Johnson Matthey exemplify the integrated archetype combining formulation development with metals supply chain control. Topsoe occupies a distinct position as a dedicated catalyst specialist with deep Nordic market penetration. These three anchors illustrate how competitive positioning splits between trading-integrated scale and technical service depth.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries |
| Clariant International |
| Umicore |
| Axens |
| Criterion Catalysts & Technologies |
| Johnson Matthey |
| W.R. Grace |
| Topsoe |
| Others |
Supply & Pricing Matrix
Eighteen-month REACH registration timelines for imported catalyst precursors concentrate pricing power with EU-registered suppliers possessing established dossiers, while compressing margins for manufacturers dependent on South African ruthenium supply chains. Buyers face tiered procurement economics where sulfur-tolerant nickel formulations trade at volume discounts against premium palladium variants optimized for California LCFS carbon intensity scoring.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Pd-based noble metal catalysts from Ni-based volume formulations and Co-based mid-tier options. Price differentiation hinges on certification grade for EU Green Deal compliance and volume scale in Gulf Coast co-processing contracts. Cost compression in nickel variants is intensifying because renewable diesel producers prioritize capital discipline over noble metal activity advantages. Chemical manufacturers show highest price sensitivity due to pyrolysis oil variability forcing real-time severity adjustments, while oil majors absorb premiums for bundled regeneration service contracts.
Supply Chain Analysis
Strategic stockpile preferences dominate precious metal sourcing as catalyst fabricators buffer against South African platinum group metal supply disruptions. Primary ruthenium extraction concentrates in South Africa, with secondary refining nodes in Russia and North America. Raw material dependencies rest on alumina carriers from Chinese smelters, carbon substrates from German specialty chemical producers, and hydrogen supply from US Gulf Coast reforming infrastructure. Single-source vulnerability in South African mining operations exposes formulation costs to labor disruption and export restriction risks. Distribution runs through Rotterdam-Botlek tank terminals for European biorefineries and Houston Ship Channel pipeline networks for US renewable diesel producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for catalyst regeneration and continuous cycle extension protocols now expand faster than base formulation hardware, creating recurring revenue layers that outperform unit sales margins. This service-attach dynamic reshapes vendor economics across fixed-bed hydrotreater installations.
For Market Incumbents: Shield market position by deepening backward integration into precious metals trading desks that secure ruthenium supply chains against South African concentration risk. Expand regeneration service capacity along the US Gulf Coast corridor where independent facilities capture unbundled procurement from Marathon Petroleum and Valero retrofit projects. Certification investment in EU REACH dossiers defends against eighteen-month compliance delays threatening new formulation commercialization. For New Entrants and Emerging Players: Differentiate on modular continuous flow reactor architectures targeting Nordic forestry residue valorization projects where batch flexibility outweighs throughput optimization. White-space opportunity concentrates in sustainable aviation fuel demonstration units requiring stringent jet fuel aromatic specifications. Penetrate the green chemistry installation segment through pilot-scale validation partnerships with Swedish biorefineries converting lignocellulosic waste streams. Go-to-market leverage rests on distributed processing economics for agricultural residue pyrolysis oil variability management. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because carbon intensity accounting methodologies across California LCFS, EU Green Deal, and emerging Asia-Pacific benchmarks create persistent formulation premium opportunities. Acquisition targets should display captive precious metals sourcing or proprietary regeneration protocols extending cycle lengths. Watch hydrogen cost parity between steam methane reforming and electrolysis as the inflection signal determining HDO unit operating severity and catalyst replacement frequency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metals Trading | BASF's captive ruthenium sourcing secures supply chains against South African concentration risk. |
| Regeneration Service Capacity Expansion | Independent Gulf Coast facilities capture unbundled procurement from Valero and Marathon Petroleum retrofits. |
| EU REACH Dossier Certification | Established registration portfolios bypass eighteen-month ECHA compliance timelines blocking competitor entry. |
| Modular Continuous Flow Reactor Development | Pilot-scale validation in Nordic forestry projects opens distributed processing channels outside refinery procurement. |
| Long-term Supply Agreements with Biorefineries | Topsoe's Scandinavian contracts anchor demand for lignocellulosic feedstock HDO formulations. |
Research Methodology
Cross-validation between primary interviews with refinery procurement directors, catalyst R&D leads, and biorefinery project developers anchors the qualitative findings against secondary validation from ECHA registration databases, EPA Renewable Fuel Standard compliance filings, and California Air Resources Board LCFS pathway certifications. Bottom-up unit economics from fixed-bed hydrotreater installations triangulate with top-down market sizing across Rotterdam, Houston, and Singapore refining clusters.
Sensitivity analysis across hydrogen cost scenarios, precious metal price volatility bands, and regulatory timeline assumptions tests forecast robustness over the projection horizon. Segmentation dimensions modeled include metal type tier, reactor configuration, application severity, end-user procurement sophistication, and regional carbon intensity accounting framework. CAGRs derive from installed capacity buildout trajectories, co-processing retrofit announcements, and sustainable aviation fuel offtake commitments. Industry-specific inputs incorporate pyrolysis oil yield variability from hardwood versus softwood feedstocks and hydrotreater metallurgy compatibility constraints.
The analysis sits within stated boundaries; outcomes outside sustained California LCFS credit pricing, EU Green Deal enforcement continuity, or South African mining labor stability would require recalibration. Forecasts reflect assumptions on hydrogen infrastructure deployment pace and pyrolysis oil commercial supply scale-up. Revision becomes warranted when green hydrogen premiums compress below three times steam methane reforming baselines or when REACH registration timelines extend beyond eighteen-month standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Polyurethane Catalysts Market
Catalysts
Industrial Catalyst Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Secondary Reforming Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Refining Catalysts Market
Catalysts
Global Catalyst Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Catalyst Handling Services Market
Catalysts
Global Zeolites Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Primary Reforming Catalyst Market