
 Biodiesel Catalyst Market | 2026-2036
Biodiesel Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Biodiesel Catalyst Market Analysis
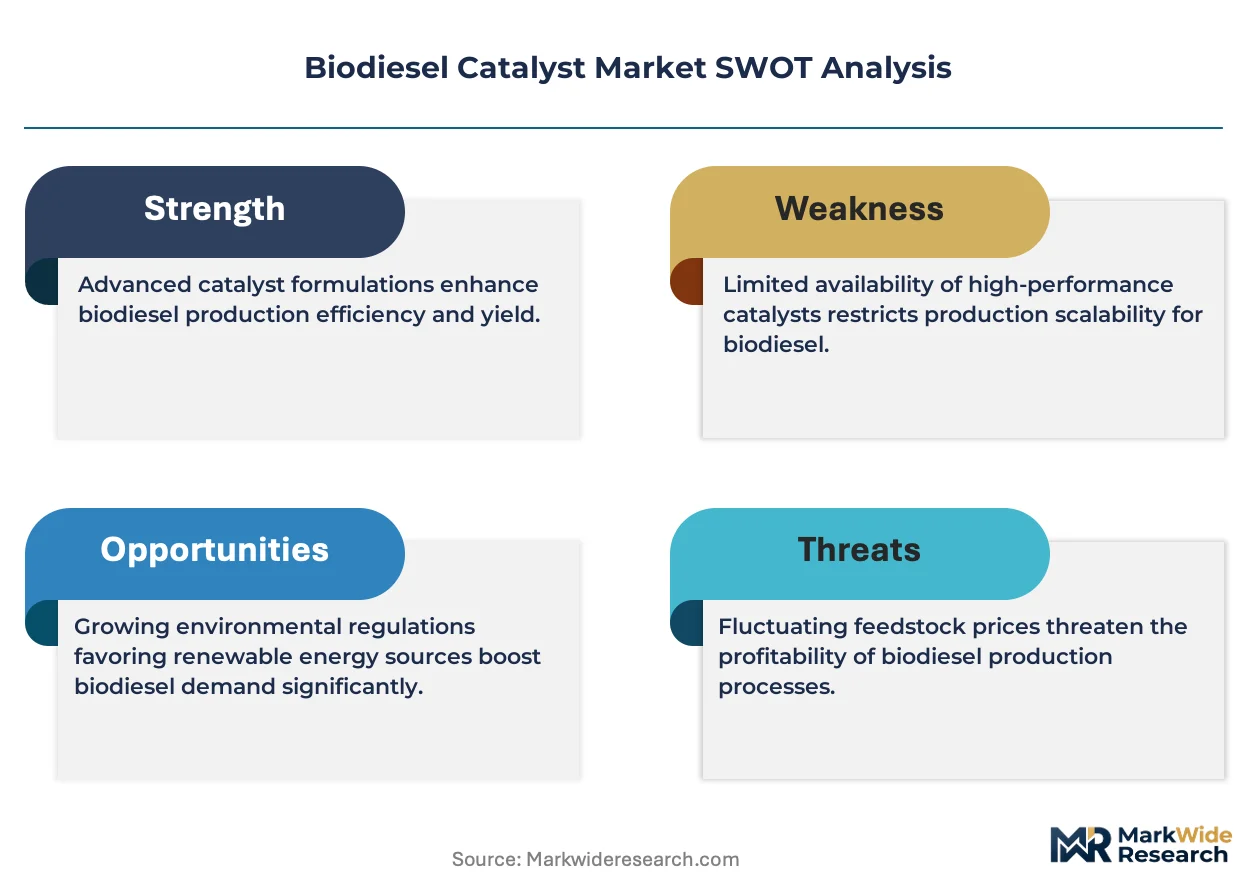
High-purity homogeneous catalyst grades is reorganizing procurement standards across European and North American biodiesel refineries. BASF SE leverages its integrated methanol-sodium methoxide supply chain to sustain cost-competitive positions in bulk catalyst delivery. Evonik Industries anchors specialty alkoxide production with tight specification control for premium esterification applications. Clariant AG differentiates through tailored heterogeneous catalyst geometries that reduce soap formation during high free-fatty-acid feedstock processing.
A biodiesel catalyst is a chemical or biological agent that accelerates the conversion of triglycerides or free fatty acids into fatty acid methyl esters through transesterification or esterification reactions, typically operating at temperatures between 50°C and 70°C with methanol-to-oil molar ratios of 6:1 to 12:1. These catalysts serve the primary industrial purpose of enabling efficient, economically viable biodiesel production from varied feedstock quality while meeting fuel specification standards such as ASTM D6751 and EN 14214. Heterogeneous catalysts command expanding share due to their separability and reduced neutralization waste, while enzymatic catalysts occupy niche positions where ultra-low-temperature processing of sensitive feedstocks justifies higher unit costs. Continuous flow systems dominate technology selection for large-scale biofuel producers seeking throughput optimization, whereas batch process configurations persist among smaller chemical manufacturers and laboratory validation units.
EPA renewable fuel standards and the EU Green Deal sustainability criteria shape catalyst selection by mandating lifecycle greenhouse-gas reduction thresholds that favor high-efficiency conversion pathways. REACH registration requirements and EN 14214 fuel quality specifications constrain market access for uncertified catalyst suppliers while rewarding documented environmental performance. ASTM D6751 testing protocols in the United States create parallel compliance obligations for catalyst performance validation across export-oriented producers. Stakeholders must monitor evolving feedstock flexibility requirements as regulatory bodies tighten traceability rules on waste oil and animal fat sourcing.
Market Dynamics
Heterogeneous catalyst formulations are compressing process economics for biodiesel refiners by eliminating neutralization steps and cutting wastewater treatment burdens. The shift from homogeneous systems is restructuring supplier relationships and capex planning across production facilities.
Growth Catalysts
- EU Green Deal sustainability criteria:Lifecycle greenhouse-gas reduction thresholds mandate high-efficiency conversion pathways. Refiners upgrade catalyst systems to meet certified fuel output requirements.
- Renewable diesel mandates:Transport energy policy in Germany and neighboring jurisdictions tightens biofuel quotas. Procurement volumes from clustered refining infrastructure concentrate demand pull.
- Waste oil feedstock processing:High free-fatty-acid tolerance in next-generation heterogeneous geometries unlocks lower-cost input streams. Catalyst durability under corrosive conditions extends replacement cycles.
Market Restraints
- Methanol price volatility:Sodium methoxide production depends on methanol feedstock costs. Margin compression ripples through homogeneous catalyst supply chains.
- REACH registration barriers:ECHA compliance documentation requirements block uncertified suppliers from European market access. Registration timelines stretch 18-24 months for novel formulations.
- Enzymatic catalyst substitution ceiling:Lipase-based systems capture ultra-low-temperature niches but cannot scale to refinery throughput. Price-performance gaps limit displacement of chemical catalysis.
Strategic Opportunities
- Continuous flow system adoption:Large-scale biofuel producers seek throughput optimization. Equipment-catalyst integrated offerings capture upgrade cycles.
- India biofuel policy expansion:National biofuel blending targets under CEA guidance create new procurement geography. Domestic refining capacity additions require catalyst supply partnerships.
- Alkoxide-methanol supply integration:Backward control over methanol sourcing secures cost positions. Captive alkoxide production buffers against commodity swings.
Industry Challenges
- ASTM D6751 validation timelines:Performance certification for export-oriented producers requires extensive testing protocols. Fuel quality specification alignment delays market entry.
- Feedstock traceability system integration:Waste oil and animal fat sourcing rules tighten under evolving regulatory frameworks. Documentation systems must interface with legacy batch tracking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodiesel Catalyst Market |
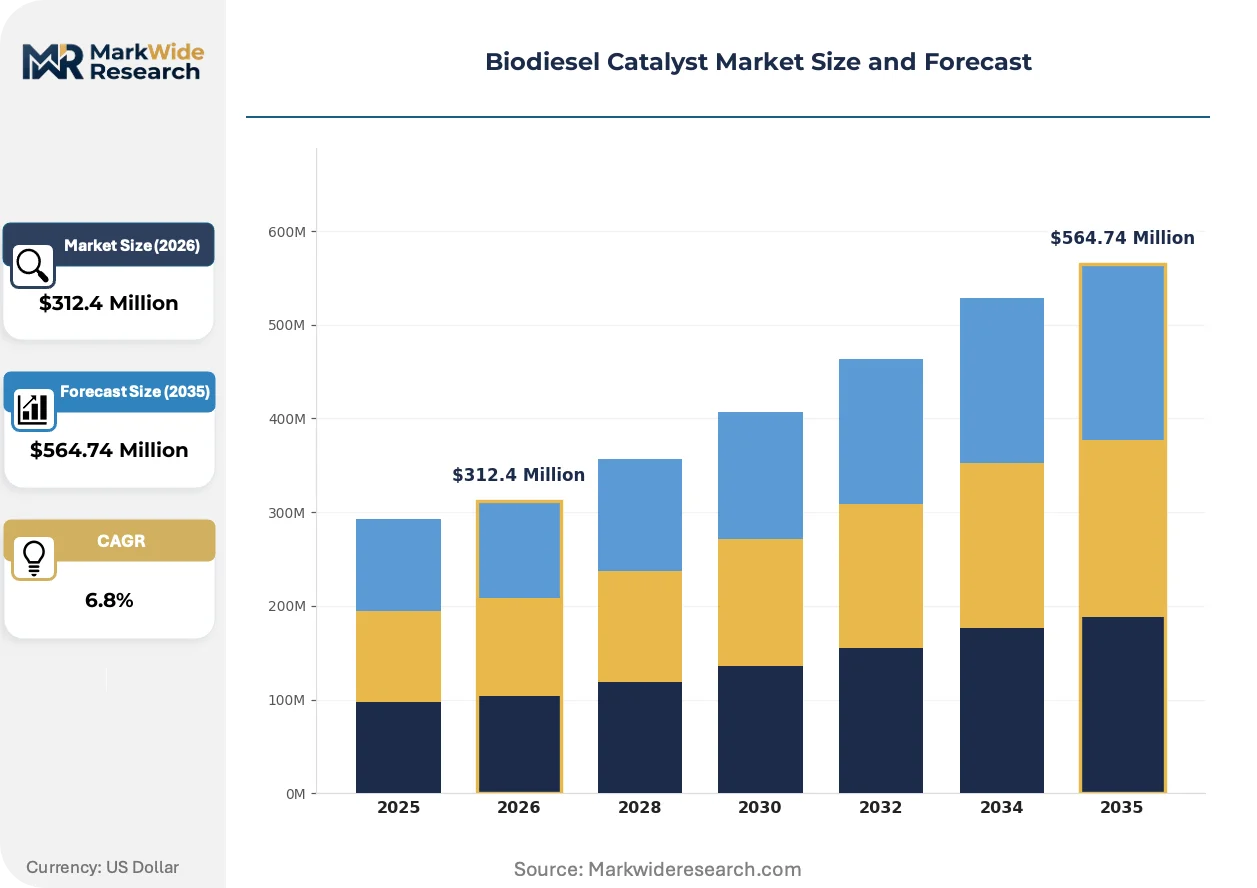
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homogeneous Catalysts, Heterogeneous Catalysts, Enzymatic Catalysts, Ionic Liquids Application: Transesterification, Esterification, Biodiesel Production, Oil Refining End User: OEMs, Biofuel Producers, Chemical Manufacturers, Laboratories Technology: Continuous Flow Systems, Batch Process, Membrane Reactors, Microwave-Assisted |
| Companies Covered | BASF SE, Evonik Industries, Clariant AG, Dow Chemical Company, Haldor Topsoe, Novozymes, Johnson Matthey, Nouryon, Albemarle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodiesel Catalyst Market Emerging Trajectories
Catalyst architecture and refinery process design are converging around separability, reusability, and feedstock flexibility. Formulation chemistry and reactor engineering now advance in lockstep rather than as isolated disciplines.
Structured ceramic supports with engineered pore geometries are miniaturizing active site distribution while maintaining mechanical stability under high-velocity flow conditions. Large-scale continuous processors in the US and Germany adopt these configurations to suppress soap formation during high-FFA feedstock runs. The technology is miniaturizing the trade-off between conversion efficiency and catalyst longevity that previously forced batch-mode compromises.
REACH registration requirements under ECHA jurisdiction are tightening documentation burdens for novel heterogeneous formulations. Suppliers must submit comprehensive environmental fate data and toxicological profiles before commercial authorization. European refiners respond by consolidating procurement relationships with established registrants rather than qualifying emerging entrants.
Refiner procurement functions are unbundling catalyst supply from technical service contracts. Buyers now source alkoxide chemicals through commodity channels while retaining specialized engineering support separately. This bifurcation is most visible in Germany's clustered Rhine-Ruhr refining corridor, where standardized specification sheets replace negotiated performance guarantees.
Biodiesel Catalyst Market Segmentation
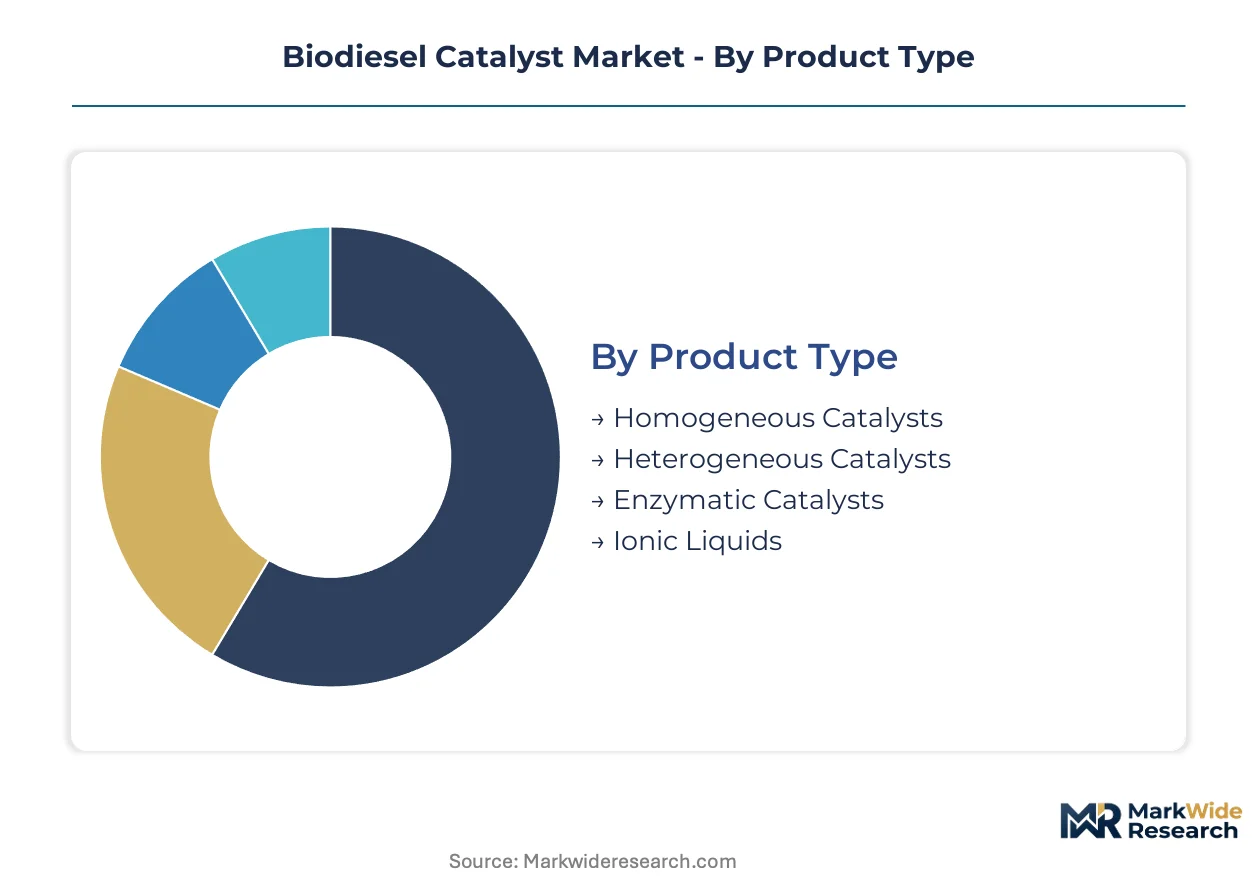
Catalyst selection in biodiesel production determines conversion efficiency, wastewater burden, and compliance with ASTM D6751 and EN 14214 fuel specifications. Segmentation reveals where technology transitions are restructuring procurement budgets and supplier relationships across refinery scales.
Product Type:
Margin pools concentrate in heterogeneous formulations where reusability commands premium pricing over single-use homogeneous alternatives.
- Homogeneous Catalysts:Alkoxide solutions including sodium methoxide and potassium hydroxide dissolve in methanol to create single-phase reaction environments. German biofuel producers along the Rhine-Ruhr corridor maintain bulk procurement contracts for these systems where neutralization infrastructure is already amortized.
- Heterogeneous Catalysts:Solid acid and base catalysts on ceramic or metal oxide supports enable separation and reuse without aqueous quenching. Clariant AG and specialty chemical suppliers capture value here as REACH-registered formulations displace uncertified competitors in EU Green Deal compliance scenarios.
- Enzymatic Catalysts:Immobilized lipase biocatalysts operate at sub-ambient temperatures for heat-sensitive waste oil streams.
- Ionic Liquids:Task-specific molten salt catalysts dissolve polar and nonpolar substrates in single-phase systems.
Heterogeneous catalysts hold installed capacity. Enzymatic catalysts are rotating up the share rankings in premium cold-process niches.
Application:
Volume concentration follows transesterification where triglyceride feedstocks dominate refinery input slates.
- Transesterification:Base-catalyzed conversion of triglycerides with methanol produces fatty acid methyl esters at 6:1 to 12:1 alcohol-to-oil molar ratios. Continuous flow adopters in the US and Germany specify catalyst geometries optimized for 50°C to 70°C operating windows.
- Esterification:Acid-catalyzed free fatty acid neutralization pretreats high-FFA waste oils before transesterification. Evonik Industries and alkoxide specialists supply tight-specification grades here where soap suppression determines downstream process economics.
- Biodiesel Production:Integrated catalyst-service packages target ASTM D6751 certification for export-oriented producers.
- Oil Refining:Hydrotreating catalysts for renewable diesel upgrading operate in separate process trains.
Transesterification holds installed capacity. Esterification is rotating up the share rankings as waste oil feedstock ratios climb.
End User:
Procurement scale bifurcates between commodity chemical buyers and integrated engineering-service seekers.
- Biofuel Producers:Large-scale refiners with 100,000+ tonne annual capacity negotiate alkoxide supply agreements tied to methanol price indices. These operators drive continuous flow system adoption and specify catalyst durability under corrosive high-FFA conditions.
- OEMs:Equipment manufacturers bundle catalyst loading with reactor system sales. BASF SE leverages backward integration into methanol-sodium methoxide supply chains to anchor these relationships.
- Chemical Manufacturers:Batch processors purchase standardized specification sheets through commodity channels.
- Laboratories:Validation units source gram-scale quantities for ASTM D6751 and EN 14214 protocol development.
Biofuel producers hold installed capacity. OEMs are rotating up the share rankings through equipment-catalyst integration.
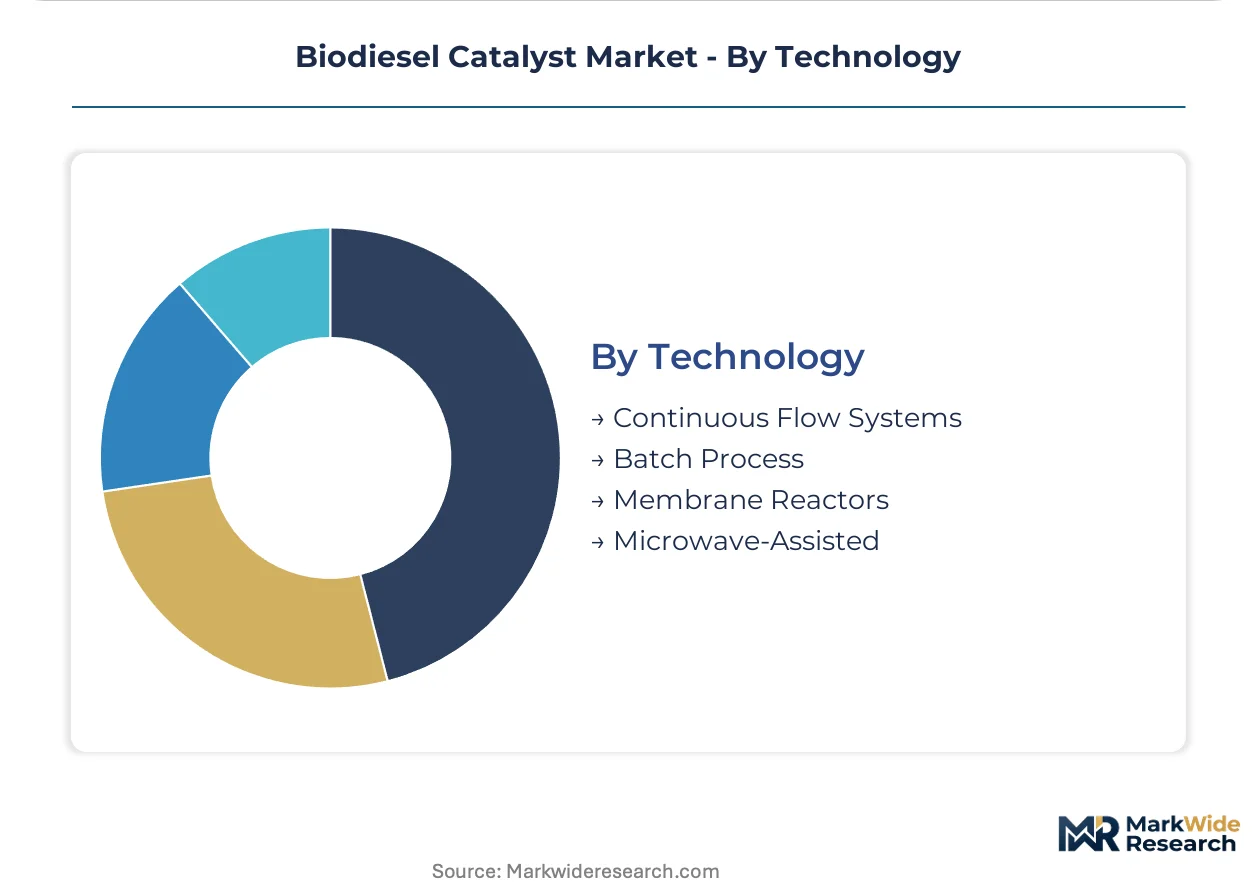
Technology:
Capital deployment favors continuous configurations where throughput optimization justifies front-loaded engineering investment.
- Continuous Flow Systems:Plug-flow and loop reactors with structured catalyst beds achieve residence times under 30 minutes at high velocity. Large-scale US and German refiners adopt these for soap suppression during high-FFA feedstock campaigns.
- Batch Process:Stirred-tank configurations persist among smaller chemical manufacturers and laboratory validation units where feedstock variability demands manual intervention.
- Membrane Reactors:Integrated separation-catalyst systems remove glycerol in situ to drive equilibrium conversion.
- Microwave-Assisted:Electromagnetic heating reduces thermal gradients and reaction times in pilot-scale installations.
Continuous flow systems hold installed capacity. Membrane reactors are rotating up the share rankings in next-generation facility designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German catalyst manufacturers export alkoxide formulations to US biofuel refineries along trans-Atlantic supply corridors. This trade flow reflects divergent regulatory timelines and capacity buildouts across Atlantic markets.
United States
EPA renewable fuel standards mandate annual biofuel blending volumes that tighten each compliance period. ASTM D6751 testing protocols require catalyst performance validation for export certification. Gulf Coast refining clusters in Texas and Louisiana drive procurement scale for continuous flow system upgrades.
Germany
The national biofuel quota framework concentrates demand pull within the Rhine-Ruhr refining corridor. EU Green Deal sustainability criteria enforce lifecycle greenhouse-gas reduction thresholds on certified fuel output. BASF SE and Evonik Industries anchor supply relationships through integrated methanol-alkoxide production.
India
National biofuel blending targets under CEA guidance create new procurement geography for heterogeneous catalyst systems. BIS standards alignment with EN 14214 specifications enables export-oriented production. Gujarat and Maharashtra host emerging refining capacity requiring catalyst supply partnerships.
China
Dual carbon goals accelerate renewable diesel capacity additions across coastal provinces. GB standards for biodiesel quality create parallel compliance obligations to ASTM and EN specifications. Yangtze River Delta chemical parks cluster alkoxide production for domestic biofuel processors.
Brazil
ANP biofuel mandates sustain feedstock-flexible catalyst demand for soybean and waste oil processing. National biodiesel production targets expand procurement volumes for both homogeneous and heterogeneous systems. São Paulo state refineries concentrate equipment-catalyst integration decisions.
Biodiesel Catalyst Market Vendor Landscape
Listed leaders compete with private specialists across formulation chemistry and supply chain integration dimensions. The vendor base spans multinational chemical conglomerates with backward methanol integration and specialty catalyst houses with REACH-registered geometries. Three archetypes dominate: integrated alkoxide producers, heterogeneous formulation specialists, and enzymatic biocatalyst developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure methanol supply agreements and equipment-catalyst bundled offerings.
Within the integrated chemical tier, BASF SE exemplifies backward control over methanol-sodium methoxide supply chains. Evonik Industries anchors specialty alkoxide production with tight specification positioning. Clariant AG occupies a differentiated slot through tailored heterogeneous catalyst geometries. These three represent distinct strategic postures rather than overlapping competitive territory.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries |
| Clariant AG |
| Dow Chemical Company |
| Haldor Topsoe |
| Novozymes |
| Johnson Matthey |
| Nouryon |
| Albemarle Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-day alkoxide inventory cycles at German refineries concentrate procurement leverage among Rhine-Ruhr biofuel producers, compressing margin pools for homogeneous catalyst suppliers while amplifying pricing power for REACH-registered heterogeneous formulation houses.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the European biodiesel catalyst trade. Three-tier pricing structure across premium REACH-certified, standard EN 14214-compliant, and economy unregistered grades separates procurement tiers by documentation burden and feedstock flexibility. Cost compression in economy homogeneous alkoxides is intensifying because methanol price volatility ripples through sodium methoxide production. Small batch chemical manufacturers exhibit highest price sensitivity, while integrated biofuel producers with captive methanol sourcing show lowest.
Supply Chain Analysis
Sixty-day alkoxide inventory cycles reflect just-in-time methanol sourcing dependencies that tether catalyst production to commodity chemical logistics. Germany, China, and the United States concentrate heterogeneous catalyst manufacturing, while methanol feedstock draws from natural gas reforming corridors in the Middle East and North America. REACH registration documentation creates regulatory chokepoint risk for uncertified formulations entering European jurisdictions. Distribution runs through integrated chemical distributors with technical service capabilities rather than pure commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among clustered Rhine-Ruhr refineries and Gulf Coast biofuel producers, fragmenting supplier margins and forcing catalyst houses toward equipment-catalyst bundled offerings to defend pricing authority.
For Market Incumbents: Compound backward integration into methanol-alkoxide supply chains to buffer margin compression from commodity price swings. Invest in REACH-registered heterogeneous geometries that neutralize soap formation during high-FFA waste oil campaigns, displacing uncertified competitors as EU Green Deal traceability rules tighten. For New Entrants and Emerging Players: Differentiate on feedstock-flexible catalyst architectures targeting India's emerging biofuel blending mandates under CEA guidance. Capture white-space in continuous flow system retrofits for mid-scale US refineries seeking ASTM D6751 certification without full engineering overhauls. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-monetized catalyst divisions lacking REACH registration depth. Long-term viability hinges on positioning for renewable diesel capacity buildouts rather than legacy biodiesel substitution. Watch for EPA renewable volume obligation announcements as policy inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | BASF SE and Evonik Industries anchor cost positions through captive alkoxide production. |
| REACH Registration Investment | Clariant AG captures EU Green Deal compliance premiums through documented environmental fate data. |
| Continuous Flow System Partnerships | Equipment-catalyst bundles capture refinery upgrade cycles in Texas and Louisiana clusters. |
| Waste Oil Feedstock Catalyst Development | High-FFA tolerance geometries unlock lower-cost input streams for German biofuel producers. |
| India Market Supply Agreements | Gujarat and Maharashtra refining capacity additions require catalyst partnerships under CEA biofuel targets. |
Methodological Framework
The analysis maps homogeneous alkoxides, heterogeneous ceramic supports, enzymatic biocatalysts, and ionic liquid formulations, each validated through refinery procurement managers, catalyst R&D directors, and chemical distribution channel heads. Primary interviews with biofuel plant engineers and ECHA regulatory consultants combined with secondary validation from customs trade data, SEC chemical sector filings, and EPA renewable fuel standard dockets. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the projection horizon.
Consistency checks against EIA biofuel production statistics and IEA renewable energy deployment trackers validated segment-level outputs. The analytical framework modeled catalyst type, application chemistry, end-user scale tier, and process technology configuration throughout the forecast period. CAGRs derived from elasticity-adjusted feedstock demand curves and policy mandate trajectory analysis, incorporating methanol price correlation coefficients and REACH registration pipeline visibility.
Forecasts assume regulatory continuity in EPA renewable fuel standards and EU Green Deal sustainability criteria; material policy shifts would require re-modeling with adjusted compliance thresholds. Outputs reflect assumptions on biofuel blending target achievement rates and waste oil feedstock availability trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Chemical Catalyst Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
Organic Catalyst Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Global FCC Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Hydro-Processing Catalysts Market