
 Polyurethane Catalysts Market | 2026-2036
Polyurethane Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Catalysts Market Analysis
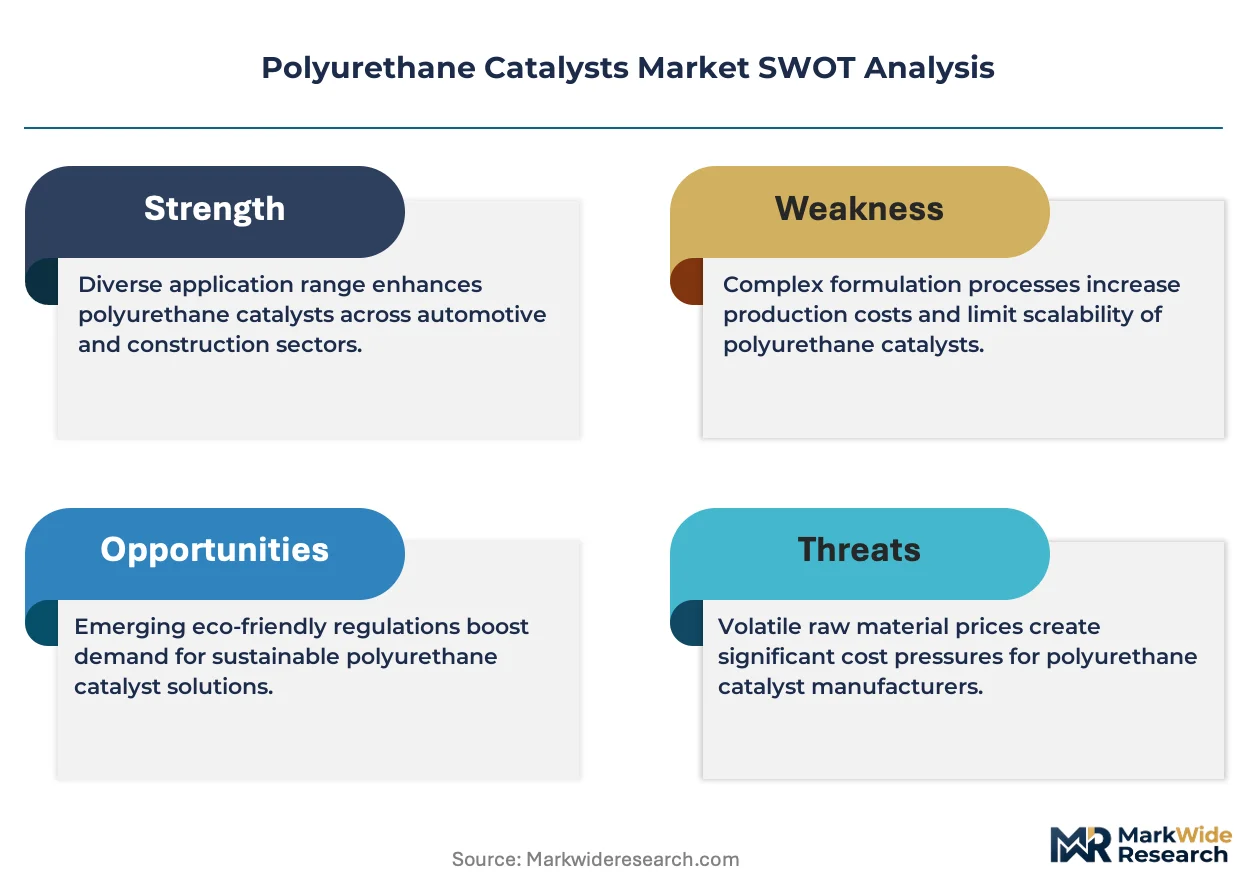
The EU F-Gas Regulation is hardening demand for low-emission rigid foam formulations in refrigeration and construction. BASF SE leverages integrated catalyst-polyol systems to sustain pricing power across European appliance supply chains. Evonik Industries AG anchors its position through specialty amine catalysts optimized for automotive interior applications. Huntsman International LLC competes on differentiated formulations that reduce VOC emissions during spray foam installation.
Polyurethane catalysts are chemical accelerators—typically tertiary amines or organometallic salts—that control gelation and blow reactions in polyurethane polymerization, with loading levels typically ranging from 0.1% to 5.0% by polyol weight to manage cure profiles and final foam properties. Their primary purpose is to enable precise control over reaction kinetics, ensuring dimensional stability and performance consistency across molded, sprayed, or poured applications. Tertiary amines dominate current formulation volumes due to their versatility across rigid and flexible foam systems, while organometallic compounds capture premium positioning in coatings and adhesives where tin-free compliance commands price premiums. Flexible foam applications for furniture and bedding represent mature demand with stable replacement cycles, whereas rigid foam for construction insulation and cold-chain logistics is expanding fastest as energy-efficiency mandates tighten.
EPA regulations under the Significant New Alternatives Policy constrain ozone-depleting blowing agents, indirectly reshaping catalyst selection to match reformulated foam systems. ECHA REACH restrictions on dibutyltin and dioctyltin compounds force reformulation toward bismuth, zinc, and zirconium-based organometallic catalysts across European supply chains. China's MEE enforces volatile organic compound emission standards in industrial coatings that filter back to catalyst specification requirements for local formulators. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
The polyurethane catalysts sector is experiencing acute formulation pressure as REACH organotin bans force rapid migration toward bismuth and tertiary amine systems, compressing reformulation timelines across European supply chains while automotive lightweighting accelerates catalyst consumption per vehicle.
Growth Catalysts
- EU F-Gas Regulation:Refrigeration and construction sectors in Germany, France, and Italy are adopting low-emission rigid foam systems that require specialized amine catalysts to maintain cure profiles with reduced blowing agent potency.
- Automotive seating:Vehicle manufacturers in Detroit, Stuttgart, and Shanghai are expanding catalyst volumes as seat foam density reductions become essential to meet fleet efficiency targets without sacrificing comfort performance.
- China construction clusters:Prefabricated building adoption in Guangdong and Jiangsu provinces is driving rigid foam demand for insulated wall panels, pulling catalyst consumption through integrated polyol-catalyst supply relationships.
Market Restraints
- Raw material volatility:Ethylene oxide and propylene oxide feedstock costs fluctuate with crude oil indices, compressing catalyst producer margins during polyol price spikes.
- Supplier concentration:Organometallic precursor production concentrates in German and Chinese chemical parks, creating geographic vulnerability for tin-free catalyst supply security.
- Technical substitution limits:Bismuth catalysts exhibit slower cure kinetics than organotins in certain coating applications, restricting complete formulation migration in high-performance segments.
Strategic Opportunities
- India construction acceleration:Affordable housing mandates and cold-chain infrastructure expansion in Maharashtra and Gujarat are creating first-mover advantages for catalyst suppliers establishing local technical service capabilities.
- Refrigerant transition alignment:Hydrofluoroolefin adoption timelines under EPA SNAP regulations are creating catalyst specification windows for foam systems optimized to reduced thermal conductivity blowing agents.
- Digital formulation platforms:AI-driven reaction kinetic modeling is enabling remote catalyst customization, allowing technical sales teams to serve dispersed spray foam contractors without on-site laboratory support.
Industry Challenges
- Formulation chemist scarcity:Expertise in organometallic synthesis and polyurethane reaction balancing is concentrating among aging specialists in Basel, Ludwigshafen, and Shanghai, constraining R&D throughput for new product development.
- Multi-jurisdiction compliance:Divergent timelines between EPA SNAP, ECHA REACH, and China MEE volatile organic compound standards force parallel inventory management and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Catalysts Market |
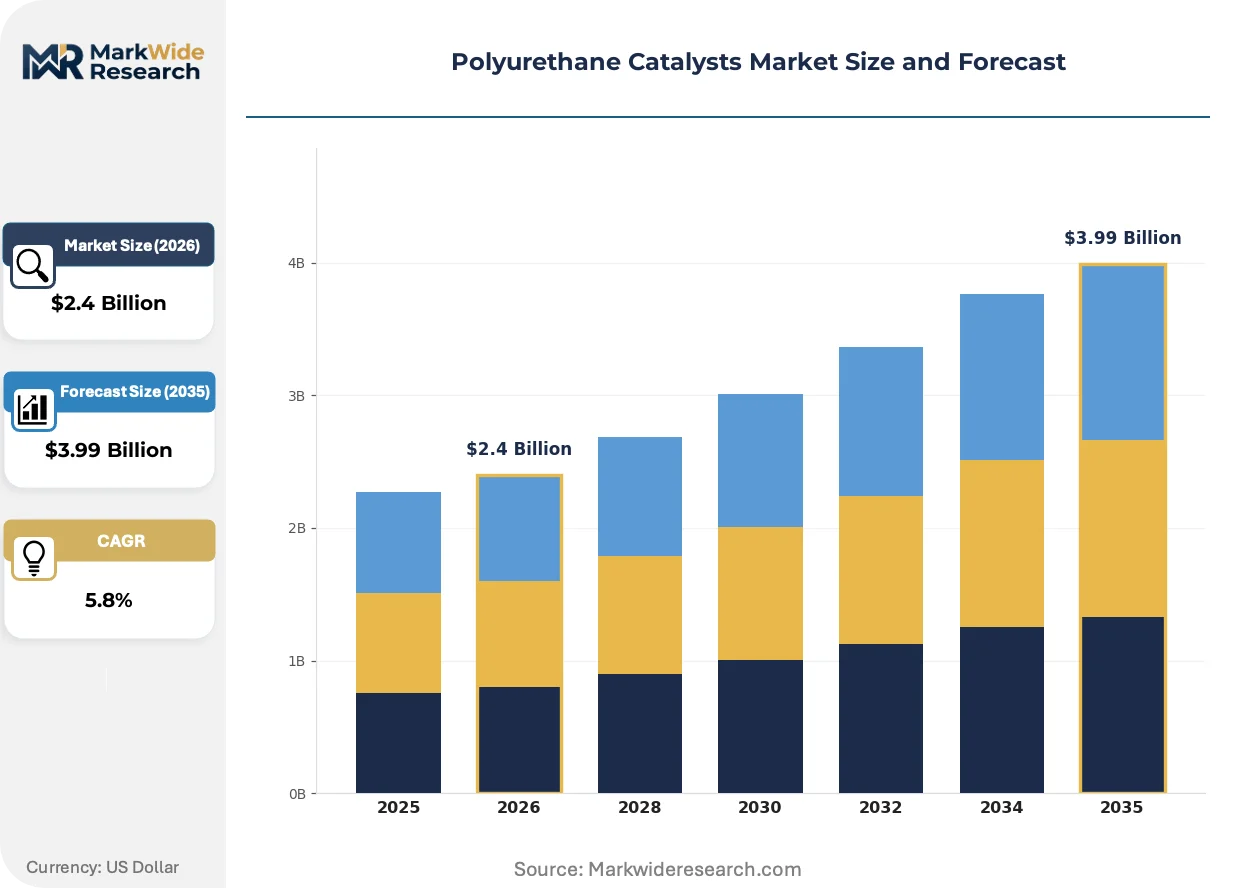
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tertiary Amines, Organometallic Compounds, Other Catalysts, Catalytic Agents Application: Rigid Foam, Flexible Foam, Coatings, Adhesives Formulation: Polyester-based, Polyether-based, Blends, Specialty Formulations End User: Automotive, Furniture, Construction, Footwear |
| Companies Covered | BASF SE, Evonik Industries AG, Huntsman International LLC, Covestro AG, Dow Chemical Company, Momentive Performance Materials Inc., Tosoh Corporation, Air Products and Chemicals, Inc., Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Catalysts Market Emerging Trajectories
Reactive amine catalyst technologies are rewriting formulation economics by enabling lower loading levels without sacrificing cure speed, while regulatory fragmentation between jurisdictions is forcing catalyst suppliers to maintain parallel product portfolios.
Blocked amine catalyst systems are decentralizing supply chain control by extending pot life in field-applied spray foam applications. Roofing contractors in Texas and Florida are adopting these systems to reduce waste from premature gelling in hot ambient conditions. The technology is decentralizing project execution by enabling smaller crews to complete larger continuous pours without batch segmentation.
EPA SNAP restrictions on hydrofluorocarbon blowing agents are compressing catalyst selection windows for appliance manufacturers. Refrigerator producers in the Midwest must now match catalyst systems to hydrofluoroolefin or hydrocarbon formulations with distinct thermal profiles. Cold-chain equipment segments are responding by qualifying catalyst-polyol integrated systems that lock in supplier relationships.
Specification consolidation among appliance OEMs is compressing catalyst vendor lists as procurement teams reduce qualification overhead. Tier-1 foam suppliers in Ohio and Tennessee are consolidating purchases around integrated catalyst-polyol platforms that transfer technical risk upstream. This pattern is most visible in North American residential refrigeration, where three manufacturers account for dominant volume.
Polyurethane Catalysts Market Segmentation
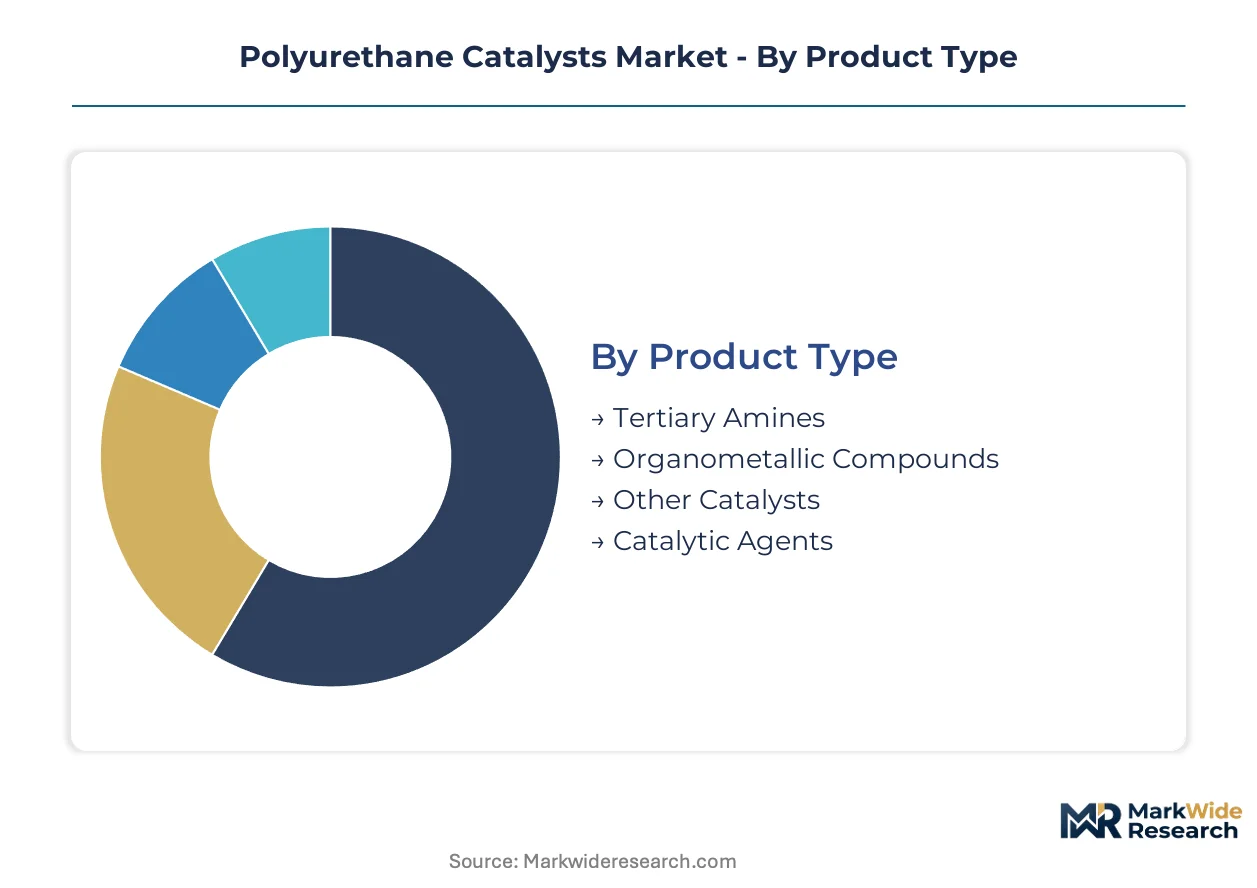
Polyurethane catalyst segmentation reflects divergent supply chain configurations across chemistries and end-use specifications. Formulation requirements vary sharply between rigid insulation systems and flexible comfort foams, with regulatory compliance adding complexity to supplier portfolio management.
Product Type:
Supply concentration for amine precursors clusters in German Rhineland and Chinese Yangtze River Delta chemical parks, while organometallic synthesis requires specialized metal refining relationships.
- Tertiary Amines:Nitrogen-based accelerators such as dimethylethanolamine and bis(dimethylaminoethyl)ether control gelation kinetics through proton abstraction mechanisms. Automotive seating plants in Stuttgart and Shanghai specify these for flexible foam systems where rapid demold cycles maximize press utilization. ECHA REACH compliance pressures are forcing reformulation toward lower-emission amine variants.
- Organometallic Compounds:Tin, bismuth, and zinc-based catalysts coordinate with isocyanate groups to regulate reaction selectivity. Coatings formulators in Bavaria and Michigan pay premiums for bismuth alternatives as dibutyltin restrictions eliminate legacy options. Slower cure kinetics in certain applications limit complete substitution timelines.
- Other Catalysts:Delayed-action and heat-activated systems serve specialized spray foam contractors in Texas and Florida requiring extended pot life.
- Catalytic Agents:Co-catalyst packages and promoter additives fine-tune reaction balancing for appliance manufacturers optimizing rigid foam density targets.
Tertiary amines absorb the bulk of installed capacity; organometallic compounds are expanding most quickly as tin-free mandates accelerate.
Application:
Application segmentation tracks divergent margin structures between commodity flexible foam and specification-driven rigid insulation systems.
- Rigid Foam:Closed-cell insulation for construction panels and refrigeration equipment demands catalysts compatible with reduced-potency hydrofluoroolefin blowing agents. German appliance OEMs in Bavaria specify amine systems calibrated to HFO thermal profiles under EU F-Gas Regulation timelines. Cold-chain infrastructure expansion in India and China is pulling volume through integrated polyol-catalyst supply relationships.
- Flexible Foam:Open-cell comfort foams for furniture and automotive seating rely on balanced gelation-blow catalyst packages. Michigan and Tennessee seating plants specify systems that maintain dimensional stability across density reduction initiatives targeting fleet efficiency compliance.
- Coatings:Surface finishing applications in industrial maintenance and automotive refinish use tin-free organometallic catalysts to meet VOC emission standards.
- Adhesives:Bonding formulations for construction and footwear assembly require rapid tack development without residual odor or skin irritation.
Flexible foam commands the largest share of catalyst volume; rigid foam is gaining share fastest as energy-efficiency mandates tighten across building codes.
Formulation:
Formulation chemistry determines catalyst compatibility windows and supplier qualification requirements for downstream foam producers.
- Polyester-based:Ester-linked polyol backbones provide hydrolytic stability for footwear and industrial applications. Catalyst selection must balance reactivity against premature degradation in humid climates.
- Polyether-based:Ether-linked structures dominate flexible foam production due to cost efficiency and hydrolysis resistance. BASF and Covestro integrated systems pair proprietary polyols with matched catalyst packages to lock in supply relationships.
- Blends:Hybrid polyester-polyether formulations optimize property combinations for specific automotive interior specifications.
- Specialty Formulations:Bio-based and recycled-content polyols emerging in European sustainable construction projects require recalibrated catalyst loading levels.
Polyether-based systems account for the majority of catalyst consumption; specialty formulations are climbing the fastest as sustainability specifications proliferate.
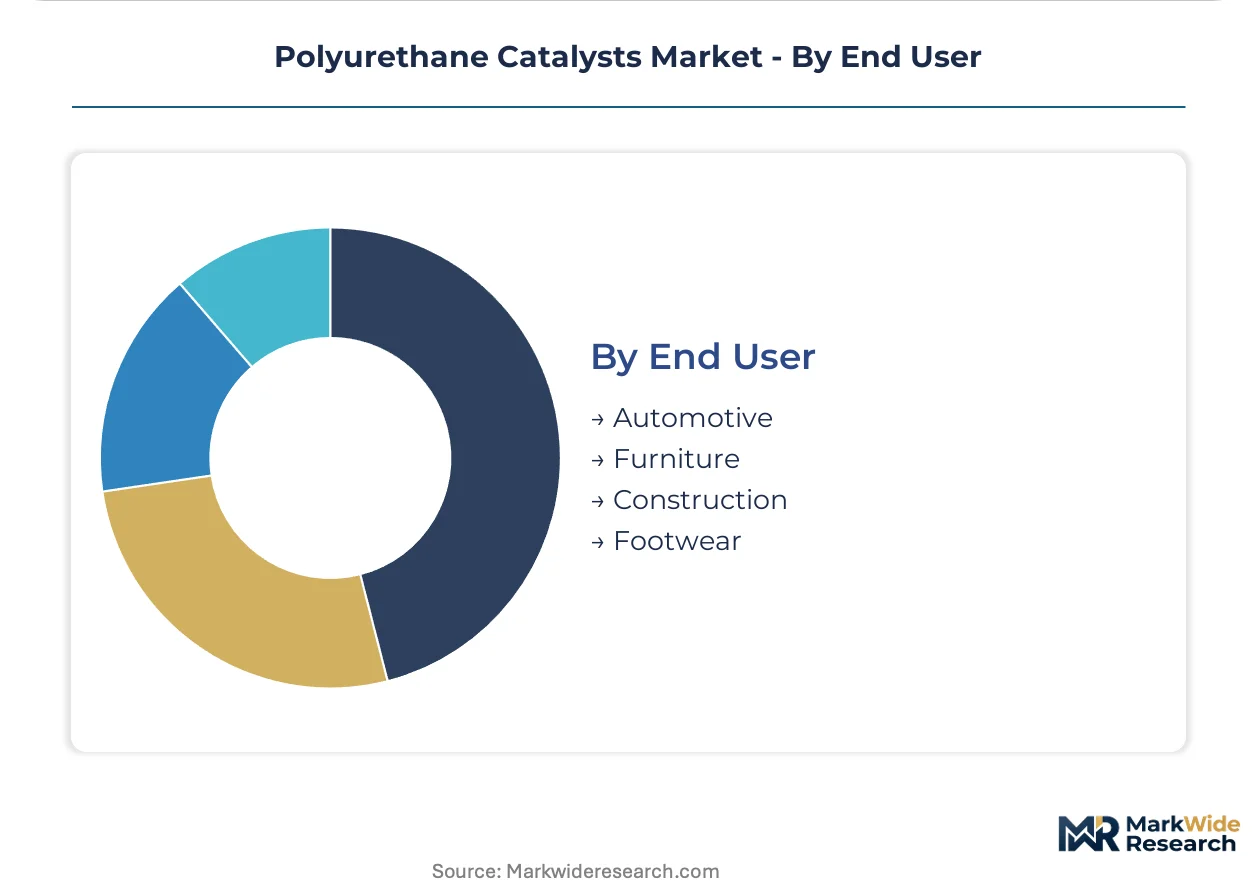
End User:
End-user concentration varies sharply between fragmented furniture producers and consolidated automotive seating tiers.
- Automotive:Seating and interior trim specifications from Detroit, Stuttgart, and Shanghai OEMs drive catalyst innovation toward low-VOC, rapid-cure systems. Density reduction targets for fleet compliance are expanding catalyst consumption per vehicle despite lighter foam weights.
- Furniture:Bedding and upholstery manufacturers in North Carolina and Guangdong operate on mature replacement cycles with stable catalyst demand patterns.
- Construction:Prefabricated building adoption in Guangdong and Jiangsu provinces is pulling rigid foam catalyst volume through insulated panel specifications. India's affordable housing mandates in Maharashtra and Gujarat are creating first-mover opportunities for technical service investment.
- Footwear:Midsole and bonding applications in Fujian and Vietnam manufacturing clusters specify polyester-compatible catalyst systems for durability requirements.
Automotive applications dominate catalyst value capture; construction is expanding most quickly as building energy codes tighten across Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta chemical corridor anchors global polyurethane catalyst consumption through integrated polyol-catalyst manufacturing clusters serving construction and appliance sectors.
China
Prefabricated building adoption in Guangdong and Jiangsu provinces drives rigid foam catalyst demand for insulated wall panels. MEE volatile organic compound emission standards enforce reformulation toward low-emission amine systems. Catalyst-polyol integrated supply relationships concentrate manufacturing in Shanghai and Ningbo chemical parks.
Germany
Bavarian appliance OEMs specify amine catalysts calibrated to hydrofluoroolefin thermal profiles under EU F-Gas Regulation timelines. ECHA REACH restrictions on organotin compounds accelerate migration toward bismuth-based alternatives. Ludwigshafen and Leverkusen chemical parks host specialized organometallic synthesis capabilities for tin-free catalyst production.
United States
Midwest refrigerator manufacturers match catalyst systems to reduced-potency blowing agents under EPA SNAP regulations. Automotive seating plants in Michigan and Tennessee expand catalyst consumption per vehicle through density reduction initiatives. Ohio and Kentucky foam suppliers consolidate purchases around integrated catalyst-polyol platforms.
India
Affordable housing mandates in Maharashtra and Gujarat create rigid foam demand for construction insulation. BIS standards for building materials indirectly shape catalyst specification requirements for local formulators. Cold-chain infrastructure expansion in Mumbai-Pune corridor pulls volume through technical service relationships.
Japan
Automotive interior specifications from Toyota City and Yokohama OEMs drive low-VOC catalyst innovation for seating applications. METI energy-efficiency guidelines for appliances align catalyst selection with rigid foam thermal performance targets. Chubu region chemical producers specialize in delayed-action systems for precision molding operations.
Polyurethane Catalysts Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive polyol-catalyst systems. Three to five multinational suppliers dominate formulation volumes through backward integration into amine precursor production. Strategic archetypes separate into integrated systems providers, specialty amine developers, and regional toll manufacturers. Capacity expansion in Chinese Yangtze Delta chemical parks and technology licensing partnerships represent the dominant competitive moves.
Among European-based integrated suppliers, BASF SE and Evonik Industries AG exemplify the systems-provider archetype through Rhineland chemical park infrastructure. Huntsman International LLC occupies a position within the specialty formulation tier, reflecting US Gulf Coast manufacturing heritage. These three entities anchor the premium segment through technical service capabilities and regulatory compliance portfolios spanning REACH, EPA SNAP, and China MEE frameworks.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Huntsman International LLC |
| Covestro AG |
| Dow Chemical Company |
| Momentive Performance Materials Inc. |
| Tosoh Corporation |
| Air Products and Chemicals, Inc. |
| Umicore |
| Others |
Supply Flow & Price Mechanics
Specialist formulation chemists concentrated in Ludwigshafen, Basel, and Shanghai command wage premiums that propagate through catalyst pricing tiers, compressing spreads between standard amine packages and premium organometallic systems as labor costs anchor value capture in high-complexity synthesis.
Pricing Analysis
Yield-guarantee contracts tied to foam throughput metrics anchor value-based pricing for integrated catalyst-polyol systems. BASF and Evonik stratify offerings across certification-grade tiers—REACH-compliant bismuth alternatives command premiums over standard tertiary amines, while economy-grade packages serve commodity furniture producers. Pricing pressure stems from ethylene oxide feedstock volatility transmitted through polyol cost pass-through mechanisms. Appliance OEMs in Bavaria and Michigan exhibit lowest price sensitivity due to qualification lock-in effects; spray foam contractors in Texas and Florida show highest sensitivity, driving spot-market purchasing for non-integrated amine packages.
Supply Chain Analysis
Reverse-logistics channels for spent catalyst recovery remain underdeveloped, constraining circularity economics as bismuth and zinc precursors face mounting reclamation mandates under extended producer responsibility frameworks. Amine precursor production clusters in Germany's Rhineland and China's Yangtze River Delta feed formulation plants across three continents. Critical dependencies include ethylene oxide from Gulf Coast crackers, specialty metal salts from Belgian refiners, and nitrogen intermediates from Sinopec complexes. Single-source vulnerability concentrates in organometallic synthesis capabilities at Ludwigshafen and Leverkusen. Distribution runs through integrated polyol-catalyst platforms for appliance and automotive tiers, with spot-market chemical distributors serving fragmented construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH organotin prohibitions function as a compliance moat, elevating capital requirements for bismuth catalyst qualification and consolidating margin capture among incumbent REACH-registered suppliers with existing dossier infrastructure.
For Market Incumbents: Deepen backward integration into amine precursor production at Ningbo and Ludwigshafen chemical parks to defend against Chinese state-backed entrants capturing standard-grade volume. Accelerate REACH registration timelines for next-generation zirconium catalysts before regulatory windows narrow. Lock in appliance OEM specification consolidation through integrated technical service teams embedded at Ohio and Tennessee foam plants. For New Entrants and Emerging Players: The premium-economy pricing gap in Indian rigid foam catalysts creates entry space for technical service-focused regional formulators. Target Maharashtra and Gujarat construction insulation markets where affordable housing mandates outpace established supplier technical coverage. Pursue toll-manufacturing partnerships with Yangtze Delta chemical park operators to bypass capital-intensive precursor synthesis. For Investors and Strategic Acquirers: Re-rating potential sits with specialty amine developers possessing REACH-registered bismuth platforms given EU F-Gas Regulation acceleration and refrigerant transition catalyst specification windows. Five-to-ten-year viability favors suppliers with dual US-Europe regulatory compliance infrastructure over pure-play Chinese volume competitors. Monitor EPA SNAP hydrofluoroolefin adoption timelines as inflection signals for catalyst-polyol integrated system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Precursors | Captures margin compression from ethylene oxide volatility at Rhineland and Yangtze Delta hubs. |
| REACH Registration Acceleration for Zirconium Catalysts | Secures regulatory runway before ECHA tightens organometallic substitution timelines. |
| Technical Service Localization in India | Exploits Maharashtra and Gujarat affordable housing mandates outpacing incumbent coverage. |
| AI-Driven Formulation Platform Deployment | Reduces on-site laboratory dependency for dispersed Texas and Florida spray foam contractors. |
| Integrated Catalyst-Polyol System Lock-In | Transfers technical risk upstream at Ohio and Tennessee refrigerator OEM qualification stages. |
Methodological Framework
Trade databases, ECHA REACH registration dossiers, and SEC chemical segment filings formed the secondary backbone, cross-referenced with primary interviews involving polyurethane plant managers, appliance OEM procurement leads, automotive seating foam engineers, and specialty chemical distribution channel heads. Bottom-up catalyst loading estimates by application segment triangulated against top-down polyol consumption forecasts from ACC and Cefic industry reports.
Historical trendline analysis of amine and organometallic price spreads informed elasticity assumptions across the projection horizon. Segmentation modeling incorporated chemistry type, foam formulation chemistry, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from slope-consistency tests against patent filing velocities and capacity announcement pipelines. Forecast inputs included EPA SNAP refrigerant transition schedules and EU F-Gas Regulation phase-down timelines.
Inputs from ECHA registration databases and China MEE emission standard filings were available through the study window; gaps in Indian BIS catalyst-specific standard development introduce uncertainty bands around Maharashtra and Gujarat demand projections. Forecasts embed assumptions regarding REACH enforcement consistency and hydrofluoroolefin blowing agent adoption curves. Practitioners should monitor EPA SNAP rulemaking dockets and ECHA SVHC candidate list updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Light Powered Catalyst Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
North America Refining Catalysts Market
Catalysts
Catalyst Regeneration Market
Catalysts
Steam Methane Reforming Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Photocatalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Zeolite Molecular Sieve Market
Catalysts
Global VOC Catalysts Market
Catalysts
North America Zeolite Market
Catalysts
Refining Catalysts Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Catalyst Handling Services Market
Catalysts
Industrial Catalytic Converters Market