
 CO2 Reforming Catalysts Market | 2026-2036
CO2 Reforming Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
CO2 Reforming Catalysts Market Analytics
Energy sector procurement is collapsing toward large-scale hydrogen and synthetic fuel producers as the dominant buyer archetype. BASF leverages its integrated catalyst manufacturing and petrochemical feedstock expertise to sustain long-term supply relationships. Johnson Matthey anchors its position through proprietary reforming technology leadership and deep partnerships with blue hydrogen developers. Haldor Topsoe competes on high-temperature catalyst stability and modular reforming system integration.
CO2 reforming catalysts are heterogeneous materials—typically nickel, cobalt, or noble metal formulations supported on alumina, ceria-zirconia, or perovskite structures—that catalyze the dry reforming of methane with carbon dioxide to produce synthesis gas at operating temperatures between 700°C and 1000°C. Fixed bed catalysts dominate current industrial deployment due to proven reactor compatibility and lower capital retrofit requirements, while membrane catalysts represent the fastest-growing technology segment as integrated reaction-separation systems reduce downstream purification costs. The energy sector application of synthesis gas production commands the largest volume share, though hydrogen production applications are attracting disproportionate R&D investment.
The EU Green Deal and REACH chemical safety protocols shape product formulation standards and market access conditions for catalyst suppliers operating in Europe. China's MIIT dual carbon targets and GB emissions standards mandate industrial CO2 utilization rates that directly stimulate domestic catalyst procurement. EPA stationary source regulations in the United States create compliance pathways that favor reforming-based carbon management over end-of-pipe capture. Stakeholders must monitor evolving carbon border adjustment mechanisms and national hydrogen strategies to anticipate demand shifts and certification requirements.
Market Dynamics
Carbon pricing mechanisms across the European Union, China, and the United States are restructuring procurement economics for CO2 reforming catalysts. Buyers now treat catalyst selection as a compliance instrument rather than a commodity purchase, with carbon intensity metrics embedded in supplier scorecards.
Growth Catalysts
- EU Green Deal carbon border adjustments:Industrial importers face embedded carbon tariffs that make domestic reforming-based hydrogen production cost-competitive against unabated imports. German chemical clusters are retrofitting steam methane reformers with dry reforming catalysts to secure CBAM-compliant supply chains.
- China MIIT dual carbon mandates:Steel and chemical sectors must achieve peak carbon emissions before 2030. State-owned enterprises in Shandong and Jiangsu provinces are procuring nickel-ceria reforming catalysts to convert captured CO2 into synthesis gas for methanol production.
- Synthetic fuel offtake agreements:Aviation and maritime fuel producers in Rotterdam, Houston, and Singapore are signing decade-long catalyst supply contracts tied to e-fuel production quotas. These agreements de-risk capital deployment for reforming plant operators.
Market Restraints
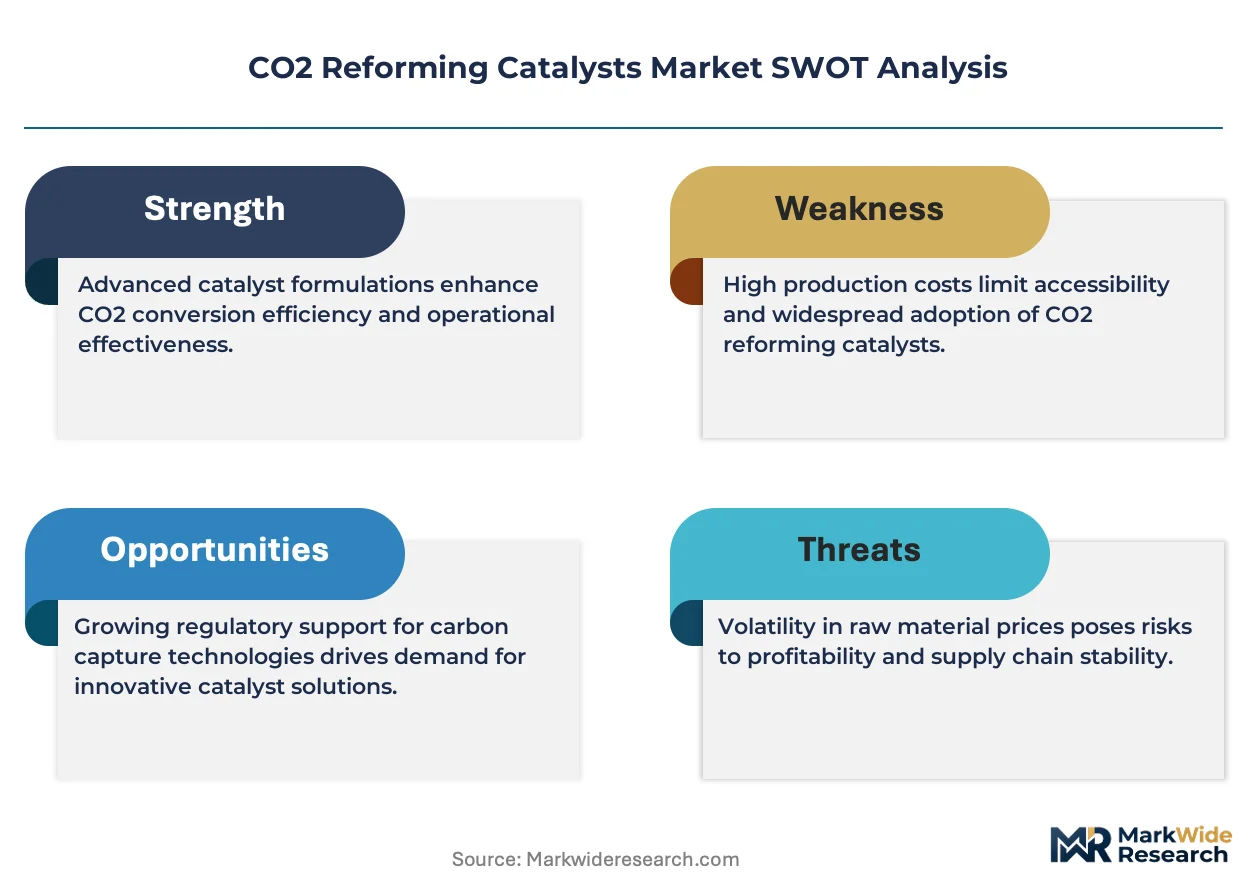
- Noble metal cost volatility:Rhodium and ruthenium price swings exceeding 40% annually compress margins for high-activity catalyst formulations. Platinum-group metal dependency limits adoption in price-sensitive industrial hydrogen projects.
- Alumina supply concentration:Gamma-alumina support materials for catalyst substrates concentrate in Chinese and Russian production facilities. Western catalyst manufacturers face raw material security risks from geopolitical trade restrictions.
- Coking degradation limits:Nickel-based catalysts suffer rapid carbon deposition during dry reforming operations above 850°C. Thermal stability constraints force shorter replacement cycles than steam methane reforming equivalents.
Strategic Opportunities
- US Inflation Reduction Act hydrogen hubs:Regional clean hydrogen production networks in Texas, California, and Appalachia allocate federal cost-sharing for reforming-based blue hydrogen. Catalyst suppliers can anchor long-term service contracts through hub consortium participation.
- Perovskite-structured catalyst convergence:Integration of solid oxide electrolysis cells with dry reforming reactors enables electrochemical CO2 activation. Combined systems reduce operating temperatures while maintaining syngas output quality.
- India PLI scheme for green hydrogen:Production-linked incentives for electrolyzer manufacturing create adjacent demand for reforming catalysts in hybrid hydrogen production configurations. Domestic catalyst formulation capabilities remain underdeveloped relative to projected demand.
Industry Challenges
- High-temperature materials engineering expertise:Catalyst development requires rare combinations of heterogeneous catalysis knowledge and reactor design experience. European and North American universities produce insufficient graduates with relevant dual competencies.
- REACH registration timelines:Novel catalyst formulations face 18-24 month approval cycles for European market entry. Registration costs for small-batch specialty catalysts disproportionately burden mid-size suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CO2 Reforming Catalysts Market |
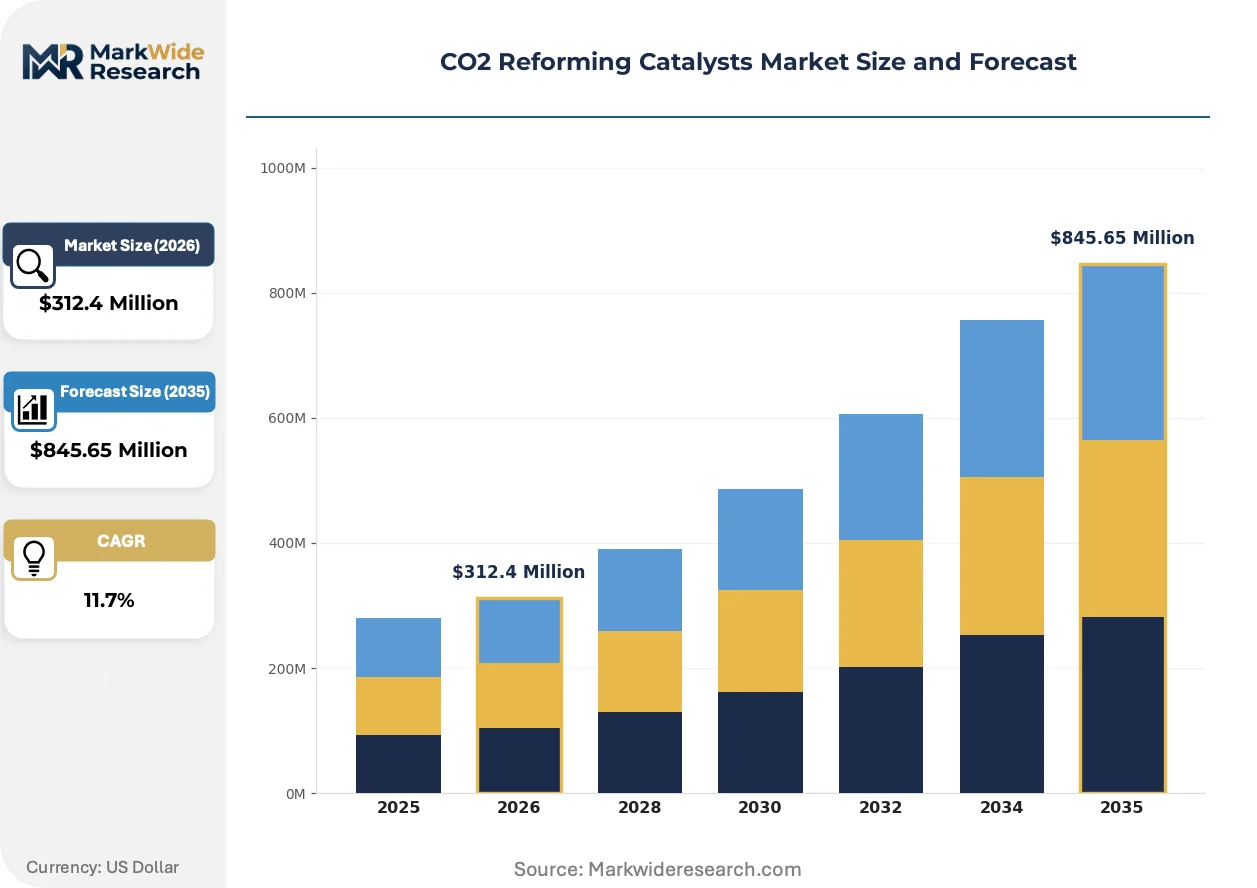
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bed Catalysts, Fluidized Bed Catalysts, Membrane Catalysts, Monolithic Catalysts Technology: Chemical Looping, Plasma Technology, Solvated Electrode, Hydrogenation End User: Chemical Industry, Energy Sector, Environmental Applications, Research Institutions Application: Synthesis Gas Production, Methanol Production, Hydrogen Production, CO2 Utilization |
| Companies Covered | TANAKA, Chiyoda Corporation, BASF, Dorf Ketal, Linde Engineering, Filtra Catalysts, HYCO1, Haldor Topsoe, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CO2 Reforming Catalysts Market Evolving Landscape
Reforming catalyst technology is fragmenting along performance-versus-cost tradeoffs as end-use applications diversify. Suppliers must now maintain parallel development tracks for commodity hydrogen production and premium synthetic fuel applications.
Membrane-integrated reforming catalysts are bifurcating the technology landscape. These palladium-alloy or ceramic membrane systems combine reaction and separation in single units, eliminating downstream water-gas shift stages. Blue hydrogen developers in the Netherlands and Canada are piloting membrane catalysts at 50-100 MW scale, with commercial deployment targeted for industrial clusters. The technology is bifurcating project economics by reducing capital intensity for small-scale distributed hydrogen production while pressuring traditional fixed-bed suppliers to demonstrate cost parity at large scale.
REACH chemical safety protocols are tightening substance authorization requirements for nickel catalyst precursors. The European Chemicals Agency's 2024 restriction proposal on nickel compounds threatens reforming catalyst import pathways. Catalyst suppliers are accelerating cobalt and iron-based formulation development to maintain European market access. German and French chemical regulators are coordinating transitional approval periods to prevent supply disruption during formulation substitution.
Long-term catalyst leasing models are displacing conventional equipment purchase contracts. Synthetic fuel producers in Rotterdam and Houston prefer performance-guaranteed supply agreements that bundle catalyst replacement, regeneration, and spent material recovery. This restructuring transfers technical risk to catalyst manufacturers while locking in decade-long revenue streams. The leasing transition is most advanced in European industrial clusters where carbon accounting requirements favor supplier-managed circular material flows.
CO2 Reforming Catalysts Market Segmentation
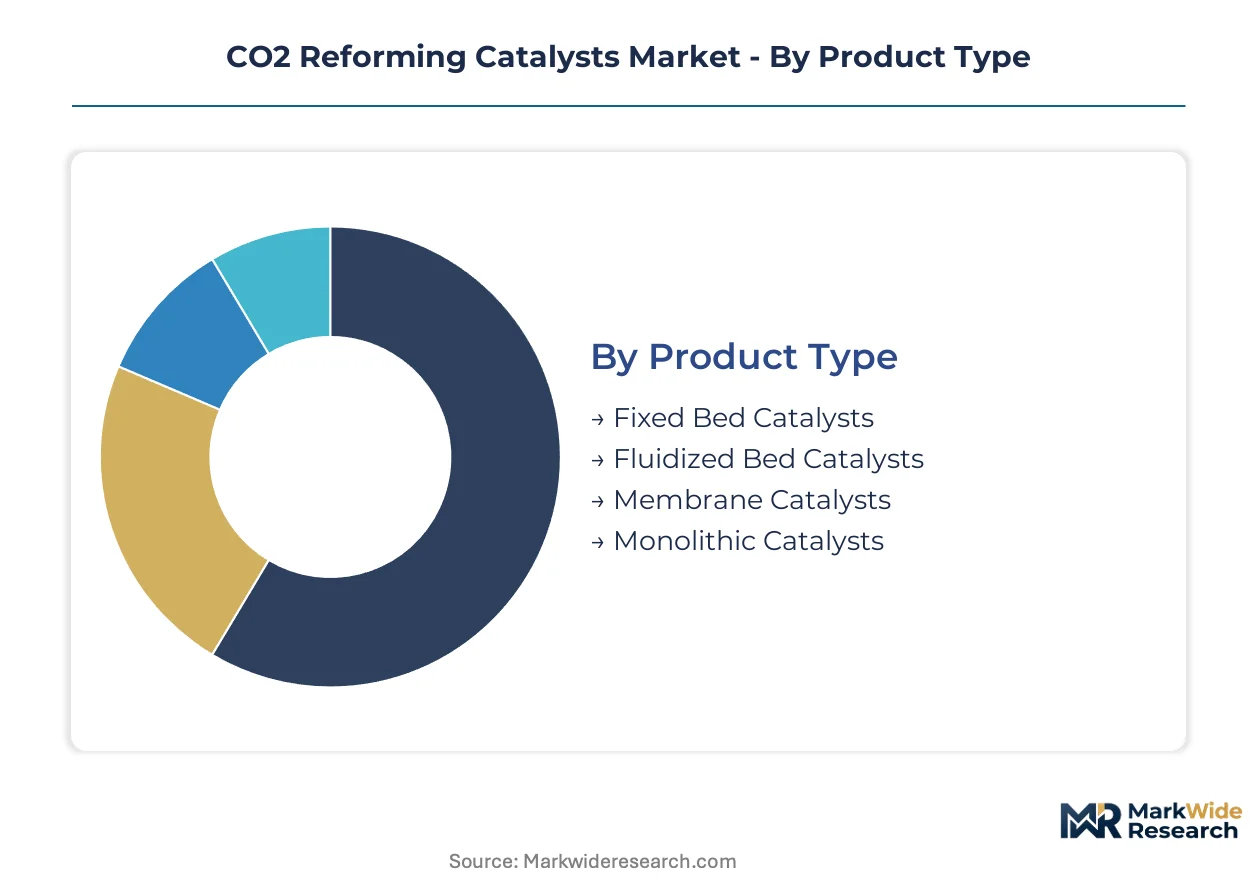
CO2 reforming catalyst buyers select formulations based on reactor compatibility, carbon intensity targets, and feedstock flexibility. Segmentation reveals where proprietary technology commands premium pricing versus where commodity specifications dominate procurement. Suppliers must align R&D investment with the performance thresholds each segment demands.
Product Type:
Membrane catalysts face the strongest substitution pressure from next-generation electrochemical systems, while fixed bed formats resist displacement due to installed base inertia and lower retrofit capital requirements.
- Fixed Bed Catalysts:Pellet or extruded nickel-alumina formulations loaded into tubular reactors dominate existing steam methane reformer retrofits. German chemical clusters in Ludwigshafen and Marl procure these catalysts for dry reforming conversions that preserve reactor pressure vessels and burner configurations.
- Membrane Catalysts:Palladium-alloy or ceramic membrane systems integrate hydrogen separation with methane-CO2 reforming in single units. Pilot deployments at Rotterdam and Houston hydrogen hubs target 50-100 MW scale commercialization by eliminating downstream water-gas shift stages and pressure swing adsorption units.
- Fluidized Bed Catalysts:Attrition-resistant alumina-supported formulations enable continuous catalyst regeneration in circulating reactor configurations. Fluid catalytic cracking technology transfer from petroleum refining accelerates adoption in Chinese methanol-to-olefins complexes.
- Monolithic Catalysts:Ceramic honeycomb substrates coated with active metal washcoats minimize pressure drop in compact reactor designs. Modular hydrogen production skids for distributed fueling stations favor these configurations for rapid start-stop cycling.
Fixed bed catalysts anchor the volume base while membrane catalysts gain share at the steepest rate.
Technology:
Cost tier stratification separates mature thermal processes from electrochemical routes still seeking scale economies.
- Chemical Looping:Oxygen carrier materials—typically iron, nickel, or copper oxides—cycle between oxidation and reduction zones to supply lattice oxygen for partial oxidation reforming without air separation units. Texas clean hydrogen hub developers evaluate chemical looping for inherent CO2 capture integration.
- Plasma Technology:Non-equilibrium plasma discharges activate methane and CO2 at lower temperatures than thermal catalysis. Research institutions in Eindhoven and Toronto pursue plasma-catalytic hybrid systems for distributed synthetic fuel production.
- Solvated Electrode:Molten salt or ionic liquid electrolytes enable electrochemical CO2 reduction at elevated pressures. Technology readiness gaps limit procurement to pilot-scale electrolyzer manufacturers.
- Hydrogenation:Direct CO2 hydrogenation to methane or methanol using nickel or copper-zinc catalysts competes with reforming-based syngas routes. Methanol producers in Shandong province evaluate hydrogenation against dry reforming for carbon utilization compliance.
Chemical looping captures the largest project pipeline while plasma technology expands most quickly in research-driven procurement.
End User:
Application maturity determines margin structure—energy sector buyers negotiate long-term service contracts while research institutions pay premiums for custom formulations.
- Energy Sector:Blue hydrogen developers and synthetic fuel producers procure catalysts under performance-guaranteed leasing arrangements. Rotterdam and Houston offtake agreements bundle catalyst supply with regeneration services and spent material recovery.
- Chemical Industry:Methanol and ammonia producers retrofit existing reformers with dry reforming catalysts to meet EU carbon border adjustment requirements. BASF and Covestro procurement teams embed carbon intensity metrics in supplier scorecards.
- Environmental Applications:Landfill gas and biogas upgrading facilities use CO2 reforming to convert methane-CO2 mixtures into pipeline-quality hydrogen or syngas. California low-carbon fuel standard credits improve project economics.
- Research Institutions:National laboratories and university consortia purchase small-batch perovskite and ceria-zirconia formulations for mechanistic studies. REACH registration burdens disproportionately limit European supplier participation.
The energy sector dominates contract value while the chemical industry provides the most predictable replacement demand.
Application:
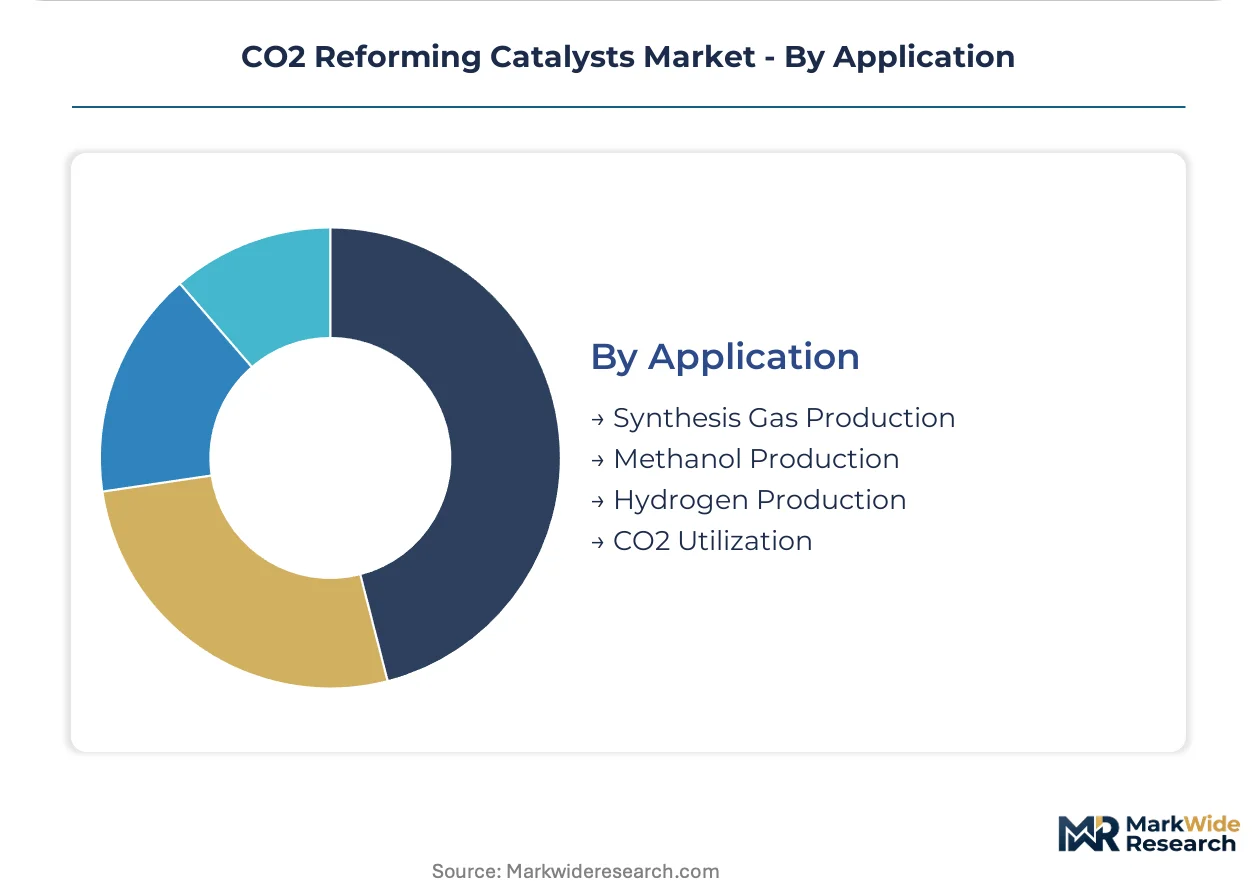
Customer type concentration varies—synthesis gas production serves diversified chemical buyers whereas hydrogen production concentrates among integrated energy companies.
- Synthesis Gas Production:Nickel-alumina and cobalt-ceria catalysts convert methane-CO2 mixtures into H2:CO ratios tailored for Fischer-Tropsch or methanol synthesis. German steelmakers in Duisburg integrate reforming with direct reduction iron processes.
- Hydrogen Production:High-purity hydrogen for ammonia and refining applications demands low methane slip and stable operation above 900°C. US Gulf Coast hydrogen hub consortia specify catalysts compatible with carbon capture and sequestration integration.
- Methanol Production:Copper-zinc-alumina catalysts downstream of reforming units convert syngas to methanol. Chinese state-owned enterprises in Ningxia and Inner Mongolia expand coal-to-methanol capacity with CO2 co-feeding.
- CO2 Utilization:Direct catalytic conversion of captured CO2 into chemicals or fuels without methane feedstock remains pre-commercial. EU Innovation Fund projects in Antwerp and Port of Rotterdam test novel routes.
Synthesis gas production anchors installed capacity while hydrogen production attracts the steepest capacity expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam hydrogen backbone pipeline anchors European reforming catalyst procurement. This cross-border infrastructure connects Dutch chemical clusters to German industrial demand centers. Texas Gulf Coast hydrogen hub networks underwrite North American deployment scale.
Germany
Ludwigshafen and Marl chemical clusters drive nickel-alumina catalyst procurement for steam methane reformer retrofits. EU Green Deal carbon border adjustments force domestic reforming adoption. BASF and Covestro procurement teams embed carbon intensity metrics in supplier scorecards.
China
Shandong and Jiangsu steel and chemical sectors must achieve peak carbon emissions before 2030. MIIT dual carbon mandates require industrial CO2 utilization rates that stimulate domestic catalyst procurement. State-owned enterprises in Ningxia and Inner Mongolia expand coal-to-methanol capacity with CO2 co-feeding.
United States
Texas clean hydrogen hub developers evaluate chemical looping for inherent CO2 capture integration. EPA stationary source regulations create compliance pathways favoring reforming-based carbon management. Houston and California hydrogen hub consortia specify catalysts compatible with carbon capture and sequestration.
Netherlands
Rotterdam hydrogen backbone terminals enable blue hydrogen exports to German industrial buyers. ETS coverage expansion accelerates compliance-driven catalyst demand. Port of Rotterdam e-fuel producers sign decade-long catalyst supply contracts tied to aviation and maritime fuel production quotas.
India
Production-linked incentives for electrolyzer manufacturing create adjacent demand for reforming catalysts in hybrid configurations. PLI scheme for green hydrogen outpaces domestic catalyst formulation capabilities. Reliance Industries and Indian Oil evaluate reforming integration at Jamnagar and Paradip refining complexes.
CO2 Reforming Catalysts Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and specialized catalyst manufacturers. The vendor base spans three tiers: petrochemical majors with captive catalyst production, dedicated heterogeneous catalysis specialists, and regional formulation houses serving retrofit markets. Strategic moves center on long-term service contract anchoring and formulation substitution to navigate REACH nickel restrictions.
Among diversified chemical conglomerates, BASF and Johnson Matthey exemplify the integrated-petrochemical archetype with reforming technology leadership and deep energy sector relationships. Haldor Topsoe occupies a position within the specialized catalysis tier, competing on high-temperature stability and modular system integration. These three anchors represent distinct competitive vectors: feedstock integration, proprietary technology licensing, and reactor-catalyst bundling.
| Leading Market Players |
|---|
| TANAKA |
| Chiyoda Corporation |
| BASF |
| Dorf Ketal |
| Linde Engineering |
| Filtra Catalysts |
| HYCO1 |
| Haldor Topsoe |
| Johnson Matthey |
| Others |
Value Network & Pricing Analysis
Six-month catalyst formulation lead times concentrate pricing power among integrated manufacturers with captive alumina processing capabilities, while buyers in Rotterdam and Houston hydrogen hubs absorb premium markups for REACH-compliant nickel alternatives. Inventory buffers at German chemical clusters rarely exceed 45 days, forcing spot-market exposure when Chinese gamma-alumina shipments face customs delays.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates membrane-integrated palladium-alloy systems from fixed-bed nickel-alumina formulations and commodity cobalt-ceria catalysts. Price differentiation hinges on thermal stability certification under EU ETS carbon intensity thresholds and bundled regeneration service terms. Cost compression in standard-grade fixed-bed catalysts is intensifying because Chinese state-owned enterprises are flooding methanol retrofit markets with domestic ceria-zirconia formulations. Research institutions exhibit the highest price sensitivity due to small-batch procurement volumes, while synthetic fuel producers in maritime aviation clusters prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strait of Malacca transit routes carry 60% of global gamma-alumina substrate shipments from Chinese and Russian production facilities to European catalyst formulators. Raw material dependencies center on nickel laterite concentrates from Indonesia, platinum-group metal sponge from South Africa, and rare-earth stabilized ceria from Chinese separation plants. Single-source vulnerability concentrates in palladium-alloy membrane fabrication, where Johnson Matthey and Tanaka hold overlapping patent thickets around hydrogen-selective foil production. Distribution runs through long-term service contracts that bundle catalyst loading, regeneration cycles, and spent material recovery, displacing spot-market spot transactions in European industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating toward synthetic fuel offtake consortia in Rotterdam, Houston, and Singapore, where decade-long catalyst supply contracts now outnumber spot procurement by a four-to-one ratio. This consolidation forces suppliers to accept performance-guaranteed leasing terms that transfer technical risk downstream.
For Market Incumbents: Fortify backward integration into alumina substrate production to escape Chinese supply concentration, while accelerating cobalt-iron formulation pipelines ahead of ECHA nickel restriction enforcement. BASF and Haldor Topsoe should anchor capacity expansion in Texas hydrogen hub corridors to capture IRA cost-sharing allocations before regional consortiums finalize vendor panels. For New Entrants and Emerging Players: Differentiate on modular membrane catalyst skids for distributed hydrogen fueling stations, where incumbent fixed-bed suppliers lack rapid start-stop cycling expertise. India's PLI scheme for electrolyzer manufacturing creates the most penetrable white space, given domestic catalyst formulation capabilities lag projected demand by a three-to-five year gap. Pursue joint development agreements with Reliance Industries at Jamnagar to bypass established channel relationships. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because carbon border adjustments and ETS expansion embed reforming catalysts as non-discretionary inputs for EU chemical and steel sector survival. Acquisition targets should display dual competencies in heterogeneous catalysis and reactor engineering, with active patent portfolios in perovskite-structured materials. Watch for inflection when EU Innovation Fund disbursements trigger commercial-scale CO2 utilization project FIDs at Antwerp and Port of Rotterdam.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Substrates | Reduces exposure to Chinese gamma-alumina supply concentration under REACH chemical safety protocols. |
| Long-term Service Contract Anchoring | Locks in decade-long revenue streams with Rotterdam and Houston synthetic fuel producers under performance guarantees. |
| Perovskite-Structured Catalyst Development | Enables solid oxide electrolysis integration that lowers operating temperatures while maintaining syngas output quality. |
| Joint Venture with Hydrogen Hub Consortia | Secures federal cost-sharing allocations under US Inflation Reduction Act regional clean hydrogen production networks. |
| Formulation Substitution for REACH Compliance | Maintains European market access as ECHA nickel compound restrictions threaten incumbent nickel-alumina import pathways. |
Research Methodology
The analysis maps fixed-bed, membrane, fluidized-bed, and monolithic catalyst formats, each validated through catalyst plant managers, hydrogen hub procurement leads, EPC contractors, and petrochemical R&D directors. Primary fieldwork combined structured interviews with downstream OEM procurement teams and technical service heads at BASF, Johnson Matthey, and Haldor Topsoe with secondary validation against customs trade data, SEC 10-K filings, and IEA hydrogen project databases. Bottom-up capacity buildouts by reactor type triangulate against top-down spending flows from EU Innovation Fund and US Department of Energy hydrogen hub allocations.
Consistency checks validated volume and value outputs against external benchmarks including IEA hydrogen supply chain tracking, ETS carbon price correlation models, and regional industrial cluster capex disclosures. The analytical framework models catalyst demand across product type, technology maturity tier, end-user industry, and application chemistry throughout the projection horizon. CAGRs derive from segmented adoption curves weighted by regulatory enforcement timelines and offtake agreement visibility. Industry-specific forecast inputs include ETS coverage expansion schedules and MIIT dual carbon mandate compliance deadlines.
Material uncertainties — rhodium-ruthenium price volatility, alumina supply disruption from geopolitical trade restrictions, and coking degradation rate variability — sit outside the modeled envelope. Forecasts reflect assumptions about carbon pricing mechanism durability and hydrogen hub project execution rates. Revision becomes warranted when EU carbon border adjustment enforcement intensity or China MIIT compliance penalty severity crosses thresholds that alter retrofit economics for steam methane reformer conversions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Global Zeolites Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
North America Industrial Catalyst Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Catalyst Handling Services Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Asia-Pacific Refining Catalysts Market