
 North America Zeolite Market | 2026-2036
North America Zeolite Market Size, Share, and Industry Trends Forecast 2026-2036
North America Zeolite Market Intelligence
Aftermarket catalyst regeneration revenue is narrowing as refiners shift toward longer-lasting synthetic zeolite formulations. BASF SE leverages its integrated catalyst manufacturing network to capture value from this transition. W. R. Grace & Co. sustains its position through specialized FCC catalyst technologies. Honeywell International Inc. controls distribution channels across the U.S. refining belt.
Zeolites are crystalline aluminosilicate minerals with defined pore structures typically measuring 0.3 to 2.0 nanometers, engineered for molecular sieving, cation exchange, and catalytic cracking across industrial processes. Synthetic zeolite dominates value generation in petrochemical catalysis, where precise pore architecture commands premium positioning. Natural zeolite competes on cost in agricultural and water treatment applications, while modified zeolite variants are capturing margin pools in specialized ion-exchange deployments.
The EPA enforces effluent discharge standards that mandate ammonia and heavy metal removal, directly expanding zeolite demand in municipal water infrastructure. OSHA and state-level environmental agencies in Texas and Louisiana impose workplace exposure limits that shape product handling specifications and market access requirements. Stakeholders must monitor evolving state-level PFAS treatment mandates, as these regulations will determine whether modified zeolite or alternative adsorbents capture the next wave of remediation spending.
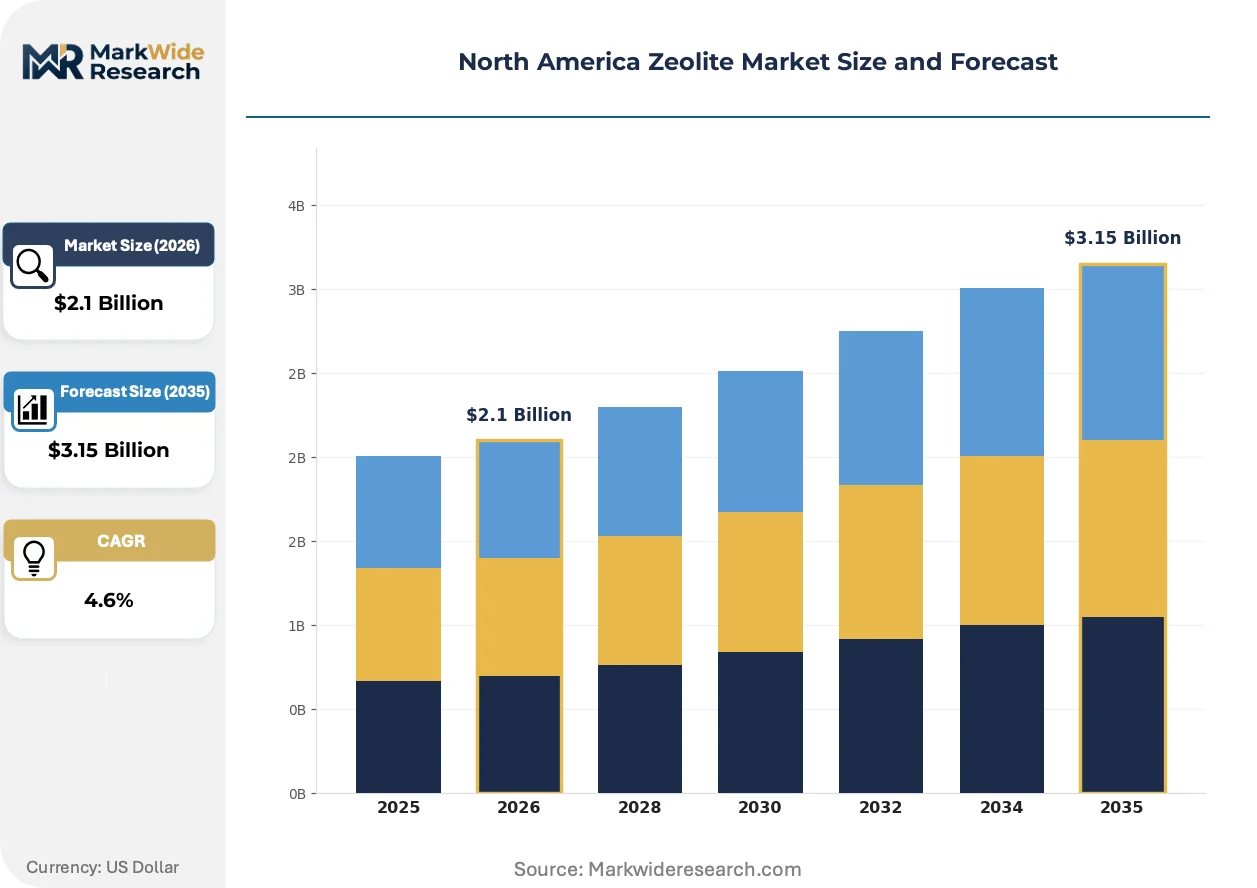
Market Dynamics
The North America zeolite market is experiencing structural compression from EPA effluent limitation guidelines that mandate ammonia and heavy metal removal, forcing municipal water infrastructure upgrades and shortening refinery catalyst replacement cycles across the U.S. Gulf Coast petrochemical corridor.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tightening discharge standards for ammonia and heavy metals are compelling U.S. municipalities to install advanced ion-exchange media in wastewater treatment facilities.
- Petrochemical corridor demand:Refinery catalyst replacement cycles are compressing in Texas and Louisiana as processing intensity rises, accelerating consumption of synthetic zeolite formulations.
- Heavy metal filtration mandates:State-level environmental agencies in the U.S. and Canada are expanding adoption of modified zeolite variants for specialized remediation deployments.
Market Restraints
- Natural gas feedstock volatility:Synthetic zeolite production depends on stable energy inputs, and price swings in North American natural gas markets compress manufacturing margins unpredictably.
- Activated carbon substitution:Municipal water treatment operators in cost-constrained jurisdictions are evaluating granular activated carbon as an alternative adsorbent for organic contaminant removal.
- Prolonged OSHA exposure compliance:Workplace handling specifications for crystalline silica content in natural zeolite mining operations add processing steps and extend facility certification timelines.
Strategic Opportunities
- PFAS treatment mandates:Evolving state-level regulations in Michigan, New York, and California will determine whether modified zeolite or competing adsorbents capture emerging remediation spending pools.
- Canadian agricultural expansion:Underpenetrated soil amendment applications in Alberta and Saskatchewan offer volume growth as natural zeolite competes on cost against synthetic fertilizers.
- Membrane-zeolite hybrid systems:Convergence of ion-exchange media with advanced membrane filtration is opening specialized deployment opportunities in industrial process water recycling.
Industry Challenges
- Catalyst formulation expertise scarcity:FCC zeolite engineering requires specialized knowledge in pore architecture design that concentrates among a limited pool of technical professionals in the Houston-New Orleans corridor.
- Legacy infrastructure integration:Municipal water treatment facilities face mechanical and piping reconfiguration costs when retrofitting zeolite ion-exchange systems into aging concrete basin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Zeolite Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Zeolite, Synthetic Zeolite, Modified Zeolite, Nanostructured Zeolite Application: Catalysts, Adsorbents, Ion-Exchangers, Fertilizers End User: Agriculture, Water Treatment, Petrochemicals, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | St. Cloud Mining, BASF SE, International Zeolite Corp., W. R. Grace & Co., Honeywell International Inc., KMI Zeolite Inc., Bear River Zeolite Co., Tosoh USA, Inc., Zeotech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Zeolite Market Strategic Shifts & Innovations
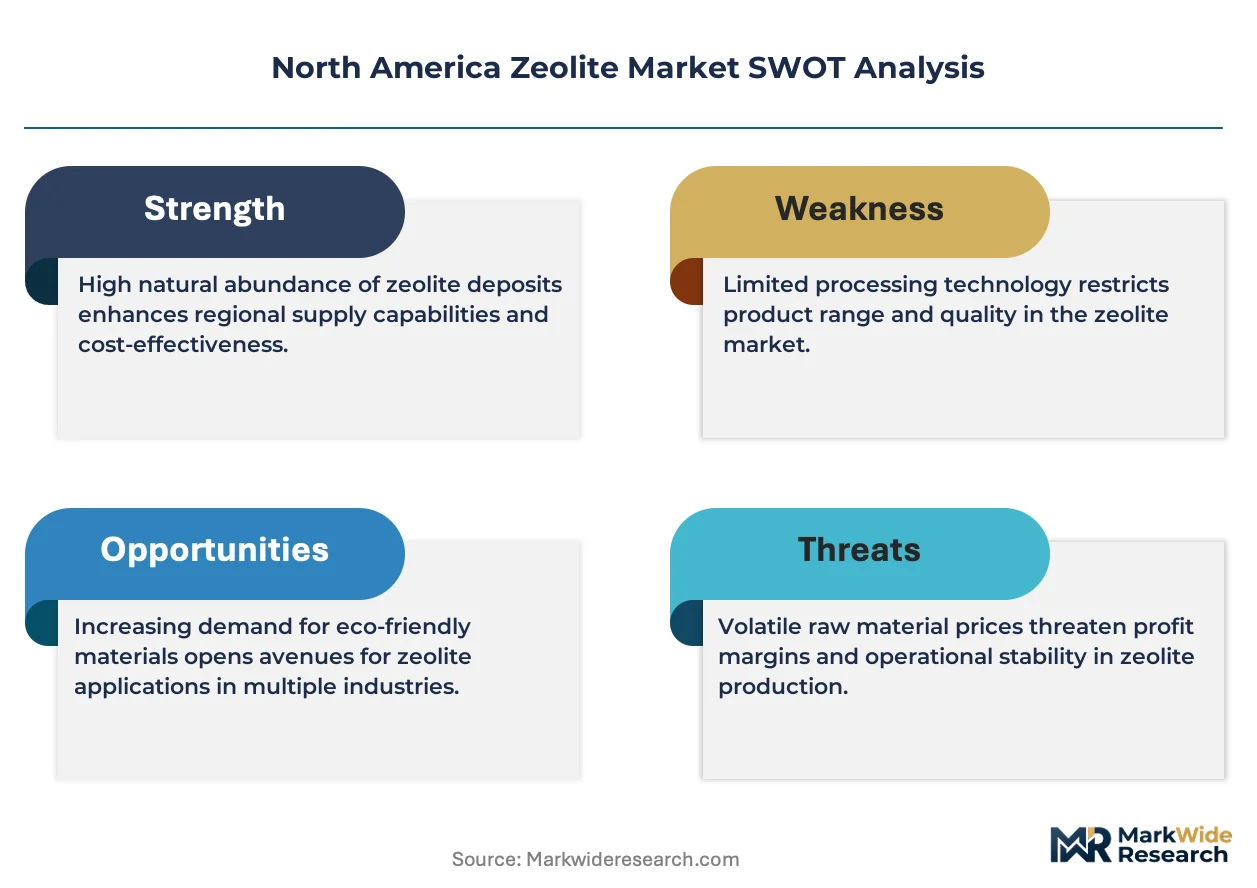
Zeolite innovation across North America is pivoting toward precision-engineered pore architectures and hybrid system designs that extract maximum performance from both synthetic and modified natural variants. Three developments are restructuring competitive positioning.
Synthetic zeolite formulations with hierarchical mesopore-macropore structures are rendering obsolete conventional single-pore FCC catalysts in Gulf Coast refineries. Marathon Petroleum and Valero are accelerating adoption of these dual-pore systems to handle heavier crude slates. The technology is compressing catalyst replacement revenue cycles while elevating technical performance specifications that only integrated manufacturers can satisfy.
The EPA's evolving effluent limitation guidelines are mandating tertiary treatment for ammonia and heavy metal removal in municipal wastewater discharge. This regulatory pressure is expanding ion-exchange media procurement across U.S. water authorities from California to the Great Lakes region. Modified zeolite variants are capturing specification share where natural zeolite pore distributions prove inadequate for targeted contaminant profiles.
Water treatment procurement is consolidating toward performance-based service contracts that bundle media supply, regeneration logistics, and compliance reporting. Municipal buyers in Texas and Florida are displacing transactional spot purchasing with multi-year agreements that transfer operational risk to specialized service providers. This shift favors vendors with captive regeneration facilities and analytical testing capabilities positioned near major metropolitan demand clusters.
North America Zeolite Market Segmentation
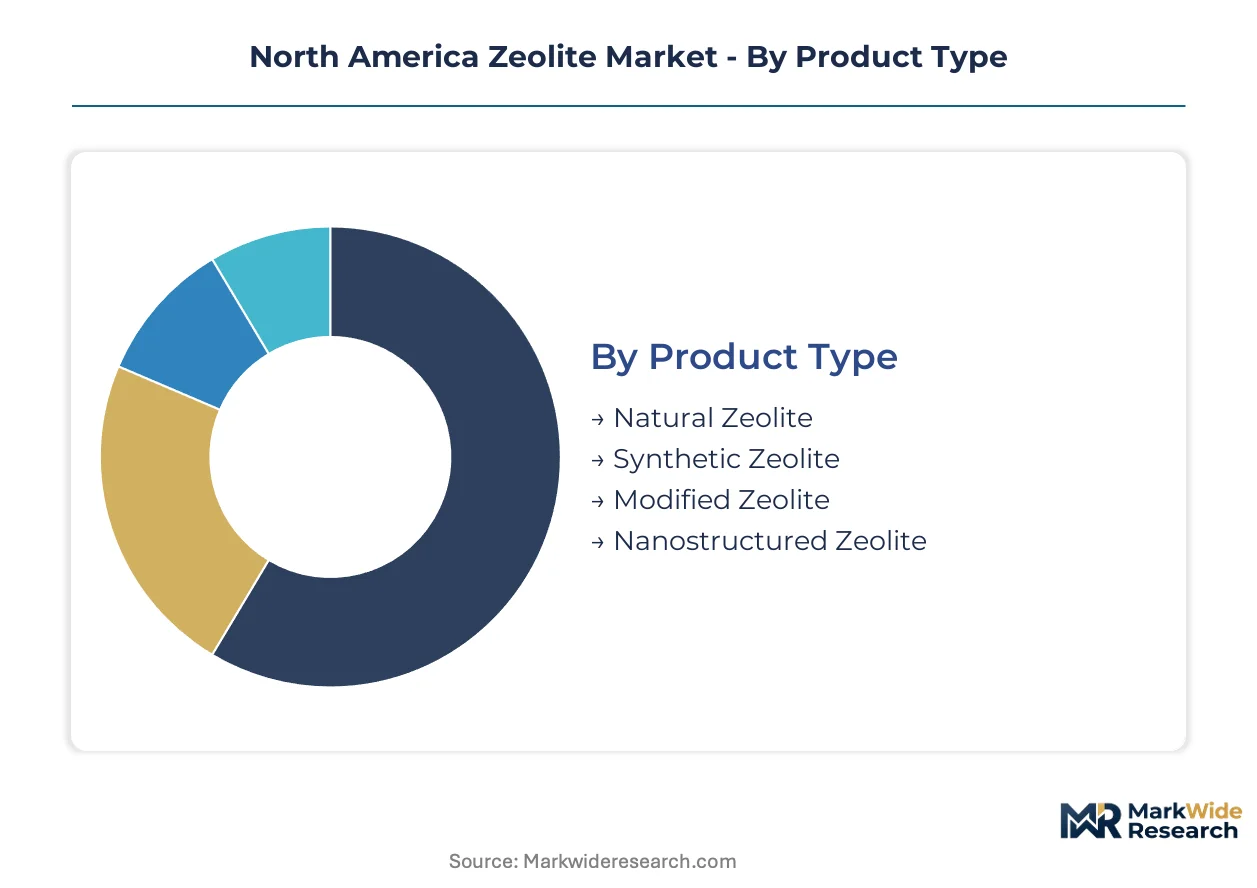
Zeolite segmentation in North America reflects divergent technical requirements across industrial catalysis and environmental remediation. Product architecture, application intensity, and channel economics create distinct margin pools that vendors navigate through specialized service models.
Product Type:
After-sales regeneration intensity varies dramatically across zeolite categories, with synthetic formulations demanding continuous technical support while natural variants require minimal post-sale intervention.
- Natural Zeolite:Mined aluminosilicate minerals with inherent pore structures ranging 0.3 to 2.0 nanometers. Agricultural soil amendment demand concentrates in Alberta and Saskatchewan, where cost positioning against synthetic fertilizers drives procurement decisions.
- Synthetic Zeolite:Engineered crystalline structures with precisely controlled pore architectures command premium positioning in petrochemical catalysis. Gulf Coast refineries in Texas and Louisiana compress replacement cycles as processing intensity rises, elevating service contract attach rates.
- Modified Zeolite:Surface-altered variants optimized for specialized ion-exchange applications including heavy metal filtration.
- Nanostructured Zeolite:Sub-micron engineered particles targeting advanced membrane-zeolite hybrid systems for industrial process water recycling.
By volume, natural zeolite leads. By growth pace, synthetic zeolite is ahead.
Application:
Cost tier stratification separates commodity-grade adsorbents from precision-engineered catalytic systems that absorb disproportionate R&D investment.
- Catalysts:Fluid catalytic cracking (FCC) zeolites dominate value generation through hierarchical mesopore-macropore architectures. Marathon Petroleum and Valero accelerate adoption of dual-pore systems to handle heavier crude slates across the U.S. Gulf Coast.
- Adsorbents:Molecular sieving applications in natural gas processing and industrial drying command mid-tier pricing. The Permian Basin and Appalachian shale corridors sustain steady procurement for dehydration units.
- Ion-Exchangers:Ammonia and heavy metal removal media in municipal wastewater treatment.
- Fertilizers:Slow-release nutrient carriers competing with conventional synthetic products in Canadian prairie agriculture.
Catalysts capture the largest revenue share. Ion-exchangers are climbing the fastest as EPA effluent guidelines tighten.
End User:
Customer maturity diverges sharply between specification-driven petrochemical buyers and price-sensitive agricultural operators.
- Petrochemicals:Integrated refineries and chemical processors in the Houston-New Orleans corridor demand FCC zeolite engineering with specialized pore architecture design. Technical professional scarcity concentrates formulation expertise among limited qualified suppliers.
- Water Treatment:Municipal authorities from California to the Great Lakes region expand tertiary treatment procurement for ammonia removal. Texas and Florida buyers displace spot purchasing with multi-year performance-based service contracts.
- Agriculture:Soil amendment applications in underpenetrated Canadian prairie provinces.
- Construction:Lightweight aggregate and cement additive applications.
Petrochemicals anchor revenue concentration. Water treatment shows the steepest expansion trajectory as infrastructure upgrades accelerate.
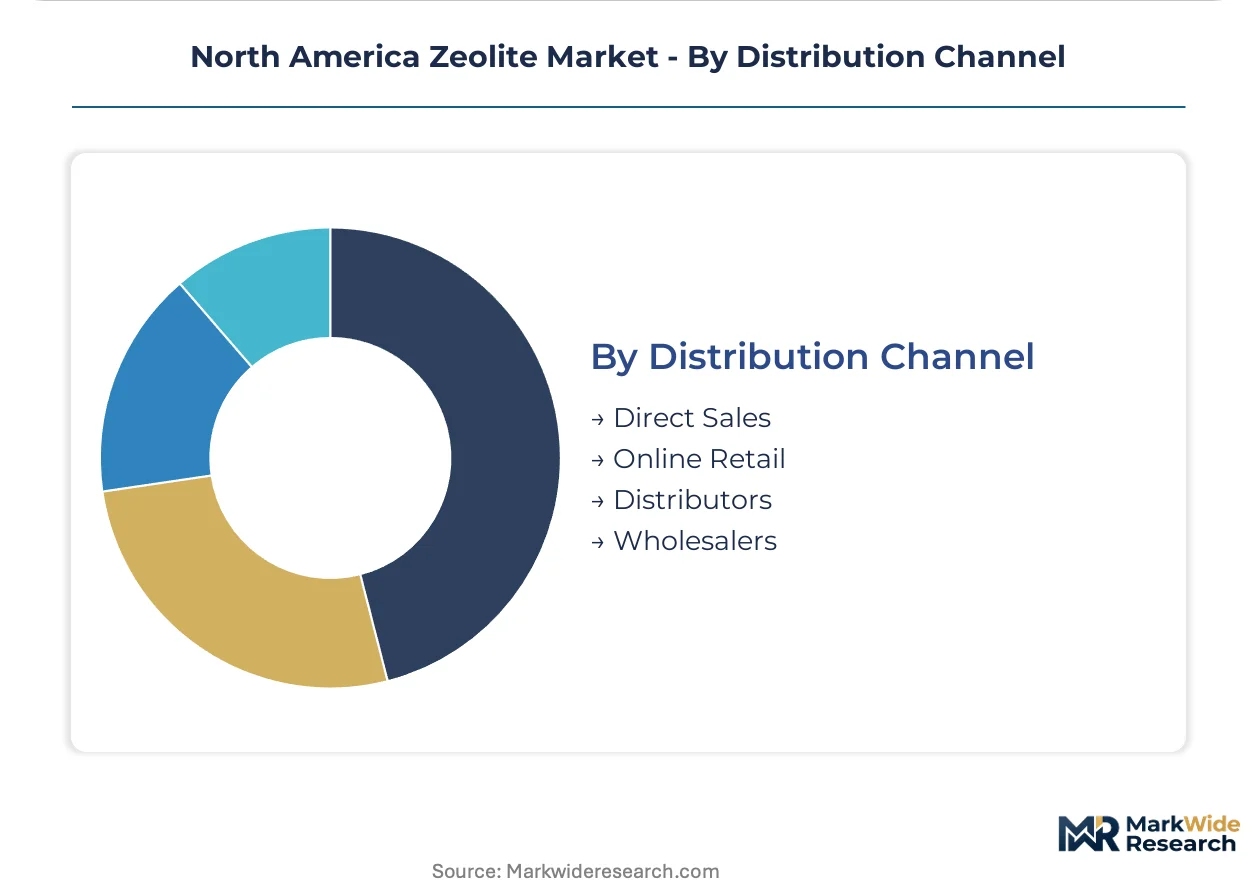
Distribution Channel:
Supply chain configuration determines whether vendors capture value through direct technical relationships or cede margin to intermediary layers.
- Direct Sales:Integrated manufacturers including BASF SE and W. R. Grace & Co. deploy technical sales teams for FCC catalyst specification. Direct relationships with Gulf Coast refineries enable captive regeneration facility positioning.
- Distributors:Regional intermediaries serve fragmented municipal water treatment procurement across mid-size U.S. cities and Canadian provinces.
- Online Retail:Agricultural zeolite for soil amendment moves through digital channels serving small-scale farming operations.
- Wholesalers:Bulk material handlers aggregate natural zeolite volumes for construction and agricultural blending operations.
Direct sales command the highest service attach rates. Distributors are gaining share fastest as procurement consolidates toward specialized providers with analytical testing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian agricultural buyers exhibit acute price sensitivity toward natural zeolite soil amendments, while Gulf Coast petrochemical operators absorb substantial premiums for synthetic FCC catalysts with hierarchical pore architectures.
United States
EPA effluent limitation guidelines mandate tertiary ammonia removal across municipal wastewater facilities from California to the Great Lakes. Texas and Florida water authorities displace spot purchasing with multi-year performance-based service contracts. The Houston-New Orleans petrochemical corridor compresses catalyst replacement cycles as Marathon Petroleum and Valero adopt dual-pore systems for heavier crude processing.
Canada
Alberta and Saskatchewan prairie agriculture drives underpenetrated soil amendment demand where natural zeolite competes on cost against synthetic fertilizers. Health Canada and PMRA oversight shapes product registration pathways for agricultural inputs. Ontario municipal water infrastructure in the Great Lakes basin expands ion-exchange media procurement for heavy metal filtration compliance.
Mexico
Pemex refinery modernization programs in the Tula and Salina Cruz corridors elevate synthetic zeolite consumption for FCC unit upgrades. The country's national environmental regulator tightens wastewater discharge standards for petrochemical zones. Northern border states concentrate natural zeolite construction applications as cement additive demand tracks infrastructure investment.
North America Zeolite Market Key Industry Players
Integrated catalyst manufacturers and specialized natural zeolite miners split the market along a technology-versus-commodity fault line. Structure concentrates among three to five synthetic formulation leaders while fragmenting across numerous regional natural material suppliers. Dominant competitive moves include captive regeneration facility positioning near Gulf Coast demand clusters and backward integration into aluminosilicate mining operations.
Among Germany-based chemical conglomerates, BASF SE exemplifies integrated catalyst manufacturing archetypes with value-chain control over synthetic formulation. W. R. Grace & Co. and Honeywell International Inc. occupy positions within the specialized FCC technology tier, anchoring technical specification relationships with U.S. refining operators. St. Cloud Mining represents the natural zeolite extraction archetype with regional supply concentration.
| Leading Market Players |
|---|
| St. Cloud Mining |
| BASF SE |
| International Zeolite Corp. |
| W. R. Grace & Co. |
| Honeywell International Inc. |
| KMI Zeolite Inc. |
| Bear River Zeolite Co. |
| Tosoh USA, Inc. |
| Zeotech Corporation |
| Others |
Cost & Logistics Intelligence
The Houston-New Orleans petrochemical corridor concentrates synthetic zeolite manufacturing capacity, and this geographic density grants integrated producers substantial leverage over pricing in FCC catalyst contracts. Downward pressure on municipal water treatment budgets is compressing margins for ion-exchange media suppliers serving Texas and Florida authorities.
Pricing Analysis
Catalyst regeneration service contracts anchor lifetime value for synthetic zeolite producers, with multi-year performance agreements capturing recurring revenue streams from Gulf Coast refiners. Three-tier pricing structure across premium hierarchical pore architectures, standard single-pore formulations, and economy natural zeolite grades reflects technical differentiation and application intensity. Cost compression in natural zeolite agricultural tiers is intensifying because Alberta and Saskatchewan buyers evaluate synthetic fertilizer substitutes on delivered cost per ton. Municipal water authorities exhibit acute price sensitivity, while petrochemical operators absorb premiums for FCC engineering precision.
Supply Chain Analysis
BASF SE, W. R. Grace & Co., and Honeywell International Inc. hold captive manufacturing capacity across the U.S. Gulf Coast, with integrated production networks feeding directly into refinery technical service relationships. Synthetic zeolite production draws from bauxite-derived alumina and sodium silicate feedstocks, while natural zeolite extraction centers on volcanic tuff deposits in the western United States. Single-source vulnerability concentrates in specialized FCC formulation expertise clustered among Houston-area technical professionals. Distribution runs through direct sales teams for petrochemical catalysts and regional distributors for municipal water treatment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA effluent limitation guidelines are forcing municipal infrastructure upgrades at a pace that outstrips current ion-exchange media supply capacity, creating structural expansion opportunity for vendors with regeneration logistics positioned near metropolitan demand clusters.
For Market Incumbents: Insulate FCC catalyst margins by deepening backward integration into aluminosilicate mining operations and expanding captive regeneration facilities near Marathon Petroleum and Valero processing sites. Activated carbon substitution in cost-constrained water jurisdictions threatens ion-exchange specification share; defend by bundling compliance reporting into multi-year service contracts that transfer operational risk from municipal buyers. For New Entrants and Emerging Players: Build out membrane-zeolite hybrid system capabilities targeting industrial process water recycling in the Permian Basin and Appalachian shale corridors, where convergence of ion-exchange media with advanced filtration is opening specialized deployment opportunities. Canadian prairie agriculture presents the most penetrable volume tier for natural zeolite soil amendments competing against synthetic fertilizers on delivered cost. A performance-based service contract model with analytical testing capabilities displaces transactional spot purchasing among Texas and Florida water authorities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated catalyst manufacturers with value-chain control over synthetic formulation and hierarchical pore architecture engineering. The five-to-ten year viability window hinges on PFAS treatment mandate outcomes in Michigan, New York, and California that will determine whether modified zeolite or alternative adsorbents capture remediation spending. Acquisition targets should demonstrate captive regeneration infrastructure near Gulf Coast demand clusters. The signal to watch is state-level PFAS regulatory finalization timing, which will trigger step-function demand inflection for specialized ion-exchange media.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining | Captive supply of volcanic tuff secures natural zeolite cost positioning against synthetic fertilizer substitutes. |
| Capacity Expansion in Regeneration | Positioning near Houston-New Orleans refineries captures catalyst replacement cycle compression revenue. |
| Long-term Service Agreement | Multi-year performance contracts with Texas and Florida water authorities transfer operational risk and lock procurement. |
| Joint Venture for Hybrid Systems | Membrane-zeolite convergence partnerships open industrial process water recycling in shale production corridors. |
| Green Manufacturing Transition | Energy-efficient synthetic zeolite production mitigates natural gas feedstock volatility margin compression. |
Research Approach
A standing panel of FCC catalyst procurement managers at Gulf Coast refineries, municipal water treatment plant engineers, agricultural input distributors in Alberta and Saskatchewan, and zeolite mining operations managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against EPA effluent limitation guideline dockets, SEC 10-K filings from integrated chemical producers, customs trade data on aluminosilicate imports, and state-level environmental agency procurement records. Bottom-up volume estimates from end-use applications triangulated with top-down market sizing from producer capacity disclosures.
Scenario-bracketing framed projections across the analysis window, with demand trajectories modeled by product type, application intensity, end-user maturity, and regional regulatory enforcement pace. Segmentation dimensions included synthetic versus natural versus modified versus nanostructured zeolite grades; catalyst, adsorbent, ion-exchanger, and fertilizer applications; and petrochemical, water treatment, agriculture, and construction end-use sectors. CAGRs were derived from regression analysis of historical replacement cycle data and regulatory mandate implementation timelines, with inputs from refinery processing intensity trends and municipal infrastructure investment patterns.
Stress conditions across natural gas feedstock price volatility, activated carbon substitution rates in water treatment, and PFAS regulatory timeline uncertainty were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EPA guideline enforcement consistency and petrochemical corridor demand stability. Quarterly review of state-level PFAS mandate progression, refinery catalyst replacement announcements, and municipal water authority procurement contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Global FCC Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Catalase Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Global Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Hydrogenation Catalyst Market