
 Hydrotreating Catalyst Market | 2026-2036
Hydrotreating Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrotreating Catalyst Market Outlook
Asset-light leasing models for catalyst regeneration services is rewriting competitive dynamics for mid-size refiners seeking to avoid capital-intensive fresh catalyst purchases. Haldor Topsoe A/S leverages its integrated technology platform to dominate high-activity CoMo formulations for ultra-low sulfur diesel production. Albemarle Corporation anchors its position through captive control over specialty alumina supports and base metal sourcing. Johnson Matthey competes via deep R&D intensity in noble-metal promoted systems for severe hydrotreating conditions.
Hydrotreating catalysts are heterogeneous materials typically comprising cobalt-molybdenum or nickel-molybdenum sulfides dispersed on gamma-alumina carriers, engineered to operate at pressures between 30 and 130 bar and temperatures of 300 to 400 degrees Celsius for the removal of sulfur, nitrogen, and oxygen heteroatoms from petroleum fractions. NiMo formulations command premium positioning in hydrocracking pretreatment and denitrogenation duty where higher hydrogenation activity justifies elevated pricing. Fixed bed technology occupies the mature volume base across conventional refineries, while membrane reactor configurations represent an emerging architecture for intensified hydrogen management in smaller-scale processing units.
The EPA enforces Tier 3 gasoline sulfur standards at 10 parts per million, compelling US refiners to operate higher-severity hydrotreaters with accelerated catalyst replacement cycles. REACH registration requirements in Europe constrain the import and formulation of certain metal oxide precursors, elevating compliance costs for catalyst suppliers serving EU downstream clients. Stakeholders must monitor how the International Maritime Organization's sulfur regulations cascade into marine gasoil hydrotreating investments and associated catalyst procurement patterns.

Market Dynamics
Refinery operators face mounting pressure to process heavier, higher-sulfur crude slates while meeting ultra-low sulfur fuel specifications, forcing continuous catalyst replacement cycles and regenerable service models that reshape supplier-buyer power dynamics.
Growth Catalysts
- IMO 2020 Sulfur Cap:The International Maritime Organization's marine fuel sulfur regulations compel refiners to upgrade hydrotreating capacity for gasoil desulfurization, sustaining catalyst demand across coastal processing hubs.
- China Petrochemical Integration:State-owned refiners constructing deep-conversion complexes with hydrocracking pretreatment units generate concentrated procurement for high-activity NiMo formulations.
- Shale Oil Heaviness:Permian Basin crude gravity declines increase hydrotreating severity requirements for US refiners operating downstream of tight oil production.
Market Restraints
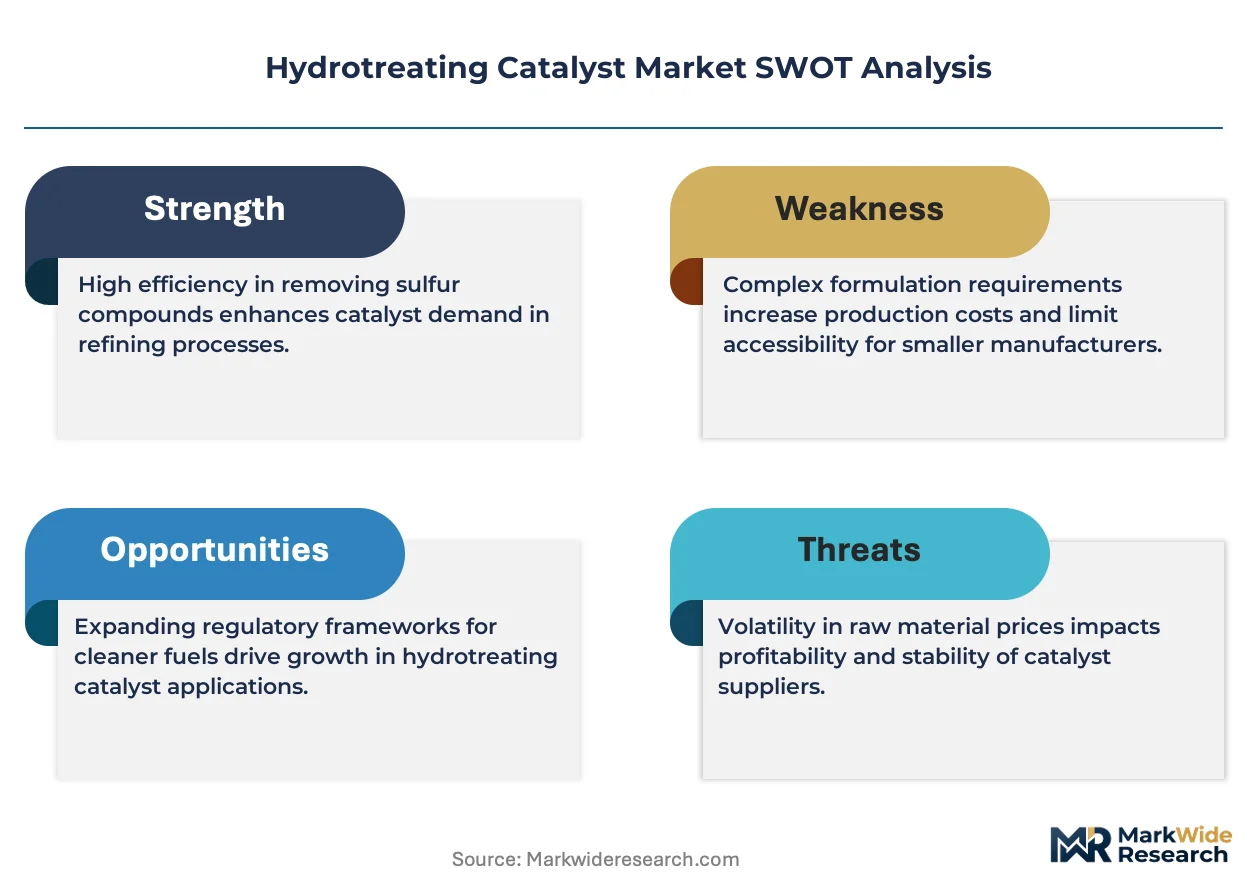
- Cobalt Supply Concentration:Democratic Republic of Congo dominance in cobalt mining creates price volatility and ethical sourcing risks for CoMo catalyst manufacturers dependent on African metal supply.
- REACH Registration Barriers:European Chemicals Agency requirements for metal oxide precursor documentation elevate compliance costs and extend formulation approval timelines for EU market entry.
- Fixed Bed Inertia:Mature reactor configurations at legacy refineries resist capital-intensive upgrades to intensified membrane architectures despite hydrogen efficiency gains.
Strategic Opportunities
- India Refinery Expansion:Reliance Industries and public sector undertakings commission coker-hydrotreater complexes to process domestic heavy crude, opening fresh catalyst demand in South Asia.
- Catalyst-as-a-Service Models:Regeneration leasing contracts allow mid-size refiners to convert capital expenditure into operational spending while securing supplier technical support.
- Biofuel Coprocessing:Renewable diesel and SAF hydrotreating requirements create dual-purpose catalyst specifications compatible with both petroleum and vegetable oil feedstocks.
Industry Challenges
- Sulfided Catalyst Handling:Pyrophoric spent catalyst unloading requires specialized contractor expertise and nitrogen inerting infrastructure that refiners struggle to staff during turnaround windows.
- Multi-Metal Formulation Complexity:Noble metal promotion for severe hydrotreating conditions demands precise impregnation protocols and quality control systems that strain technical capabilities outside integrated suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrotreating Catalyst Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CoMo, NiMo, Pd, Others Application: Desulfurization, Denitrogenation, Hydrocracking, Hydrodynamics End User: Refineries, Petrochemicals, Fuel Producers, Chemical Manufacturers Technology: Fixed Bed, Fluidized Bed, Membrane Reactor, Batch Processing |
| Companies Covered | Haldor Topsoe A/S, Axens, Albemarle Corporation, W. R. Grace & Co., Johnson Matthey, BASF SE, Honeywell UOP, Clariant AG, Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrotreating Catalyst Market Strategic Shifts
Digital process control and modular reactor architectures are compressing catalyst development cycles while enabling distributed hydrogen management across smaller processing footprints.
Catalyst support engineering is hybridizing mesoporous alumina structures with hierarchical pore architectures to improve diffusion of bulky sulfur molecules in heavy gasoil service. Refiners operating coker-fed hydrotreaters adopt these materials to extend cycle length between regenerations. The technology is hybridizing traditional fixed bed economics with extended-run reliability premiums that reshape procurement evaluation criteria.
EPA Tier 3 gasoline sulfur standards at 10 parts per million enforce final-stage hydrotreater operation at maximum severity, accelerating catalyst deactivation and replacement frequency. US refiners respond by negotiating multi-year supply agreements with technical service bundles to secure turnaround scheduling priority. The regulation most impacts FCC naphtha post-treatment units where sulfur removal competes with octane preservation.
Leased regeneration services displace spot catalyst purchases among independent refiners lacking in-house technical staff for spent material management. Third-party processors with dedicated presulfiding and rejuvenation capabilities capture recurring revenue streams previously retained by fresh catalyst suppliers. The shift concentrates most visibly among US Gulf Coast merchant refiners optimizing working capital during margin compression cycles.
Hydrotreating Catalyst Market Segmentation

Hydrotreating catalyst procurement patterns diverge sharply by duty cycle and severity. Replacement frequency, regeneration economics, and feedstock complexity create distinct commercial profiles across each segment category.
Product Type:
Cycle times compress most dramatically for high-activity formulations in severe service, while base metal workhorses turn over predictably across conventional units.
- CoMo:Cobalt-molybdenum sulfides on gamma-alumina carriers dominate diesel hydrotreating for sulfur removal at moderate hydrogenation severity. Demand concentrates in Middle Eastern refineries expanding capacity to process heavier crude slates under IMO marine fuel regulations. The formulation offers the most favorable balance of activity and cobalt sourcing cost for merchant refiners.
- NiMo:Nickel-molybdenum systems deliver superior hydrogenation activity for hydrocracking pretreatment and denitrogenation where nitrogen removal competes with sulfur elimination. Chinese state-owned refiners building integrated petrochemical complexes generate concentrated procurement for these premium formulations. Higher nickel content justifies elevated pricing through extended cycle lengths in severe duty.
- Pd:Palladium-promoted catalysts serve specialized applications requiring noble metal hydrogenation selectivity.
- Others:Emerging formulations including mixed metal oxides and zeolite-based systems address niche biofuel coprocessing requirements.
CoMo anchors the volume base while NiMo gains share at the steepest rate.
Application:
Margin structures align with regulatory enforcement intensity rather than feedstock throughput alone.
- Desulfurization:Sulfur removal from gasoil and naphtha fractions consumes the majority of catalyst volume across coastal refining hubs. EPA Tier 3 gasoline standards at 10 parts per million force US refiners into maximum-severity operation with accelerated replacement cycles. The application captures recurring revenue through regenerable service contracts.
- Denitrogenation:Nitrogen heteroatom removal protects downstream cracking catalysts and improves product stability for premium fuel blending. Coker-fed hydrotreaters at US Gulf Coast refineries drive demand for hierarchical pore architectures that accommodate bulky nitrogen compounds. Cycle lengths extend when diffusion limitations are engineered out of support structures.
- Hydrocracking:Pretreatment duty for hydrocracker feedstocks demands the highest activity NiMo formulations to protect zeolite cracking catalysts from nitrogen and metal poisoning.
- Hydrodynamics:Hydrogen management and saturation reactions in specialty chemical feedstocks occupy a smaller volume niche.
Desulfurization commands the installed base while denitrogenation expands most quickly as coker integration deepens.
End User:
Capital intensity and technical staffing levels determine procurement modality across buyer categories.
- Refineries:Integrated refining complexes with in-house technical teams favor multi-year supply agreements bundling fresh catalyst, regeneration services, and turnaround scheduling priority. US merchant refiners lacking nitrogen inerting infrastructure increasingly adopt leased regeneration to convert capital expenditure into operational spending.
- Petrochemicals:Steam cracker feedstock pretreatment units require consistent catalyst quality to protect ethylene furnace run lengths. The segment shows rising interest in dual-purpose specifications compatible with both petroleum and renewable feedstocks.
- Fuel Producers:Standalone diesel and marine gasoil blenders operate smaller hydrotreating units with spot purchasing patterns.
- Chemical Manufacturers:Specialty chemical producers running batch or semi-continuous hydrotreaters generate fragmented demand with specification-driven procurement.
Refineries anchor the volume base while petrochemicals gain share at the steepest rate.
Technology:
Reactor architecture selection locks in catalyst morphology and regeneration logistics for decades.
- Fixed Bed:Conventional downflow packed bed configurations occupy the mature installed base across legacy refineries with predictable pressure drop and temperature profiles. Mature reactor geometries resist capital-intensive upgrades despite hydrogen efficiency gains available from intensified alternatives. The technology sustains steady catalyst demand through routine replacement cycles.
- Fluidized Bed:Ebullated or slurry-phase systems enable continuous catalyst addition and withdrawal for extremely heavy feedstocks. The configuration supports online catalyst replacement without unit shutdown, compressing effective cycle time and increasing total catalyst throughput.
- Membrane Reactor:Emerging architectures integrate hydrogen-selective membranes for distributed hydrogen management in smaller processing footprints.
- Batch Processing:Discontinuous operation serves specialty chemical and pilot-scale applications with irregular catalyst consumption patterns.
Fixed bed anchors the volume base while membrane reactor configurations gain share at the steepest rate.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States outstrips that in India by a factor reflecting technical service bundling and regulatory compliance intensity. Chinese state procurement concentrates volume leverage unmatched elsewhere. Middle Eastern capacity expansion creates spot demand surges that distort regional contract structures.
United States
EPA Tier 3 gasoline standards at 10 parts per million force maximum-severity hydrotreater operation with accelerated catalyst replacement cycles. The regulation most impacts FCC naphtha post-treatment units where sulfur removal competes with octane preservation. US Gulf Coast merchant refiners increasingly adopt leased regeneration services to convert capital expenditure into operational spending during margin compression cycles.
China
State-owned refiners constructing deep-conversion complexes with hydrocracking pretreatment units generate concentrated procurement for high-activity NiMo formulations. The country's dual carbon goals pressure operators to improve hydrogen efficiency through catalyst performance rather than energy-intensive process modifications. Integrated petrochemical complexes in the Yangtze River Delta and Pearl River Delta anchor the steepest demand growth globally.
Germany
REACH registration requirements for metal oxide precursor documentation elevate compliance costs and extend formulation approval timelines for EU market entry. The European Chemicals Agency constrains import and formulation of certain precursors, reshaping supplier access patterns. The Rhine-Ruhr refining cluster operates hydrotreaters under combined pressure from marine fuel sulfur regulations and domestic renewable fuel blending mandates.
Saudi Arabia
Refinery expansion to process heavier crude slates under IMO marine fuel regulations sustains CoMo catalyst demand across coastal processing hubs. The Kingdom's downstream integration strategy builds coker-hydrotreater complexes requiring hierarchical pore architectures for heavy gasoil service. The Jubail industrial city concentrates new capacity additions with procurement patterns favoring multi-year technical service agreements.
India
Reliance Industries and public sector undertakings commission coker-hydrotreater complexes to process domestic heavy crude, opening fresh catalyst demand in South Asia. The Petroleum and Natural Gas Regulatory Board enforces fuel quality specifications that compress replacement cycles at older refineries. The Jamnagar refining complex and Mumbai-Pune industrial corridor anchor procurement concentration for high-activity formulations.
Hydrotreating Catalyst Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply chain, creating a tiered structure where technology bundling determines contract capture. The vendor base concentrates around integrated suppliers with captive alumina support production and base metal sourcing control. Three archetypes dominate: integrated technology platforms, specialty chemical conglomerates with materials science divisions, and regional catalyst fabricators serving spot markets. Competitive moves center on regeneration service leasing contracts and multi-year supply agreements bundling technical support with turnaround scheduling priority.
Among integrated technology platforms, Haldor Topsoe A/S and Honeywell UOP exemplify the system-tier archetype through their process licensing and catalyst supply integration. Albemarle Corporation represents the materials-anchored specialist with captive control over specialty alumina supports. Johnson Matthey occupies a position within the noble-metal promoted segment for severe hydrotreating conditions. BASF SE and Clariant AG exemplify diversified chemical conglomerates competing through scale and formulation breadth rather than vertical integration depth.
| Leading Market Players |
|---|
| Haldor Topsoe A/S |
| Axens |
| Albemarle Corporation |
| W. R. Grace & Co. |
| Johnson Matthey |
| BASF SE |
| Honeywell UOP |
| Clariant AG |
| Shell |
| Others |
Value Chain & Pricing Dynamics
Jubail Industrial City's concentrated coker-hydrotreater buildouts concentrate CoMo procurement leverage among Saudi Aramco-led complexes, compressing spot pricing power for merchant refiners lacking multi-year technical service agreements. This geographic supply clustering feeds downstream into tiered contract structures where captive alumina support production anchors premium positioning.
Pricing Analysis
Configured-to-order pricing for hierarchical pore NiMo formulations commands spreads against standard gamma-alumina CoMo workhorses. Contract-based long-term offtake dominates, with price differentiation resting on cobalt sourcing security and regeneration service bundling. Cost compression in base metal tiers is intensifying because Democratic Republic of Congo supply volatility forces hedging premiums. Independent US Gulf Coast refiners show highest price sensitivity; integrated Middle Eastern complexes show least.
Supply Chain Analysis
Export-control regimes on advanced membrane reactor technologies limit flows from Germany and Japan to Chinese state-owned refiners, constraining intensified hydrogen management adoption. Geographic supply concentrates in China, the United States, and Germany for specialty alumina supports; cobalt feedstock draws from the Democratic Republic of Congo and Zambia. Single-source vulnerability in African metal supply creates structural risk. Distribution runs through integrated technology licensors bundling catalyst with process licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as biofuel coprocessing requirements splinter catalyst specifications away from unified petroleum standards, creating specification niches for specialized formulators.
For Market Incumbents: Build captive regeneration infrastructure moats by acquiring third-party presulfiding facilities in the US Gulf Coast and Rotterdam clusters. Consolidate position through backward integration into specialty alumina support production to offset REACH documentation burdens. Threat from membrane reactor intensification demands R&D priority in distributed hydrogen management architectures.
For New Entrants and Emerging Players: India's Jamnagar-Mumbai corridor offers underpenetrated white-space as Reliance and public sector undertakings commission coker-hydrotreater complexes without established catalyst supply relationships. Target leased regeneration services for mid-size refiners lacking nitrogen inerting infrastructure. Go-to-market angle: technical service bundling with turnaround scheduling priority.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because sulfur caps and renewable fuel mandates create non-discretionary replacement demand impervious to crude price cycles. Acquisition target archetype: regional catalyst fabricators with captive base metal sourcing and ECHA registration portfolios. Signal to watch: IMO marine fuel enforcement intensity at coastal blending hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alumina | Captive support production insulates margin pressure from REACH precursor documentation costs. |
| Regeneration Service Leasing Contracts | Asset-light models convert capital expenditure to operational spending for US merchant refiners. |
| Dual-Purpose Biofuel Coprocessing Formulations | Compatibility with both petroleum and vegetable oil feedstocks captures renewable diesel demand. |
| Membrane Reactor Technology Licensing | Hydrogen-selective architectures enable distributed processing for smaller-scale renewable fuel units. |
| Multi-Year Technical Service Agreements | Turnaround scheduling priority secures recurring revenue across Middle Eastern capacity expansions. |
Study Parameters
Initial hypotheses were tested against primary input from refinery operations managers, catalyst procurement leads, and technical service directors and refined through secondary validation. Stakeholder interviews combined with customs trade data, SEC filings from diversified chemical conglomerates, ECHA registration databases, and refinery capacity expansion trackers. Bottom-up catalyst consumption estimates triangulated against top-down refinery throughput projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application severity, end-user capital intensity, and reactor technology architecture. CAGRs derived from regression against historical replacement cycle frequencies and regulatory enforcement timelines. Forecast inputs incorporated IMO marine fuel sulfur compliance schedules and Chinese petrochemical integration project pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese catalyst producers would shift outcomes through concentrated procurement leverage. Material shifts in cobalt supply chain stability or REACH precursor classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
North America Refining Catalysts Market
Catalysts
Catalyst Regeneration Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Photocatalyst Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Environmental Catalysts Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Global Zeolites Market
Catalysts
Aluminum-Nickel Catalyst Market
Catalysts
Secondary Reforming Catalyst Market