
 Rhodium Carbon Catalyst Market | 2026-2036
Rhodium Carbon Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Rhodium Carbon Catalyst Market Analysis
Palladium is pivoting toward partial substitution by rhodium in selective hydrogenation systems where tighter chemoselectivity reduces downstream purification costs. Johnson Matthey leverages its precious metals refining infrastructure to secure feedstock continuity across catalyst production cycles. BASF SE anchors its position through proprietary carbon-support functionalization that extends catalyst lifetime in continuous-flow reactors. Evonik Industries AG competes via specialized high-surface-area carbon carriers tailored for fine-chemical hydrogenation.
Rhodium carbon catalyst denotes metallic rhodium nanoparticles dispersed on activated carbon substrates, typically loaded at 1–10 wt% and reduced under hydrogen atmosphere to achieve active metallic surface areas of 40–120 m²/g; the composite serves primarily to catalyze olefin reduction, carbonyl hydrogenation, and nitro-group conversion in batch and continuous pharmaceutical and petrochemical processes. Catalyst powder formulations dominate current volume due to faster dispersion kinetics in slurry-phase reactors, while catalyst pellets capture margin pools in fixed-bed petrochemical units where pressure-drop management governs operating economics. Heterogeneous catalysts lead formulation demand because carbon-supported rhodium permits straightforward filtration recovery, though homogeneous variants retain niche positions in asymmetric synthesis where ligand-controlled selectivity justifies separation complexity.
EMA pharmaceutical manufacturing guidelines and REACH substance registration requirements in Europe enforce residual metal leaching thresholds that directly shape catalyst validation protocols and supplier qualification timelines. EPA hazardous waste rules in the United States impose spent catalyst recovery obligations that incentivize closed-loop refining partnerships between end users and precious metals recyclers. Stakeholders must monitor evolving hydrogen economy subsidy frameworks and carbon-border adjustment mechanisms to align catalyst sourcing decisions with shifting clean-production compliance boundaries.
Market Dynamics
Hydrogenation demand from pharmaceutical intermediates is compressing catalyst qualification timelines while REACH compliance in the European Union tightens purity thresholds for imported batches, forcing suppliers to revalidate carbon-support functionalization protocols.
Growth Catalysts
- Pharmaceutical intermediate hydrogenation:Olefin reduction and carbonyl hydrogenation in batch reactors drives replacement cycles for spent catalyst loads.
- REACH substance registration:ECHA enforcement of residual metal leaching thresholds validates closed-loop refining partnerships between end users and precious metals recyclers.
- Coal-to-chemicals expansion:China's domestic hydrogen fuel cell programs concentrate demand for high-surface-area carbon carriers in continuous-flow applications.
Market Restraints
- Rhodium price volatility:Precious metals feedstock costs fluctuate with South African mining output disruptions and London Bullion Market Association pricing.
- Carbon-support supply concentration:Specialized activated carbon substrates for pharmaceutical-grade catalysts depend on limited Southeast Asian coconut-shell processing capacity.
- Homogeneous catalyst substitution:Ligand-controlled asymmetric synthesis retains niche positions where filtration recovery complexity is acceptable.
Strategic Opportunities
- Continuous-flow reactor adoption:BASF SE's proprietary carbon-support functionalization extends catalyst lifetime in petrochemical fixed-bed units.
- EPA hazardous waste rule incentives:Closed-loop spent catalyst recovery obligations create service revenue pools for precious metals refiners.
- Hydrogen economy subsidy frameworks:Evolving carbon-border adjustment mechanisms align catalyst sourcing with clean-production compliance boundaries.
Industry Challenges
- Metallic surface area calibration:Achieving 40–120 m²/g active metallic surface requires precise hydrogen atmosphere reduction protocols.
- EMA validation timelines:Pharmaceutical manufacturing guidelines extend supplier qualification periods for residual metal leaching documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhodium Carbon Catalyst Market |
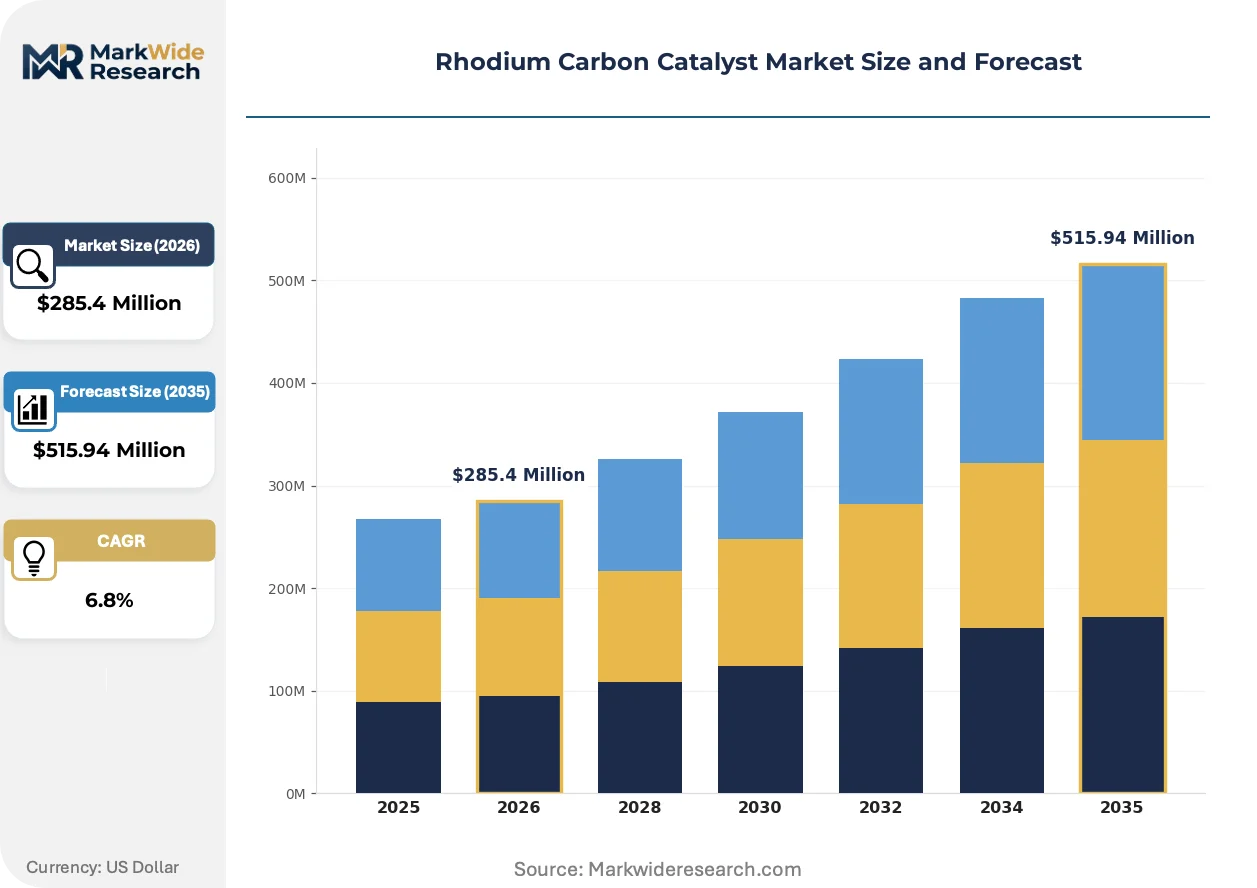
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catalyst Powder, Catalyst Granules, Catalyst Pellets, Catalyst Sheets Application: Petrochemical Processing, Chemical Synthesis, Fuel Cells, Environmental Remediation End User: Chemical Manufacturers, Oil Refineries, Automotive Industry, Research Laboratories Formulation: Supported Catalysts, Homogeneous Catalysts, Heterogeneous Catalysts, Others |
| Companies Covered | Johnson Matthey, BASF SE, Evonik Industries AG, Heraeus Holding, Umicore, Strem Chemicals, Shanxi Kaida Chemical Engineering, Gelest, Stanford Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhodium Carbon Catalyst Market Emerging Trajectories
Carbon-support engineering and regulatory compliance protocols are compressing catalyst development cycles while reshaping procurement relationships between pharmaceutical manufacturers and precious metals refiners.
Atomic layer deposition of rhodium nanoparticles onto functionalized carbon substrates is integrating precise loading control at 1–10 wt% with enhanced dispersion kinetics. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these engineered carriers for slurry-phase hydrogenation. This precision loading is integrating downstream purification cost reductions by tightening chemoselectivity in nitro-group conversion processes.
EMA pharmaceutical manufacturing guidelines now mandate residual metal leaching thresholds that directly shape catalyst validation protocols. European Union enforcement of these thresholds extends supplier qualification timelines for imported batches. Fine-chemical hydrogenation operations in Basel and Ludwigshafen are responding by consolidating supplier bases to pre-qualified precious metals refiners with captive carbon-support production.
Buyer consolidation among pharmaceutical intermediates manufacturers is compressing catalyst procurement cycles from annual tenders to quarterly spot arrangements with pre-approved suppliers. Distributor networks in the Rhineland and New Jersey are losing volume to direct refiner relationships. This channel disintermediation is most visible in high-volume olefin reduction contracts where filtration recovery economics dominate total cost of ownership calculations.
Rhodium Carbon Catalyst Market Segmentation
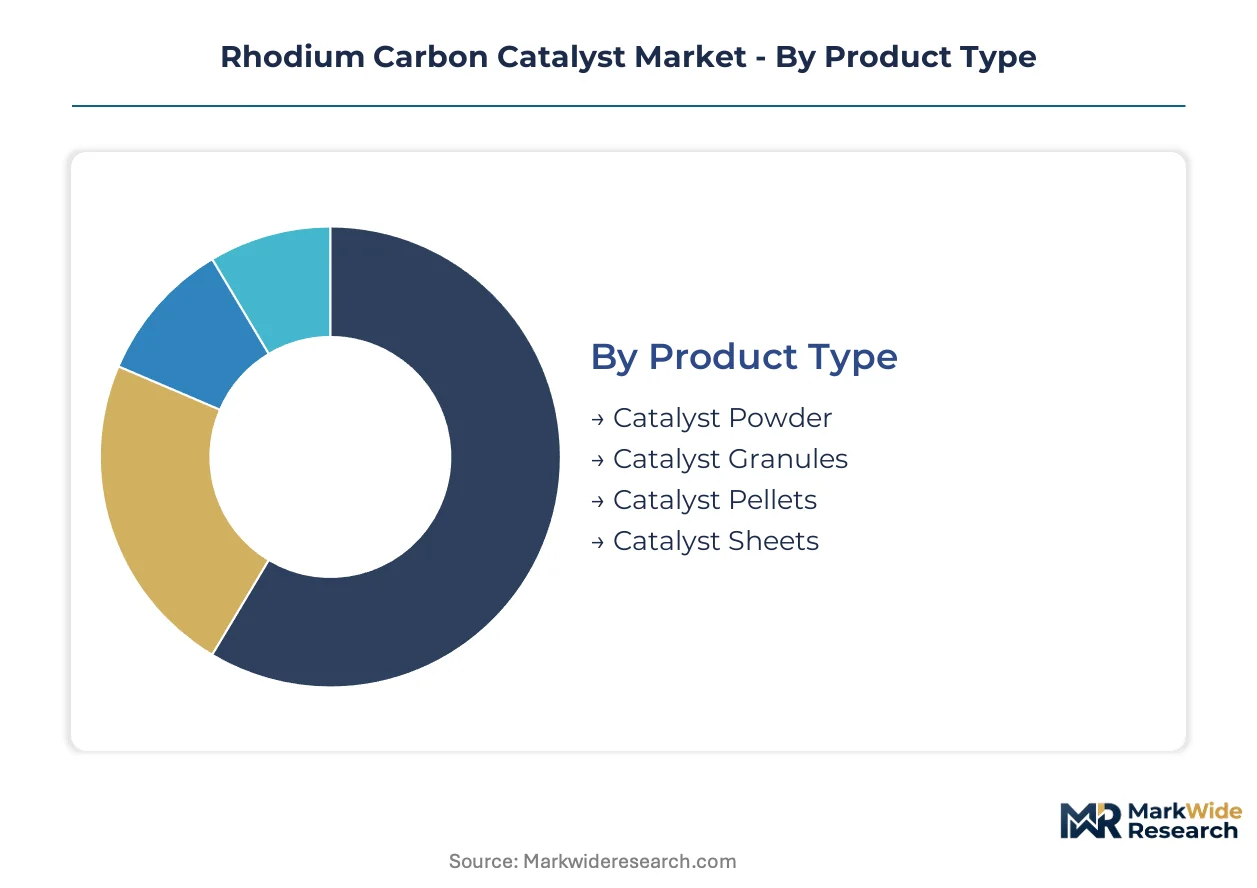
Segmentation in rhodium carbon catalysts reveals divergent technical requirements across hydrogenation intensities, regulatory exposure, and recovery economics. Buyers select formulations based on filtration feasibility, metal leaching thresholds, and reactor configuration constraints.
Product Type:
Cost tier separates batch pharmaceutical processors from continuous petrochemical operators.
- Catalyst Powder:Fine particulate dispersions at 1–10 wt% rhodium loading enable rapid mass transfer in slurry-phase reactors. Demand concentrates in Swiss and German pharmaceutical contract manufacturers running nitro-group reduction under EMA residual metal leaching guidelines.
- Catalyst Granules:Intermediate particle sizing balances dispersion kinetics with pressure-drop management in mixed-phase systems. Oil refineries in the US Gulf Coast deploy these for olefin hydrogenation under EPA hazardous waste recovery obligations.
- Catalyst Pellets:Engineered extrudates for fixed-bed configurations where pressure-drop economics govern operating costs.
- Catalyst Sheets:Thin-film substrates for specialized electrochemical applications in fuel cell membrane electrode assemblies.
Volume sits with Catalyst Powder; growth tilts toward Catalyst Pellets.
Application:
Volume concentration tracks hydrogen economy subsidy intensity and carbon-border exposure.
- Petrochemical Processing:Fixed-bed hydrogenation of olefin streams in coal-to-chemicals complexes. China's domestic hydrogen fuel cell programs concentrate demand for high-surface-area carbon carriers in continuous-flow units.
- Chemical Synthesis:Batch carbonyl hydrogenation for pharmaceutical intermediates. Basel and Ludwigshafen fine-chemical operations consolidate supplier bases to pre-qualified refiners with captive carbon-support production.
- Fuel Cells:Membrane electrode assembly fabrication for proton-exchange systems.
- Environmental Remediation:Catalytic reduction of chlorinated contaminants in groundwater treatment.
Revenue concentrates in Petrochemical Processing; Chemical Synthesis climbs the fastest.
End User:
Procurement sophistication divides closed-loop refiners from spot-market buyers.
- Chemical Manufacturers:Fine-chemical and pharmaceutical intermediates producers with validated refining partnerships. REACH compliance tightens purity thresholds for imported batches, extending supplier qualification timelines.
- Oil Refineries:Hydrotreating and hydrocracking operators with integrated precious metals recovery infrastructure.
- Automotive Industry:Fuel cell stack assemblers sourcing membrane electrode components.
- Research Laboratories:Small-volume purchasers for asymmetric synthesis and catalyst screening protocols.
Volume concentrates with Chemical Manufacturers; expansion tilts toward Oil Refineries.
Formulation:
Recovery complexity determines preference between filtration-amenable and ligand-controlled systems.
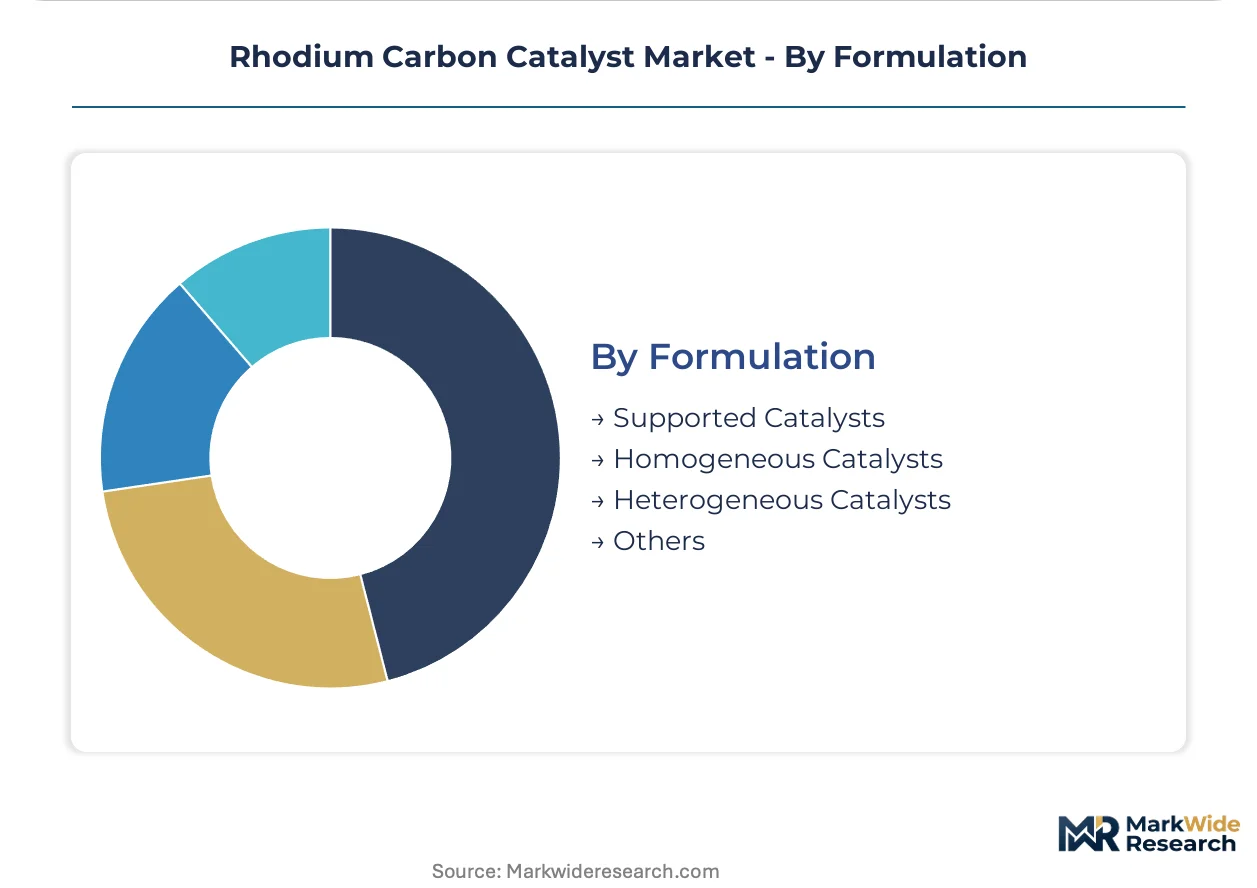
- Heterogeneous Catalysts:Carbon-supported rhodium nanoparticles permitting straightforward filtration recovery. These dominate pharmaceutical manufacturing where EMA guidelines enforce residual metal leaching documentation.
- Supported Catalysts:Engineered carriers with functionalized surface chemistry for extended lifetime in continuous reactors.
- Homogeneous Catalysts:Ligand-controlled systems retaining niche positions in asymmetric synthesis where selectivity justifies separation complexity.
- Others:Emerging formulations including ionic-liquid phases and encapsulated catalyst systems.
Volume sits with Heterogeneous Catalysts; growth tilts toward Supported Catalysts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates demand for rhodium carbon catalysts through coal-to-chemicals expansion and hydrogen fuel cell programs, while European pharmaceutical clusters enforce REACH-driven purity thresholds that reshape supplier qualification timelines.
China
Coal-to-chemicals complexes in Ningxia and Inner Mongolia drive fixed-bed hydrogenation demand for olefin reduction. MEE enforcement of dual carbon goals tightens emissions standards for catalyst manufacturing facilities. The Yangtze River Delta cluster around Shanghai concentrates domestic production of high-surface-area carbon carriers for continuous-flow petrochemical units.
Germany
Fine-chemical hydrogenation in Ludwigshafen and Leverkusen compresses catalyst procurement cycles under ECHA residual metal leaching thresholds. REACH substance registration requirements extend validation timelines for imported carbon-support batches. The BASF SE integrated site anchors captive refining partnerships that close-loop spent catalyst recovery.
United States
Gulf Coast oil refineries deploy rhodium catalysts for hydrotreating under EPA hazardous waste recovery obligations. FDA pharmaceutical manufacturing guidelines enforce residual metal documentation for contract manufacturers in New Jersey and Puerto Rico. The Houston Ship Channel cluster concentrates demand for catalyst granules in mixed-phase hydrogenation systems.
Switzerland
Basel pharmaceutical contract manufacturers consolidate supplier bases to pre-qualified precious metals refiners. Swissmedic guidelines align with EMA validation protocols for residual metal leaching in nitro-group conversion processes. The Basel-Ludwigshafen corridor represents the densest European concentration of batch hydrogenation capacity.
India
API intermediate producers in Hyderabad and Ahmedabad accelerate catalyst replacement cycles for olefin reduction. CDSCO pharmaceutical manufacturing regulations tighten documentation requirements for imported catalyst batches. The Gujarat chemical belt expands continuous-flow reactor adoption for carbonyl hydrogenation under PLI scheme incentives.
Rhodium Carbon Catalyst Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated precious metals refiners commanding premium positioning in pharmaceutical-grade supply chains. The vendor base concentrates around three strategic archetypes: captive refiners with backward integration into carbon-support production, specialized high-surface-area carrier fabricators, and regional toll manufacturers serving spot-market demand. Consolidation pressure intensifies through closed-loop refining partnerships and direct refiner relationships that disintermediate traditional distributor networks.
Among UK-based precious metals specialists, Johnson Matthey occupies a position exemplifying captive refining infrastructure integrated across catalyst production cycles. BASF SE anchors the German chemical conglomerate archetype with proprietary carbon-support functionalization capabilities. Evonik Industries AG represents the specialized carrier fabricator tier with high-surface-area carbon engineering for fine-chemical applications.
| Leading Market Players |
|---|
| Johnson Matthey |
| BASF SE |
| Evonik Industries AG |
| Heraeus Holding |
| Umicore |
| Strem Chemicals |
| Shanxi Kaida Chemical Engineering |
| Gelest |
| Stanford Advanced Materials |
| Others |
Supply Flow & Price Mechanics
Specialized precious metals refining expertise concentrated in South Africa and the United Kingdom feeds directly into tiered pricing spreads between pharmaceutical-grade and industrial-grade rhodium carbon catalysts, with labor-cost differentials in carbon-support fabrication widening the gap between premium and economy formulations.
Pricing Analysis
Volume concentrates in catalyst powder for slurry-phase pharmaceutical hydrogenation, while margin pools sit with engineered catalyst pellets for fixed-bed petrochemical units. Price differentiation hinges on EMA residual metal leaching certification tiers and captive carbon-support production capabilities. Pricing pressure stems from South African mining output disruptions transmitting volatility through London Bullion Market Association benchmarks. Spot-market buyers in India's API belt exhibit highest price sensitivity, whereas Swiss and German contract manufacturers with closed-loop refining partnerships absorb premium tiers.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian coconut-shell activated carbon processing, which pharmaceutical-grade catalyst fabrication draws from. Raw material dependencies center on South African rhodium sponge, German high-surface-area carbon engineering, and Chinese coal-to-chemicals complex offtake. Tariff exposure on precious metals imports into the European Union and United States compounds structural concentration risk. Distribution runs through direct refiner relationships disintermediating traditional distributor networks in the Rhineland and New Jersey.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rhodium carbon catalyst market sits in a technology-transition phase, with atomic layer deposition precision loading displacing conventional impregnation methods for pharmaceutical hydrogenation applications.
For Market Incumbents:Acquire captive carbon-support production assets to secure high-surface-area carrier supply against Southeast Asian processing bottlenecks. Deepen backward integration into precious metals refining infrastructure to buffer London Bullion Market Association price volatility. Lock long-term offtake agreements with China's coal-to-chemicals complexes before hydrogen economy subsidy frameworks reshape demand geography.
For New Entrants and Emerging Players:Capture membrane electrode assembly fabrication for proton-exchange fuel cell systems, where automotive industry qualification timelines remain shorter than pharmaceutical EMA validation protocols. Penetrate India's Gujarat chemical belt continuous-flow reactor installations, where PLI scheme incentives accelerate capital deployment. Lead with toll-manufacturing partnerships offering atomic layer deposition loading precision without captive precious metals inventory.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized high-surface-area carbon carrier fabricators given REACH compliance tightening purity thresholds for imported batches. Long-term viability over the next decade hinges on hydrogen economy subsidy durability and carbon-border adjustment mechanism evolution. Watch MEE enforcement of dual carbon goals in China's Yangtze River Delta cluster as inflection signal for domestic production capacity rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Support Production | Captive supply of pharmaceutical-grade activated carbon insulates against Southeast Asian coconut-shell processing bottlenecks. |
| Atomic Layer Deposition Capacity Expansion | Precision rhodium nanoparticle loading at 1–10 wt% tightens chemoselectivity for nitro-group conversion in Basel operations. |
| Closed-Loop Refining Partnership Formation | Direct end-user relationships with Johnson Matthey or Umicore disintermediate distributor networks and secure metal recovery economics. |
| Continuous-Flow Reactor Qualification | BASF SE proprietary carbon-support functionalization extends catalyst lifetime in coal-to-chemicals fixed-bed units. |
| Fuel Cell Membrane Electrode Assembly Certification | Proton-exchange system qualification opens automotive industry procurement channels outside pharmaceutical EMA timelines. |
Methodological Framework
Trade databases, ECHA substance registration filings, and SEC 10-K disclosures from precious metals refiners formed the secondary backbone, cross-referenced against primary interviews with pharmaceutical contract manufacturing executives, petrochemical plant managers, and carbon-support procurement leads. Bottom-up catalyst volume estimates triangulated against top-down hydrogenation process demand modeling across the analysis window.
Historical trendline analysis of rhodium loading intensity per pharmaceutical batch and fixed-bed petrochemical unit underpinned projection frameworks, with segmentation across product type, application, end user, and formulation dimensions. CAGRs derived from regression against coal-to-chemicals capacity expansion in China and REACH compliance timeline compression in Europe, incorporating London Bullion Market Association price volatility bands and coconut-shell carbon supply elasticity assumptions.
The model holds under sustained hydrogen economy subsidy frameworks and stable South African mining output; deviation in carbon-border adjustment mechanism implementation or MEE dual carbon enforcement stringency would shift regional demand concentration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Steam Methane Reforming Market
Catalysts
Polymer Catalyst Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Organic Catalyst Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Refinery Catalyst Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Industrial Catalyst Market
Catalysts
North America Refining Catalysts Market
Catalysts
Polyolefin Catalyst Market