
 Molecular Sieve for Air Separation Market | 2026-2036
Molecular Sieve for Air Separation Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Sieve for Air Separation Market Insights
Advanced lithium-based zeolite formulations are reshaping oxygen yield rates in pressure swing adsorption systems. Honeywell UOP leverages its integrated catalyst-manufacturing infrastructure to sustain cost advantages in high-purity nitrogen applications. BASF SE anchors European supply through specialized 13X zeolite production for cryogenic pre-purification units. Tosoh Corporation differentiates via tight control over Japanese domestic medical oxygen specifications.
Molecular sieve for air separation comprises synthetic crystalline aluminosilicates engineered with precise pore apertures, typically 3Å to 10Å, that selectively adsorb molecules based on kinetic diameter and polarity to fractionate air into oxygen, nitrogen, and argon streams. Zeolite molecular sieves dominate oxygen generation applications where lithium-exchanged variants achieve nitrogen selectivity ratios exceeding 6.0, while activated alumina pre-layers protect downstream beds from moisture-induced degradation in air drying systems. Pressure swing adsorption technology leads unit deployment across industrial end users due to lower capital intensity versus cryogenic distillation, though vacuum swing adsorption gains traction in medical settings requiring portable oxygen concentrators. Membrane separation occupies a narrowing niche for low-purity nitrogen blanket gas where energy costs outweigh selectivity requirements.
EPA New Source Performance Standards and OSHA workplace oxygen concentration mandates in the United States compel industrial gas producers to certify adsorbent performance under variable humidity loads. REACH registration requirements in Europe restrict certain binder chemistries in zeolite manufacturing, elevating compliance costs for imported formulations. China's GB standards on industrial gas purity, enforced by SAMR, create localized certification barriers that favor domestic producers like Shanghai Hengye. Stakeholders must weigh regional regulatory divergence against centralized manufacturing scale when siting new molecular sieve production capacity.
Market Dynamics
Pressure swing adsorption technology maturation is compressing oxygen production costs below cryogenic thresholds, redirecting industrial gas procurement toward modular zeolite-based systems that bypass centralized air separation unit infrastructure.
Growth Catalysts
- EPA New Source Performance Standards:Tighter emissions mandates in the United States compel industrial gas producers to certify adsorbent performance under variable humidity loads, accelerating replacement cycles for legacy molecular sieve beds.
- Medical oxygen concentrators:Portable VSA systems for home healthcare are pulling lithium-exchanged zeolite demand as post-acute care shifts toward decentralized oxygen delivery models.
- China's industrial gas investments:Domestic manufacturing scale and SAMR-enforced GB standards on industrial gas purity are pulling volume eastward, favoring localized molecular sieve production capacity.
Market Restraints
- Lithium supply concentration:Battery sector competition for lithium carbonate elevates input cost volatility for Li-LSX zeolite formulations, squeezing margin structures for oxygen-grade sieve producers.
- Cryogenic pre-purification lock-in:Existing 13X zeolite installations at major air separation units create technical switching costs that slow PSA adoption in high-volume nitrogen applications.
- REACH registration friction:ECHA restrictions on certain binder chemistries elevate compliance costs for imported formulations entering European cryogenic pre-purification supply chains.
Strategic Opportunities
- India's healthcare infrastructure:PLI scheme incentives for medical device manufacturing create white space for domestic oxygen concentrator assembly, pulling localized zeolite formulation demand.
- Dual carbon goals in China:MEE enforcement of industrial energy efficiency standards creates regulatory tailwinds for PSA retrofits that displace energy-intensive cryogenic distillation at steel and chemical complexes.
- Membrane-PSA hybrid systems:Convergence of polymeric membrane pre-separation with zeolite polishing stages enables modular nitrogen units for electronics blanketing applications with sub-10 ppm oxygen specifications.
Industry Challenges
- Crystallization process control:Tight particle size distribution requirements for Li-LSX zeolites demand specialized hydrothermal synthesis expertise that concentrates among a limited supplier base.
- Multi-regional certification timelines:Simultaneous EPA, REACH, and SAMR compliance testing extends product qualification cycles by 18-24 months for molecular sieve formulations targeting cross-border industrial gas markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Sieve for Air Separation Market |
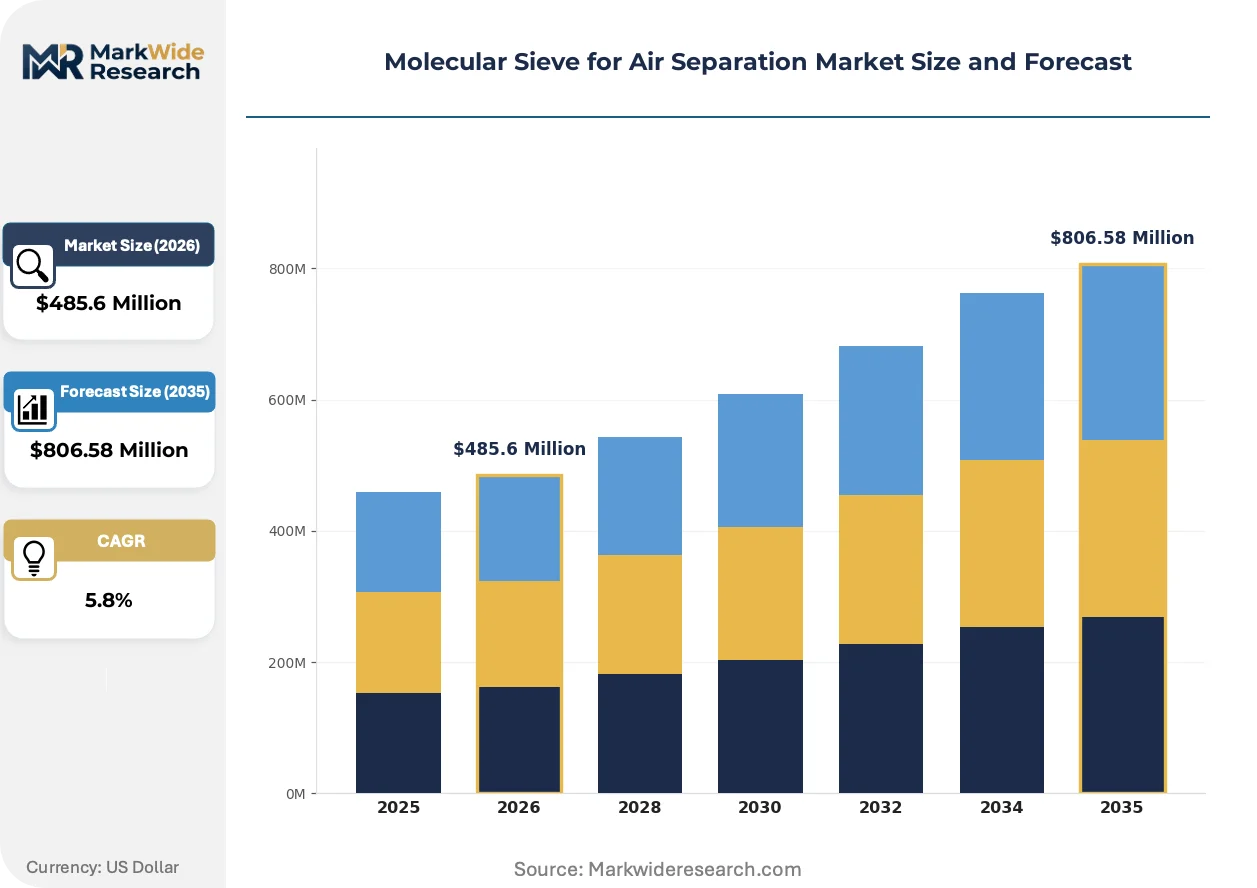
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $806.58 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolite, Activated Alumina, Silica Gel, Calcium Carbonate Application: Oxygen Generation, Nitrogen Purification, Air Drying, Gas Separation End User: Industrial, Medical, Environmental, Chemical Processing Technology: Pressure Swing Adsorption, Vacuum Swing Adsorption, Cryogenic Distillation, Membrane Separation |
| Companies Covered | Honeywell UOP, BASF SE, Arkema, Zeochem AG, Tosoh Corporation, W. R. Grace & Co., Clariant Produkte (Schweiz AG), Shanghai Hengye, Pingxiang Xintao, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Sieve for Air Separation Market Trends and Innovations
Zeolite engineering advances are compressing the performance gap between pressure swing and vacuum swing systems, while regulatory pressure on industrial emissions intensifies scrutiny of adsorbent lifecycle efficiency.
Advanced lithium-exchanged low-silica X zeolites are achieving nitrogen-to-oxygen selectivity ratios above 6.0 in medical-grade PSA systems. Home healthcare providers and portable concentrator manufacturers are adopting these formulations at accelerating pace as device miniaturization demands higher specific productivity. This materials progression is digitizing oxygen yield optimization algorithms that previously required manual bed configuration tuning.
EU F-Gas Regulation phase-down schedules are tightening restrictions on fluorinated greenhouse gases used in cryogenic air separation refrigerant loops. Industrial gas producers in Germany and France are responding by redirecting capital toward PSA nitrogen systems that eliminate refrigeration dependency entirely. Cryogenic pre-purification units face accelerated obsolescence risk in sub-1000 Nm³/h applications where zeolite-based alternatives now deliver comparable purity.
Long-term service contracting is displacing spot procurement for molecular sieve replacement cycles at major industrial gas facilities. Air separation plant operators in the United States are unbundling adsorbent supply from OEM maintenance agreements, creating direct purchasing relationships with zeolite formulators. This channel disintermediation is most visible in the Gulf Coast petrochemical corridor where integrated producers seek inventory control over critical spare beds.
Molecular Sieve for Air Separation Market Segmentation
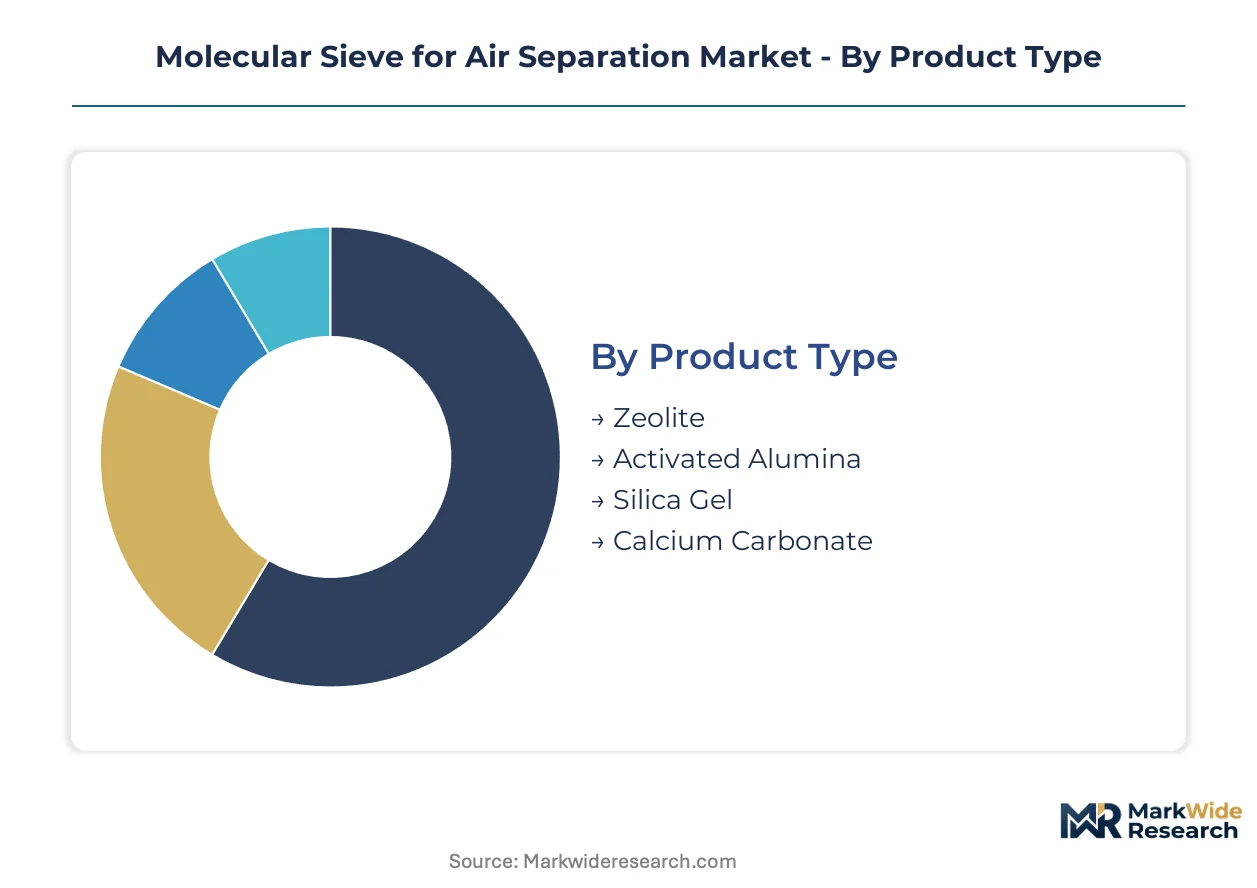
Segmentation in molecular sieve markets tracks the divergence between commodity-grade desiccants and high-performance lithium-exchanged zeolites. Each dimension—product chemistry, separation application, end-use sector, and process technology—carries distinct margin structures and certification requirements that reshape procurement patterns.
Product Type:
Cost tier differentiation separates premium lithium-exchanged formulations from commodity aluminosilicates in this category.
- Zeolite:Synthetic crystalline aluminosilicates with precisely engineered pore apertures between 3Å and 10Å dominate oxygen generation. Lithium-exchanged low-silica X variants achieve nitrogen-to-oxygen selectivity ratios exceeding 6.0, concentrating demand in medical PSA systems where Honeywell UOP and BASF SE compete on yield optimization algorithms.
- Activated Alumina:Porous aluminum oxide spheres serve as protective pre-layers in air drying systems, adsorbing moisture before it degrades downstream zeolite beds. Demand clusters in Gulf Coast petrochemical corridors where humidity loads stress PSA unit longevity, with procurement shifting toward unbundled direct purchasing from formulators.
- Silica Gel:Amorphous silicon dioxide adsorbents handle lower-specification drying applications where kinetic diameter selectivity requirements relax.
- Calcium Carbonate:Cost-driven filler applications occupy narrow niches in non-critical gas conditioning systems.
Zeolite holds installed capacity. Activated Alumina is rotating up the share rankings as pre-layer protection gains recognition in humid climates.
Application:
Application segmentation isolates purity thresholds and flow rate requirements that dictate adsorbent formulation selection.
- Oxygen Generation:Medical-grade PSA systems demand lithium-exchanged zeolites with sub-ppm nitrogen breakthrough characteristics. Portable concentrator manufacturers are adopting these formulations as post-acute care shifts toward decentralized oxygen delivery models, with India's PLI scheme for medical device manufacturing creating localized demand pull.
- Nitrogen Purification:Industrial blanketing applications require 13X zeolite formulations capable of achieving sub-10 ppm oxygen specifications in electronics manufacturing. EU F-Gas Regulation phase-down schedules are redirecting capital from cryogenic systems toward PSA alternatives in Germany and France.
- Air Drying:Moisture removal upstream of cryogenic distillation units protects heat exchanger integrity.
- Gas Separation:Argon recovery and rare gas purification occupy specialized niches with extended qualification cycles.
Oxygen Generation captures the steepest expansion trajectory as healthcare infrastructure modernizes. Nitrogen Purification maintains the largest installed base in industrial gas facilities.
End User:
Customer type segmentation reveals divergent procurement behaviors between centralized industrial gas producers and fragmented medical device assemblers.
- Industrial:Steel mills, chemical complexes, and petrochemical refineries operate large-scale air separation units with 10-15 year adsorbent replacement cycles. China's MEE enforcement of industrial energy efficiency standards is accelerating PSA retrofits that displace energy-intensive cryogenic distillation.
- Medical:Home healthcare providers and hospital systems source portable oxygen concentrators with miniaturized zeolite beds. SAMR-enforced GB standards on industrial gas purity in China create localized certification barriers that favor domestic producers like Shanghai Hengye.
- Environmental:Emissions control and carbon capture applications are emerging with specialized selectivity requirements.
- Chemical Processing:Specialty gas production and catalyst protection use standardized 4A and 13X formulations.
Industrial dominates current procurement volume. Medical is climbing fastest as portable concentrator penetration deepens.
Technology:
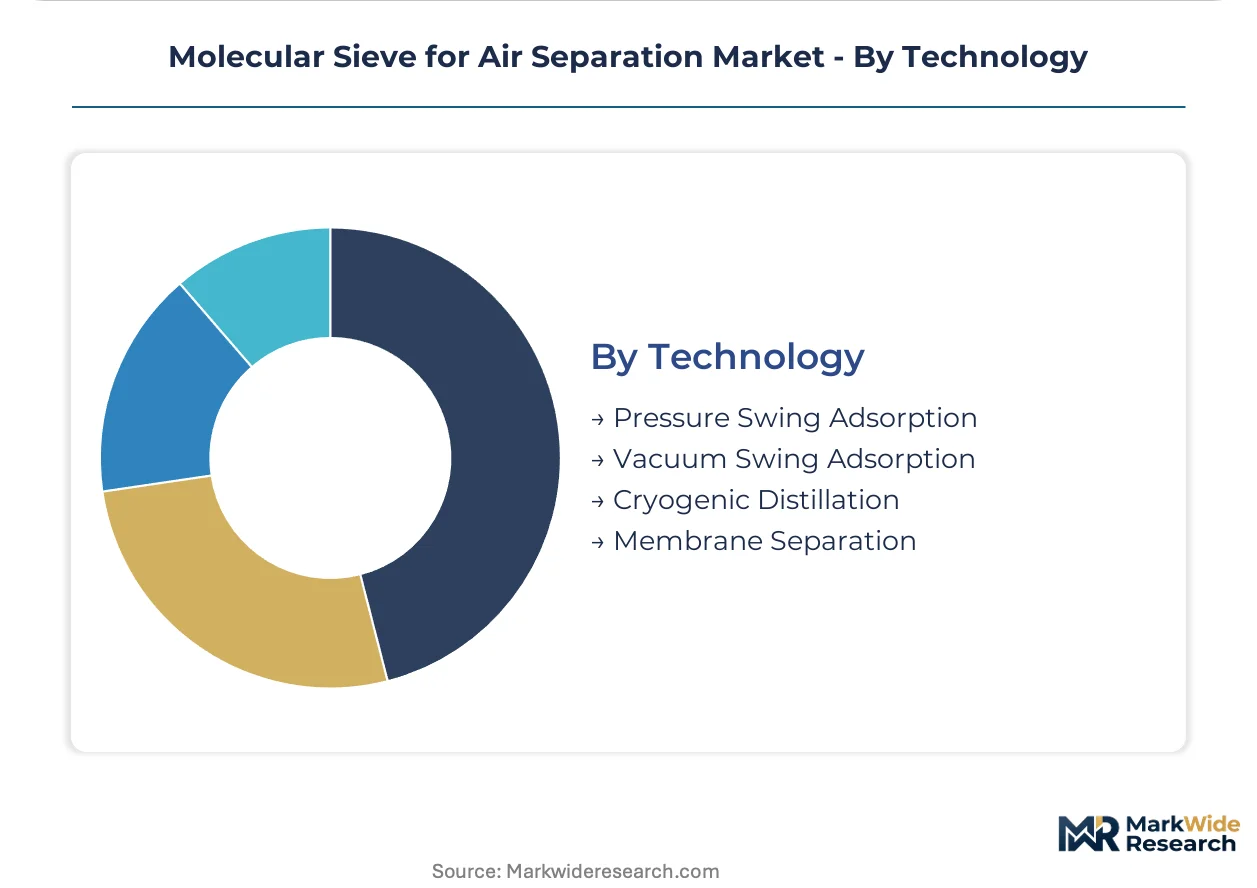
Process technology segmentation tracks the competitive displacement of energy-intensive separation methods by modular adsorbent systems.
- Pressure Swing Adsorption:Cyclic pressurization-depressurization of zeolite beds fractionates air without refrigeration dependency. PSA maturation is compressing oxygen production costs below cryogenic thresholds, redirecting procurement toward modular systems that bypass centralized air separation unit infrastructure in United States Gulf Coast facilities.
- Vacuum Swing Adsorption:Sub-atmospheric desorption enables smaller bed volumes for portable medical devices. VSA gains traction in home healthcare settings where device miniaturization demands higher specific productivity from lithium-exchanged formulations.
- Cryogenic Distillation:Legacy high-volume nitrogen production faces accelerated obsolescence risk in sub-1000 Nm³/h applications.
- Membrane Separation:Polymeric systems occupy narrowing niches for low-purity nitrogen blanket gas where energy costs outweigh selectivity requirements.
Cryogenic Distillation retains legacy capacity in mega-scale facilities. Pressure Swing Adsorption is rotating up the share rankings as modular deployment spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial gas producers and medical device assemblers concentrate procurement in four distinct national markets, each shaped by divergent regulatory enforcement and infrastructure investment cycles.
United States
Gulf Coast petrochemical complexes and Midwest steel mills drive replacement demand for PSA zeolite beds. EPA New Source Performance Standards compel certified adsorbent performance under variable humidity loads. Houston and Corpus Christi host unbundled direct purchasing relationships where plant operators bypass OEM maintenance agreements.
China
Domestic manufacturing scale and steel sector modernization pull volume toward localized molecular sieve capacity. SAMR-enforced GB standards on industrial gas purity create certification barriers favoring Shanghai Hengye and other domestic producers. Yangtze River Delta industrial clusters accelerate PSA retrofits displacing energy-intensive cryogenic distillation.
Germany
EU F-Gas Regulation phase-down schedules redirect capital from cryogenic nitrogen systems toward PSA alternatives. ECHA REACH restrictions on binder chemistries elevate compliance costs for imported formulations. Ruhr industrial corridor facilities face accelerated obsolescence risk in sub-1000 Nm³/h applications.
India
PLI scheme incentives for medical device manufacturing create white space for domestic oxygen concentrator assembly. CDSCO medical device regulations intersect with BIS industrial standards to shape zeolite formulation requirements. Maharashtra and Gujarat medical device clusters pull localized demand for lithium-exchanged zeolites.
Molecular Sieve for Air Separation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated catalyst manufacturers hold cost advantages in high-purity nitrogen applications. The vendor base separates into three strategic archetypes: diversified chemical conglomerates with integrated manufacturing infrastructure, specialized zeolite formulators with tight crystallization process control, and regional producers leveraging domestic certification barriers. Competitive moves concentrate on capacity expansion in lithium-exchanged formulations and strategic partnerships for multi-regional certification compliance.
Among diversified chemical conglomerates, Honeywell UOP and BASF SE exemplify archetypes with integrated catalyst-manufacturing infrastructure sustaining cost advantages. Tosoh Corporation occupies a position within the specialized formulator tier, anchoring Japanese domestic medical oxygen specifications. Shanghai Hengye represents the regional producer archetype, leveraging SAMR-enforced GB standards to capture localized demand in China's industrial gas investments.
| Leading Market Players |
|---|
| Honeywell UOP |
| BASF SE |
| Arkema |
| Zeochem AG |
| Tosoh Corporation |
| W. R. Grace & Co. |
| Clariant Produkte (Schweiz AG) |
| Shanghai Hengye |
| Pingxiang Xintao |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in lithium-exchanged zeolite production across China and Japan is compressing supplier margins while elevating pricing power for crystallization-process specialists serving medical-grade PSA specifications.
Pricing Analysis
Cost-plus contracts indexed to lithium carbonate spot benchmarks dominate procurement for oxygen-grade zeolite formulations. Three-tier pricing structure across medical-certified, industrial-standard, and commodity desiccant levels separates lithium-LSX premiums from activated alumina pre-layers. Pricing pressure stems from battery-sector competition for lithium carbonate feedstock. Medical device assemblers exhibit highest price sensitivity due to concentrator miniaturization demands, while industrial gas producers absorb premiums for EPA-certified humidity performance.
Supply Chain Analysis
Contract manufacturing concentrates among Honeywell UOP's integrated catalyst facilities, BASF SE's Ludwigshafen complex, and Tosoh Corporation's specialized Japanese lines. China, Germany, and the United States anchor global molecular sieve production capacity. Raw material dependencies center on lithium carbonate from South American brine operations, kaolin clay from Georgia and Ukraine deposits, and sodium silicate from regional chemical producers. Single-source vulnerability in lithium supply creates structural risk. Distribution runs through direct purchasing relationships with industrial gas operators and OEM maintenance channels for medical device assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks cyclical recovery patterns tied to steel sector capital expenditure cycles, with China's MEE enforcement accelerating PSA retrofit demand at idled blast furnaces.
For Market Incumbents: Pre-empt margin erosion in commodity 13X zeolites by deepening backward integration into lithium carbonate offtake agreements with Chilean and Argentine producers. Defend medical-grade positioning through SAMR certification investment ahead of China's healthcare infrastructure expansion. Cryogenic pre-purification lock-in at major air separation units represents the primary substitution threat requiring active displacement campaigns. For New Entrants and Emerging Players: Build out regional formulation capacity in India to capture PLI scheme pull for domestic oxygen concentrator assembly. Maharashtra and Gujarat medical device clusters offer the most penetrable white space. CDSCO regulatory alignment with BIS industrial standards creates a certification-fast-follow go-to-market angle against established multinational suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane-PSA hybrid system manufacturing as modular nitrogen unit demand scales. Long-term viability favors acquisition targets with crystallization-process IP and multi-regional EPA-REACH-SAMR certification portfolios. Watch lithium carbonate price volatility as the primary inflection signal for oxygen-grade zeolite margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Supply | Secures carbonate offtake against battery sector competition for Li-LSX production. |
| Multi-Regional Certification Investment | Compresses EPA-REACH-SAMR qualification timelines for cross-border industrial gas markets. |
| Membrane-PSA Hybrid System Development | Captures electronics blanketing applications with sub-10 ppm oxygen specifications. |
| Regional Capacity Expansion in India | Aligns with PLI scheme incentives for domestic medical device manufacturing clusters. |
| Long-Term Service Contracting | Displaces spot procurement with direct purchasing relationships at Gulf Coast petrochemical facilities. |
Research Methodology
Cross-validation between primary interviews with zeolite plant managers, industrial gas procurement leads, and medical device R&D directors and secondary sources including SAMR GB standards filings, EPA New Source Performance Standards documentation, and ECHA REACH registration databases anchors the qualitative findings. Customs data from China and Germany, SEC 10-K disclosures from diversified chemical conglomerates, and industrial gas trade association reports provide volume triangulation. Bottom-up capacity modeling and top-down end-use demand estimation converge on segment-level outputs.
Calibration against historical PSA unit deployment rates and cryogenic distillation retrofit patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include product chemistry tier, separation application purity threshold, end-user procurement behavior, and process technology deployment scale. CAGRs derive from fitted growth curves against lithium supply elasticity and regulatory enforcement intensity. Forecast inputs incorporate MEE energy efficiency standard compliance timelines and EU F-Gas Regulation phase-down schedules.
Stress conditions across lithium carbonate price bands, SAMR certification timeline extensions, and cryogenic-to-PSA substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding industrial gas infrastructure investment cycles and healthcare decentralization trends. Quarterly review of lithium spot price movements, EPA enforcement actions, and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Cooling Tower Chemicals Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Wire Compound and Cable Compound Market