
 Asia-Pacific Refining Catalysts Market | 2026-2036
Asia-Pacific Refining Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Refining Catalysts Market Outlook
Chinese catalyst producers is broadening output of FCC and hydrotreating systems to serve domestic mega-refinery expansions along the Bohai Rim and Yangtze Delta. Albemarle Corporation anchors its Asia-Pacific position through integrated rare earth supply chains and regional manufacturing scale. BASF SE leverages proprietary zeolite platforms to compete in hydrocracking applications across Indian and Southeast Asian markets. Sinopec dominates captive demand through backward integration into catalyst production for its own refining network.
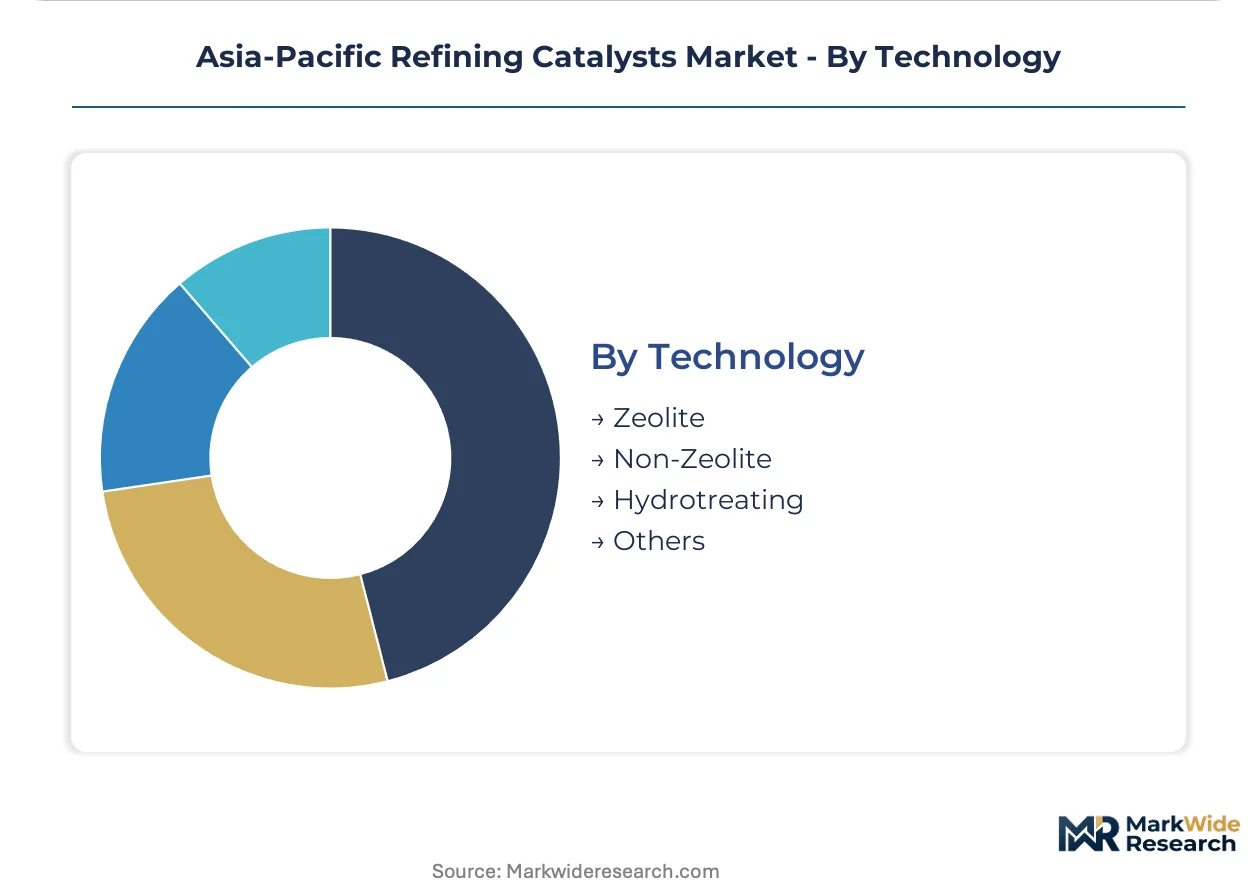
Refining catalysts are heterogeneous substances—typically comprising crystalline zeolites, alumina supports, and active metal phases such as nickel, molybdenum, or cobalt—that accelerate petroleum conversion reactions under high temperature and pressure conditions. These materials enable fluid catalytic cracking, hydrocracking, and catalytic reforming processes that transform heavy hydrocarbon feedstocks into gasoline, diesel, and petrochemical precursors. FCC catalysts occupy the largest volume share across the region as refiners maximize light olefin and gasoline yields from heavier crudes, while hydrocracking catalysts command premium pricing due to their critical role in middle distillate production and sulfur removal. Zeolite-based technologies lead the technology dimension given their tunable acidity and pore structures that deliver superior selectivity and longer cycle lengths.
China's Ministry of Ecology and Environment enforces National VI fuel standards that mandate ultra-low sulfur content, directly stimulating demand for advanced hydrotreating catalysts. India's BIS and Petroleum and Natural Gas Regulatory Board implement Bharat Stage VI norms that compel refinery upgrades, creating procurement windows for imported high-performance systems. The analysis shows stakeholders must monitor regulatory tightening timelines and catalyst regeneration economics to optimize capital deployment across the region's fragmented refinery base.
Market Dynamics
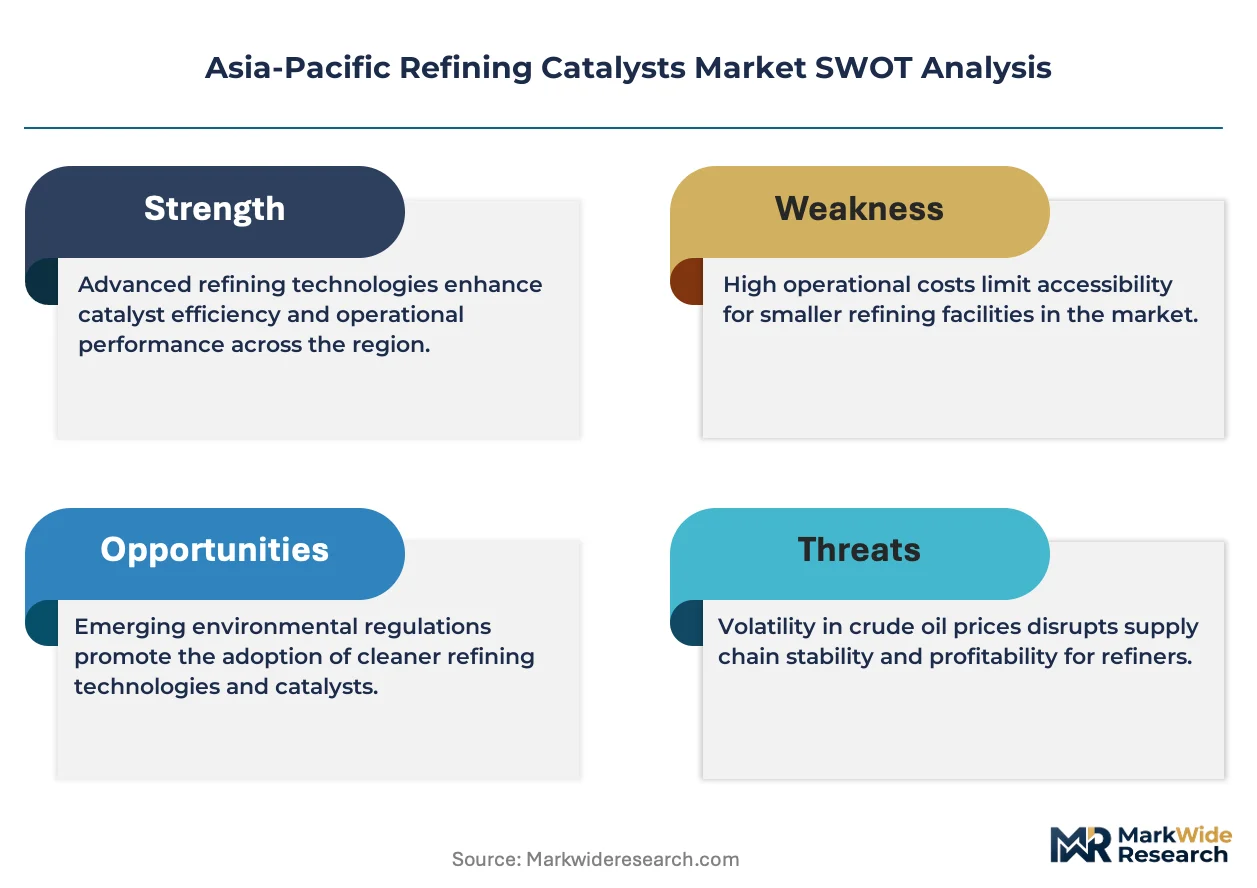
Refinery feedstock heavification across Asia-Pacific is compressing catalyst cycle lengths and forcing accelerated regeneration schedules, fundamentally altering procurement economics for hydrocracking and hydrotreating systems.
Growth Catalysts
- National VI fuel standards:China's MEE mandates for ultra-low sulfur diesel and gasoline are compelling coastal refiners to upgrade hydrotreating catalyst loadings at Bohai Rim facilities.
- Middle distillate deficit:Southeast Asian import dependence on diesel and jet fuel is driving hydrocracker capacity additions in Thailand, Vietnam, and Indonesia.
- Zeolite acidity tuning:Advances in hierarchical pore architecture are extending FCC catalyst stability when processing high-metal opportunity crudes.
Market Restraints
- Rare earth supply concentration:Lanthanum and cerium sourcing dependence on Chinese separation capacity creates price volatility for FCC catalyst formulations.
- Catalyst regeneration cost inflation:Rising natural gas and hydrogen prices in South Korea and Japan are eroding the economics of ex-situ regeneration versus fresh catalyst purchase.
- Refinery margin compression:Complex crude differentials have narrowed, limiting capital availability for discretionary catalyst upgrades at independent Indian processors.
Strategic Opportunities
- Vietnam's Nghi Son and Long Son complexes:Greenfield refinery startups lacking captive catalyst supply chains represent open procurement contests for hydrotreating and reforming systems.
- Bio-feedstock co-processing:FCC unit retrofits for vegetable oil and waste lipid injection are creating demand for modified zeolite matrices with controlled basic site density.
- India's BS-VI Stage II preparation:Anticipated particulate number limits for gasoline will require next-generation reforming catalysts with enhanced aromatics management.
Industry Challenges
- Catalyst handling specialist scarcity:Safe unloading and screening of spent hydroprocessing catalysts requires certified technicians in short supply across Indonesian and Philippine maintenance markets.
- Legacy FCC unit metallurgy constraints:Older Chinese and Indian riser reactors cannot accommodate the higher regeneration temperatures demanded by modern low-coke zeolite formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Refining Catalysts Market |
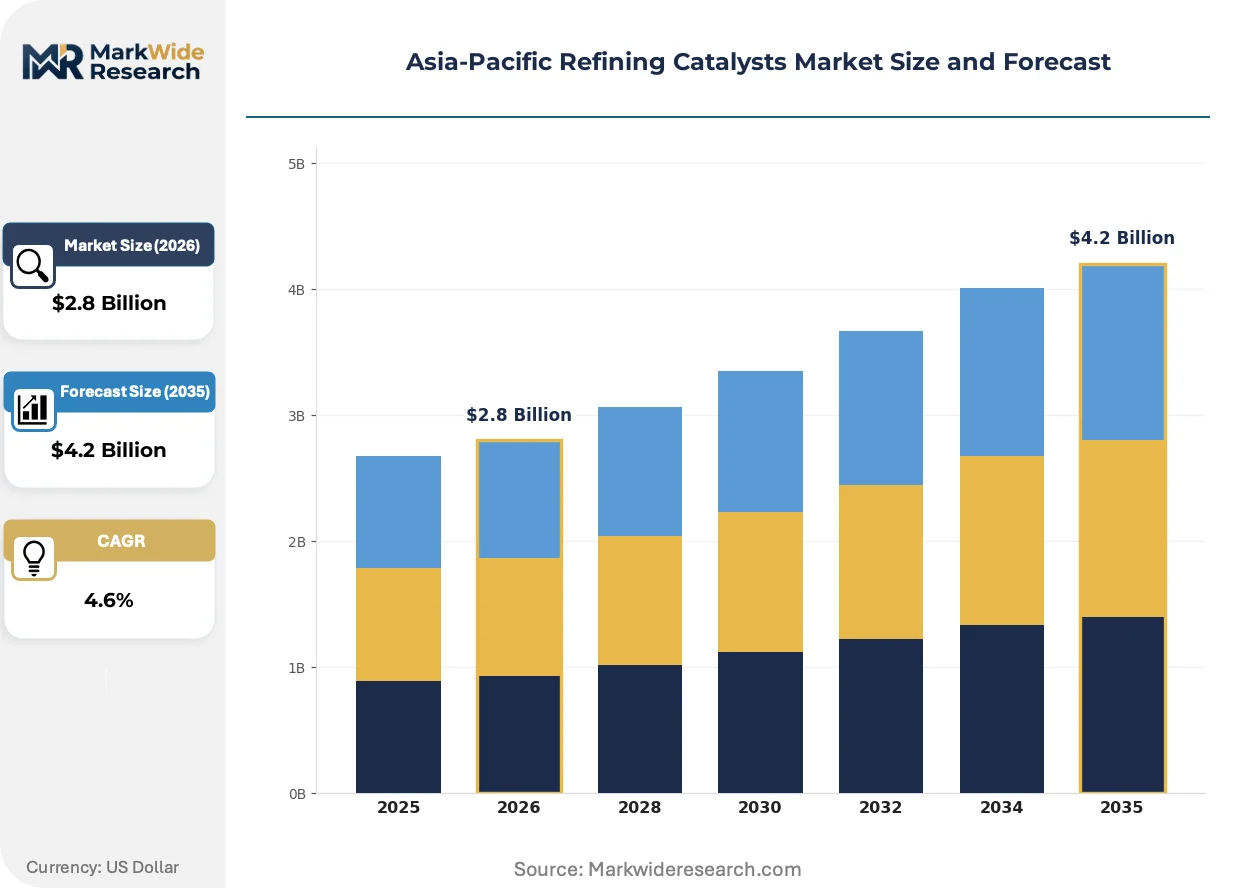
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FCC Catalysts, Hydrocracking Catalysts, Reforming Catalysts, Others Application: Gasoline Production, Diesel Production, Jet Fuel Production, Lubricant Production End User: Refineries, Petrochemical Plants, Biofuels Producers, Chemical Manufacturers Technology: Zeolite, Non-Zeolite, Hydrotreating, Others |
| Companies Covered | Haldor Topsoe A/S, Axens, BASF SE, TAIYO KOKO Co., Ltd., Johnson Matthey, Albemarle Corporation, Sinopec, UNICAT Catalyst Technologies, LLC, W. R. Grace & Co.-Conn., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Refining Catalysts Market Strategic Shifts
Zeolite platform convergence with additive manufacturing and digital performance monitoring is collapsing the traditional separation between catalyst formulation and reactor engineering services.
Metal-modified hierarchical zeolites are unifying acid-catalyzed cracking with selective hydrogenation functions in single-particle architectures. Indian refiners processing high-iron Bombay High crudes are piloting these systems to suppress dry gas make. The technology is unifying what were separate FCC and mild hydrocracking process trains into hybrid reaction schemes.
China's dual carbon goals are tightening MEE scrutiny of refinery energy intensity and catalyst manufacturing emissions. Carbon footprint disclosure requirements are propagating through Sinopec's supplier qualification protocols. Catalyst producers with verified low-carbon rare earth supply chains are securing preferential placement on refinery tender shortlists.
Aftermarket service unbundling is fragmenting what were integrated catalyst supply contracts. Japanese and South Korean refiners are separately sourcing performance guarantees, technical service, and spent catalyst reclamation. This behavior is most pronounced at coastal complexes with established logistics for offshore regeneration.
Asia-Pacific Refining Catalysts Market Segmentation
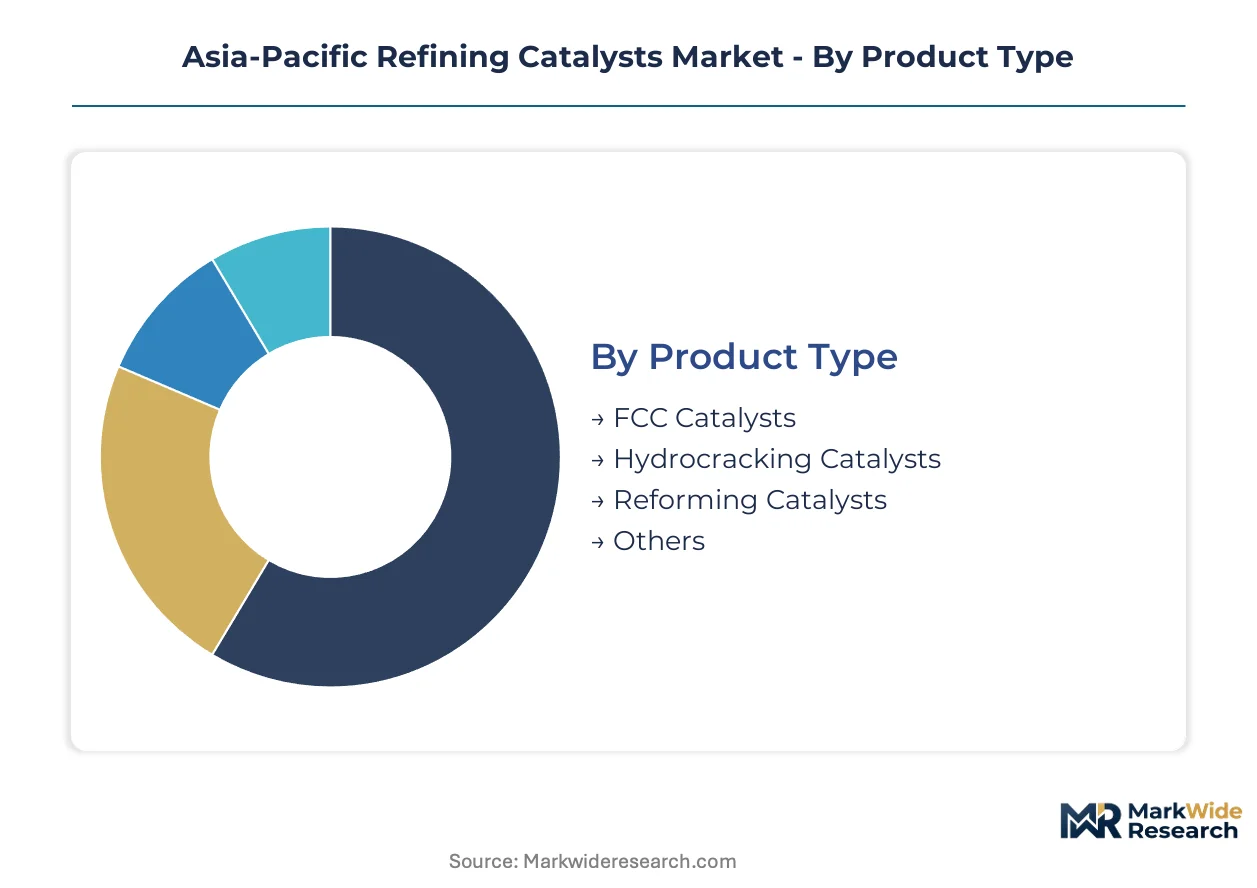
Refining catalyst procurement in Asia-Pacific splits across multiple technical and commercial dimensions. Buyers weigh catalyst activity against regeneration economics, while regulatory pressure on fuel quality creates divergent demand patterns across product categories.
Product Type:
Refinery upgrade decisions hinge on feedstock slate heavification and target product yield structures.
- FCC Catalysts:Crystalline zeolite matrices with rare earth stabilization dominate volume. Coastal Chinese refiners at Dalian and Ningbo maximize light olefin yields from high-metal opportunity crudes. MEE scrutiny on refinery emissions intensifies procurement scrutiny of catalyst coke selectivity.
- Hydrocracking Catalysts:Bifunctional systems combining acidic zeolite supports with sulfided Ni-Mo active phases command premium positioning. Thailand's Sriracha complex and Vietnam's Nghi Son facility drive demand for middle distillate maximization. India's diesel deficit sustains elevated loadings at Reliance Jamnagar.
- Reforming Catalysts:Chlorided alumina platforms with platinum-rhenium promotion enable high-octane gasoline and aromatics production.
- Others:Hydrotreating guard materials and isomerization catalysts fill specialty niches in sulfur removal and paraffin upgrading.
Volume sits with FCC Catalysts; growth tilts toward Hydrocracking Catalysts.
Application:
Product slate optimization determines catalyst selection across downstream process trains.
- Gasoline Production:FCC and reforming catalysts dominate this application. China's National VI standards mandate benzene and aromatics limits that reshape reforming catalyst specifications. Indian refiners at Mathura and Panipat balance octane enhancement against particulate precursor formation.
- Diesel Production:Hydrocracking and hydrotreating systems enable ultra-low sulfur compliance. Indonesia's Pertamina Balikpapan and Vietnam's Dung Quat complexes prioritize cetane improvement alongside sulfur removal.
- Jet Fuel Production:Hydrocracking severity tuning ensures smoke point and freezing point specifications for aviation kerosene.
- Lubricant Production:Hydroisomerization and dewaxing catalysts convert vacuum gas oil into Group II/III base stocks.
Procurement concentrates in Gasoline Production; Diesel Production expands most quickly on middle distillate deficit dynamics.
End User:
Facility scale and integration depth create distinct technical service requirements.
- Refineries:Integrated and independent processors represent the core demand base. Sinopec's captive catalyst production covers internal requirements, while Indian private refiners rely on imported high-performance systems. South Korean complexes at Yeosu and Ulsan emphasize regeneration service bundling.
- Petrochemical Plants:FCC propylene maximization and aromatics extraction create catalyst demand at steam cracker interfaces.
- Biofuels Producers:Co-processing trials at Neste Singapore and Malaysian palm oil refiners pilot modified zeolite matrices for renewable diesel.
- Chemical Manufacturers:Methanol-to-olefins and specialty chemical synthesis utilize adapted refining catalyst platforms.
Revenue gravity centers on Refineries; Petrochemical Plants gain share fastest on integration trends.
Technology:
Intellectual property positioning and manufacturing scale determine competitive access.
- Zeolite:Hierarchical pore architectures with tunable acidity dominate FCC and hydrocracking applications. BASF's proprietary platforms and Sinopec's in-house capabilities compete on rare earth efficiency and metal tolerance. Dalian and Zibo production clusters anchor Chinese supply.
- Non-Zeolite:Amorphous silica-alumina and alumina-supported systems serve hydrotreating and guard bed functions.
- Hydrotreating:Ni-Mo and Co-Mo sulfided phases on alumina supports enable sulfur, nitrogen, and oxygen removal.
- Others:Molecular sieve and mixed metal oxide systems address specialty separation and conversion requirements.
Installed base favors Zeolite; Hydrotreating climbs fastest on sulfur regulation stringency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth separation capacity concentrated in China's Inner Mongolia and Jiangxi provinces anchors regional catalyst supply chains. Coastal refining clusters from Dalian to Singapore drive procurement intensity for hydrocracking and FCC systems.
China
Mega-refinery expansions along the Bohai Rim and Yangtze Delta sustain elevated catalyst loadings for heavy crude processing. MEE enforcement of National VI fuel standards compels coastal refiners at Ningbo and Dalian to upgrade hydrotreating catalyst specifications. Sinopec's backward integration into captive catalyst production dominates internal demand while specialized suppliers serve independent processors.
India
Reliance Jamnagar and Indian Oil refineries at Mathura and Panipat drive procurement for middle distillate maximization. BIS implementation of Bharat Stage VI norms creates compliance windows for high-activity zeolite systems. Western coastal complexes in Gujarat balance diesel deficit coverage against gasoline particulate precursor regulations.
South Korea
Yeosu and Ulsan refining hubs emphasize regeneration service economics amid compressed margins. MFDS-aligned environmental scrutiny shapes spent catalyst handling protocols. Complexes source bifunctional hydrocracking systems for jet fuel and diesel yield optimization.
Japan
Osaka and Yokkaichi refineries pilot bio-feedstock co-processing retrofits for FCC units. METI carbon neutrality roadmaps pressure energy intensity reductions in catalyst regeneration cycles. Technical service unbundling separates performance guarantees from supply contracts at coastal facilities.
Vietnam
Nghi Son and Long Son greenfield startups lack captive catalyst supply infrastructure. Imported hydrotreating and reforming systems fill procurement gaps for ultra-low sulfur diesel production. Southern coastal complexes represent open tender contests for international suppliers.
Asia-Pacific Refining Catalysts Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-feedstock co-processing and carbon footprint verification services. The vendor base stratifies across integrated petrochemical conglomerates with captive production, specialized catalyst houses with rare earth supply chain control, and regional fabricators serving maintenance replacement cycles. Three archetypes dominate: state-linked refiners with backward integration, multinational technology licensors with proprietary zeolite platforms, and independent regeneration service providers. Capacity expansion and strategic technology licensing constitute the primary competitive vectors.
Among multinational technology licensors, BASF SE and Albemarle Corporation exemplify premium-tier positioning through integrated rare earth access and regional manufacturing scale. Haldor Topsoe A/S anchors the specialized catalyst house archetype with sulfided metal phase expertise for hydroprocessing applications. Sinopec represents state-linked vertical integration, converting captive demand into procurement insulation against import competition.
| Leading Market Players |
|---|
| Haldor Topsoe A/S |
| Axens |
| BASF SE |
| TAIYO KOKO Co., Ltd. |
| Johnson Matthey |
| Albemarle Corporation |
| Sinopec |
| UNICAT Catalyst Technologies, LLC |
| W. R. Grace & Co.-Conn. |
| Others |
Value Chain & Pricing Dynamics
Premium-unbundled service tiers separate Japanese and South Korean coastal refiners from Southeast Asian independents, with the former stripping performance guarantees from catalyst supply contracts while the latter cling to bundled technical service packages. This divergence manifests in procurement economics: bundled contracts absorb regeneration logistics costs into upfront pricing, while unbundled structures expose buyers to spot-market volatility in hydrogen and natural gas inputs.
Pricing Analysis
Warranty and technical service unbundling distinguishes contract structures across the region. Japanese refiners at Yokkaichi and Osaka separately negotiate performance guarantees, spent catalyst reclamation, and on-site technical support, creating three-tier pricing stratification across premium, standard, and economy levels. Price differentiation rests on rare earth efficiency certifications and regeneration service bundling. Cost compression in the economy tier intensifies because Indian independent processors face margin pressure from narrowed crude differentials. Southeast Asian greenfield refineries exhibit highest price sensitivity; South Korean integrated complexes show least sensitivity due to captive regeneration infrastructure.
Supply Chain Analysis
Certified catalyst handling technicians remain scarce across Indonesian and Philippine maintenance markets, constraining turnaround scheduling flexibility. Manufacturing gravity centers on China's Dalian and Zibo clusters, with secondary capacity in South Korea and Japan. Rare earth separation draws from Inner Mongolia and Jiangxi provinces, tethering FCC catalyst formulations to Chinese upstream control. Single-source vulnerability concentrates in lanthanum and cerium supply channels. Distribution runs through coastal bulk terminals serving Bohai Rim and Yangtze Delta refining complexes, with spot charter rates for specialized catalyst vessels feeding procurement cost volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific refining catalyst procurement functions as a cost-of-compliance market where China's MEE National VI enforcement and India's BIS Bharat Stage VI norms erect regulatory moats favoring certified suppliers with verified low-carbon supply chains.
For Market Incumbents: To counter aftermarket service unbundling by Japanese and South Korean refiners, Albemarle and BASF should anchor regeneration service economics through long-term hydrogen supply agreements at Yeosu and Ulsan. Backward integration into rare earth separation capacity within China preserves margin position against Sinopec's captive supply dominance. For New Entrants and Emerging Players: Begin with Vietnam's Nghi Son and Long Son greenfield complexes, where absence of captive catalyst infrastructure creates open procurement contests for hydrotreating and reforming systems. Bio-feedstock co-processing trials at Neste Singapore and Malaysian palm oil refiners represent the most penetrable white-space segment. Position through carbon footprint verification services aligned with Sinopec's supplier qualification protocols. For Investors and Strategic Acquirers: Re-rating potential sits with independent regeneration service providers given tightening MFDS environmental scrutiny on spent catalyst handling across South Korea. Long-term viability favors specialists with certified technician networks and offshore regeneration vessel access. Watch for MEE carbon disclosure mandates propagating through Chinese refinery tender processes as inflection signal for premium-tier supplier selection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Separation | Secures lanthanum and cerium supply channels against Chinese export volatility for FCC formulations. |
| Regeneration Service Capacity Expansion | Captures unbundled demand from Japanese and South Korean coastal refiners seeking hydrogen cost hedging. |
| Carbon Footprint Verification Program | Qualifies suppliers for Sinopec tender shortlists under MEE dual carbon disclosure protocols. |
| Bio-Feedstock Co-Processing Catalyst Development | Addresses Neste Singapore and Malaysian palm oil refiner trials for renewable diesel production. |
| Certified Technician Training Network | Resolves handling specialist scarcity constraining Indonesian and Philippine turnaround scheduling. |
Study Parameters
Document review covered customs trade data from China and India, SEC filings of listed catalyst producers, MEE environmental enforcement records, and BIS fuel standard notifications, complemented by interviews with refinery procurement managers, catalyst plant technical directors, and rare earth separation facility operators. Secondary validation drew from refinery expansion databases, hydrogen supply contract registries, and spent catalyst reclamation logistics records. Bottom-up capacity and loading estimates were triangulated against top-down market sizing from regional refining throughput projections.
Installed base and replacement cycle modeling produced volume and value estimates across the projection horizon. Segmentation dimensions included catalyst product type, application process train, end-user facility scale, and technology platform. CAGRs were derived from regression analysis of historical procurement patterns against regulatory compliance timelines and refinery upgrade capex cycles. Forecast inputs incorporated crude slate heavification trajectories and dual carbon policy implementation intensity.
Underlying measurement precision varies by segment; FCC catalyst volume estimates carry tighter precision than hydrocracking catalyst value projections given proprietary pricing opacity. Forecasts reflect assumptions on MEE enforcement consistency, BIS implementation timelines, and rare earth supply chain stability. Material deviation in National VI compliance deadlines or Chinese environmental export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Catalyst Handling Services Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Environmental Catalysts Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market