
 Middle-East and Africa Refining Catalysts Market | 2026-2036
Middle-East and Africa Refining Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Refining Catalysts Market Foresight
Zeolite formulations are recalibrating cost structures for fluid catalytic cracking units across Middle-East and Africa refineries. Albemarle Corporation leverages its bromine-specialty supply chain to secure precursor access for high-activity hydroprocessing catalysts. BASF SE anchors its regional position through localized manufacturing partnerships in the Gulf Cooperation Council zone. Johnson Matthey Plc competes on emission-control catalyst integration, extending its refining portfolio into dual-function systems.
Refining catalysts are heterogeneous substances—typically comprising alumina supports impregnated with cobalt, molybdenum, nickel, or zeolite structures—that accelerate hydrocarbon conversion reactions at temperatures between 300°C and 450°C and pressures up to 200 bar, primarily enabling sulfur removal, molecular cracking, and octane enhancement in crude oil processing. Hydrotreating catalysts command the largest share of replacement demand as regional refiners process heavier, higher-sulfur crudes. Metallic catalysts lead technology adoption for hydrocracking units, while zeolite catalysts gain ground in FCC applications where yield optimization matters most. Petrochemical production represents the fastest-growing application segment, driven by integrated refinery-chemical complexes in Saudi Arabia and the UAE.
Saudi Arabia's SFDA and the UAE's MOHAP enforce industrial chemical standards that cascade into catalyst purity and trace-metal specifications, while Euro V-equivalent fuel regulations adopted across Gulf Cooperation Council members mandate ultra-low sulfur diesel production. These frameworks compel refiners to retire legacy catalyst systems ahead of mechanical end-of-life, creating recurring demand for higher-activity replacements. Stakeholders must track how national oil companies balance domestic catalyst sourcing mandates against technology licensing agreements with international suppliers.
Market Dynamics
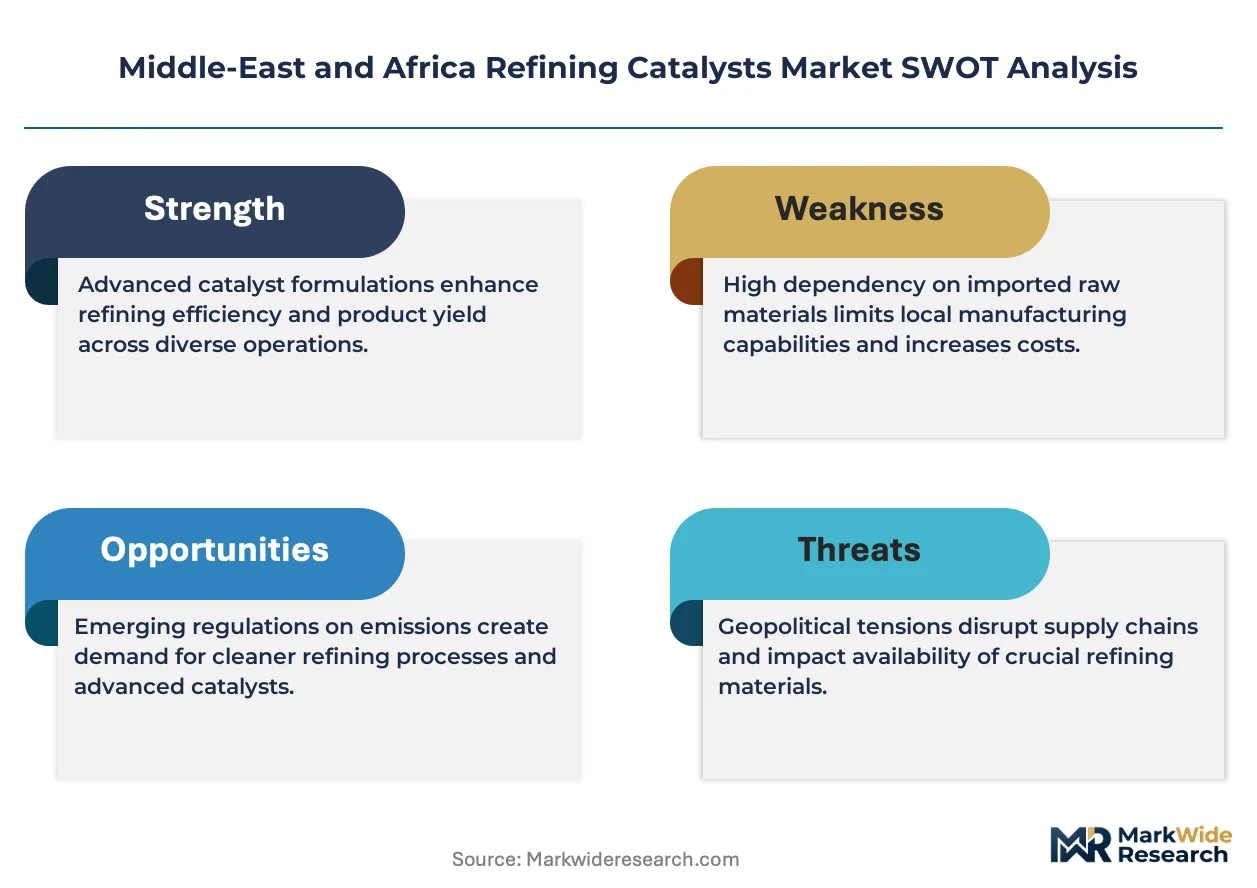
Stricter sulfur-content mandates under Euro V-equivalent standards across Gulf Cooperation Council members are forcing refiners to retire legacy catalyst systems ahead of mechanical end-of-life, creating recurring replacement demand for higher-activity hydrotreating formulations.
Growth Catalysts
- Euro V-equivalent fuel regulations:Saudi Arabia and the UAE now mandate ultra-low sulfur diesel production, compelling continuous catalyst upgrades across Jubail and Yanbu refining corridors.
- Integrated refinery-chemical complexes:Petrochemical production represents expanding catalyst demand as Saudi Aramco and ADNOC build downstream conversion capacity.
- Heavier crude processing:Regional refiners increasingly process high-sulfur feedstocks, accelerating metallic catalyst adoption for hydrocracking units.
Market Restraints
- Cobalt and molybdenum price volatility:Precursor metal cost swings compress catalyst manufacturer margins and destabilize refinery procurement budgets.
- Supply concentration in bromine-specialty chains:Limited precursor access routes create vulnerability for high-activity hydroprocessing catalyst production.
- Technical limitation in zeolite thermal stability:Fluid catalytic cracking units face activity degradation above 750°C, constraining yield optimization in heavy residuum processing.
Strategic Opportunities
- Underpenetrated Nigerian refining capacity:Dangote Refinery operations and planned upgrades create new catalyst demand outside traditional Gulf supply bases.
- Emission-control catalyst integration:Dual-function systems combining refining and environmental applications open premium pricing segments.
- Localized manufacturing partnerships:Gulf Cooperation Council domestic sourcing mandates incentivize technology licensing with regional production facilities.
Industry Challenges
- Catalyst regeneration technician scarcity:Specialized hydroprocessing unit expertise concentrates among aging workforces in Saudi Arabia and South Africa.
- IP licensing complexity:Proprietary zeolite formulations from international suppliers conflict with national oil company technology transfer requirements.
- Legacy system integration friction:New high-activity catalysts require reactor retrofitting incompatible with 1980s-era hydrotreater designs still operating in Egypt and Algeria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Refining Catalysts Market |
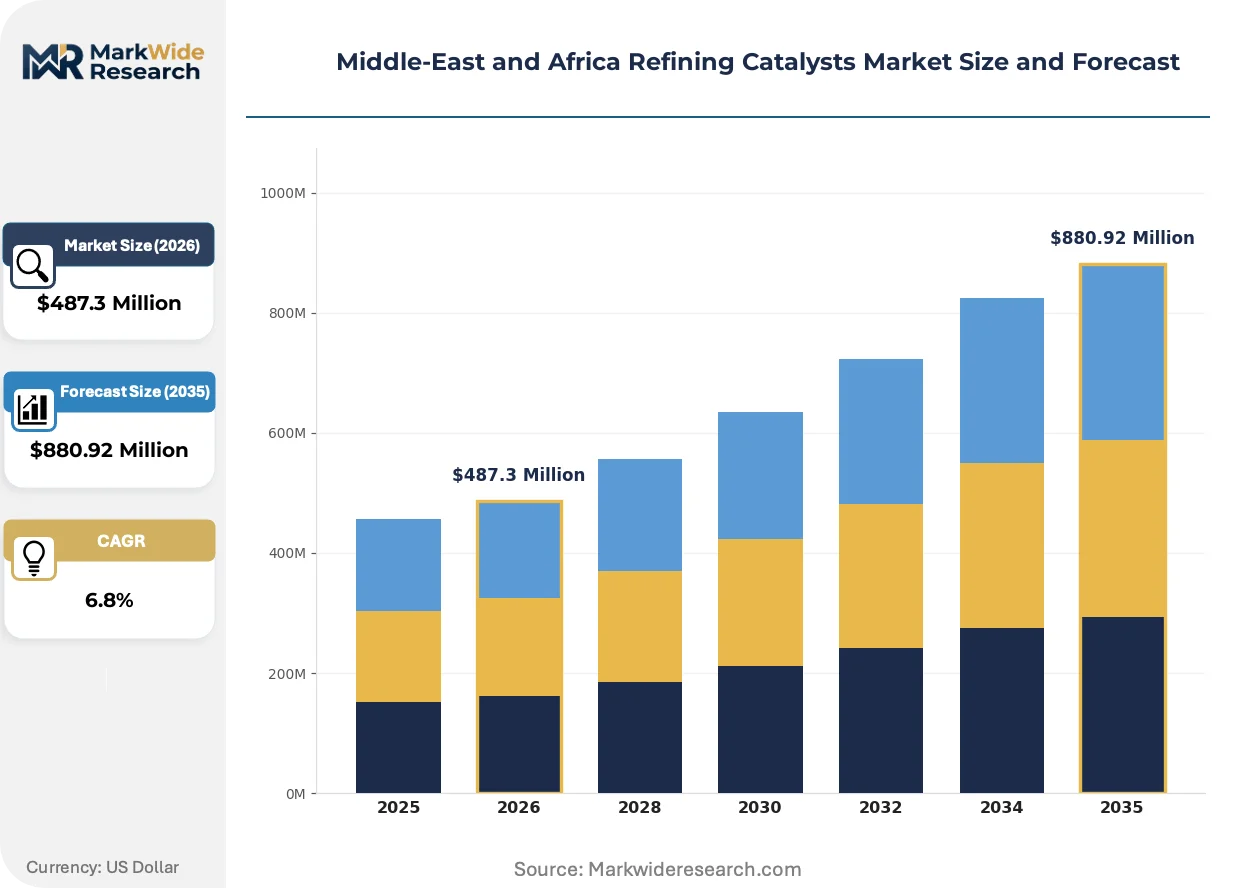
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocracking Catalysts, Hydrotreating Catalysts, Reforming Catalysts, Additive Catalysts Application: Petroleum Refining, Petrochemical Production, Fuel Production, Chemical Manufacturing End User: Oil Refineries, Chemical Plants, Petrochemical Companies, Government Entities Technology: Metallic Catalysts, Zeolite Catalysts, Biocatalysts, Composite Catalysts |
| Companies Covered | Honeywell International Inc., W. R. Grace, Albemarle Corporation, DuPont, Axens, BASF SE, Johnson Matthey Plc, Kuwait Catalyst Company, Clariant, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Refining Catalysts Market Shifts & Advancements
Zeolite-based formulations are recalibrating cost structures across fluid catalytic cracking operations while regulatory convergence on Euro V-equivalent standards compresses replacement cycles. These forces are reshaping how refiners procure, deploy, and regenerate catalyst systems.
Advanced zeolite structures with tailored acidity profiles are consolidating market share in FCC applications where yield optimization determines refinery economics. Saudi Aramco and ADNOC affiliates are adopting these materials at accelerated replacement schedules. The technology is consolidating supplier positions around precursor-secure manufacturers with captive bromine access.
SFDA and MOHAP industrial chemical standards now cascade into mandatory catalyst purity specifications and trace-metal limits across Saudi Arabia and the UAE. Refiners must certify each catalyst batch against heavy-metal contamination thresholds before reactor loading. Hydrotreating operations face the steepest compliance burden, with replacement intervals shortening to accommodate verification protocols.
Refiners are unbundling catalyst supply from technical service contracts, separating procurement of alumina-supported formulations from regeneration and spent catalyst management. This disintermediation pressures traditional full-service suppliers and opens direct manufacturer relationships. The shift is most visible in Saudi Arabia's Jubail corridor, where national oil companies negotiate volume-based precursor supply agreements independent of technical support packages.
Middle-East and Africa Refining Catalysts Market Segmentation
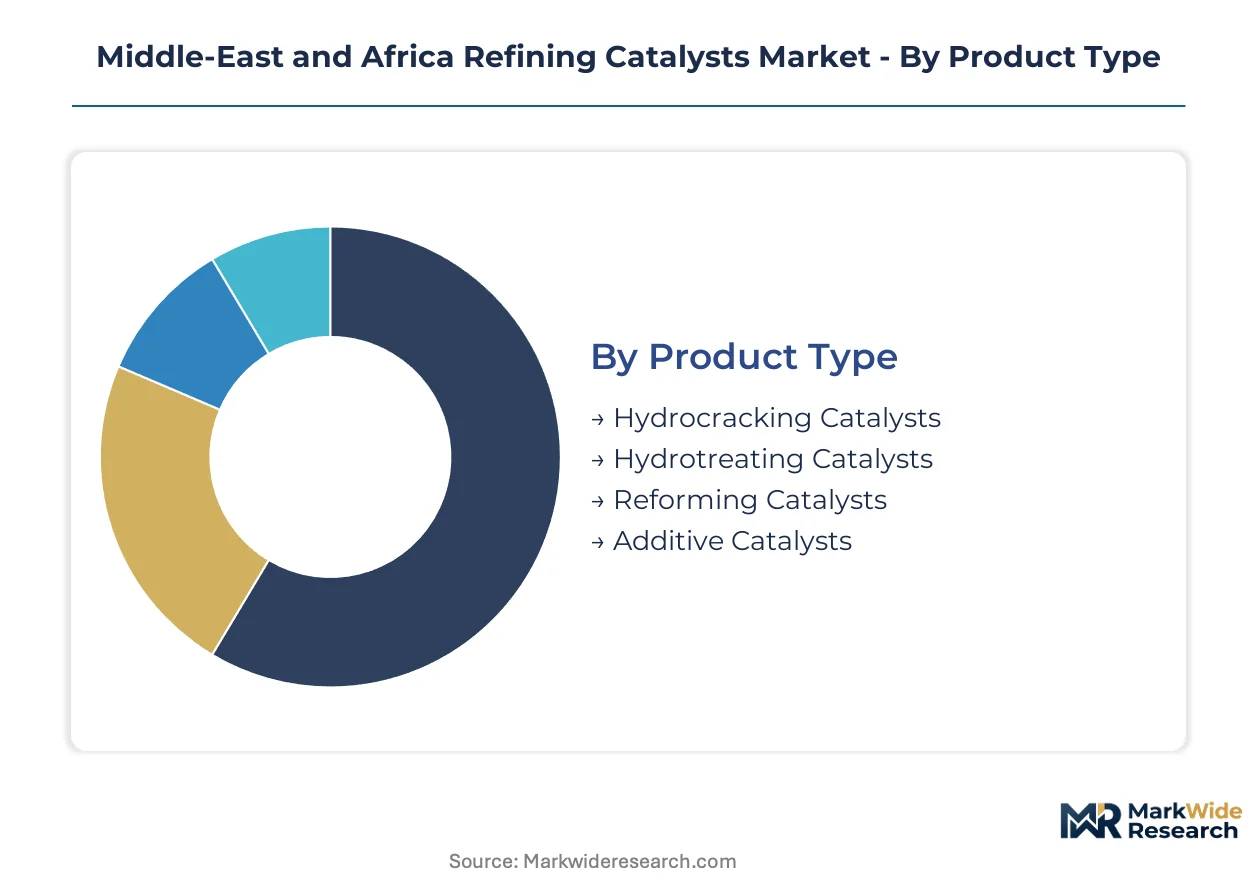
Refining catalyst procurement patterns diverge sharply across product formulations, end-use applications, and technology platforms. Each dimension reveals distinct supply chain configurations and margin structures that determine competitive positioning among regional refiners.
Product Type:
Supply concentration for high-activity formulations centers on manufacturers with captive precursor access to cobalt, molybdenum, and specialty zeolite structures.
- Hydrotreating Catalysts:Alumina-supported formulations impregnated with cobalt-molybdenum or nickel-molybdenum active phases dominate sulfur removal operations. Saudi Arabia's Jubail and Yanbu corridors consume continuous replenishment volumes driven by Euro V-equivalent diesel mandates.
- Hydrocracking Catalysts:Metallic catalysts featuring tailored acidity profiles convert heavy vacuum gas oil into lighter distillates. ADNOC's Ruwais complex and Saudi Aramco's integrated facilities anchor regional demand for these high-pressure systems.
- Reforming Catalysts:Bimetallic platinum-rhenium formulations on chlorided alumina supports upgrade naphtha octane ratings for gasoline blending.
- Additive Catalysts:Specialized materials including combustion promoters and SOx reduction additives optimize fluid catalytic cracking unit performance.
Hydrotreating catalysts absorb the bulk of installed capacity; hydrocracking catalysts are expanding most quickly as refiners process heavier crudes.
Application:
Cost tier differentiation separates continuous replacement cycles in mature refining from capital-intensive expansions in integrated chemical complexes.
- Petroleum Refining:Hydrotreating and hydrocracking operations consume catalyst volumes tied directly to crude throughput and sulfur content. Egyptian and Algerian refineries operating 1980s-era hydrotreaters face retrofitting costs to accommodate modern high-activity systems.
- Petrochemical Production:Integrated refinery-chemical complexes in Saudi Arabia and the UAE drive fastest-expanding catalyst demand for aromatics production and olefin conversion. These facilities require specialized zeolite formulations with controlled acidity profiles.
- Fuel Production:Ultra-low sulfur gasoline and diesel specifications mandate precise catalyst selection for reforming and alkylation units.
- Chemical Manufacturing:Specialty chemical producers in South Africa leverage hydroprocessing catalysts for intermediate production.
Petroleum refining maintains the largest installed base; petrochemical production shows the steepest expansion trajectory.
End User:
Volume concentration among national oil companies creates procurement patterns favoring long-term supply agreements over spot market transactions.
- Oil Refineries:Saudi Aramco, ADNOC, and Kuwait Petroleum Corporation operate the region's largest hydrotreating and hydrocracking unit fleets. These entities negotiate direct precursor supply agreements independent of technical service packaging.
- Petrochemical Companies:SABIC and Borouge anchor demand for FCC and reforming catalysts in integrated chemical production.
- Chemical Plants:South African synthetic fuel producers and Egyptian fertilizer manufacturers represent specialized catalyst consumers.
- Government Entities:State-backed refining ventures in Nigeria and Algeria procure through tender processes subject to domestic sourcing mandates.
Oil refineries command the dominant share of procurement volume; petrochemical companies are gaining share fastest through downstream integration.
Technology:
Margin structures favor manufacturers controlling zeolite synthesis and bromine-specialty precursor supply chains.
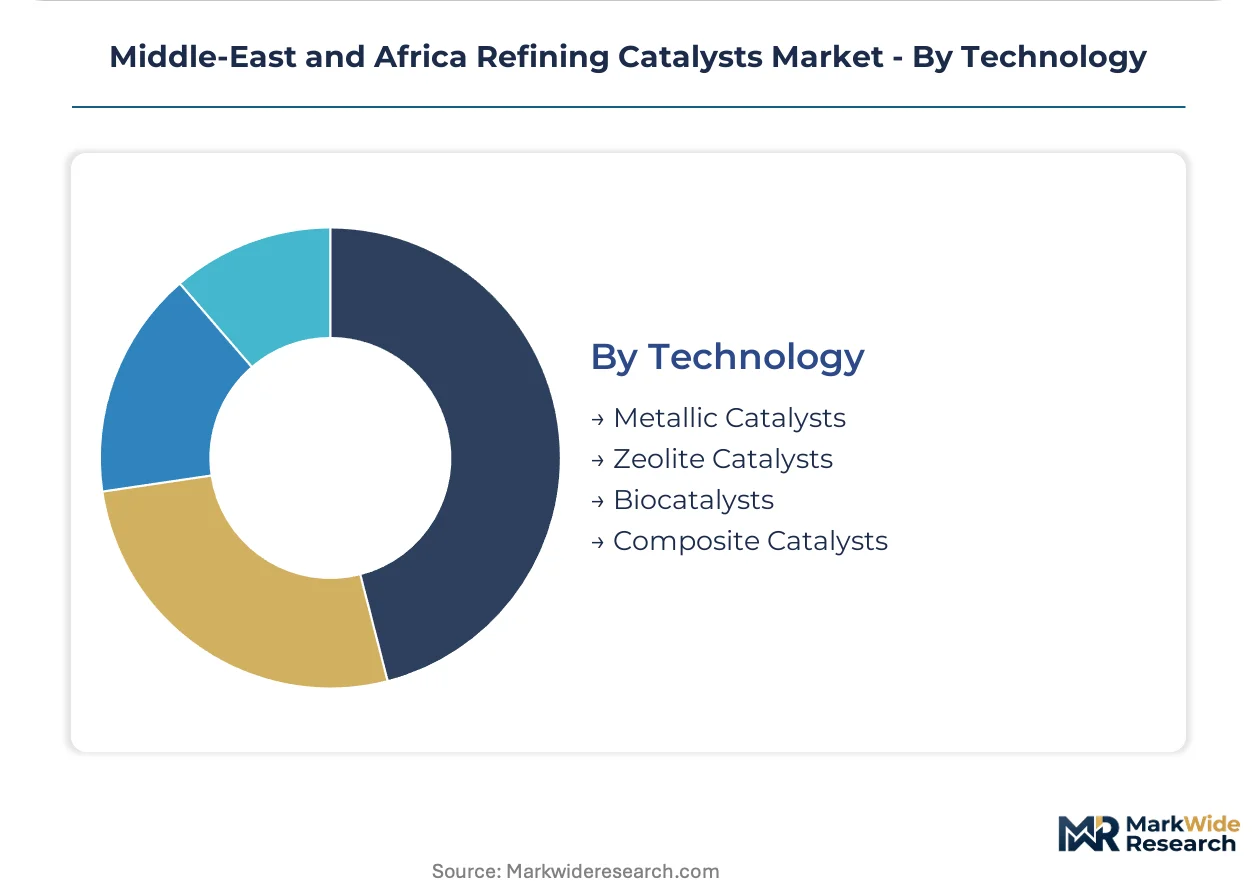
- Metallic Catalysts:Cobalt, molybdenum, and nickel active phases on alumina supports dominate hydrocracking and hydrotreating applications. Price volatility in precursor metals compresses manufacturer margins and destabilizes refinery budgeting.
- Zeolite Catalysts:Tailored acidity Y-zeolite and ZSM-5 structures optimize FCC yields and petrochemical feedstock production. Thermal stability limitations above 750°C constrain heavy residuum processing applications.
- Biocatalysts:Enzymatic systems for specialty chemical and biofuel applications remain nascent in regional refining.
- Composite Catalysts:Hybrid metallic-zeolite formulations address specific hydrocracking selectivity requirements.
Metallic catalysts retain the largest installed base; zeolite catalysts are climbing the fastest as yield optimization drives FCC economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail and Yanbu industrial cities concentrate refining catalyst demand through special economic zone status and integrated petrochemical infrastructure. Saudi Aramco operates the region's densest hydrotreating unit networks across these corridors. National oil companies anchor procurement through long-term supply agreements tied to capacity expansion timelines.
Saudi Arabia
Jubail and Yanbu refining corridors consume continuous catalyst replenishment volumes for hydrotreating and hydrocracking operations. SFDA enforces industrial chemical standards that cascade into mandatory catalyst purity specifications and trace-metal limits. Saudi Aramco's integrated refinery-chemical complexes drive fastest-expanding demand for specialized zeolite formulations with controlled acidity profiles.
United Arab Emirates
ADNOC's Ruwais complex anchors regional demand for high-pressure hydrocracking catalyst systems processing heavier crude feedstocks. MOHAP mandates industrial chemical standards that require batch certification against heavy-metal contamination thresholds before reactor loading. Dubai and Abu Dhabi refining facilities face shortened replacement intervals to accommodate verification protocols under Euro V-equivalent diesel specifications.
Nigeria
Dangote Refinery operations in Lagos State create new catalyst demand outside traditional Gulf supply bases for hydrotreating and fluid catalytic cracking units. The country's petroleum regulator enforces fuel quality standards that compel ultra-low sulfur diesel production capabilities. Lekki Free Trade Zone infrastructure supports direct precursor supply agreements independent of technical service packaging.
South Africa
Synthetic fuel producers in Mpumalanga and Free State provinces leverage hydroprocessing catalysts for intermediate chemical production. The country's national petroleum regulator aligns industrial chemical standards with regional fuel specifications. Sasolburg and Secunda industrial clusters concentrate specialized catalyst consumption for coal-to-liquids and gas-to-liquids conversion facilities.
Egypt
Mostorod and Alexandria refineries operate 1980s-era hydrotreaters requiring retrofitting costs to accommodate modern high-activity catalyst systems. The Egyptian General Petroleum Corporation enforces procurement processes subject to domestic sourcing mandates for state-backed refining ventures. Cairo-Alexandria corridor facilities face integration friction between new catalyst formulations and legacy reactor designs.
Middle-East and Africa Refining Catalysts Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology licensors dominating high-activity formulations and regional fabricators capturing regeneration services. The vendor base concentrates around manufacturers with captive precursor access to cobalt, molybdenum, and specialty zeolite structures. Three archetypes define competitive positioning: multinational technology licensors with integrated R&D pipelines, regional joint ventures serving domestic sourcing mandates, and specialized regeneration service providers. Dominant competitive moves include strategic partnerships for localized manufacturing capacity and technology licensing agreements that satisfy national oil company transfer requirements.
Within the technology licensor tier, Honeywell International Inc., Albemarle Corporation, and BASF SE exemplify multinational players anchoring premium positioning through precursor-secure supply chains and integrated service portfolios. Honeywell UOP technology licensing extends across Saudi Aramco and ADNOC facilities. Albemarle leverages bromine-specialty supply chain access for high-activity hydroprocessing formulations. BASF SE occupies a position through Gulf Cooperation Council manufacturing partnerships that satisfy domestic content requirements. These three companies represent the archetype of full-service suppliers facing disintermediation pressure as refiners unbundle catalyst procurement from technical service contracts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| W. R. Grace |
| Albemarle Corporation |
| DuPont |
| Axens |
| BASF SE |
| Johnson Matthey Plc |
| Kuwait Catalyst Company |
| Clariant |
| Others |
Supply & Pricing Matrix
Specialized catalyst regeneration technicians concentrated in Saudi Arabia's Eastern Province and South Africa's industrial hubs create labor-cost differentials that widen pricing-tier spreads between premium full-service contracts and unbundled material supply. These workforce concentrations allow Gulf-based refiners to negotiate volume-based precursor agreements while Nigerian and Egyptian buyers absorb technical-service premiums due to scarcer local expertise.
Pricing Analysis
Volume-based procurement absorbs the largest share of catalyst expenditure while margin capture concentrates in technical-service bundling. Three-tier pricing structure across premium, standard, and economy levels separates full-service regeneration contracts from material-only supply and spot-market distressed volumes. Price differentiation hinges on certification grade under SFDA and MOHAP trace-metal protocols plus after-sales technical support intensity. Pricing pressure stems from cobalt and molybdenum precursor volatility compressing manufacturer margins. National oil companies in Saudi Arabia and the UAE exhibit lowest price sensitivity due to integrated procurement authority, while Egyptian and Algerian state refineries face acute budget constraints from legacy system retrofitting requirements.
Supply Chain Analysis
Workforce availability for zeolite synthesis and catalyst impregnation concentrates in Germany, the United States, and China, constraining regional manufacturing scale-up. Raw material dependencies center on bromine-specialty precursors from Albemarle's captive supply chains, cobalt from Central African mining operations, and alumina supports from Australian and Brazilian refiners. Single-source vulnerability in high-activity hydroprocessing formulations creates supply chain risk from geopolitical disruption or export licensing shifts. Distribution runs through long-term offtake agreements directly between catalyst manufacturers and national oil company procurement divisions, bypassing traditional distributor networks in the Gulf Cooperation Council zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa refining catalysts market sits in a technology-transition phase as zeolite-based formulations displace legacy alumina-supported systems for fluid catalytic cracking yield optimization.
For Market Incumbents: Deploy captive precursor access as the primary defensive lever. Secure backward integration into cobalt and molybdenum supply chains to buffer margin compression from metal price volatility. Expand technical-service bundling in Nigeria and Egypt where workforce scarcity prevents refiner self-sufficiency in catalyst regeneration. Counter disintermediation pressure by embedding proprietary zeolite formulations into long-term technology licensing agreements with Saudi Aramco and ADNOC. For New Entrants and Emerging Players: Nigerian independent refiners represent the most penetrable buyer archetype outside established Gulf supply relationships. Target Dangote Refinery's second-phase expansion and potential domestic catalyst sourcing mandates for initial contract wins. White-space opportunity exists in spent catalyst recycling and metal recovery services for South African synthetic fuel producers. Pursue joint-venture structures with Gulf Cooperation Council manufacturing partners to satisfy domestic content requirements without full technology transfer. For Investors and Strategic Acquirers: Re-rating potential sits with specialized regeneration service providers given accelerating catalyst replacement cycles under Euro V-equivalent standards. Long-term viability favors asset-light technical-service platforms over capital-intensive manufacturing in a market trending toward unbundled procurement. Watch for inflection in Nigerian refining utilization rates as signal for regional demand rebalancing away from Gulf concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Metals | Captive cobalt and molybdenum supply secures margin stability against commodity volatility for hydroprocessing formulations. |
| Localized Manufacturing Partnership | Gulf Cooperation Council joint ventures satisfy Saudi and UAE domestic sourcing mandates while preserving IP control. |
| Dual-Function Catalyst Development | Emission-control integration opens premium pricing segments in ADNOC and Saudi Aramco environmental compliance programs. |
| Spent Catalyst Metal Recovery | Circular economy positioning captures value from South African and Nigerian refinery waste streams amid supply concentration. |
| Technical-Service Unbundling Response | Separate regeneration and procurement contracts address Jubail corridor national oil company pricing pressure. |
Research Methodology
Multi-period observation of catalyst replacement intervals, refinery capacity utilization, and precursor metal price movements anchored the trend analysis, supplemented by interviews with hydroprocessing unit managers at Saudi Aramco and ADNOC facilities, catalyst procurement leads at Egyptian General Petroleum Corporation, technical R&D directors at zeolite formulation specialists, and regeneration service technicians in South Africa's Sasolburg complex. Secondary validation drew from customs and trade data on cobalt and molybdenum imports, SEC filings of listed catalyst manufacturers, Gulf Cooperation Council industrial chemical standards documentation, and refinery expansion project databases. Bottom-up unit-level catalyst consumption estimates triangulated against top-down market sizing from regional refining capacity assessments.
Input-output matrices mapped catalyst demand against crude throughput projections, sulfur-content regulatory phase-in schedules, and technology adoption curves for zeolite versus metallic formulations across the modeling period. Segmentation dimensions modeled include product type tier, application intensity, end-user procurement authority, and technology platform maturity. CAGRs derived from regression analysis of historical replacement cycles extrapolated against announced capacity additions and regulatory compliance deadlines. Industry-specific forecast inputs incorporated SFDA and MOHAP certification timeline assumptions plus Dangote Refinery ramp-up trajectory.
Revisions become necessary when Euro V-equivalent adoption timelines accelerate, cobalt supply disruptions from Central African sources materialize, or Nigerian refining utilization diverges from base-case assumptions. Forecasts reflect documented assumptions regarding zeolite thermal stability improvements and national oil company unbundling preferences. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Global VOC Catalysts Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Polymerization Catalysts Market
Catalysts
Natural Zeolites Market
Catalysts
Global Catalyst Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Hydrodesulfurization Catalyst Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Refining Catalysts Market
Catalysts
Heterogeneous Catalyst Market