
 FCC Catalyst Additive Market | 2026-2036
FCC Catalyst Additive Market Size, Share, and Industry Trends Forecast 2026-2036
FCC Catalyst Additive Market Intelligence
Project finance for FCC unit retrofits is tilting competitive dynamics toward suppliers with balance-sheet capacity to underwrite long-term catalyst supply contracts. Albemarle leverages its integrated rare earth supply chain to secure multi-year offtake agreements with Middle Eastern refiners. BASF sustains R&D intensity across zeolite architectures, while Johnson Matthey navigates the shift toward residue FCC processing with specialized metal passivation technologies.
FCC catalyst additives are zeolite-based materials, typically incorporating ZSM-5, Y zeolite, or beta zeolite frameworks within a silica-alumina matrix, designed to enhance gasoline yield, reduce coke formation, or boost propylene selectivity in fluid catalytic cracking units operating at 480–540°C. Their primary purpose is to optimize refinery margins by converting heavy vacuum gas oil into lighter, higher-value transportation fuels and petrochemical feedstocks. Y zeolite formulations still anchor the largest volume share due to their established cracking activity, though ZSM-5 additive demand is accelerating fastest as refiners target petrochemical integration. Fixed bed installations retain the dominant installed base, while fluidized bed configurations are capturing new-build preference for operational flexibility.
EPA fuel standards, China's MEE emission mandates, and India's BIS refining product specifications collectively tighten sulfur and particulate limits, which directly expands demand for high-activity FCC additives that enable cleaner combustion profiles. The EU F-Gas Regulation and REACH chemical frameworks add compliance layers for catalyst precursors imported into European refineries. Stakeholders must monitor how carbon border adjustments and national hydrogen strategies reshape the economic viability of FCC-based refining relative to alternative cracking technologies.
Market Dynamics
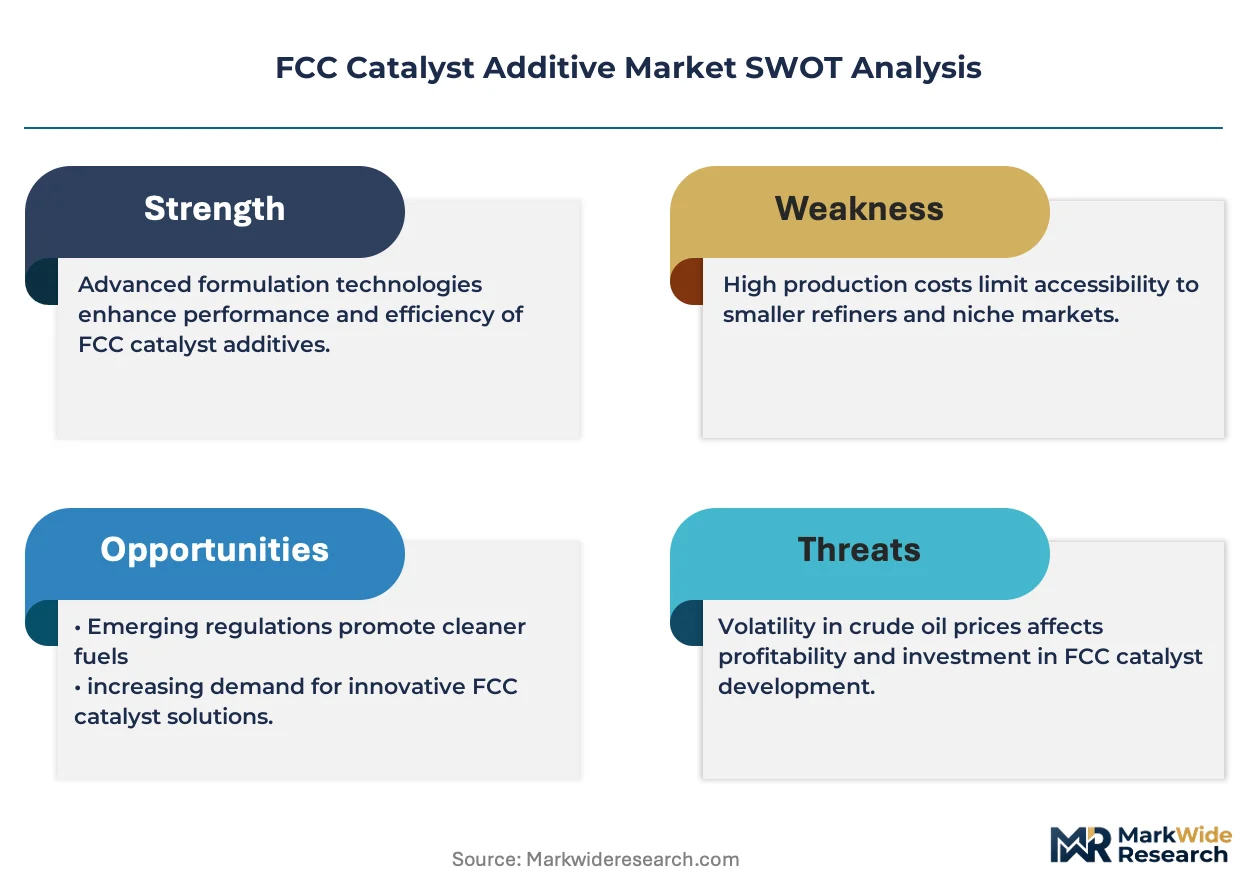
The FCC catalyst additive market pivots on refiners' urgent need to process heavier, higher-sulfur crude slates while meeting tightening emission standards. This structural pressure forces continuous reformulation of zeolite architectures and metal passivation systems to maintain gasoline yield and propylene selectivity.
Growth Catalysts
- China's MEE emission mandates:Tightening sulfur and particulate limits force refiners to upgrade FCC units with high-activity additives that enable cleaner combustion profiles and reduce stack emissions.
- Petrochemical integration wave:Refiners across India and the Middle East are reconfiguring FCC units to maximize propylene output, accelerating ZSM-5 additive demand for enhanced light olefin selectivity.
- Residue processing economics:Vacuum residue FCC installations require specialized metal passivation and bottoms-cracking additives to handle elevated nickel, vanadium, and Conradson carbon levels.
Market Restraints
- Rare earth supply concentration:Lanthanum and cerium availability hinges on Chinese export quotas and domestic processing capacity, creating input cost volatility for Y zeolite formulations.
- Residual oil cracking limitations:Metal tolerance in conventional zeolite frameworks caps the percentage of resid feedstock without severe catalyst deactivation and regenerator constraints.
- EU REACH compliance friction:Catalyst precursor registration and authorization timelines extend 18-24 months, delaying new additive introductions into European refineries.
Strategic Opportunities
- India's capacity expansion:New FCC units at Reliance Jamnagar and Indian Oil refineries create captive demand for long-term catalyst supply contracts with technical service bundling.
- Hydrogen co-processing convergence:Integration of FCC additives with hydrocracker pretreatment units enables single-refinery optimization across cracking severity and hydrogen consumption.
- Digital catalyst monitoring:Real-time particle attrition and activity tracking via refinery sensor networks enables predictive additive dosing and performance guarantees.
Industry Challenges
- Zeolite synthesis expertise scarcity:Commercial-scale production of stabilized ultra-stable Y zeolite requires rare colloid chemistry and hydrothermal engineering skills concentrated at legacy research centers.
- Refinery-specific formulation complexity:Each FCC unit's feedstock slate, riser design, and regenerator metallurgy demands customized additive matrices, fragmenting production runs and extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FCC Catalyst Additive Market |
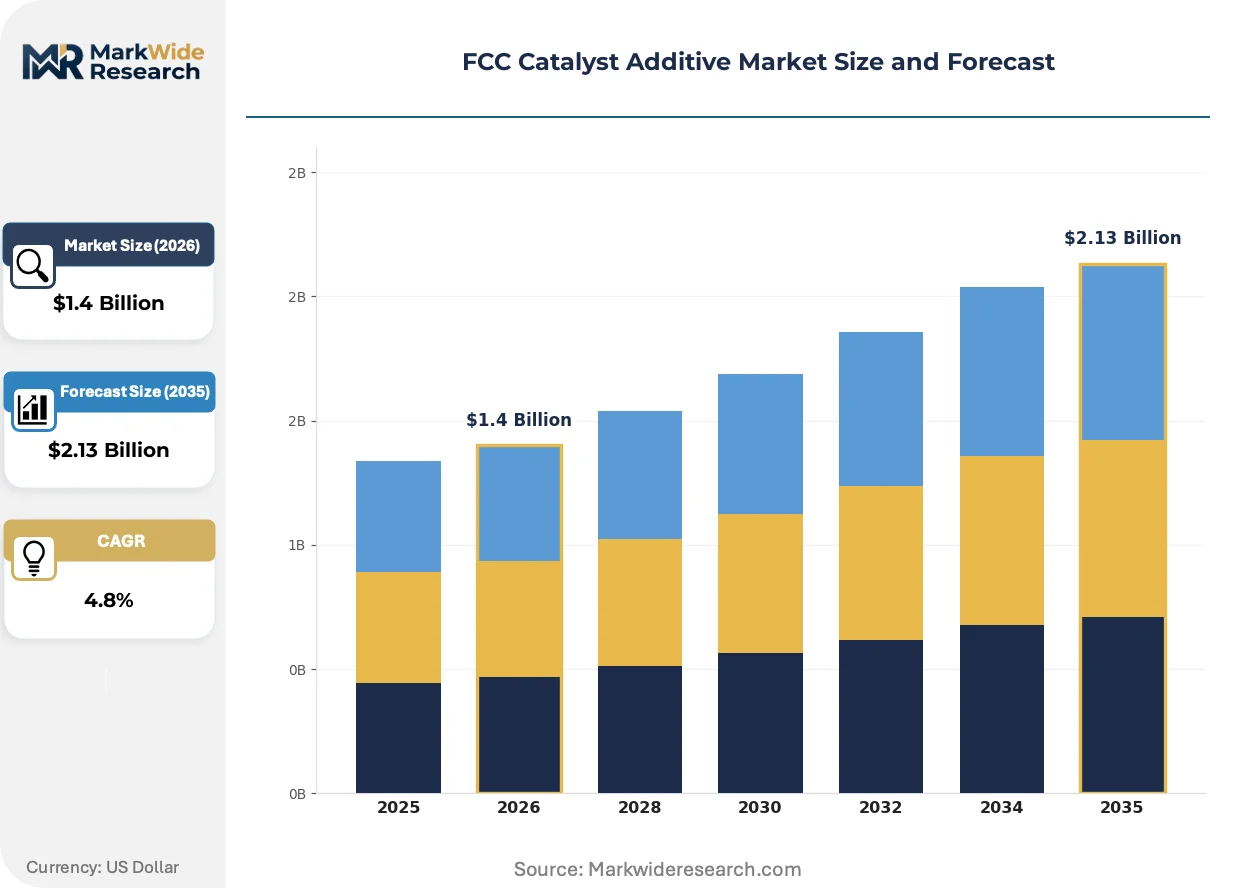
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ZSM-5, Beta Zeolite, Y Zeolite, Other Additives Application: Catalytic Cracking, Hydrocracking, Fluid Catalytic Cracking, Other Processes End User: Refineries, Petrochemical Plants, Chemical Manufacturers, Oil Processing Companies Installation: Fixed Bed, Fluidized Bed, Moving Bed, Other Configurations |
| Companies Covered | Albemarle, CNPC, Grace Catalysts Technologies, Honeywell UOP, JGC Catalyst and Chemicals, BASF, Sinopec, Axens, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FCC Catalyst Additive Market Strategic Shifts & Innovations
Zeolite architecture advances and regulatory tightening are compressing product lifecycles while opening premium tiers for performance-guaranteed formulations. Additive suppliers now compete on technical service intensity rather than commodity chemistry alone.
Structured mesoporous zeolites with hierarchical pore systems are digitizing how refiners model and predict FCC yield structures. These materials combine microporous cracking activity with enhanced diffusion pathways for bulky resid molecules. European and Middle Eastern refiners are adopting them fastest for heavy feedstock flexibility. The technology is digitizing refinery planning by enabling real-time integration of catalyst properties with process simulation platforms.
REACH authorization requirements for synthetic amorphous silica and alumina precursors are extending supplier qualification timelines and favoring incumbents with established dossiers. The regulation forces additive manufacturers to maintain dual supply chains for EU and non-EU formulations. Catalyst precursors containing nanoscale particles face the strictest scrutiny, compressing innovation pipelines for next-generation architectures.
Refiners are consolidating catalyst procurement under enterprise-wide framework agreements that unbundle technical service from material supply. This shift compresses the number of qualified suppliers per region while expanding performance-based penalty and bonus clauses. The transformation is most visible in the Middle East, where national oil companies centralize additive buying across multiple FCC units.
FCC Catalyst Additive Market Segmentation
Zeolite architecture diversity and reactor configuration variations fragment the FCC catalyst additive landscape into distinct technical tiers. Each segment carries unique qualification cycles and margin structures that reshape supplier competitive positioning.
Product Type:
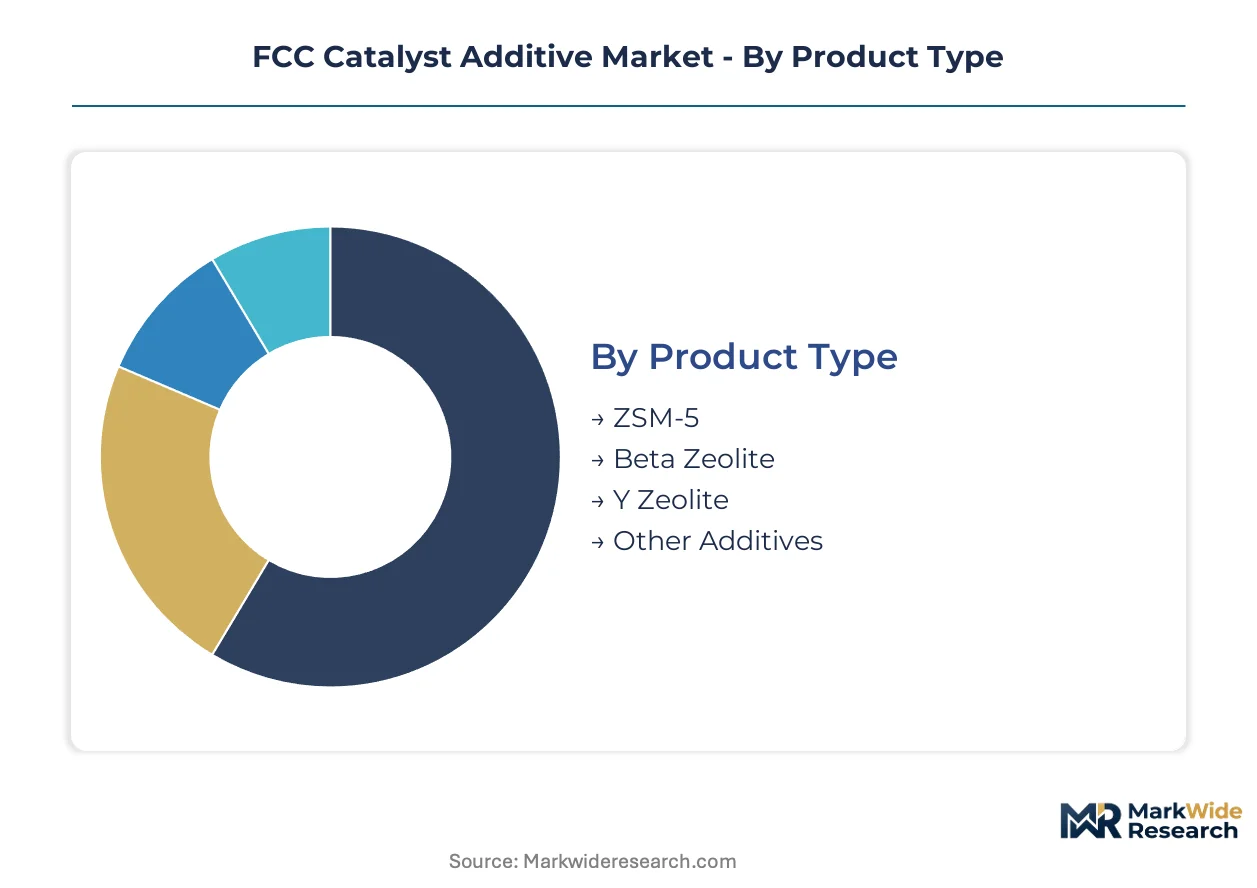
Cost tier differentiation separates commodity Y zeolite formulations from premium ZSM-5 and beta zeolite architectures engineered for petrochemical selectivity.
- Y Zeolite:Ultra-stable faujasite frameworks stabilized by rare earth exchange dominate volume shipments. Refineries in India and the Middle East anchor demand for this established chemistry where gasoline yield maximization remains the primary objective.
- ZSM-5:Pentasil zeolite structures with controlled acid site density enable light olefin selectivity. Demand concentrates at Reliance Jamnagar and Saudi Aramco facilities reconfiguring FCC units for propylene output amid the petrochemical integration wave.
- Beta Zeolite:Three-dimensional 12-ring channel systems offer intermediate cracking severity for naphtha range products.
- Other Additives:Metal passivation agents and bottoms-cracking enhancers address resid processing economics.
Y Zeolite commands the established base. The steepest expansion runs through ZSM-5.
Application:
Application scope spans cracking severity gradients from mild hydrocracking pretreatment to maximum severity fluid catalytic cracking operations.
- Fluid Catalytic Cracking:Riser-reactor configurations operating at 480–540°C consume the majority of zeolite additive volumes. China's MEE emission mandates force continuous reformulation of these units to reduce stack sulfur and particulate outputs.
- Catalytic Cracking:Fixed bed and moving bed variants serve smaller refineries with lighter feedstock slates. Indian Oil and HPCL facilities utilize these configurations for intermediate distillate production.
- Hydrocracking:Bifunctional catalyst systems combining zeolite acidity with metal hydrogenation sites.
- Other Processes:Residue hydroprocessing and mild hydrocracking applications.
Fluid Catalytic Cracking anchors installed capacity. Catalytic Cracking configurations gain share fastest in emerging market refinery expansions.
End User:
Customer type determines procurement sophistication, with integrated refiners demanding performance guarantees that independent processors cannot underwrite.
- Refineries:Integrated refining-petrochemical complexes like Reliance Jamnagar and Saudi Aramco's Ras Tanura drive formulation co-development programs. These operators specify zeolite architectures tied to real-time yield optimization models.
- Petrochemical Plants:Standalone olefin producers purchase FCC additives for fluidized bed propylene maximization units. Chinese private refiners expanding into petrochemicals represent the fastest-expanding customer cohort.
- Chemical Manufacturers:Specialty chemical producers utilizing FCC by-products as feedstock.
- Oil Processing Companies:Upstream operators with captive refining capacity.
Refineries concentrate the mature demand base. Petrochemical Plants are climbing the fastest as crackers integrate with FCC units.
Installation:
Reactor configuration dictates additive physical properties, with fluidized bed systems demanding optimized particle attrition resistance absent in fixed bed designs.
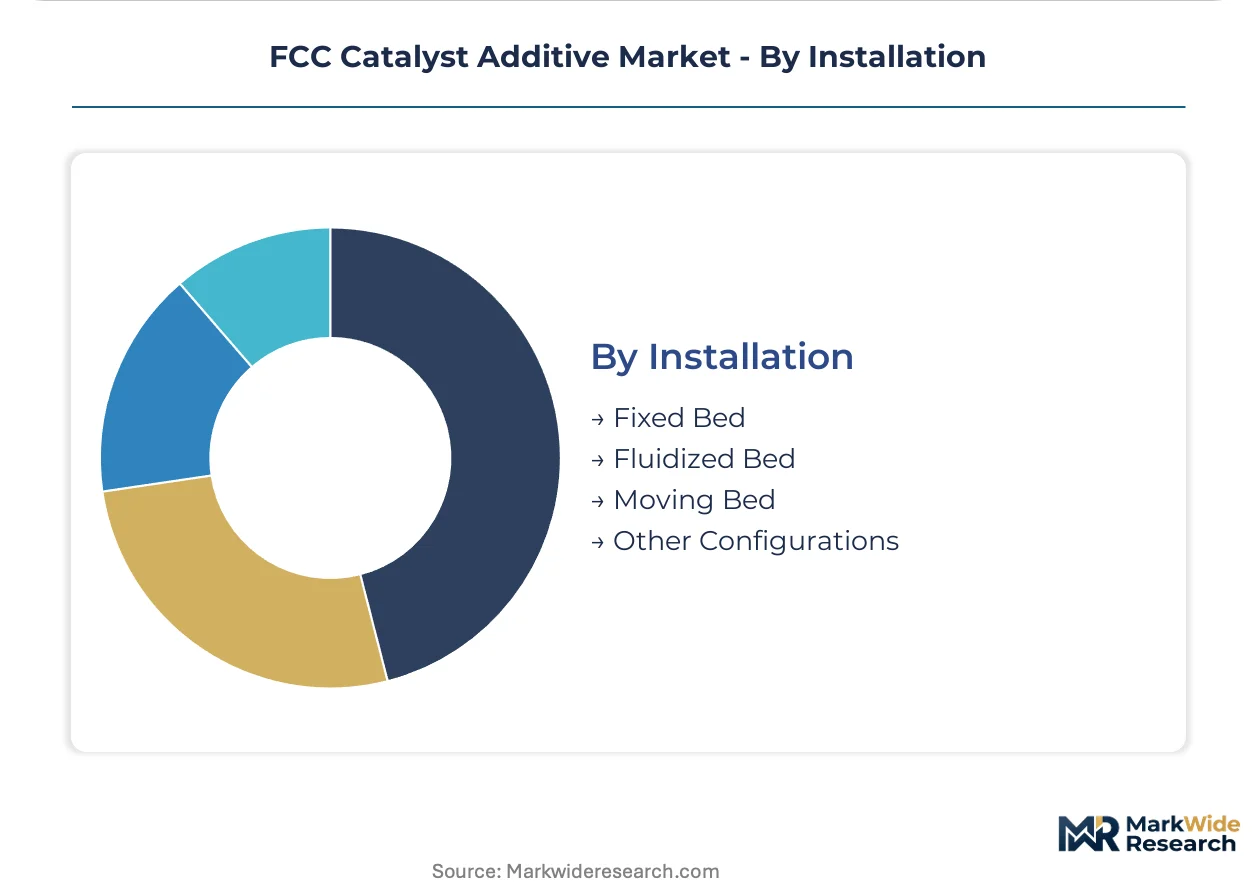
- Fixed Bed:Pelletized catalyst configurations retain the largest historical installed base across European and North American refineries. These units favor Y zeolite formulations with established regeneration protocols.
- Fluidized Bed:Circulating catalyst systems with continuous regeneration dominate new-build preference. Middle Eastern national oil companies specify these configurations for operational flexibility and heavier feedstock tolerance.
- Moving Bed:Semi-continuous regeneration systems serve niche resid processing applications.
- Other Configurations:Dual-riser and downer reactor designs.
Fixed Bed retains the legacy installed base. Fluidized Bed captures the steepest expansion trajectory in greenfield refinery investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in rare earth elements and finished catalyst formulations are redrawing regional supply maps. China maintains net exporter status for lanthanum and cerium precursors, while India and Middle Eastern nations remain import-dependent for high-activity zeolite architectures.
China
Domestic FCC additive production serves both internal refinery upgrades and selective export markets. MEE emission mandates force continuous catalyst reformulation to reduce stack sulfur outputs. Sinopec and CNPC facilities in Shandong and Liaoning provinces are expanding ultra-stable Y zeolite synthesis capacity for resid processing applications.
United States
EPA fuel standards and refinery margin compression drive demand for metal passivation additives in Gulf Coast processing complexes. The IRA's clean hydrogen provisions are reshaping FCC unit economics relative to hydrocracker alternatives. Houston and Port Arthur host the densest concentration of catalyst technical service operations.
India
Reliance Industries and Indian Oil are commissioning new FCC units at Jamnagar and Paradip, creating captive demand for long-term supply contracts. BIS refining product specifications tighten sulfur limits in transportation fuels. Gujarat and Odisha are emerging as the primary clusters for catalyst formulation partnerships with international suppliers.
Saudi Arabia
Saudi Aramco's Ras Tanura and Yanbu refineries are reconfiguring FCC units for maximum propylene selectivity. SFDA chemical registration requirements extend qualification timelines for new additive introductions. The Eastern Province concentrates both resid processing capacity and catalyst performance guarantee negotiations.
Germany
REACH authorization requirements for synthetic amorphous silica precursors favor incumbent suppliers with established dossiers. ECHA's scrutiny of nanoscale catalyst particles compresses innovation pipelines for next-generation zeolite architectures. The Ruhr industrial region and Ludwigshafen chemical cluster anchor EU catalyst precursor manufacturing.
FCC Catalyst Additive Market Key Industry Players
On the supply side, the industry is consolidating around integrated rare earth processors and specialized zeolite synthesis houses. Three strategic archetypes dominate: diversified chemical conglomerates with captive rare earth supply chains, pure-play catalyst specialists with refinery-embedded technical service teams, and state-affiliated energy companies with backward integration into additive manufacturing. Competitive moves center on multi-year offtake agreements with performance guarantees and geographic expansion through localized formulation facilities.
Within the integrated chemical tier, Albemarle and BASF exemplify supply chain control strategies. Albemarle leverages its rare earth processing footprint to underwrite long-term contracts with Middle Eastern refiners. BASF occupies a position anchored in European zeolite R&D infrastructure. Among state-affiliated players, Sinopec and CNPC represent captive demand integration, with internal consumption driving scale economics in lanthanum-exchanged Y zeolite production. Johnson Matthey sits within the specialist tier, its metal passivation expertise aligning with resid FCC processing trends.
| Leading Market Players |
|---|
| Albemarle |
| CNPC |
| Grace Catalysts Technologies |
| Honeywell UOP |
| JGC Catalyst and Chemicals |
| BASF |
| Sinopec |
| Axens |
| Johnson Matthey |
| Others |
Cost & Logistics Intelligence
Shandong province's rare earth processing clusters concentrate lanthanum and cerium extraction capacity, translating directly into pricing power for Y zeolite formulations. Refiners in India and the Middle East face cost pass-through pressure when Chinese export quotas tighten, while additive suppliers with captive rare earth supply chains command premium contract terms.
Pricing Analysis
Industrial OEM buyers anchor long-term offtake contracting as the dominant pricing structure. Price differentiation rests on rare earth exchange grade and technical service bundling intensity. Cost compression in standard Y zeolite formulations is intensifying because Indian refiners are consolidating procurement under enterprise-wide frameworks. National oil companies in Saudi Arabia and the UAE show least price sensitivity, prioritizing performance guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for catalyst precursor imports. Manufacturing concentrates in China, Germany, and the United States, with lanthanum, cerium, and synthetic amorphous silica as critical inputs. Single-source vulnerability in rare earth separation capacity threatens formulation continuity. Distribution runs through refinery-embedded technical service teams rather than merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FCC catalyst additive market tracks a cyclical recovery pattern tied to refinery capacity expansion waves. New FCC unit commissioning in India and the Middle East drives the current upswing phase.
For Market Incumbents: Build rare earth supply chain moats through backward integration into lanthanum and cerium processing. Secure multi-year offtake agreements with Reliance Industries and Saudi Aramco before new entrant qualification cycles complete. Counter the threat of Sinopec and CNPC expanding export capacity by embedding technical service teams directly at refinery sites. For New Entrants and Emerging Players: India's petrochemical integration wave offers underpenetrated white-space for ZSM-5 additive specialists. Target standalone propylene maximization units at Chinese private refiners expanding downstream from fuel into chemicals. Enter through performance-based contracting that shifts revenue risk to yield outcomes rather than volume shipments. For Investors and Strategic Acquirers: Long-term, this sits as a specialty chemicals consolidation play because formulation complexity and REACH dossier requirements erect durable barriers. Acquire mid-scale zeolite synthesis houses with established refinery qualification records. Watch for inflection when Middle Eastern national oil companies centralize additive procurement across multiple FCC units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Captive lanthanum supply secures multi-year contracts with Middle Eastern refiners against Chinese quota volatility. |
| Long-term Supply Agreement with Performance Guarantees | Reliance Jamnagar and Indian Oil contracts bundle technical service with material supply, compressing supplier count. |
| Joint Venture for Localized Formulation | Gujarat and Odisha production partnerships reduce logistics costs and accelerate BIS qualification timelines. |
| Green Manufacturing Transition | REACH-compliant synthetic amorphous silica precursors extend dossier timelines but lock out unqualified competitors. |
| Technology Licensing for Resid Processing | Metal passivation expertise transfers to national oil companies building vacuum residue FCC capacity. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with refinery operations managers, catalyst procurement leads, and zeolite R&D directors; and secondary validation through customs trade data, SEC 10-K filings, and refinery capacity databases. Bottom-up unit economics triangulated against top-down market sizing across zeolite architecture segments.
Forecast inputs considered FCC unit capacity additions, crude slate heaviness trends, and petrochemical integration intensity across the projection horizon. Segmentation dimensions modeled include zeolite type, reactor configuration, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from capacity-weighted demand projections and additive consumption rates per barrel of feedstock processed.
Macroeconomic conditions sit as an overlay; deviation in refinery margin compression or rare earth export policy would shift the trajectory. Material shifts in China's dual carbon enforcement or India's BIS sulfur standard implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Zeolite Molecular Sieve Market
Catalysts
Environmental Catalysts Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Natural Zeolites Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market