
 Hydrodesulfurization Catalyst Market | 2026-2036
Hydrodesulfurization Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrodesulfurization Catalyst Market Analysis
A capital-intensity divergence between integrated catalyst manufacturers and specialty licensors is redrawing competitive boundaries in hydrodesulfurization catalyst supply. Albemarle Corporation leverages captive cobalt and molybdenum sourcing to sustain margin stability across volatile metal cycles. Johnson Matthey anchors its position through proprietary ACTIVE PRINCIPLE technology that dominates high-pressure residuum service. Criterion Catalysts & Technologies competes via extensive refiner technical service networks that extend unit lifecycle value.
Hydrodesulfurization catalysts are heterogeneous materials—typically cobalt-molybdenum (CoMo) or nickel-molybdenum (NiMo) oxides on alumina supports—engineered to cleave carbon-sulfur bonds in petroleum fractions at 300–400°C and 30–130 bar hydrogen pressure. Their primary purpose is reducing sulfur content in transportation fuels to meet environmental specifications while preserving hydrocarbon yield. NiMo formulations command premium positioning in severe hydrotreating of vacuum gas oils where nitrogen tolerance determines unit run length. CoMo catalysts occupy the high-volume diesel desulfurization segment where sulfur reduction targets approach ten parts per million. Noble metal variants lead in naphtha pretreatment for catalytic reforming, though their cost structure limits deployment scale.
The EPA's Tier 3 gasoline sulfur standards and the EU's Fuel Quality Directive enforce sub-ten ppm sulfur ceilings that mandate catalyst replacement at US and European refineries. China's MEE enforces national VI fuel standards that accelerate NiMo adoption for diesel hydrotreater revamps. India's BIS aligns automotive fuel norms with Euro 6 equivalents, creating procurement urgency at Reliance Jamnagar and Indian Oil Paradip. Stakeholders must monitor cobalt supply concentration in the Democratic Republic of Congo and evaluate catalyst regeneration economics against fresh load costs as metal prices fluctuate.
Market Dynamics
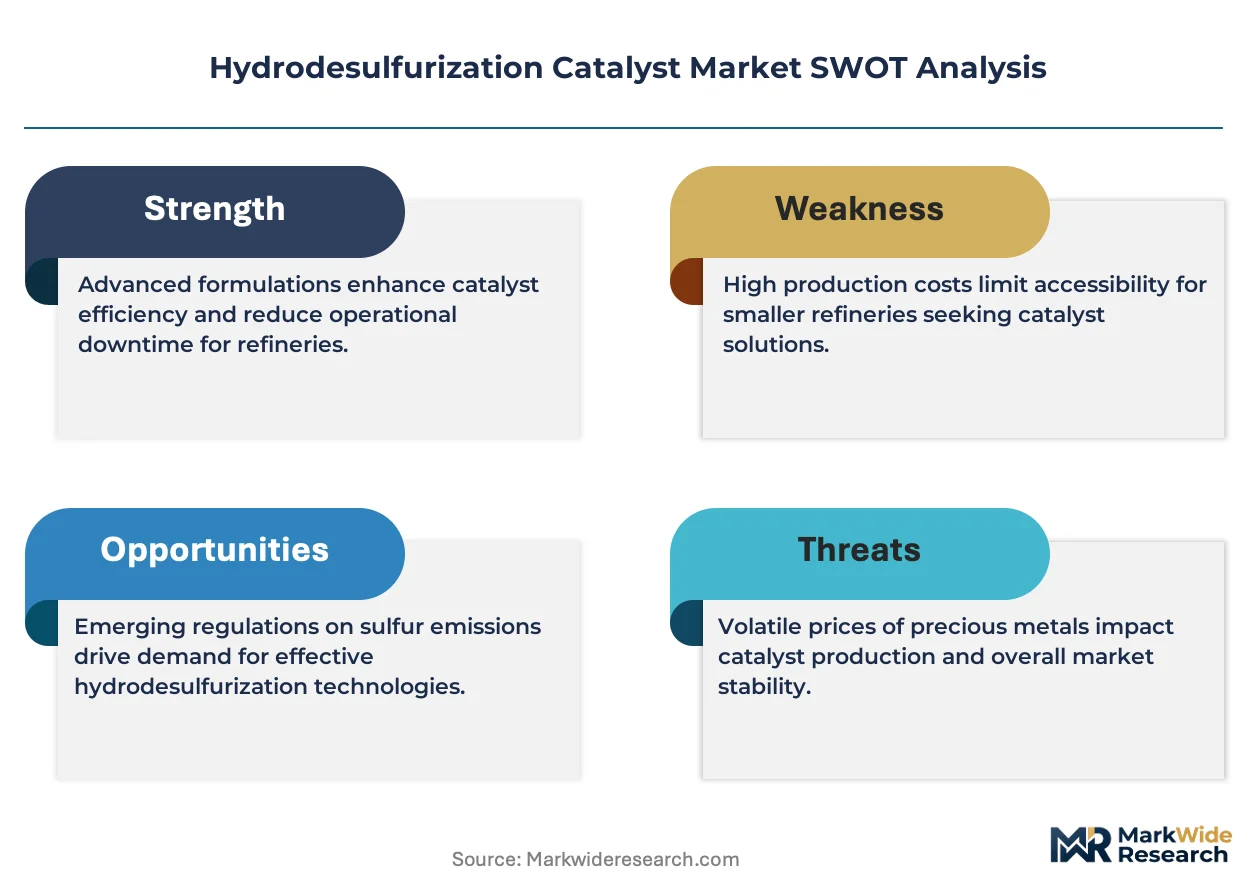
Refinery catalyst replacement cycles are compressing as sulfur specifications tighten across major fuel markets, forcing operators to prioritize high-activity NiMo formulations over legacy CoMo systems despite metal price volatility.
Growth Catalysts
- EPA Tier 3 gasoline standards:Sub-ten ppm sulfur mandates at US refineries accelerate fresh catalyst loading schedules and revamp project timelines.
- India's BIS Euro 6 alignment:Automotive fuel norm convergence triggers procurement urgency at Jamnagar and Paradip complex hydrotreaters.
- Residuum hydrotreating intensity:Heavy crude processing economics favor high-pressure units requiring premium NiMo catalysts with superior nitrogen tolerance.
Market Restraints
- Cobalt supply concentration:Democratic Republic of Congo dominance in cobalt ore creates geopolitical exposure for CoMo catalyst manufacturers.
- Platinum group metal cost structure:Noble metal catalysts for naphtha pretreatment face deployment limits due to palladium and platinum price volatility.
- Hydrogen infrastructure gaps:Hydrotreater revamps require parallel hydrogen production investment that delays project sanctioning in emerging markets.
Strategic Opportunities
- Saudi Arabia's Jazan and SATORP expansions:Greenfield refinery construction creates demand for initial catalyst loads and long-term technical service partnerships.
- Catalyst regeneration economics:Metal recovery and rejuvenation services offer margin expansion as cobalt and molybdenum prices fluctuate.
- Biofuel hydrotreating convergence:Renewable diesel and SAF production units require adapted catalyst formulations for oxygenated feedstocks.
Industry Challenges
- Specialized hydrotreating engineering talent:Deep process knowledge for high-pressure residuum service remains concentrated among a limited pool of licensors and refinery technical staff.
- Extended catalyst qualification timelines:Refiner validation protocols for new formulations stretch 18-36 months, delaying commercialization of improved active phase technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrodesulfurization Catalyst Market |
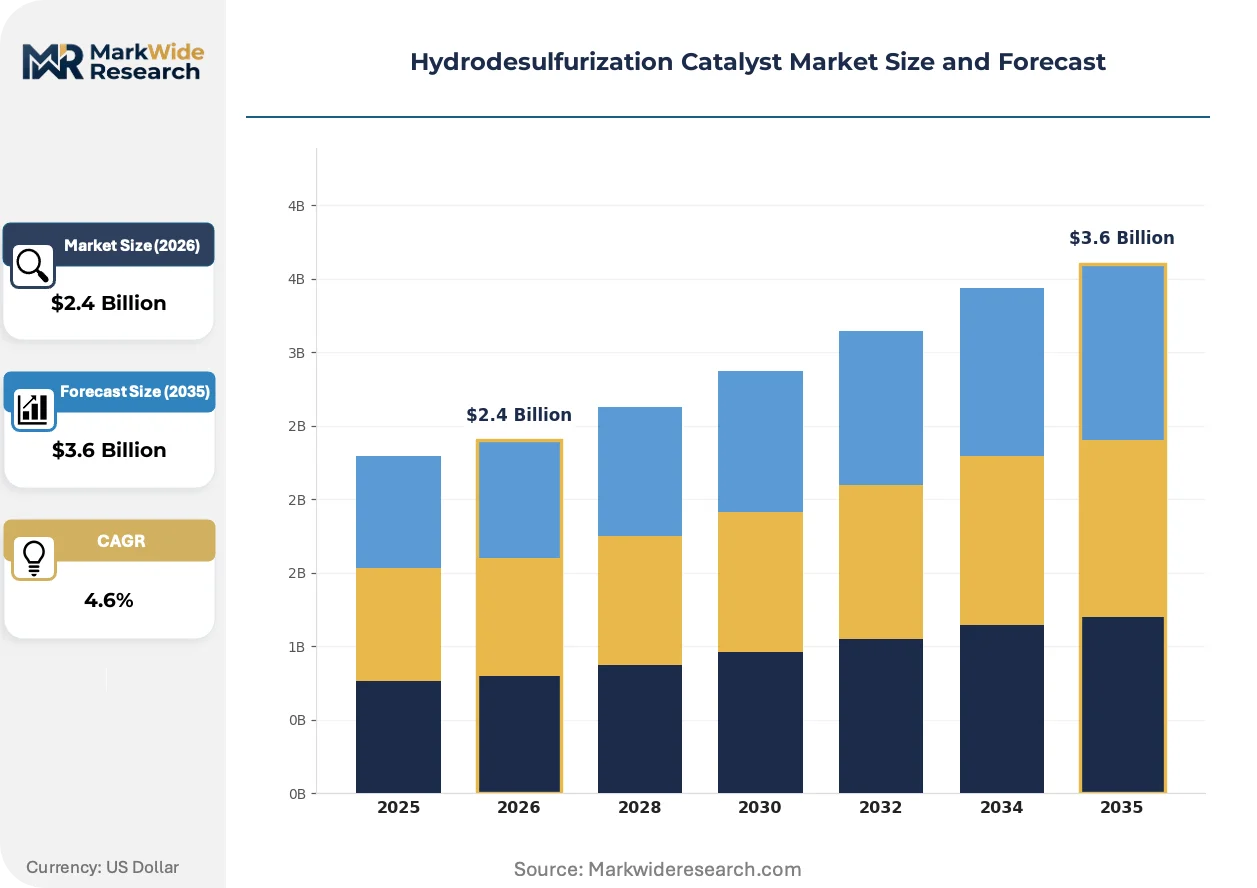
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.6 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CoMo, NiMo, Noble Metals, Others Form: Granular, Powder, Pellet, Others End User: Refineries, Petrochemical Plants, Chemical Manufacturers, Others Application: Environmental Compliance, Fuel Upgrading, Oil Refining, Others |
| Companies Covered | Criterion Catalysts & Technologies, Johnson Matthey, Advanced Refining Technologies, Axens, Haldor Topsoe, Albemarle Corporation, BASF SE, Clariant, Honeywell UOP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrodesulfurization Catalyst Market Emerging Trajectories
Catalyst architecture is evolving toward higher active metal dispersion and tailored pore structures that extend unit run length while meeting ultra-low sulfur targets. These advances are compressing replacement economics and reshaping supplier-refiner relationships.
Layered bed catalyst systems is miniaturizing reactor volume requirements while maintaining desulfurization depth. European refiners facing hydrogen constraints adopt these configurations to avoid costly revamp investments. The technology is compressing capital intensity for diesel hydrotreater upgrades in constrained sites.
China's MEE enforcement of national VI fuel standards is mandating NiMo dominance for diesel service across Sinopec and PetroChina complexes. Refiners accelerate revamp schedules to avoid compliance penalties. The policy shift is displacing legacy CoMo loads in medium-pressure units previously exempt from stringent sulfur targets.
Refiner procurement patterns now emphasize total lifecycle cost over initial catalyst price, unbundling technical service from material supply. Integrated licensors capture extended service contracts spanning 5-7 year operating cycles. This behavioral shift is most pronounced at Indian Oil and Reliance Industries, where run-length guarantees determine vendor selection.
Hydrodesulfurization Catalyst Market Segmentation
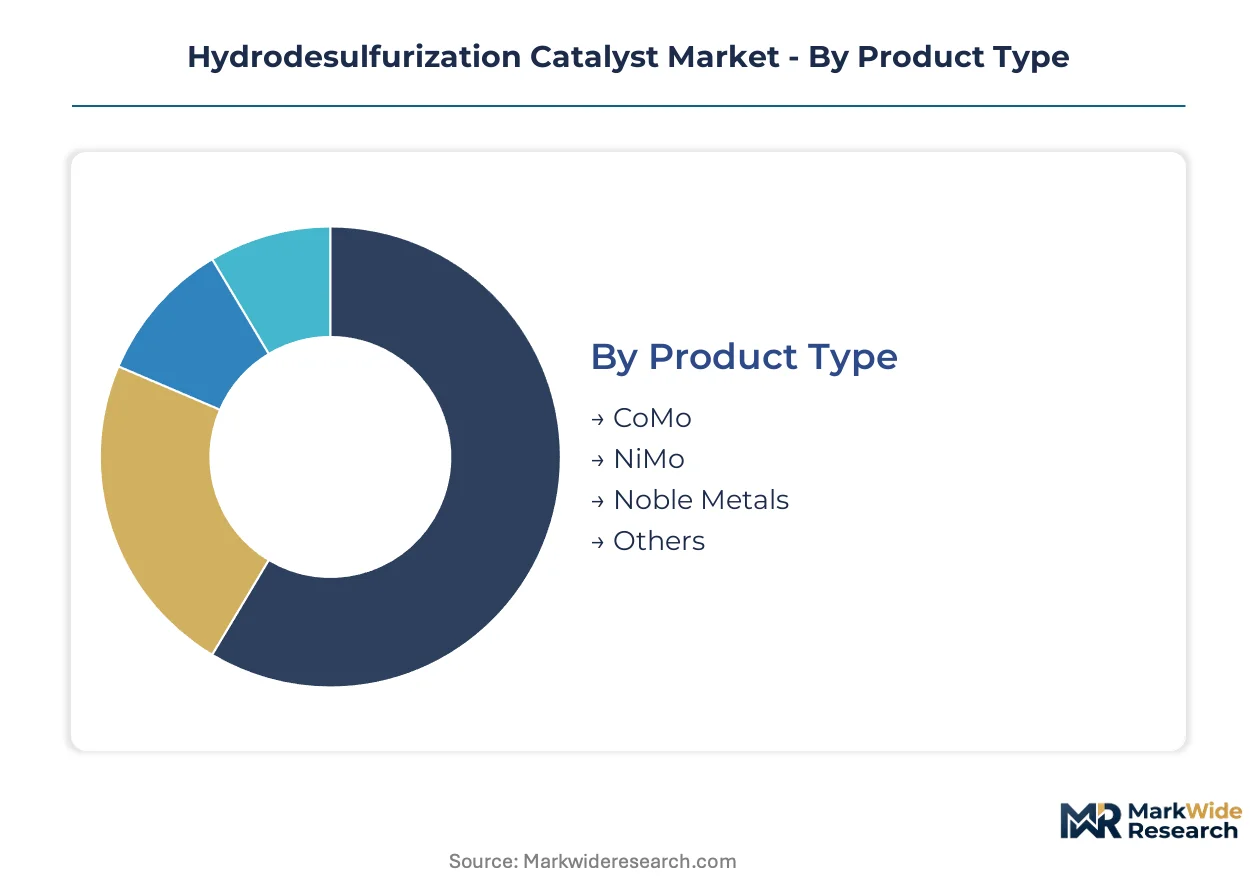
Hydrodesulfurization catalyst procurement flows through distinct technical-commercial channels. Product chemistry determines refiner specification protocols, while physical form shapes reactor loading logistics and regeneration economics.
Product Type:
Channel mix varies sharply by active metal chemistry, with integrated suppliers dominating CoMo and NiMo through captive raw material positions while noble metal formulations route through specialized distributors.
- CoMo:Cobalt-molybdenum oxides on alumina supports deliver sulfur reduction in diesel hydrotreaters targeting sub-ten ppm specifications. Demand concentrates at US Gulf Coast refineries modernizing for EPA Tier 3 compliance, with Albemarle Corporation and Criterion Catalysts capturing volume through technical service bundling.
- NiMo:Nickel-molybdenum formulations command premium positioning in severe hydrotreating of vacuum gas oils and residuum feeds where nitrogen tolerance extends unit run length. Indian refiners at Jamnagar and Paradip accelerate NiMo adoption as BIS Euro 6 alignment tightens diesel sulfur ceilings.
- Noble Metals:Palladium and platinum catalysts lead naphtha pretreatment for catalytic reforming units despite cost constraints from metal price volatility.
- Others:Emerging bimetallic and promoted formulations address biofuel hydrotreating for renewable diesel and SAF production.
By volume, CoMo leads. By growth pace, NiMo is ahead.
Form:
Physical configuration shapes reactor pressure drop, mass transfer efficiency, and catalyst regeneration viability across fixed-bed and ebullated-bed reactor designs.
- Granular:Irregular particle shapes optimize void fraction in high-pressure residuum service where pressure drop management determines throughput. European refiners facing hydrogen constraints adopt granular loads to minimize revamp capital.
- Pellet:Uniform cylindrical or spherical extrudates dominate diesel hydrotreater applications where consistent bed packing ensures even flow distribution. Chinese Sinopec and PetroChina complexes specify pelletized NiMo for national VI fuel standard compliance.
- Powder:Fine particle sizes serve slurry-phase and ebullated-bed hydrocracking configurations in heavy crude upgrading.
- Others:Specialized shapes including trilobe and quadrilobe extrudates address niche mass transfer requirements.
Pelletized forms dominate procurement tonnage. Granular configurations are expanding most quickly in residuum service.
End User:
Customer scale and technical sophistication fragment procurement patterns, with integrated refiners demanding lifecycle service contracts while smaller operators prioritize unit price.
- Refineries:Petroleum refining complexes account for the dominant share of catalyst consumption, with replacement cycles compressing as sulfur specifications tighten. Saudi Arabia's Jazan and SATORP greenfield projects create demand for initial loads and long-term technical partnerships.
- Petrochemical Plants:Steam cracker feed pretreatment and pyrolysis gasoline hydrotreating drive specialized catalyst requirements for olefin production.
- Chemical Manufacturers:Specialty chemical producers utilize hydrotreating for intermediate purification and sulfur removal from process streams.
- Others:Emerging biofuel producers and hydrogen generation facilities represent nascent demand segments.
Refinery procurement exceeds all other segments combined. Petrochemical applications are climbing the fastest on steam cracker capacity expansion.
Application:
Use-case priority determines performance specifications, with environmental compliance mandating maximum sulfur removal depth while fuel upgrading balances yield preservation against treatment severity.
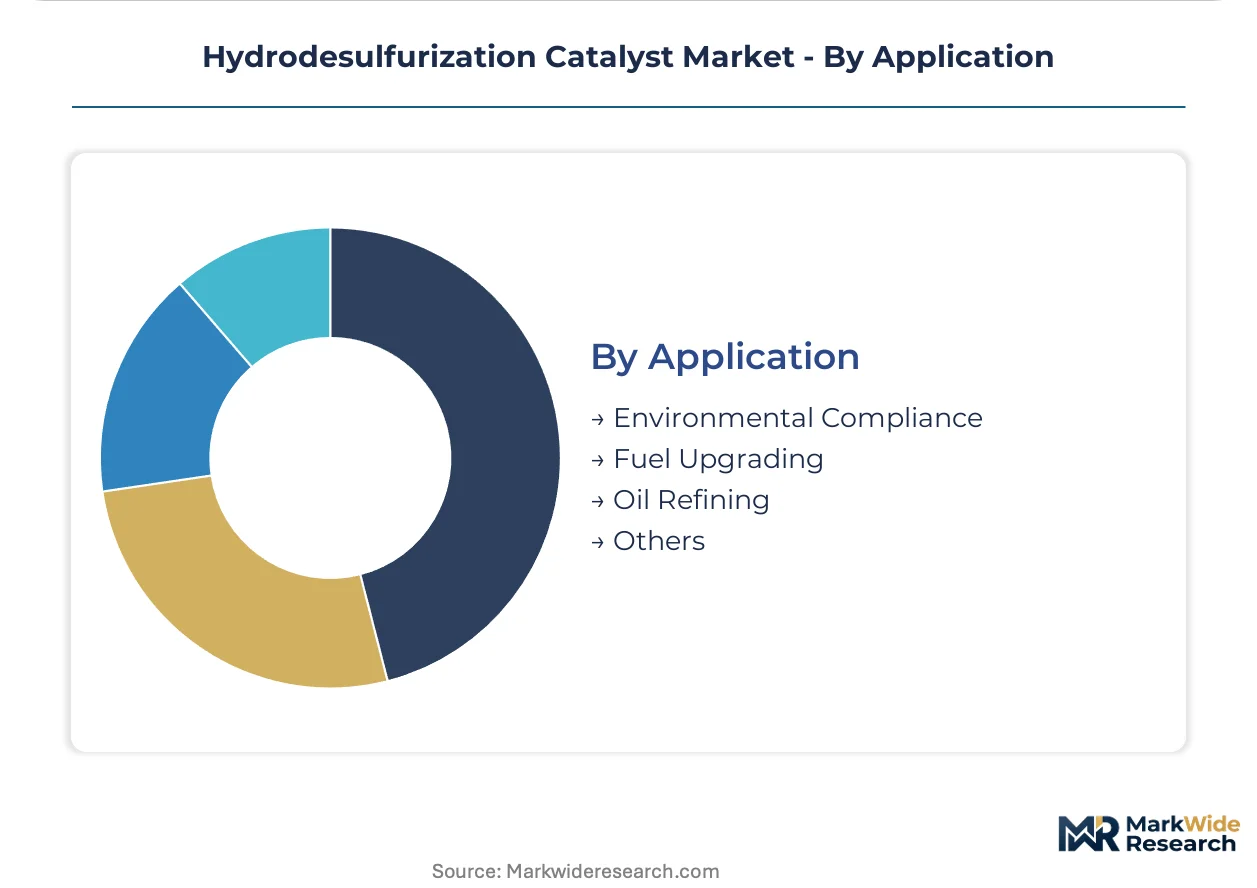
- Environmental Compliance:Regulatory-driven sulfur reduction to meet EPA Tier 3, EU Fuel Quality Directive, and China's MEE national VI standards forces catalyst replacement at compliance deadlines. Run-length guarantees determine vendor selection as penalties for non-compliance escalate.
- Fuel Upgrading:Quality improvement through hydrogen addition and heteroatom removal enables premium product positioning in transportation fuel markets. India's Reliance Industries and Indian Oil prioritize upgrading applications for export diesel competitiveness.
- Oil Refining:General hydrotreating operations encompassing feedstock preparation and intermediate processing.
- Others:Specialized applications including lube oil hydrotreating and wax upgrading.
Environmental compliance applications lead by procurement value. Fuel upgrading shows the steepest expansion trajectory on premium product margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian refiners exhibit the highest price elasticity as procurement teams negotiate run-length guarantees against fresh load costs, while Saudi greenfield projects prioritize technical service depth over unit economics. China's state-directed buyers accept premium NiMo pricing for compliance certainty. US Gulf Coast operators balance regeneration economics against spot metal prices.
United States
EPA Tier 3 gasoline standards mandate sub-ten ppm sulfur ceilings at Gulf Coast and Midwest refineries, compressing catalyst replacement cycles. The Environmental Protection Agency enforces compliance deadlines that trigger revamp procurement at Houston and Beaumont complexes. ExxonMobil Baytown and Marathon Galveston Bay accelerate high-activity NiMo loading schedules.
China
Sinopec and PetroChina complexes expand hydrocracking capacity to process heavier crude slates, driving NiMo demand for vacuum gas oil service. The Ministry of Ecology and Environment enforces national VI fuel standards that displace legacy CoMo formulations. Zhenhai and Maoming refineries complete diesel hydrotreater revamps ahead of compliance deadlines.
India
Reliance Industries and Indian Oil prioritize fuel upgrading investments for export diesel competitiveness, triggering procurement urgency at Jamnagar and Paradip. The Bureau of Indian Standards aligns automotive fuel norms with Euro 6 equivalents. Gujarat and Odisha coastal clusters concentrate hydrotreater expansion projects.
Saudi Arabia
Jazan and SATORP greenfield refineries create demand for initial catalyst loads and long-term technical partnerships in residuum hydrotreating. The Saudi Food and Drug Authority and national industrial regulators oversee chemical process safety standards. The Eastern Province refining corridor anchors premium NiMo adoption for high-pressure service.
Germany
European refiners facing hydrogen constraints adopt layered bed catalyst configurations to minimize revamp capital at constrained sites. The EU F-Gas Regulation and Fuel Quality Directive enforce sulfur ceilings that accelerate replacement schedules. The Rhine-Ruhr industrial cluster and Bavarian chemical complexes lead regeneration economics evaluation.
Hydrodesulfurization Catalyst Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated metal producers compete against specialized licensors. The market consolidates around three strategic groups: captive raw material owners, proprietary technology licensors, and technical service bundlers. M&A activity concentrates on metal recovery capabilities, while capacity expansion targets biofuel hydrotreating formulations.
Among integrated chemical conglomerates, BASF SE and Clariant occupy positions that exemplify scale-driven supply security, while Johnson Matthey represents the technology-licensor archetype with proprietary active phase expertise. Albemarle Corporation anchors the captive sourcing tier through backward integration into cobalt and molybdenum supply chains.
| Leading Market Players |
|---|
| Criterion Catalysts & Technologies |
| Johnson Matthey |
| Advanced Refining Technologies |
| Axens |
| Haldor Topsoe |
| Albemarle Corporation |
| BASF SE |
| Clariant |
| Honeywell UOP |
| Others |
Supply Flow & Price Mechanics
Long-term technical service contracts spanning 5-7 year operating cycles lock in both supply access and price visibility for refiners at Reliance Jamnagar and Indian Oil Paradip, insulating procurement teams from cobalt and molybdenum spot volatility while embedding catalyst regeneration economics into lifecycle agreements.
Pricing Analysis
After-sales technical service revenue drives lifetime value for integrated licensors, with run-length guarantees commanding premium positioning over standalone catalyst supply. Three-tier pricing structure across premium NiMo, standard CoMo, and economy regenerated loads separates procurement tiers by sulfur severity and unit pressure rating. Cost compression in standard CoMo grades is intensifying because Chinese state-directed buyers accept premium NiMo pricing for compliance certainty, forcing margin discipline on legacy formulations. Indian refiners exhibit the highest price elasticity, while Saudi greenfield projects prioritize technical service depth over unit economics.
Supply Chain Analysis
Inbound logistics costs from Antwerp and Rotterdam port congestion shape catalyst delivery timelines to European refiners facing hydrogen constraints, with container availability on Asia-Europe trade lanes determining revamp project scheduling. Manufacturing concentrates in the United States, Germany, and Japan, with cobalt feedstock anchored in the Democratic Republic of Congo. Active metal precursors draw from South Korean and Belgian chemical processors. Single-source vulnerability in cobalt ore creates geopolitical exposure. Distribution runs through refiner technical service networks that extend unit lifecycle value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrodesulfurization catalyst demand traces refinery capital cycles, with sulfur specification tightening driving replacement urgency as EPA Tier 3 and China's MEE national VI standards compress procurement timelines.
For Market Incumbents: Shield margin stability through captive cobalt and molybdenum sourcing positions, mirroring Albemarle Corporation's backward integration strategy. Deepen technical service bundling to lock out specialized licensors from 5-7 year operating contracts at Indian and Saudi complexes. Counter emerging biofuel hydrotreating entrants by accelerating oxygenated feedstock catalyst qualification timelines. For New Entrants and Emerging Players: Anchor in catalyst regeneration and metal recovery services where cobalt price volatility creates procurement urgency at US Gulf Coast refineries. Target biofuel hydrotreating formulations for renewable diesel and SAF production units, where adapted chemistry requirements remain underpenetrated by incumbent licensors. Lead with total lifecycle cost positioning against fresh load premiums. For Investors and Strategic Acquirers: Metal recovery and rejuvenation service providers with established refiner relationships represent the most defensible acquisition archetype, capturing margin expansion as cobalt and molybdenum prices fluctuate. Long-term viability hinges on hydrogen infrastructure buildout pace and heavy crude processing economics. Watch EPA enforcement intensity and China's dual carbon policy implementation as inflection indicators for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cobalt Supply | Captive ore positions insulate Albemarle from DRC geopolitical exposure and metal price cycles. |
| Long-term Technical Service Contracts | Run-length guarantees at Reliance Jamnagar lock out competitors across 5-7 year operating cycles. |
| Biofuel Hydrotreating Formulation Development | Oxygenated feedstock catalysts address renewable diesel and SAF production unit requirements. |
| Catalyst Regeneration Capacity Expansion | Metal recovery economics improve as cobalt prices fluctuate and fresh load premiums widen. |
| Joint Venture with Saudi Greenfield Refiners | Jazan and SATORP partnerships secure initial loads and embedded technical service revenue. |
Methodological Framework
A spread of perspectives from refinery process engineers, catalyst procurement managers, hydrocracker unit operators, and technical service directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings, refinery capacity databases, and catalyst supplier technical disclosures. Bottom-up unit-level modeling and top-down sector aggregation triangulated volume and value estimates.
Segmentation dimensions modeled span active metal chemistry, physical form, reactor configuration, application severity, and regional regulatory compliance tier across the projection horizon. CAGRs derive from replacement cycle compression rates, revamp project pipelines, and sulfur specification phase-in schedules. Industry-specific forecast inputs include hydrogen availability constraints, heavy crude slate shifts, and biofuel hydrotreating capacity announcements.
Underlying assumptions cover sustained EPA Tier 3 and China MEE enforcement, with deviation risk concentrated in cobalt supply disruptions and hydrogen infrastructure delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Biodiesel Catalyst Market
Catalysts
Steam Methane Reforming Market
Catalysts
North America Zeolite Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Inorganic Catalyst Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
Environmental Catalysts Market