
 Catalase Market | 2026-2036
Catalase Market Size, Share, and Industry Trends Forecast 2026-2036
Catalase Market Analysis
The Catalase Market is pivoting on a widening split between pharmaceutical-grade biocatalysts commanding stringent purity certifications and commodity-grade powders serving bulk industrial cleaning. Novozymes leverages its fermentation scale to dominate premium liquid formulations for food preservation. DuPont anchors North American supply through backward integration into proprietary strain development. BASF competes on cost-engineered powder grades for textile bleaching neutralization.
Catalase is a tetrameric heme-containing oxidoreductase enzyme that catalyzes hydrogen peroxide decomposition into water and oxygen, typically sourced via submerged fermentation of Aspergillus niger or bovine liver extraction with activity ratings spanning 2,000 to 500,000 units per milligram. Its primary industrial purpose centers on peroxide removal in food processing, cold bleaching systems, and diagnostic reagent stability. Liquid catalase formulations lead volume share in dairy and beverage applications where inline dosing integrates with existing CIP infrastructure. Powder catalase exhibits the fastest trajectory in emerging market textile hubs seeking peroxide-neutralization without thermal energy input. Fermentation technology underpins margin concentration, as genetically optimized host strains reduce downstream purification burden by half versus conventional extraction methods.
FDA enzyme preparation guidelines and EPA FIFRA registration requirements shape product specifications for US food and industrial applications, while REACH compliance in Europe mandates full toxicological dossiers for imported biocatalysts. EFSA positive opinions on food enzyme safety accelerate novel-source approvals, expanding supplier eligibility beyond traditional fermentation houses. Stakeholders must monitor CRISPR-edited strain regulatory classification, as gene-edited production organisms face divergent approval pathways across major jurisdictions.
Market Dynamics
Food processors are abandoning synthetic preservatives in favor of enzyme-based solutions, creating a bifurcation where fermentation-derived catalase commands premium positioning against legacy bovine liver extracts.
Growth Catalysts
- REACH Compliance:European purity mandates under ECHA regulations are disqualifying low-grade imports, consolidating demand around certified fermentation suppliers.
- Cold Bleaching Adoption:Textile hubs in Bangladesh and Vietnam are retrofitting peroxide-neutralization systems to eliminate thermal energy costs from finishing lines.
- Inline Dosing Infrastructure:Dairy processors are integrating liquid catalase into CIP loops, embedding recurring enzyme consumption into operational budgets.
Market Restraints
- Feedstock Volatility:Molasses and corn steep liquor prices swing with agricultural commodity cycles, compressing margins for fermentation-based producers.
- Strain IP Concentration:Proprietary Aspergillus niger host cell lines remain concentrated among three legacy suppliers, creating bottleneck risk for new entrants.
- Thermal Stability Limits:Catalase denaturation above 50°C restricts deployment in high-temperature industrial processes, ceding ground to chemical alternatives.
Strategic Opportunities
- India Food Processing:FSSAI enzyme approval pathways are shortening, opening formal market access for fermentation-grade catalase in dairy and bakery applications.
- Diagnostic Reagent Stability:Lyophilized catalase formats are penetrating point-of-care device supply chains as manufacturers seek extended shelf-life for hydrogen peroxide-based assays.
- CRISPR Strain Optimization:Gene-edited production organisms promise 40% yield improvements, though regulatory classification remains unresolved across FDA, EFSA, and NMPA jurisdictions.
Industry Challenges
- Downstream Purification Bottlenecks:Chromatography resin costs and skilled bioprocess engineering talent scarcity constrain capacity expansion timelines.
- Multi-Jurisdiction Dossier Burden:EFSA novel food enzyme approvals require 18-24 month toxicology studies, delaying revenue recognition for new fermentation sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catalase Market |
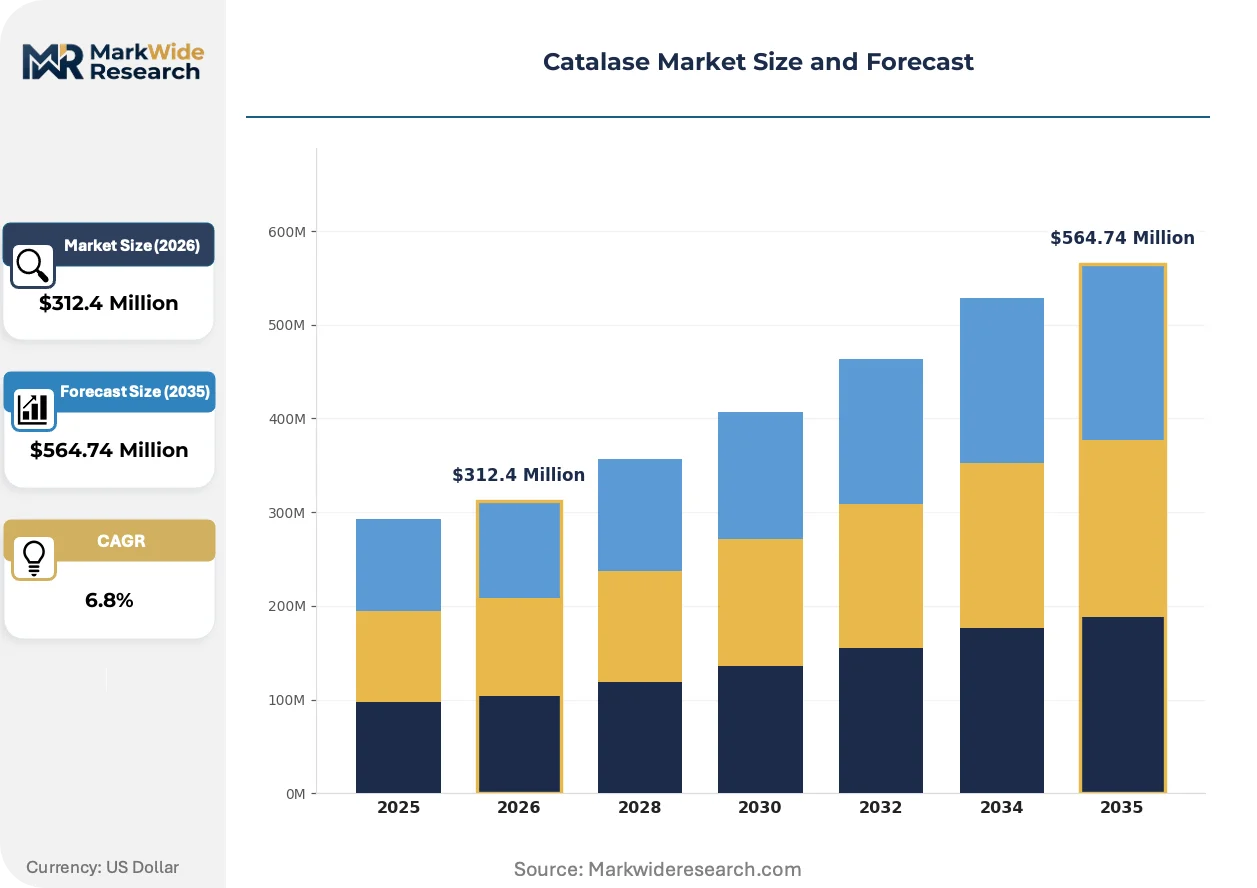
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Catalase, Powder Catalase, Enzyme Tablets, Catalase Solutions Application: Food Preservation, Pharmaceutical Manufacturing, Textile Processing, Industrial Cleaning End User: Food Industry, Pharmaceutical Companies, Cosmetics, Research Laboratories Technology: Fermentation Technology, Bioprocessing, Genetic Engineering, Bio-catalysis |
| Companies Covered | Novozymes, DuPont, BASF, Chr. Hansen, Amano Enzyme, Sigma-Aldrich Co. LLC, MP Biomedicals LLC, Biocatalysts Limited, DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catalase Market Emerging Trajectories
Bioprocess engineering is converging with synthetic biology to compress production economics, while regulatory frameworks scramble to classify gene-edited organisms alongside shifting procurement patterns in food manufacturing.
Continuous fermentation technology is decentralizing catalase production economics by enabling smaller-footprint facilities with real-time titer monitoring. Mid-scale dairy cooperatives in Wisconsin and Bavaria are piloting skid-mounted bioreactors to captive-produce liquid formulations. This distributed manufacturing model is compressing freight costs and cold-chain dependencies that historically favored centralized mega-facilities.
EFSA's 2023 updated guidance on food enzyme allergenicity assessment is extending safety study requirements for novel microbial sources. Fermentation houses must now submit extended clinical datasets, raising entry barriers for second-tier suppliers. The diagnostic reagent segment faces the steepest compliance burden, as dual-use classification triggers parallel medical device scrutiny under MDR.
Ingredient buyers are consolidating supplier rosters from six-plus vendors to two strategic partnerships with guaranteed volume allocations. This concentration pattern is most visible among multinational beverage conglomerates operating in Brazil and Mexico, where procurement teams now prioritize fermentation traceability and carbon footprint disclosure over unit cost minimization.
Catalase Market Segmentation
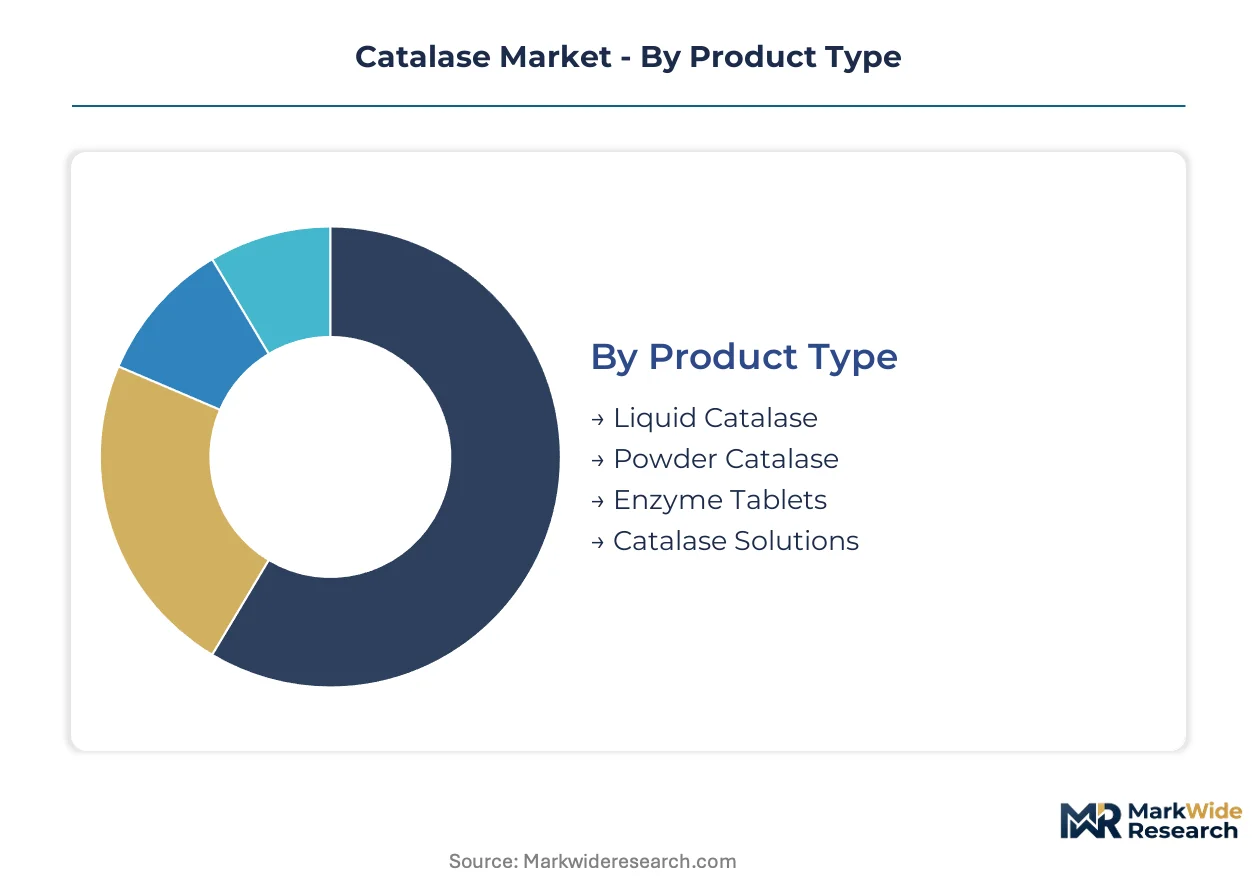
Catalase procurement patterns diverge sharply across formulation types and end-use specifications. Food processors prioritize liquid formats compatible with existing CIP infrastructure, while textile manufacturers drive powder demand for cold-bleaching neutralization.
Product Type:
Upgrade cycles in dairy and beverage processing are accelerating replacement of legacy bovine extracts with fermentation-derived alternatives that integrate with automated dosing systems.
- Liquid Catalase:Aqueous formulations with standardized activity units enable precise inline metering during milk pasteurization and juice processing. Dairy cooperatives in Wisconsin and Bavaria favor liquid formats for seamless CIP loop integration. Volume placements concentrate in liquid catalase; the faster expansion belongs to powder catalase.
- Powder Catalase:Lyophilized or spray-dried preparations offer extended shelf stability and reduced freight costs for textile hubs in Bangladesh and Vietnam retrofitting peroxide-neutralization systems. Cold-bleaching adoption eliminates thermal energy inputs from finishing lines.
- Enzyme Tablets:Solid-dose formats target small-scale bakeries and craft breweries requiring measured enzyme addition without liquid handling infrastructure.
- Catalase Solutions:Pre-diluted, buffer-stabilized preparations serve diagnostic reagent manufacturers seeking lot-to-lot consistency for hydrogen peroxide-based assays.
Margin structures favor liquid formulations in developed markets; powder grades capture emerging market volume through cost-engineered positioning.
Application:
Cost tier stratification separates premium pharmaceutical-grade biocatalysts from commodity industrial cleaners, with food preservation commanding intermediate pricing.
- Food Preservation:Peroxide removal in cheese manufacturing and beverage stabilization drives the largest application volume. FDA enzyme preparation guidelines and EFSA positive opinions on food enzyme safety shape supplier eligibility for dairy processors seeking cleaner label positioning.
- Textile Processing:Cold bleaching neutralization in Bangladesh and Vietnam textile hubs represents the steepest expansion trajectory as manufacturers eliminate thermal energy costs from finishing operations.
- Pharmaceutical Manufacturing:Diagnostic reagent stability applications require lyophilized formats with extended shelf-life for point-of-care device supply chains.
- Industrial Cleaning:Bulk peroxide decomposition in equipment sanitation programs competes on cost against chemical alternatives, with thermal stability limits restricting high-temperature deployment.
Food preservation anchors current procurement volumes; textile processing gains share fastest through cold-bleaching retrofit programs.
End User:
Customer type determines specification stringency, with pharmaceutical and food sectors demanding full toxicological dossiers that commodity industrial buyers bypass.
- Food Industry:Multinational beverage conglomerates in Brazil and Mexico consolidate supplier rosters to two strategic partnerships prioritizing fermentation traceability and carbon footprint disclosure over unit cost minimization.
- Pharmaceutical Companies:Dual-use classification triggers parallel medical device scrutiny under MDR for diagnostic reagent applications, extending compliance timelines.
- Cosmetics:Peroxide-neutralization in hair coloring formulations and skin care products requires cosmetic-grade purity certifications with allergenicity assessments.
- Research Laboratories:Small-volume, high-specific-activity preparations serve academic and contract research organizations with fragmented purchasing patterns.
The food industry dominates procurement scale; pharmaceutical companies impose the steepest qualification barriers.
Technology:
Supply concentration in proprietary Aspergillus niger host cell lines creates bottleneck risk, with genetic engineering approaches promising yield improvements pending regulatory classification resolution.
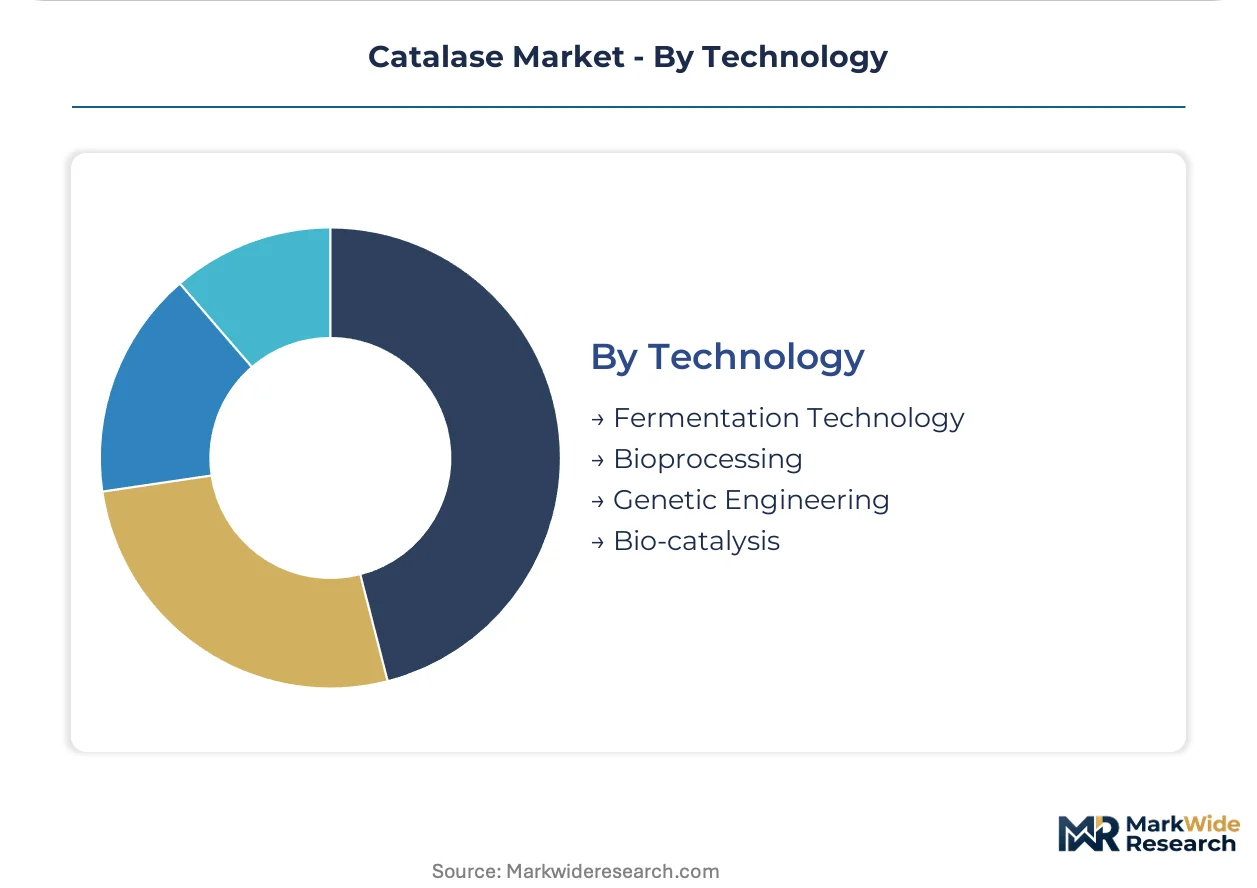
- Fermentation Technology:Submerged cultivation of optimized microbial strains underpins commercial-scale production, with genetically optimized hosts reducing downstream purification burden versus conventional extraction. Molasses and corn steep liquor feedstock costs swing with agricultural commodity cycles.
- Genetic Engineering:CRISPR-edited production organisms promise substantial yield improvements, though FDA, EFSA, and NMPA jurisdictions apply divergent approval pathways for gene-edited strains.
- Bioprocessing:Continuous fermentation technology enables smaller-footprint facilities with real-time titer monitoring, compressing freight costs and cold-chain dependencies.
- Bio-catalysis:Immobilized enzyme systems and flow chemistry integration target pharmaceutical intermediate manufacturing with reusability economics.
Fermentation technology captures installed capacity; genetic engineering approaches climb fastest pending regulatory clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors global catalase manufacturing scale, hosting fermentation facilities supplying dairy processors across Asia-Pacific and textile neutralization systems throughout Southeast Asia.
China
Domestic enzyme manufacturing scales rapidly in Jiangsu and Shandong provinces, displacing imported fermentation grades. NMPA novel food enzyme approvals accelerate local strain registrations. Zhengzhou textile clusters retrofit cold-bleaching systems with peroxide-neutralization capacity.
United States
Dairy cooperatives in Wisconsin integrate liquid catalase into CIP infrastructure, embedding recurring enzyme consumption. FDA enzyme preparation guidelines shape supplier qualification for cheese manufacturing. Boston-area diagnostic reagent manufacturers demand lyophilized formats for point-of-care device stability.
Germany
Bavarian dairy processors pilot continuous fermentation skids for captive liquid catalase production. REACH compliance under ECHA regulations disqualifies low-grade imports, consolidating demand around certified fermentation suppliers. Frankfurt chemical distributors manage powder-grade inventory for textile bleaching neutralization.
India
FSSAI enzyme approval pathways shorten for fermentation-grade catalase in dairy and bakery applications. Maharashtra food processors abandon synthetic preservatives for cleaner-label enzyme solutions. Gujarat textile hubs expand cold-bleaching retrofit programs to eliminate thermal energy costs.
Brazil
Multinational beverage conglomerates consolidate supplier rosters to two strategic partnerships prioritizing fermentation traceability. ANVISA biocatalyst registration requirements extend qualification timelines for novel microbial sources. São Paulo dairy clusters scale inline dosing infrastructure for peroxide removal in cheese manufacturing.
Catalase Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with fermentation-derived liquid formulations commanding price multiples over bovine liver extracts. Three legacy suppliers concentrate proprietary Aspergillus niger host cell lines, creating bottleneck risk for capacity expansion. The vendor base stratifies into fermentation-scale specialists, extraction-based traditionalists, and regional powder-grade fabricators. Dominant competitive moves include backward integration into strain development and geographic footprint expansion through distribution partnerships.
Within the fermentation-scale tier, Novozymes and DuPont exemplify premium-positioned players leveraging captive strain libraries. BASF occupies a position on the cost-engineered powder-grade vector for industrial applications. Japanese specialists including Amano Enzyme represent the mid-tier bridge between pharmaceutical-grade purity and commodity-scale supply.
| Leading Market Players |
|---|
| Novozymes |
| DuPont |
| BASF |
| Chr. Hansen |
| Amano Enzyme |
| Sigma-Aldrich Co. LLC |
| MP Biomedicals LLC |
| Biocatalysts Limited |
| DSM |
| Others |
Supply Flow & Price Mechanics
Multinational beverage conglomerates in Brazil and Mexico anchor procurement volumes, forcing suppliers toward long-term contract structures with fermentation traceability premiums embedded in unit economics.
Pricing Analysis
Value-based pricing anchored to peroxide removal throughput dominates liquid catalase placements in dairy CIP loops. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications separates premium fermentation-derived formulations from commodity bovine extracts. Cost compression in powder grades is intensifying because Bangladesh and Vietnam textile hubs prioritize thermal energy savings over enzyme purity. Industrial cleaning buyers exhibit highest price sensitivity; diagnostic reagent manufacturers accept steepest premiums for lot-to-lot consistency guarantees.
Supply Chain Analysis
Single-source vulnerability sits with proprietary Aspergillus niger host cell lines concentrated among three legacy fermentation houses. Commercial-scale production draws from China, Denmark, and Germany, with Jiangsu and Shandong provinces scaling fastest. Molasses and corn steep liquor feedstock costs swing with agricultural commodity cycles, creating margin volatility. Distribution runs through Frankfurt chemical distributors for European powder-grade inventory and direct technical service relationships for liquid formulation accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into strain development and captive bioprocessing capacity defines competitive positioning, with fermentation-scale specialists racing to secure proprietary host cell libraries before regulatory pathways for gene-edited organisms stabilize.
For Market Incumbents: Lock in proprietary Aspergillus niger strain libraries through exclusive licensing or acquisition of specialized fermentation houses. Expand captive production capacity in Wisconsin and Bavaria dairy clusters before continuous fermentation skids commoditize regional supply. CRISPR-edited strain regulatory uncertainty threatens to obsolete conventional host line advantages if FDA, EFSA, and NMPA classifications diverge sharply. For New Entrants and Emerging Players: Begin with powder-grade positioning for Gujarat and Maharashtra textile hubs where cold-bleaching retrofit programs outpace supplier qualification timelines. FSSAI approval pathway acceleration creates formal market access for fermentation-grade catalase in Indian dairy and bakery applications previously served by synthetic preservatives. Technical partnership with established Frankfurt or São Paulo distributors bypasses direct selling infrastructure requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier fermentation houses with validated EFSA dossiers but constrained working capital in Germany and India. Five-to-ten year viability hinges on regulatory clarity for gene-edited production organisms and downstream purification capacity scarcity. Monitor EFSA novel food enzyme approval timelines as inflection signal for second-tier supplier consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive Aspergillus niger libraries eliminate royalty burdens to legacy fermentation houses. |
| Continuous Fermentation Scale-Up | Skid-mounted bioreactors in Wisconsin and Bavaria compress freight costs and cold-chain dependencies. |
| EFSA Novel Food Enzyme Dossier Investment | Extended toxicology datasets raise entry barriers against unvalidated imports under REACH compliance. |
| Diagnostic Reagent Lyophilization Partnership | Point-of-care device manufacturers demand extended shelf-life formats with MDR dual-use classification. |
| India FSSAI Registration Acceleration | Shortened approval pathways open formal market access for fermentation-grade dairy applications. |
Methodological Framework
Document review covered EFSA positive opinions, FDA enzyme preparation guidelines, and REACH compliance dossiers, complemented by interviews with fermentation process engineers, dairy cooperative procurement managers, textile bleaching technical directors, and diagnostic reagent quality assurance leads. Secondary validation drew from customs trade data, SEC 10-K filings of listed enzyme manufacturers, and NMPA novel food enzyme registration databases. Bottom-up volume estimates triangulated against top-down market sizing across formulation types and end-use specifications.
Segment-level outputs reflect modeling across liquid, powder, tablet, and solution formats; food preservation, textile processing, pharmaceutical manufacturing, and industrial cleaning applications; and fermentation, genetic engineering, bioprocessing, and bio-catalysis technology tiers. CAGRs were derived from elasticity-adjusted demand curves incorporating cold-bleaching adoption rates in Bangladesh and Vietnam, inline dosing infrastructure penetration in dairy cooperatives, and lyophilized format uptake in point-of-care diagnostics.
Underlying measurement precision varies by segment; liquid catalase placements in established dairy CIP infrastructure carry tighter precision than emerging powder-grade textile neutralization forecasts. Projections reflect assumptions around regulatory classification timelines for CRISPR-edited strains, molasses feedstock cost trajectories, and EFSA allergenicity assessment completion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Photocatalyst Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Natural Zeolites Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
North America Zeolite Market