
 Residue Hydrodesulphurization Catalyst Market | 2026-2036
Residue Hydrodesulphurization Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Residue Hydrodesulphurization Catalyst Market Analytics
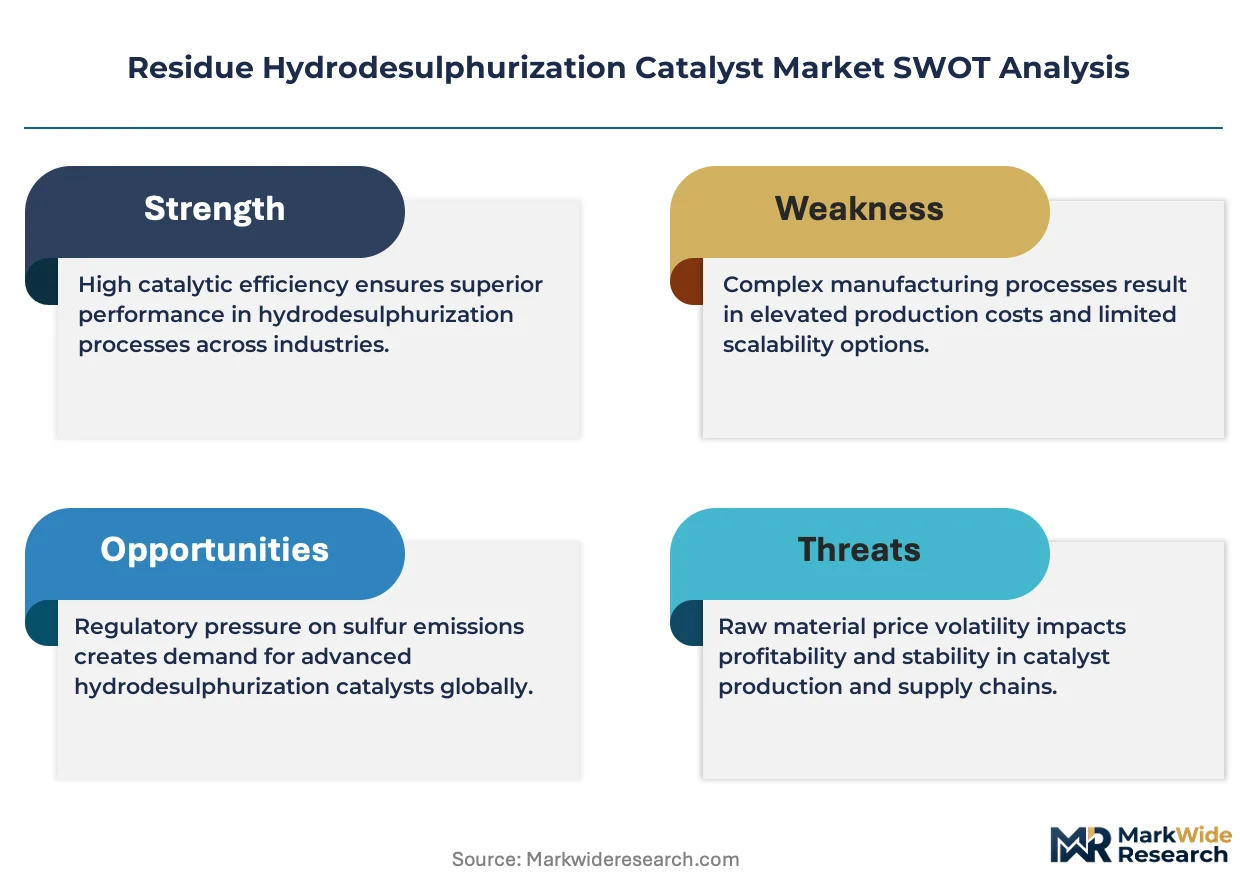
The International Maritime Organization's sulfur cap is shifting demand toward deeper hydrodesulfurization capability in residue processing units. Albemarle Corporation leverages its integrated catalyst manufacturing footprint to supply refiners seeking higher activity formulations. Haldor Topsoe A/S anchors its position through proprietary active metal distributions optimized for heavy feedstocks. Johnson Matthey PLC competes on advanced support materials that extend catalyst cycle lengths in high-severity operations.
Residue hydrodesulphurization catalysts are heterogeneous materials typically comprising cobalt-molybdenum or nickel-molybdenum active phases on alumina supports, designed to remove sulfur, nitrogen, and metals from vacuum residue and heavy atmospheric residue under hydrogen pressure at temperatures between 340°C and 420°C. Their primary purpose is enabling refineries to convert high-sulfur, high-metals feedstocks into cleaner transportation fuels and compliant fuel oil while protecting downstream units from contaminant poisoning. Advanced catalyst formulations with tailored pore architectures capture expanding share as refiners process increasingly heavy and opportunity crudes, while conventional catalysts retain volume leadership in mature markets where feedstock quality remains relatively stable. Fixed bed technology dominates installed capacity, though trickle bed configurations gain traction for revamps where pressure drop and liquid distribution improvements justify capital expenditure.
The US Environmental Protection Agency enforces Tier 3 gasoline sulfur standards that cascade into residue upgrading investments, while the EU F-Gas Regulation and REACH framework constrain catalyst precursor supply chains entering European refineries. China's Ministry of Ecology and Environment applies dual carbon goals that tighten emission benchmarks for refining operations, directly influencing catalyst selection criteria around energy efficiency and hydrogen consumption. Stakeholders must monitor regulatory divergence between sulfur specifications in marine bunker hubs and transportation fuel markets, as this tension determines whether refiners prioritize maximum conversion or selective desulfurization in residue unit design.
Market Dynamics
The International Maritime Organization's sulfur cap has created a permanent structural pull toward deeper desulfurization capability, forcing refiners to upgrade residue processing units regardless of crude price cycles. This regulatory compression is reshaping catalyst specifications across the value chain.
Growth Catalysts
- IMO 2020 Sulfur Cap:Marine fuel sulfur limits at 0.5% weight mandate residue upgrading investments at coastal refineries in Singapore, Rotterdam, and Houston. Refiners retrofit vacuum residue units to produce compliant very low sulfur fuel oil.
- China's Dual Carbon Goals:The Ministry of Ecology and Environment tightens emission benchmarks for refining clusters in Shandong and Guangdong. State-owned processors select catalysts with lower hydrogen consumption per barrel processed.
- Opportunity Crude Processing:Heavy, high-metals feedstocks from Venezuela, Canada, and Russia require advanced pore-architecture catalysts. Refiners in India and the Middle East expand residue conversion capacity to capture discounted heavy crude differentials.
Market Restraints
- Cobalt and Molybdenum Price Volatility:Active metal precursors face supply concentration from the Democratic Republic of Congo and Chile. Catalyst manufacturers absorb margin compression when metal prices spike without pass-through mechanisms.
- European Precursor Constraints:The EU REACH framework and F-Gas Regulation restrict import pathways for catalyst raw materials. Refineries in Rotterdam and Antwerp face extended qualification timelines for non-European catalyst suppliers.
- Hydrogen Supply Bottlenecks:Residue hydrodesulphurization consumes 1,000-1,500 standard cubic feet per barrel. Regions lacking hydrogen infrastructure—particularly Southeast Asia and Latin America—limit unit utilization rates regardless of catalyst performance.
Strategic Opportunities
- India's Residue Upcoming Wave:Reliance Industries and Indian Oil Corporation expand coker-hydrotreater complexes on the west coast. Domestic catalyst demand will outpace local manufacturing capacity through 2030.
- Renewable Diesel Co-Processing:Refiners blend vegetable oils and animal fats with vacuum residue in hydroprocessing units. Catalyst formulations tolerant of oxygenated feedstocks command premium positioning in North American and European markets.
- Carbon Border Adjustment Mechanism:The EU CBAM phases in embodied carbon reporting for imported refined products. Catalyst suppliers offering lifecycle-certified, lower-carbon manufacturing processes gain preferential access to European refineries.
Industry Challenges
- Catalyst Regeneration Skill Shortage:Specialized technicians for ex-situ regeneration of spent residue HDS catalysts are concentrated at Albemarle's Rotterdam facility and a handful of US Gulf Coast service providers. Refiners in emerging markets face 8-12 week turnaround delays.
- Fixed-Bed Revamp Complexity:Trickle bed retrofits require pressure vessel re-rating and distributor replacement. Engineering procurement construction contractors with residue unit experience are booked 18-24 months in advance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residue Hydrodesulphurization Catalyst Market |
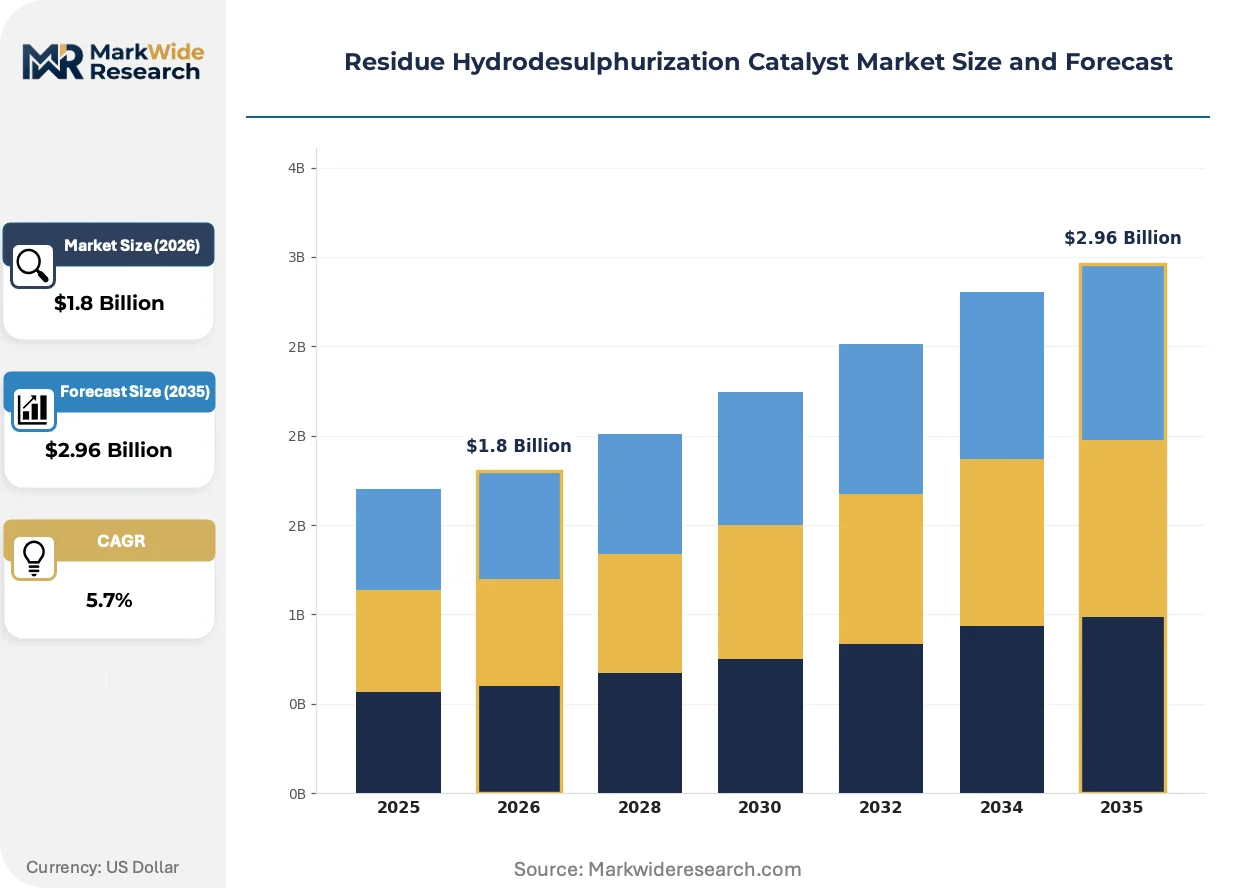
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Catalysts, Advanced Catalysts, Hybrid Catalysts, Specialty Catalysts End User: Refineries, Petrochemical Plants, Chemical Manufacturers, Others Technology: Fixed Bed, Fluidized Bed, Moving Bed, Trickle Bed Application: Transportation Fuels, Heating Oils, Chemical Feedstocks, Marine Fuels |
| Companies Covered | Albemarle Corporation, Haldor Topsoe A/S, Johnson Matthey PLC, Axens SA, Advanced Refining Technologies, Clariant AG, Honeywell UOP, CRI Catalyst Leuna GmbH, Redkino Catalyst Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residue Hydrodesulphurization Catalyst Market Evolving Landscape
Refinery catalyst technology is bifurcating between maximum-activity formulations for severe service and extended-cycle products for stable feedstock environments. This split is driving R&D investment toward application-specific architectures rather than universal solutions.
Tailored pore-structure catalysts with multimodal distributions—combining macropores for asphaltene diffusion and mesopores for sulfur accessibility—are expanding into high-severity residue service. Complex refiners on the US Gulf Coast and in the Netherlands deploy these formulations to process 6+ weight percent sulfur vacuum residue. The technology is expanding into opportunity crude processing, enabling refiners to run discounted heavy barrels without premature catalyst deactivation from metals deposition.
The US Environmental Protection Agency enforces Tier 3 gasoline sulfur standards that cascade into residue unit investment decisions. Refiners must produce FCC feedstock below 500 parts per million sulfur to meet finished gasoline pools. West Coast and Northeast refineries face the tightest constraints, accelerating catalyst replacement cycles to maintain FCC pretreater performance.
Refiners are unbundling catalyst supply from technical service contracts, reversing decades of bundled procurement. National oil companies in Saudi Arabia and Kuwait now separate catalyst procurement from process licensing, enabling direct negotiation with catalyst manufacturers. This pattern is most visible in the Middle East, where Saudi Aramco and Kuwait Petroleum Corporation have established independent catalyst qualification programs outside traditional licensor channels.
Residue Hydrodesulphurization Catalyst Market Segmentation
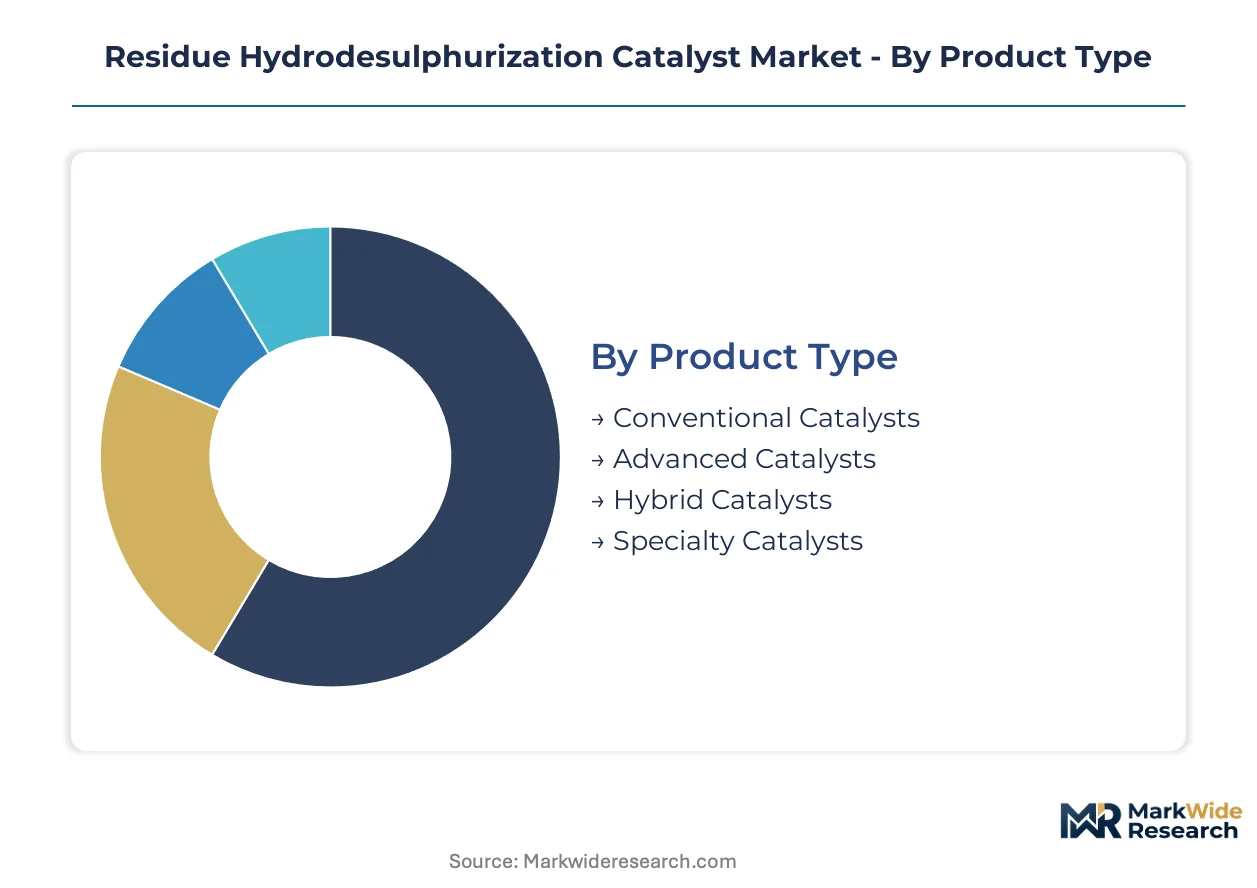
Refinery operators select catalyst formulations based on feedstock severity, unit configuration, and regulatory compliance requirements. Segmentation reveals how technology choices cascade through procurement budgets and operational performance metrics.
Product Type:
Standalone catalyst purchases dominate procurement in merchant markets, while integrated refinery-catalyst relationships embed formulations into long-term technical service agreements.
- Conventional Catalysts:Cobalt-molybdenum and nickel-molybdenum formulations on gamma-alumina supports with unimodal pore distributions. Demand concentrates in mature North American and European refineries processing relatively stable medium-sulfur crudes where cycle length predictability outweighs activity maximization.
- Advanced Catalysts:Multimodal pore architectures with tailored macropore-mesopore combinations enable diffusion of heavy asphaltenes and metals. Complex refineries on the US Gulf Coast and in Rotterdam deploy these for vacuum residue exceeding 5 weight percent sulfur, driven by the IMO 2020 sulfur cap compliance requirements.
- Hybrid Catalysts:Layered bed configurations combining conventional and advanced zones optimize capital efficiency in revamp scenarios.
- Specialty Catalysts:Custom formulations for specific contaminant profiles or co-processing applications with renewable feedstocks.
Conventional catalysts lead volumes today; advanced catalysts are gaining share fastest.
End User:
Customer concentration varies sharply between state-controlled refining clusters and independent merchant processors.
- Refineries:Petroleum refineries operating vacuum residue hydrodesulphurization units represent the dominant consumption channel. National oil companies in Saudi Arabia, Kuwait, and China account for disproportionate procurement volumes through centralized tender processes.
- Petrochemical Plants:Integrated petrochemical complexes purchase catalysts for residue conversion to aromatics feedstocks.
- Chemical Manufacturers:Specialty chemical producers utilize residue HDS for sulfur reduction in process intermediates.
- Others:Research institutions and pilot plant operators constitute minimal commercial volume.
Refineries dominate absolute consumption; petrochemical plants show the steepest expansion trajectory.
Technology:
Reactor configuration selection locks in catalyst morphology requirements and determines pressure drop tolerance.
- Fixed Bed:Downflow packed-bed reactors with structured catalyst pellets constitute the installed base majority. Refineries in India and the Middle East specify these for new residue unit construction, constrained by limited domestic engineering capacity for alternative configurations.
- Fluidized Bed:Ebullating bed systems enable online catalyst replacement for extreme metals tolerance.
- Moving Bed:Continuous catalyst circulation permits constant activity maintenance in high-severity service.
- Trickle Bed:Advanced liquid distribution systems reduce pressure drop and improve wetting efficiency. North American and European revamp projects specify these for capacity expansion within existing pressure vessel envelopes.
Fixed bed technology anchors installed capacity; trickle bed configurations climb the fastest in new project specifications.
Application:
Product slate requirements dictate desulfurization depth and hydrogen consumption intensity.
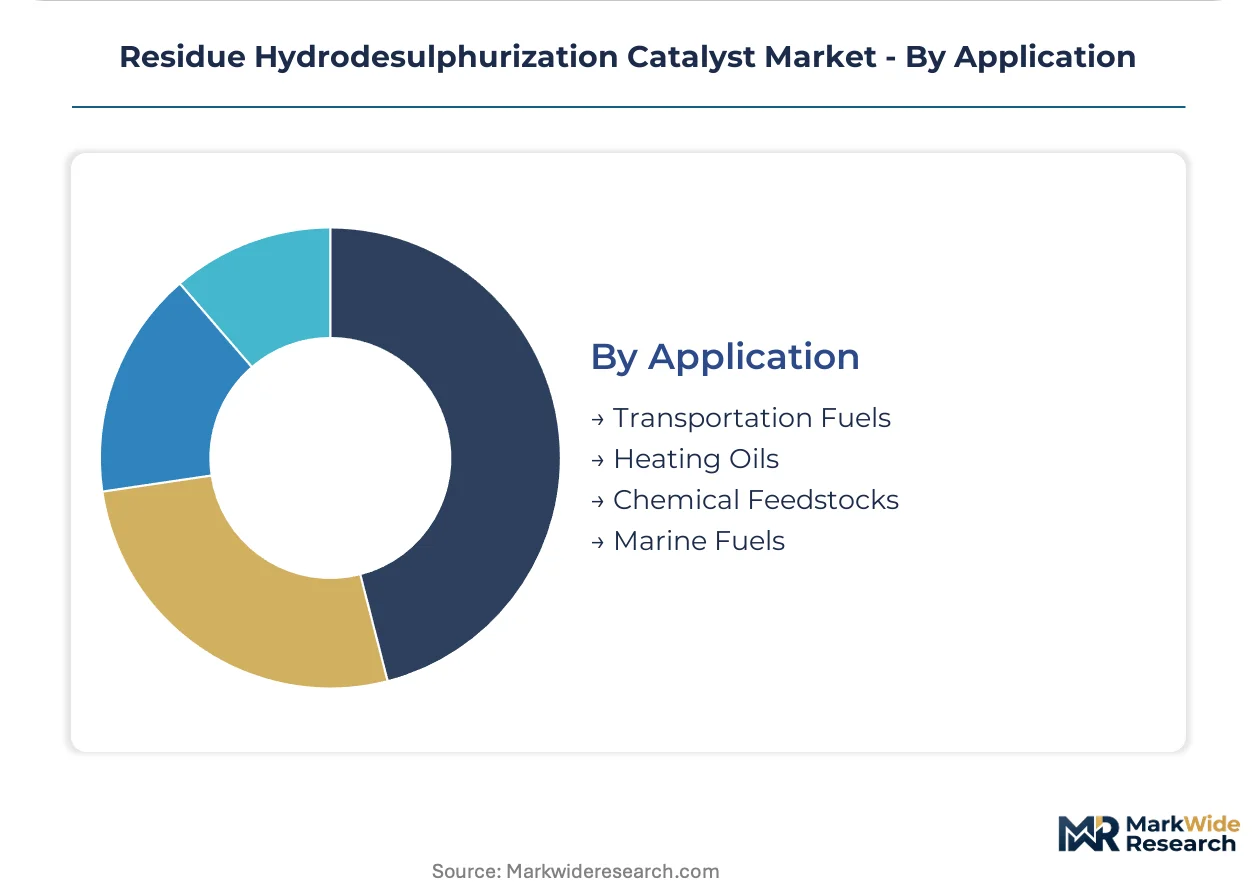
- Transportation Fuels:Gasoline and diesel pool compliance drives sulfur reduction to below 10 parts per million in FCC feed pretreatment. US West Coast refineries face the tightest EPA Tier 3 constraints, accelerating catalyst replacement cycles.
- Heating Oils:Residential and industrial fuel oil specifications require moderate desulfurization.
- Chemical Feedstocks:Aromatics and olefins production requires metals removal alongside sulfur reduction.
- Marine Fuels:Very low sulfur fuel oil production for IMO 2020 compliance commands premium catalyst formulations. Singapore and Rotterdam bunkering hubs prioritize maximum conversion to capture compliant fuel premiums.
Transportation fuels applications lead absolute demand; marine fuels represent the fastest-climbing specification tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residue hydrodesulphurization catalyst manufacturing originated in the United States and Germany during the post-war petrochemical expansion, with proprietary active metal deposition techniques developed at Gulf Coast research centers and Rhine-Ruhr chemical clusters. These foundational capabilities now distribute across refining-intensive economies seeking heavier crude processing capacity.
United States
Complex refineries on the US Gulf Coast process opportunity crudes from Latin America and Canada, driving demand for advanced pore-architecture catalysts. The EPA enforces Tier 3 gasoline sulfur standards that cascade into residue unit investment decisions. Houston and Port Arthur host the densest concentration of vacuum residue hydrodesulphurization capacity outside Asia.
China
State-owned refiners in Shandong and Guangdong provinces are retrofitting residue upgrading units to meet stricter product specifications from heavier domestic and imported crudes. The Ministry of Ecology and Environment applies dual carbon goals that tighten emission benchmarks for refining operations. Independent refiners in the Shandong cluster now specify catalysts with lower hydrogen consumption intensity.
Saudi Arabia
Saudi Aramco operates some of the world's largest residue conversion complexes at Ras Tanura and Yanbu, processing high-sulfur domestic crudes for export product compliance. The Kingdom's national oil company has established independent catalyst qualification programs outside traditional licensor channels. The Jubail industrial city anchors catalyst demand for new coker-hydrotreater integrations.
Netherlands
Rotterdam serves as Europe's primary marine bunkering hub, compelling residue unit investments to produce IMO 2020-compliant very low sulfur fuel oil. The EU REACH framework and F-Gas Regulation constrain catalyst precursor supply chains entering Dutch refineries. Shell's Pernis complex and independent processors at the port deploy advanced formulations for maximum conversion to capture compliant fuel premiums.
India
Reliance Industries and Indian Oil Corporation are expanding coker-hydrotreater complexes on the west coast to process discounted heavy Middle Eastern and Latin American crudes. Domestic catalyst demand will outpace local manufacturing capacity through 2030. The Jamnagar refining cluster represents the single largest residue upgrading investment zone in South Asia.
Residue Hydrodesulphurization Catalyst Market Competitive Landscape
Premium-margin players sit above commodity-margin players across active metal loading precision and technical service bundling. The vendor base concentrates among integrated chemical conglomerates with captive precursor supply and specialized catalyst houses with proprietary support engineering. Three archetypes dominate: diversified materials conglomerates with refinery catalyst divisions, pure-play catalyst specialists with process licensing heritage, and regional fabricators serving emerging market procurement channels. Capacity expansion and strategic decoupling of catalyst supply from process licensing represent the dominant competitive vectors.
Within the diversified conglomerate tier, Albemarle Corporation and Clariant AG exemplify players leveraging integrated manufacturing footprints to supply refiners across multiple geographies. Haldor Topsoe A/S anchors the specialist tier with Danish engineering heritage in active metal distribution optimization. Johnson Matthey PLC occupies a position bridging both archetypes through its historical process licensing relationships and advanced materials capabilities. These three represent the structural poles around which procurement patterns organize in residue hydrodesulphurization catalyst selection.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Haldor Topsoe A/S |
| Johnson Matthey PLC |
| Axens SA |
| Advanced Refining Technologies |
| Clariant AG |
| Honeywell UOP |
| CRI Catalyst Leuna GmbH |
| Redkino Catalyst Company |
| Others |
Value Network & Pricing Analysis
Performance-grade bifurcation between advanced multimodal pore-architecture catalysts and conventional unimodal formulations manifests in divergent pricing power and supply chain configurations. Premium formulations command sustained margins through captive precursor supply and technical service bundling, while commodity-grade products face cost compression from metal price volatility and spot-market procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with differentiation driven by active metal loading precision and after-sales regeneration support. Price differentiation intensifies as refiners unbundle catalyst procurement from process licensing, forcing standalone suppliers to compete on technical specifications alone. Pricing pressure stems from cobalt and molybdenum precursor volatility originating in the Democratic Republic of Congo and Chile. National oil companies in Saudi Arabia and Kuwait exhibit lowest price sensitivity through centralized long-term agreements, while independent refiners in India and Southeast Asia drive hardest bargain terms.
Supply Chain Analysis
Active metal precursor supply rests on mining concentration in Central Africa and South American copper-molybdenum belts, with gamma-alumina support materials drawing from Chinese and German specialty chemical producers. Raw material dependencies center on cobalt sulfate, ammonium molybdate, and tailored alumina hydrates. Single-source vulnerability concentrates in ex-situ regeneration capacity, where Albemarle's Rotterdam facility and US Gulf Coast providers handle majority of spent catalyst recovery. Distribution runs through refinery-integrated technical service contracts in the Middle East and direct merchant sales in India and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as IMO 2020 sulfur caps and China's dual carbon goals shift procurement criteria toward higher-activity, lower-hydrogen formulations that extend catalyst life and reduce emission intensity.
For Market Incumbents: To counter unbundling of catalyst supply from process licensing by Saudi Aramco and Kuwait Petroleum Corporation, deepen technical service capabilities around regeneration and spent catalyst metals recovery. Secure backward integration into cobalt and molybdenum precursor supply through offtake agreements with Chilean and Congolese mining operations to defend margin position against metal price spikes. For New Entrants and Emerging Players: Specialty catalyst formulations tolerant of oxygenated renewable feedstocks offer the most penetrable wedge for North American and European markets where co-processing regulations are tightening. Target India's residue upgrading wave where domestic manufacturing capacity lags demand through 2030, partnering with Reliance Industries or Indian Oil Corporation on qualification programs for Jamnagar and west coast complexes. For Investors and Strategic Acquirers: Consolidation pressure builds where catalyst regeneration skill shortage creates bottleneck delays for emerging market refiners. Mid-cap specialists with proprietary active metal distribution technology and established relationships with national oil companies present acquisition targets with 5-10 year viability windows. Watch for EU Carbon Border Adjustment Mechanism implementation as inflection signal favoring lifecycle-certified, lower-carbon manufacturing processes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive cobalt and molybdenum sourcing from Chile and DRC insulates margins against metal price volatility. |
| Regeneration Capacity Expansion | Ex-situ spent catalyst recovery facilities in Rotterdam and US Gulf Coast reduce 8-12 week turnaround delays. |
| Renewable Feedstock Co-Processing Formulations | Oxygen-tolerant catalysts capture premium positioning in North American and European renewable diesel blending. |
| Independent Qualification Programs | Saudi Aramco and Kuwait Petroleum Corporation's decoupled procurement enables direct manufacturer negotiation. |
| Trickle Bed Revamp Engineering | Advanced liquid distribution systems unlock capacity expansion within existing pressure vessel envelopes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, catalyst procurement leads at national oil companies, technical service directors, and EPC contractors specializing in residue unit revamps with secondary validation through customs trade data, SEC 10-K filings of diversified chemical conglomerates, refinery capacity databases, and EPA regulatory filings. Bottom-up unit-level capacity estimates and top-down market size triangulation cross-checked segmentation outputs across product type, end user, technology, and application dimensions.
Comparable-period anchoring linked forward projections to historical installation waves of vacuum residue hydrodesulphurization units, with CAGR derivation reflecting feedstock severity shifts, regulatory compliance deadlines, and metals tolerance requirements across the projection horizon. Segmentation modeling incorporated catalyst grade tier, refinery complexity level, reactor configuration type, regional regulatory framework, and hydrogen infrastructure availability as core dimensions. Industry-specific forecast inputs centered on crude slate heavification trends and national oil company procurement centralization patterns.
The model holds under stable cobalt-molybdenum supply conditions and sustained IMO 2020 enforcement; deviation in marine fuel sulfur regulation relaxation or hydrogen infrastructure buildout delays would shift residue upgrading investment timelines. Forecasts reflect documented assumptions around feedstock quality trajectories and catalyst replacement cycle norms. A small set of named triggers—EU CBAM phase-in, China's dual carbon goal acceleration, and India domestic manufacturing capacity expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Phosphorus Based Catalyst Market
Catalysts
South America Refining Catalysts Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Refining Catalysts Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Polyurethane Catalysts Market
Catalysts
Inorganic Catalyst Market
Catalysts
Global FCC Catalyst Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Refinery Catalyst Market