
 Asia and Middle East FCC Catalyst Market | 2026-2036
Asia and Middle East FCC Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Asia and Middle East FCC Catalyst Market Outlook
Market Context
Middle Eastern catalyst production is decoupling from traditional European supply chains as regional refiners build captive manufacturing. Albemarle Corporation leverages its rare earth processing foothold in Jordan to sustain regional zeolite supply. JGC Catalysts & Chemicals Co., Ltd. anchors technical service networks across Southeast Asian refineries. China Petroleum & Chemical Corporation dominates domestic catalyst replacement cycles through backward integration into rare earth mining.
Technical Definition and Segment Structure
Asia and Middle East FCC catalyst refers to synthetic zeolite-based materials, typically Y-type faujasite with 1-3 wt% rare earth oxide stabilization, manufactured via spray-drying and ion-exchange processes to crack heavy vacuum gas oil into lighter olefins and gasoline-range hydrocarbons. Zeolite formulations command the largest volume share due to their established cracking selectivity and thermal stability under regenerator temperatures exceeding 700°C. Petrochemical refining applications are expanding fastest as integrated refinery-petrochemical complexes in China and Saudi Arabia prioritize propylene yields over fuel production. Fluid catalytic cracking technology leads installed capacity, though hydrocracking catalyst demand is accelerating where middle distillate deficits persist.
Regulatory Framework and Outlook
China's MIIT enforces GB VI-B automotive fuel standards that mandate ultra-low sulfur gasoline, directly tightening FCC catalyst specifications for sulfur transfer functionality. Saudi Arabia's SFDA and India's BIS coordinate product quality benchmarks that determine import eligibility for foreign catalyst suppliers. REACH-equivalent chemical registration frameworks across Gulf Cooperation Council jurisdictions are raising documentation burdens for European and Japanese exporters. Stakeholders must monitor how carbon border adjustments and refinery decarbonization timelines reshape catalyst replacement economics before committing to long-term supply contracts.
Market Dynamics
Refinery-petrochemical integration across China and Saudi Arabia is compressing catalyst replacement cycles as operators chase higher propylene yields from the same FCC unit hardware, forcing suppliers to accelerate formulation refresh rates.
Growth Catalysts
- IMO 2020 Sulfur Mandates:Southeast Asian refiners are expanding hydrotreating capacity ahead of marine fuel specifications, multiplying catalyst consumption per barrel processed.
- Rare Earth Supply Security:China's MIIT prioritizes domestic rare earth oxide allocation to catalyst manufacturers, insulating regional producers from export quota volatility.
- Propylene Yield Optimization:Integrated complexes in Saudi Arabia demand ZSM-5 additive packages that maximize light olefin output over gasoline production.
Market Restraints
- Lanthanum Price Volatility:Rare earth oxide feedstock costs swing with Chinese export policy, eroding margin predictability for non-integrated catalyst blenders.
- Captive Supply Concentration:Sinopec's backward integration into rare earth mining locks independent refiners into single-source dependency for critical zeolite precursors.
- REACH-Equivalent Documentation:Gulf Cooperation Council chemical registration frameworks impose compliance costs that disproportionately burden European and Japanese exporters.
Strategic Opportunities
- Vietnam Refinery Buildout:Nghi Son and Long Son complexes create greenfield demand for full catalyst suites without incumbent supplier lock-in.
- Carbon Border Adjustments:EU CBAM proposals on imported refined products incentivize Middle Eastern exporters to adopt lower-carbon catalyst regeneration cycles.
- Digital Catalyst Monitoring:Real-time regenerator temperature analytics enable predictive replacement scheduling, opening subscription revenue streams for technical service providers.
Industry Challenges
- Rare Earth Metallurgy Expertise Gap:Formulation chemists with ion-exchange process experience command premium compensation, constraining R&D team scaling.
- Zeolite Synthesis Scale-Up:Translating lab-optimized rare earth stabilization protocols to commercial spray-drying throughput requires capital-intensive pilot facilities.
- Multi-Jurisdiction Certification:Simultaneous compliance with China's GB standards, India's BIS, and Saudi SFDA timelines stretches quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia and Middle East FCC Catalyst Market |
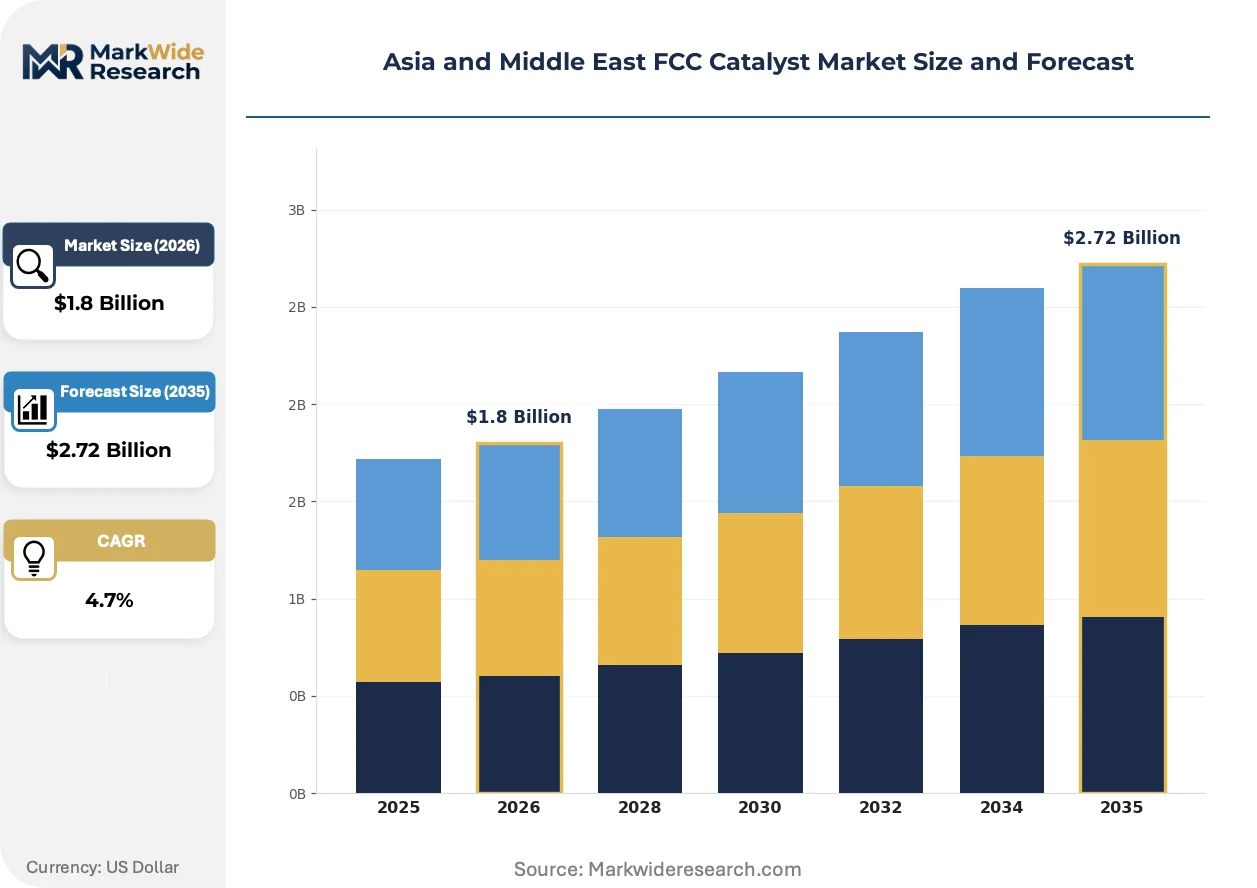
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolite, Transition Metal, Rare Earth, Non-metal Application: Petrochemical Refining, Fuel Production, Lubricants, Chemical Synthesis End User: Oil Refineries, Chemical Producers, Gas Processing Facilities, Specialty Chemical Manufacturers Technology: Fluid Catalytic Cracking, Hydrocracking, Catalytic Reforming, Gas-to-Liquids |
| Companies Covered | Clariant International Ltd., China Petroleum & Chemical Corporation, BASF SE, Yueyang Sciensun Chemical Co., Ltd., JGC Catalysts & Chemicals Co., Ltd., W. R. Grace & Co., Haldor Topsoe A/S, Anten Chemical Co., Ltd., Albemarle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia and Middle East FCC Catalyst Market Strategic Shifts
Zeolite architecture refinement and regenerator heat management systems are converging to extend catalyst life while meeting stricter sulfur transfer specifications. Suppliers now compete on predictive analytics integration rather than base cracking activity alone.
Dual-function FCC catalysts incorporating sulfur transfer agents alongside traditional cracking zeolites is modularizing how refiners approach post-treatment investment. Chinese operators in Shandong province are piloting these formulations to defer hydrotreater expansion. The technology compresses capital allocation decisions by embedding compliance functionality directly into the cracking unit.
China's MIIT enforcement of GB VI-B automotive fuel standards is tightening sulfur specifications for gasoline pool components. Refiners must now specify catalysts with demonstrated sulfur transfer efficiency under high-severity operating conditions. Guangdong province processors are leading adoption of rare-earth-enhanced formulations to meet the 10 ppm sulfur ceiling without downstream hydrotreater bottlenecks.
Technical service unbundling is fragmenting traditional supply relationships across Southeast Asian refineries. Operators in Thailand and Indonesia now procure catalyst formulations separately from regeneration and spent catalyst reclamation services. This purchasing pattern is most pronounced among independent processors lacking captive technical teams, who prioritize per-ton cracking economics over bundled lifecycle contracts.
Asia and Middle East FCC Catalyst Market Segmentation
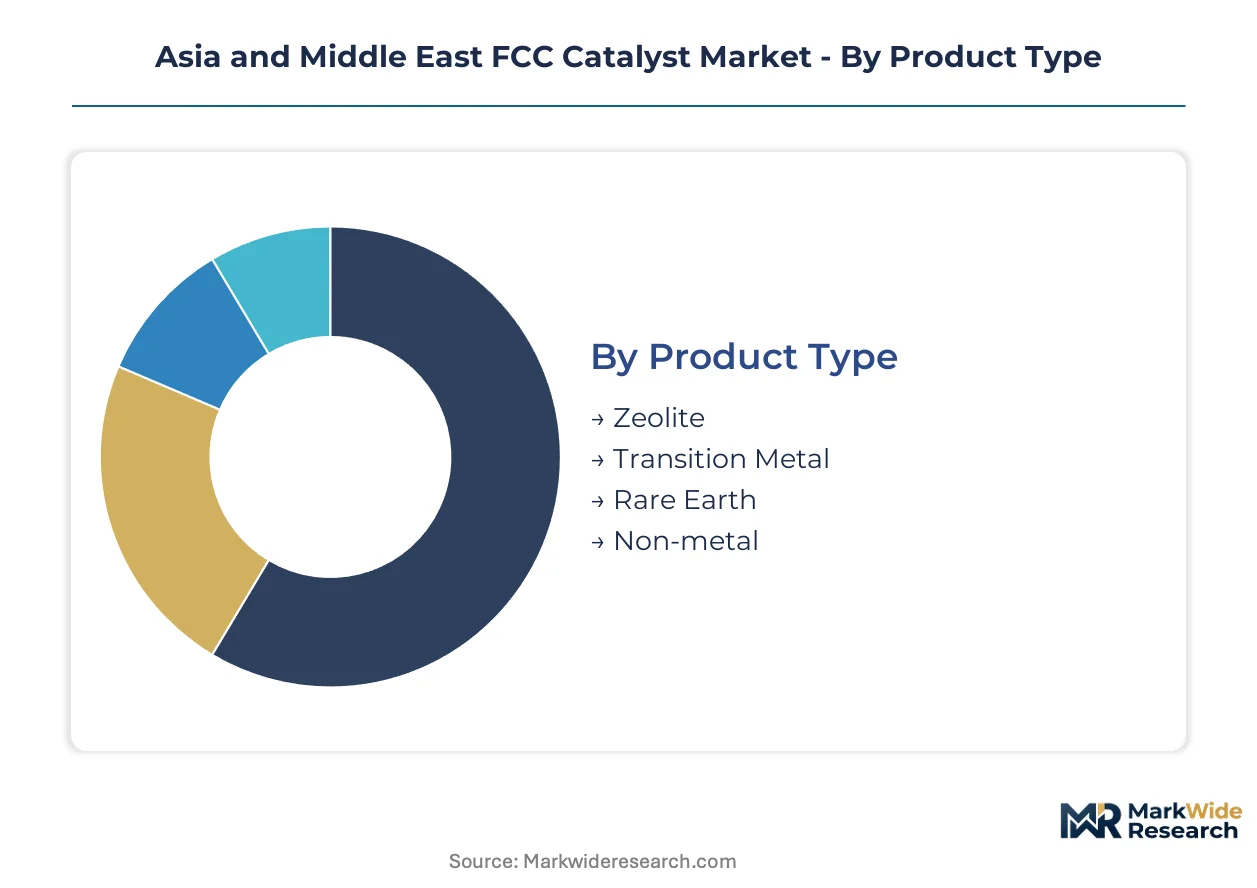
Refinery operators in Asia and the Middle East select catalyst formulations based on feedstock quality, target product slate, and integration with existing unit hardware. Segmentation reveals how technical specifications diverge between fuel-focused refiners and integrated petrochemical complexes chasing olefin yields.
Product Type:
Buyers prioritize thermal stability and rare earth oxide content when evaluating catalyst formulations for high-severity FCC operations.
- Zeolite:Y-type faujasite structures with 1-3 wt% rare earth stabilization dominate installed capacity due to established cracking selectivity under regenerator temperatures exceeding 700°C. Shandong and Guangdong refiners specify these formulations to meet China's MIIT GB VI-B sulfur mandates without hydrotreater bottlenecks.
- Rare Earth:Lanthanum and cerium oxide-enhanced variants command premium positioning for ultra-low sulfur gasoline production. Demand concentrates in integrated Chinese complexes where backward integration into domestic rare earth mining insulates supply security.
- Transition Metal:Nickel and vanadium tolerance additives extend catalyst life when processing high-metal crudes from Middle Eastern heavy oil streams.
- Non-metal:Silica-alumina base materials serve niche applications in mild cracking conditions or as cost-sensitive filler components.
Volume sits with Zeolite; growth tilts toward Rare Earth.
Application:
Application selection tracks refinery configuration complexity and product margin differentials across the region.
- Petrochemical Refining:Propylene-maximizing ZSM-5 additive packages are expanding fastest as Saudi Aramco and Sinopec integrated complexes prioritize light olefin yields over gasoline production. These formulations require precise rare earth stabilization to maintain activity across shorter replacement cycles.
- Fuel Production:Gasoline-range hydrocarbon cracking remains the baseline application for standalone refiners in Indonesia and Thailand facing IMO 2020 marine fuel sulfur compliance pressures.
- Lubricants:Hydrocracking-derived base oil production drives catalyst consumption in South Korean and Japanese specialty refineries.
- Chemical Synthesis:FCC off-gas utilization for BTX aromatics recovery creates specialized catalyst demand in Chinese coal-to-chemicals corridors.
Revenue concentrates in Petrochemical Refining; replacement frequency peaks in Fuel Production.
End User:
Procurement scale and technical service requirements vary sharply by operator sophistication and captive supply integration.
- Oil Refineries:Nghi Son and Long Son complexes in Vietnam represent greenfield demand without incumbent supplier lock-in, while established Middle Eastern operators build captive manufacturing to decouple from European supply chains.
- Chemical Producers:Integrated refinery-petrochemical complexes in Saudi Arabia and China drive formulation customization for dual-product optimization.
- Gas Processing Facilities:Gas-to-liquids operators in Qatar and Malaysia require specialized catalysts for Fischer-Tropsch integration with FCC product streams.
- Specialty Chemical Manufacturers:Small-batch producers in India and Southeast Asia source technical-grade catalysts through unbundled service arrangements.
Contract value peaks with Oil Refineries; technical service intensity defines Chemical Producers.
Technology:
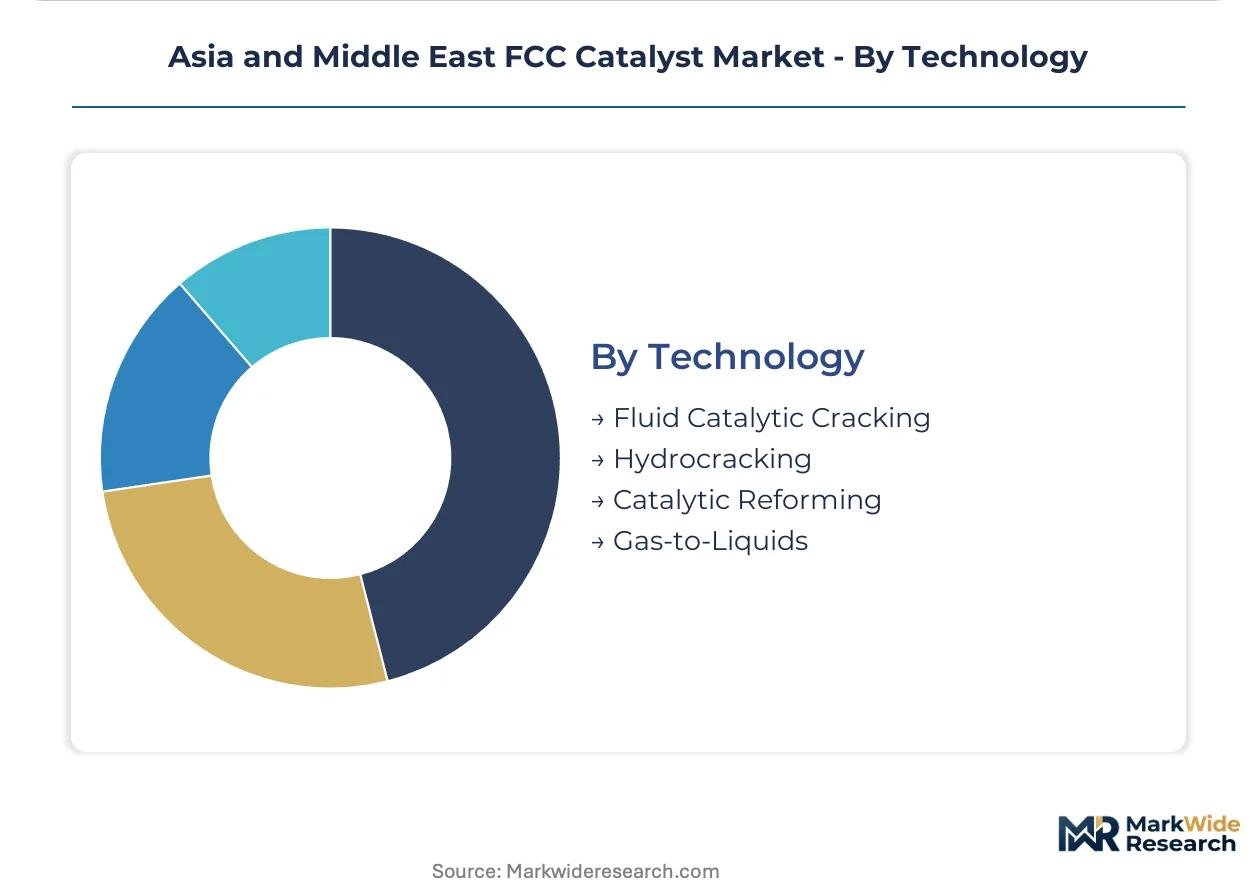
Technology selection reflects feedstock flexibility requirements and middle distillate deficit positioning across national refining bases.
- Fluid Catalytic Cracking:Installed capacity leadership persists across Asia-Pacific, though regenerator heat management systems are converging with sulfur transfer functionality to extend catalyst life. Chinese operators pilot dual-function formulations embedding compliance directly into cracking units.
- Hydrocracking:Middle distillate deficits in India and Southeast Asia accelerate catalyst demand where vacuum gas oil upgrading targets diesel and jet fuel pools.
- Catalytic Reforming:Naphtha upgrading for high-octane gasoline components maintains steady catalyst consumption in Japan and South Korea.
- Gas-to-Liquids:Fischer-Tropsch synthesis integration with FCC product recovery operates at limited scale in Qatar and Malaysia.
Installed base favors Fluid Catalytic Cracking; capacity additions favor Hydrocracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth oxide deposits in China's Inner Mongolia and Jiangxi provinces anchor zeolite catalyst supply security across Asia. Jordan's phosphate and rare earth processing corridors feed Middle Eastern refinery demand. Southeast Asian hydroprocessing expansion concentrates catalyst consumption in Vietnam and Indonesia.
China
Shandong and Guangdong refiners drive rare-earth-stabilized zeolite consumption under MIIT's GB VI-B sulfur mandates. The ministry prioritizes domestic rare earth oxide allocation to catalyst manufacturers, insulating regional producers from export quota volatility. Sinopec's backward integration into mining locks supply chains for integrated complexes in the Bohai Rim.
Saudi Arabia
Integrated refinery-petrochemical complexes prioritize propylene-maximizing ZSM-5 additive packages over gasoline yields. SFDA coordinates product quality benchmarks that determine import eligibility for foreign catalyst suppliers. The Eastern Province hosts captive manufacturing buildouts that decouple regional refiners from European supply chains.
Vietnam
Nghi Son and Long Son complexes generate greenfield demand for full catalyst suites without incumbent supplier lock-in. The country's national petroleum regulator enforces fuel quality standards aligned with ASEAN harmonization protocols. Independent processors in the Southeast Economic Region procure technical services separately from catalyst formulations.
India
Middle distillate deficits accelerate hydrocracking catalyst demand where vacuum gas oil upgrading targets diesel and jet fuel pools. BIS certification timelines stretch quality assurance bandwidth for multi-jurisdiction suppliers. Gujarat refineries concentrate hydrotreating capacity expansion to meet IMO 2020 marine fuel sulfur compliance.
Japan
Specialty refineries maintain steady catalytic reforming catalyst consumption for high-octane gasoline components. METI oversees technical standards that influence formulation specifications across Northeast Asian export markets. Chubu region processors pilot regenerator heat management systems to extend catalyst life cycles.
Asia and Middle East FCC Catalyst Market Competitive Environment
Global majors compete with regional champions across rare earth supply security and technical service density. The vendor base stratifies between integrated miners with captive zeolite production and independent blenders dependent on spot oxide markets. Three archetypes dominate: state-linked energy conglomerates with backward integration, European specialty chemical houses with formulation licensing networks, and Asian technical service providers with refinery-embedded engineering teams. Competitive moves center on captive rare earth offtake agreements and predictive analytics platform deployment.
Within the state-linked tier, China Petroleum & Chemical Corporation exemplifies vertical control from mining through catalyst replacement cycles. Among European specialty houses, BASF SE and Clariant International Ltd. occupy positions anchored by REACH-equivalent compliance documentation capabilities. Albemarle Corporation represents the rare-earth-processing-integrated archetype through its Jordan-based oxide supply foothold.
| Leading Market Players |
|---|
| Clariant International Ltd. |
| China Petroleum & Chemical Corporation |
| BASF SE |
| Yueyang Sciensun Chemical Co., Ltd. |
| JGC Catalysts & Chemicals Co., Ltd. |
| W. R. Grace & Co. |
| Haldor Topsoe A/S |
| Anten Chemical Co., Ltd. |
| Albemarle Corporation |
| Others |
Value Chain & Pricing Dynamics
Formulation chemists with ion-exchange process experience command premium compensation in Shandong province, compressing labor-cost differentials between rare-earth-stabilized zeolite producers and standard-grade blenders. This workforce concentration widens pricing-tier spreads as captive manufacturers absorb technical talent costs while independent blenders face margin erosion from spot-market oxide procurement.
Pricing Analysis
Warranty and technical service bundling separates integrated suppliers from unbundled procurement patterns across Southeast Asian refineries. Three-tier pricing structure across premium rare-earth-enhanced, standard zeolite, and economy silica-alumina formulations tracks certification grade and volume scale. Cost compression in the standard tier is intensifying because lanthanum oxide spot volatility erodes blender margins. Independent processors lacking captive technical teams exhibit highest price sensitivity, while integrated refinery-petrochemical complexes prioritize per-ton cracking economics over upfront catalyst costs.
Supply Chain Analysis
Rare earth oxide feedstock rests on Chinese domestic allocation policies, Jordanian processing corridors, and spot-market traders in Singapore. Lanthanum and cerium oxides, Y-type faujasite precursors, and ZSM-5 additive packages anchor formulation dependencies. Single-source vulnerability concentrates around Sinopec's backward integration into Inner Mongolia mining, locking independent refiners into constrained supply alternatives. Distribution runs through technical service networks embedded at refinery sites rather than commodity broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
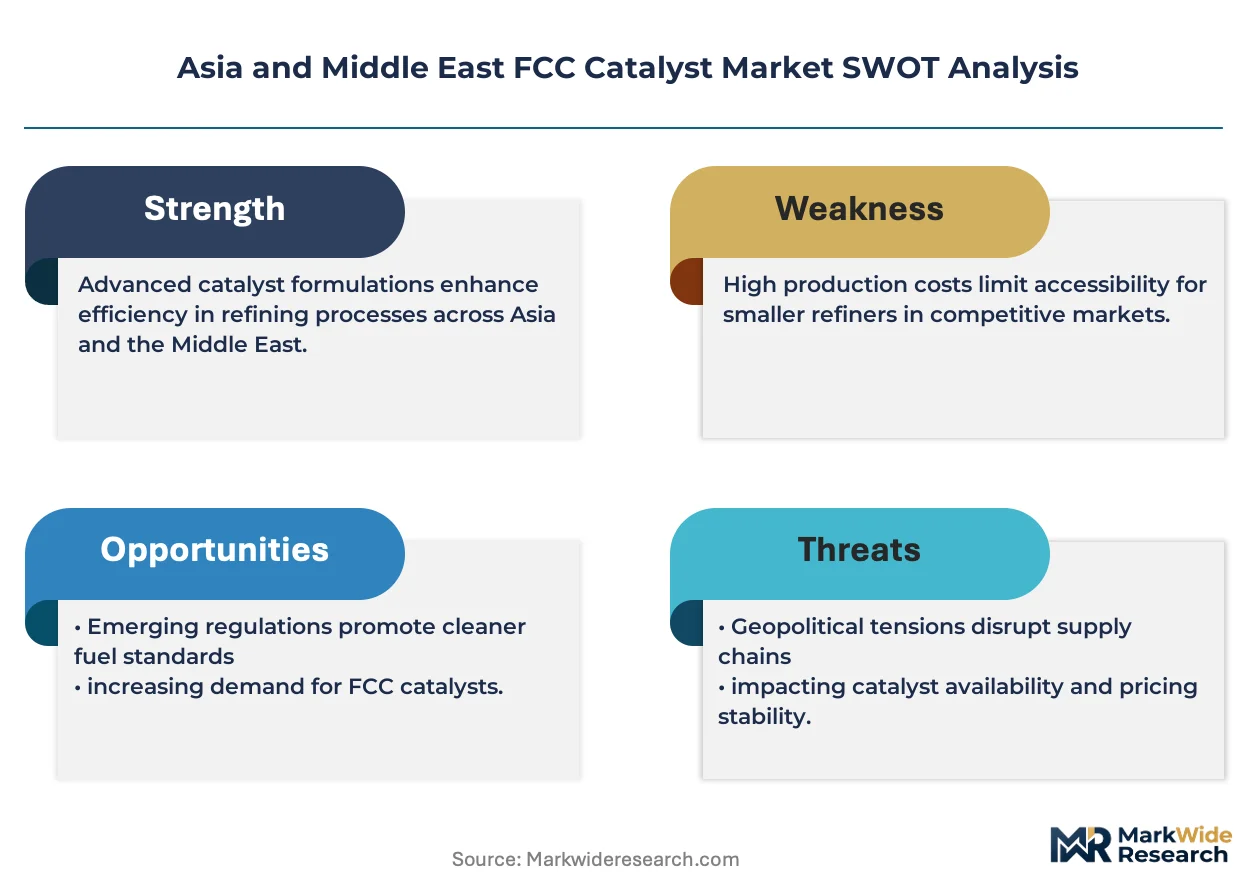
This market reads as a cost-of-compliance story where China's MIIT GB VI-B sulfur mandates erect barrier-to-entry moats favoring rare-earth-integrated incumbents with documented sulfur transfer efficiency.
For Market Incumbents: Cement rare earth offtake security through Jordanian or Inner Mongolian supply corridors before export quota tightening. Defend formulation refresh rates by embedding predictive analytics platforms at Saudi Aramco and Sinopec integrated complexes, neutralizing independent technical service providers threatening unbundled procurement relationships. For New Entrants and Emerging Players: Launch via digital catalyst monitoring subscriptions targeting Vietnamese Nghi Son and Long Son greenfield complexes lacking incumbent supplier lock-in. Penetrate the independent processor segment in Thailand and Indonesia through unbundled regeneration services, exploiting technical service fragmentation where operators prioritize per-ton economics over bundled lifecycle contracts. For Investors and Strategic Acquirers: Re-rating potential sits with rare-earth-processing-integrated specialists given carbon border adjustment catalysts reshaping Middle Eastern refinery economics. Long-term viability over a 5-10 year window favors acquisition targets with captive oxide supply and regenerator heat management IP. Watch EU CBAM implementation timelines as the inflection signal for lower-carbon catalyst regeneration cycle demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Mining | Secures lanthanum oxide supply for Shandong and Guangdong refinery demand under MIIT allocation policies. |
| Dual-Function Catalyst Formulation Launch | Embeds sulfur transfer agents into cracking zeolites to defer hydrotreater expansion for GB VI-B compliance. |
| Predictive Analytics Platform Deployment | Enables real-time regenerator temperature monitoring at Saudi integrated complexes for subscription revenue streams. |
| Technical Service Network Expansion | Anchors JGC Catalysts engineering teams across Southeast Asian refineries facing IMO 2020 sulfur mandates. |
| Greenfield Catalyst Suite Supply Agreement | Captures Nghi Son and Long Son demand without incumbent lock-in through full formulation and regeneration bundling. |
Study Parameters
Trade databases, refinery catalyst consumption disclosures, and rare earth oxide export records formed the secondary backbone, cross-referenced with primary interviews involving FCC unit operations managers, catalyst procurement leads at integrated refineries, rare earth mining coordination officers, and technical service directors. Bottom-up modeling of zeolite formulation demand and top-down triangulation against regional refining capacity expansion validated volume estimates.
Historical trendline analysis of catalyst replacement cycles and rare earth oxide price volatility informed the projection framework across the analysis window. Segmentation dimensions modeled include zeolite type, application focus, end-user sophistication, and technology platform, with CAGRs derived from regression against refinery-petrochemical integration buildouts and sulfur specification tightening trajectories. Propylene yield optimization intensity and hydrotreater capacity addition rates served as industry-specific forecast inputs.
Rare earth export policy shifts, carbon border adjustment implementation timelines, and refinery decarbonization acceleration are the dominant revision risks to modeled catalyst demand. Forecasts reflect documented assumptions about IMO 2020 compliance trajectories and MIIT enforcement consistency. A small set of regulatory triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Global Catalyst Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Solid Acid Catalysts Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Steam Methane Reforming Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
Global FCC Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market