
 Syngas to Ethylene Glycol Catalyst Market | 2026-2036
Syngas to Ethylene Glycol Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Syngas to Ethylene Glycol Catalyst Market Insights
Petrochemical integrators are unwinding from traditional naphtha-cracker ethylene glycol supply chains toward coal-syngas alternatives. HighChem leverages its captive catalyst production to serve Danhua Chemical's expanding coal-chemical complexes in western China. Johnson Matthey competes through noble-metal catalyst R&D intensity, while BASF anchors European demand with fixed-bed reactor optimization for syngas conversion efficiency.
Syngas to ethylene glycol catalysts comprise heterogeneous formulations—typically copper-zinc oxide-alumina systems or chromite spinels—engineered to catalyze carbon monoxide hydrogenation to ethylene glycol at pressures between 20 and 50 bar and temperatures of 473–573 K. These catalysts enable non-petroleum routes to a foundational chemical intermediate used across polyester fiber, PET resin, and antifreeze applications. Copper-based catalysts occupy the dominant share of operating units due to mature manufacturing scale and lower precious-metal loading, though noble metal variants lead in selectivity-sensitive membrane reactor installations. Slurry reactor technology is gaining fastest among process configurations as Chinese operators retrofit fixed-bed assets for higher syngas throughput and improved heat removal.
China's Ministry of Ecology and Environment enforces dual carbon emission intensity benchmarks that favor syngas routes with carbon capture integration, while REACH in Europe restricts chromite catalyst formulations containing hexavalent chromium compounds. The country's national chemical safety regulator mandates catalyst performance disclosure for coal-to-chemical project licensing. Stakeholders must monitor how carbon border adjustment mechanisms and catalyst durability standards reshape procurement criteria across integrated polyester producers.
Market Dynamics
Coal-to-chemical project clusters in western China are retrofitting fixed-bed reactors with slurry-phase configurations, compressing catalyst replacement cycles and concentrating procurement power among polyester integrators with captive syngas assets.
Growth Catalysts
- Dual carbon policy enforcement:China's MEE emission intensity benchmarks accelerate coal-syngas route approvals with integrated carbon capture, expanding catalyst demand from licensed coal-chemical complexes.
- Slurry reactor retrofits:Chinese operators retrofit legacy fixed-bed assets for higher throughput and improved heat removal, shortening catalyst replacement intervals and expanding volume demand.
- Copper-zinc oxide-alumina scale economies:Domestic catalyst manufacturing clusters in Shaanxi and Inner Mongolia achieve cost parity with imported formulations, lowering barriers for mid-scale coal-chemical projects.
Market Restraints
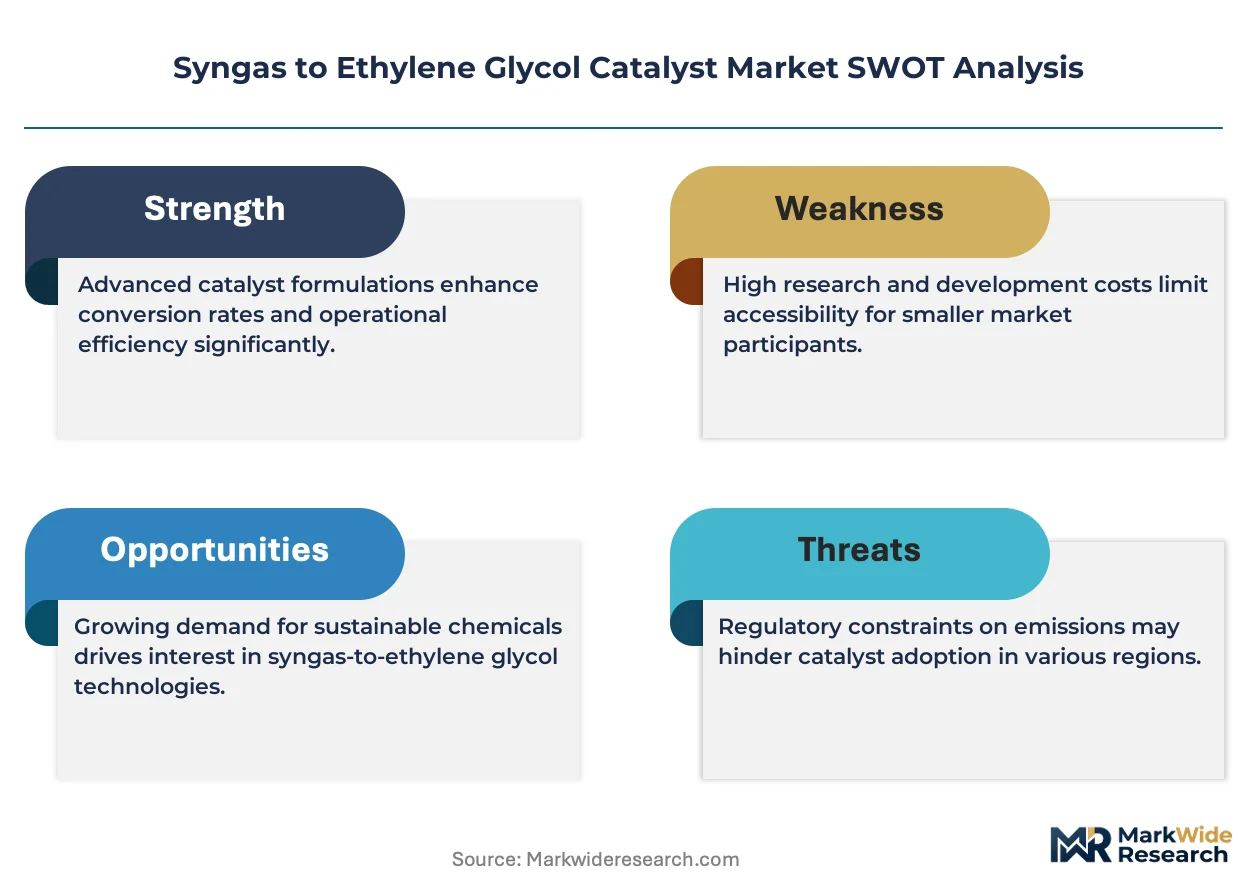
- Chromite catalyst phase-out:REACH restrictions on hexavalent chromium compounds force European operators to abandon mature chromite spinel formulations, raising switching costs for legacy asset owners.
- Noble metal cost volatility:Palladium and rhodium price swings compress margins for high-selectivity membrane reactor installations, constraining adoption outside subsidy-backed demonstration projects.
- Coal-chemical supply concentration:Over 70% of operating syngas-to-glycol capacity sits within three Chinese provincial clusters, creating geographic demand vulnerability to regional policy shifts or feedstock disruptions.
Strategic Opportunities
- Carbon border adjustment preparation:European polyester producers are piloting syngas-to-glycol catalyst trials to qualify coal-chemical glycol for CBAM-compliant supply chains ahead of full carbon border enforcement.
- Biomass-syngas convergence:Gasification of agricultural residue streams in India and Brazil creates demand for catalyst formulations tolerant of higher impurity loads in non-coal syngas feeds.
- Performance-guarantee contracting:Catalyst suppliers are bundling durability warranties with technical service packages, capturing recurring revenue from operating units in remote western China locations.
Industry Challenges
- Membrane reactor engineering scarcity:The shift toward noble-metal membrane configurations demands rare expertise in thin-film palladium deposition and seal integrity management, constraining deployment timelines.
- Legacy fixed-bed integration friction:Slurry-phase retrofits require vessel redesign and solids-handling infrastructure that many 2010-era coal-chemical plants lack, complicating upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syngas to Ethylene Glycol Catalyst Market |
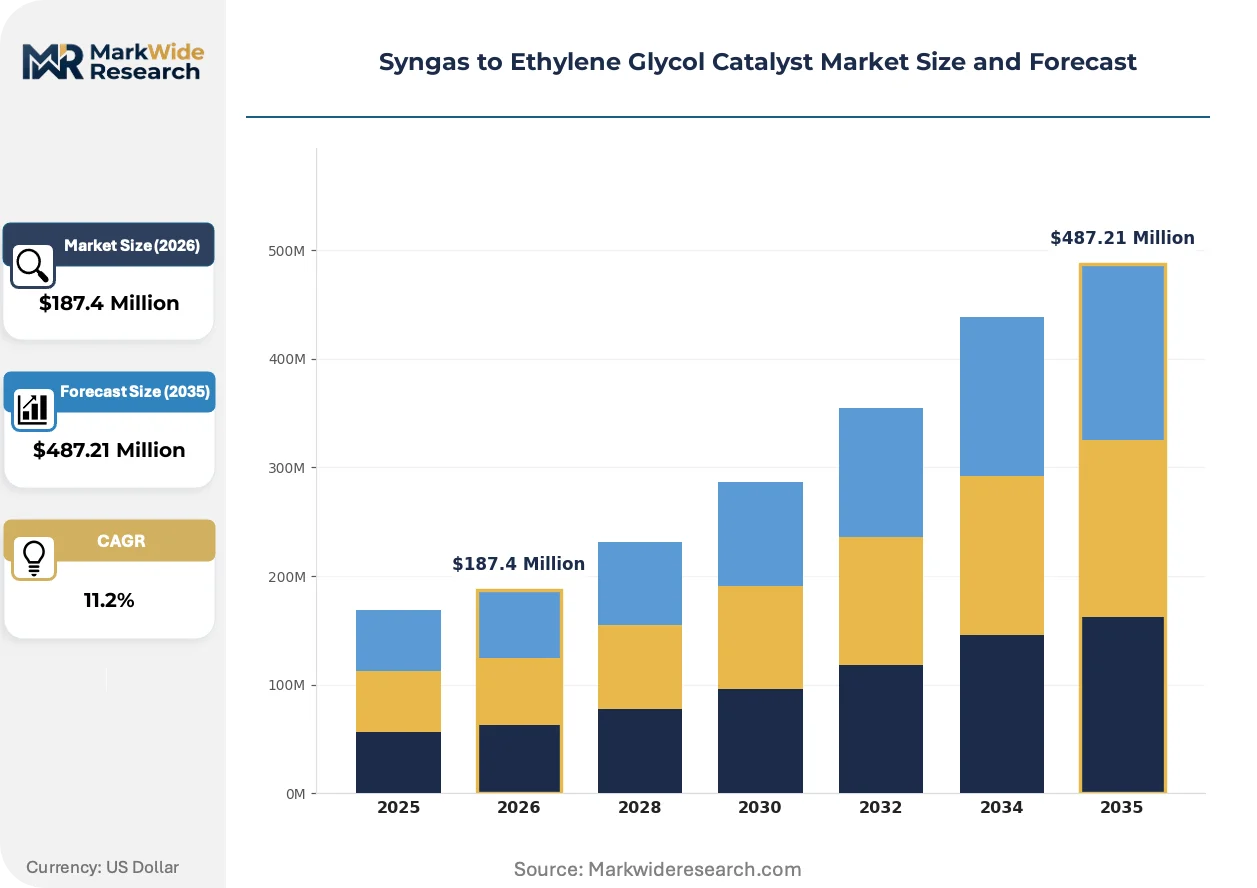
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper-Based Catalysts, Zinc-Based Catalysts, Chromite Catalysts, Noble Metal Catalysts Application: Polyester Production, Antifreeze Manufacturing, Plasticizer Synthesis, Solvent Production End User Industry: Chemical Manufacturing, Automotive Coatings, Textile Processing, Packaging Materials Process Technology: Fixed-Bed Reactors, Fluidized-Bed Reactors, Slurry Reactors, Membrane Reactors |
| Companies Covered | HighChem, Danhua Chemical, Ningbo FarEast Catalytic Engineering, Shanghai Pujing Chemical, Haiso Technology, Shangqiu Guolong New Materials, BASF, Clariant, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syngas to Ethylene Glycol Catalyst Market Trends and Innovations
Reactor technology evolution, regulatory chemistry restrictions, and procurement consolidation are compressing catalyst lifecycles while elevating performance guarantees as a competitive differentiator.
Copper-based slurry-phase catalysts are supplanting fixed-bed copper-zinc oxide-alumina systems in Chinese coal-chemical retrofits. Shaanxi and Inner Mongolia operators have accelerated adoption since 2022. The technology is supplanting decade-old fixed-bed assets that cannot achieve comparable syngas throughput without excessive pressure drop or hot-spot formation.
REACH authorization requirements for hexavalent chromium are forcing chromite spinel catalyst retirement across European syngas-to-glycol installations. Formulators must revalidate copper-alternative selectivity profiles under industrial conditions. German and Dutch polyester producers are extending qualification timelines for non-chromite catalyst supply contracts.
Long-term offtake agreements with catalyst performance clauses are displacing spot procurement among integrated Chinese polyester manufacturers. Sinopec and private coal-chemical operators now require minimum 8,000-hour durability guarantees with penalty structures. This contracting shift is most visible in western China where remote site access elevates technical service costs.
Syngas to Ethylene Glycol Catalyst Market Segmentation
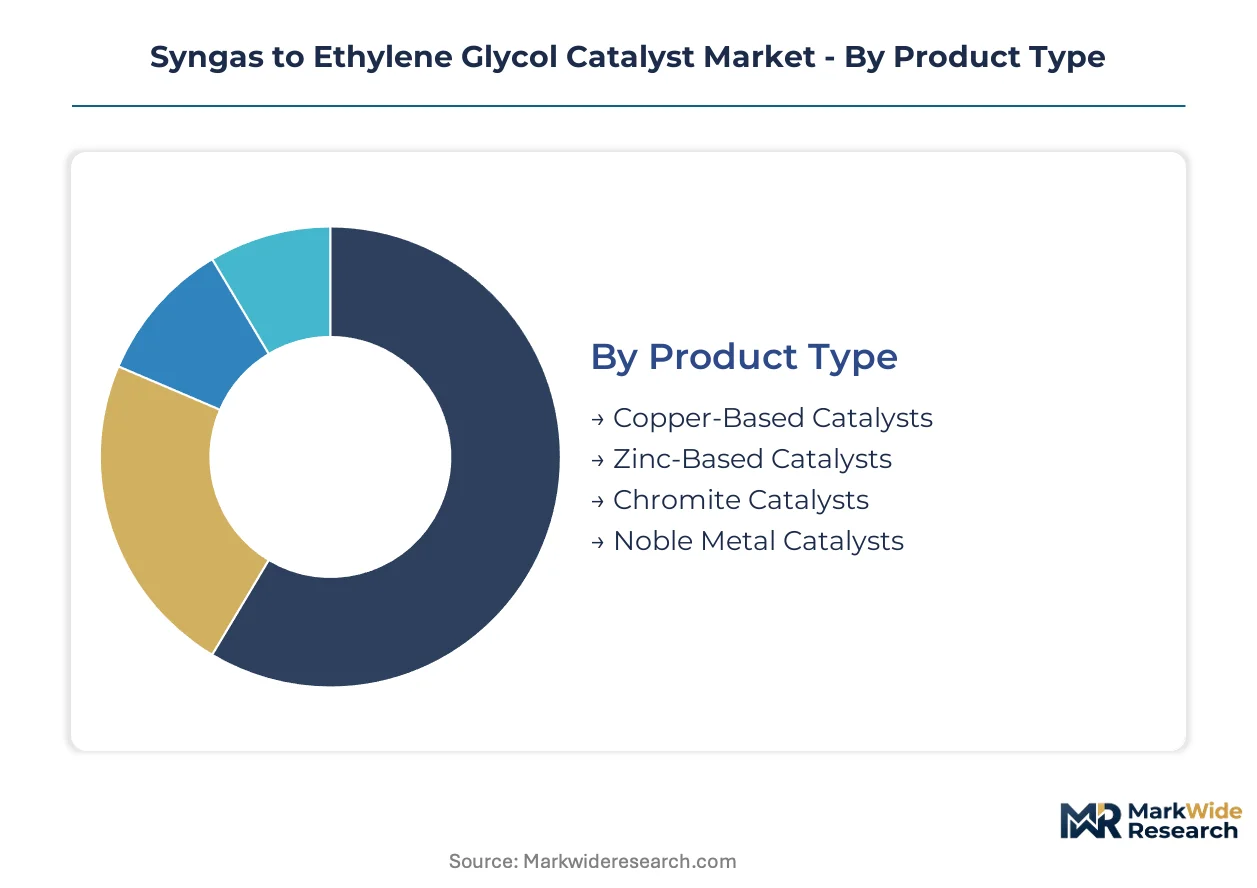
Catalyst procurement patterns in syngas-to-glycol conversion diverge sharply by formulation chemistry and reactor configuration. Understanding these fault lines reveals where substitution pressure from naphtha-based ethylene glycol routes threatens incumbent positions.
Product Type:
Copper-based formulations face the stiffest substitution pressure from bio-based glycol routes, while noble metal catalysts defend premium positions through selectivity advantages in carbon capture-integrated projects.
- Copper-Based Catalysts:Copper-zinc oxide-alumina systems dominate installed capacity across Shaanxi and Inner Mongolia coal-chemical clusters. Domestic manufacturing scale in western China has compressed procurement costs for polyester integrators operating captive syngas assets.
- Noble Metal Catalysts:Palladium and rhodium formulations enable membrane reactor configurations with superior carbon monoxide conversion selectivity. Price volatility in precious metal markets constrains deployment outside demonstration projects with subsidy backing.
- Chromite Catalysts:Chromite spinel formulations face forced retirement under ECHA REACH restrictions on hexavalent chromium compounds.
- Zinc-Based Catalysts:Zinc oxide promoters supplement copper primary active sites in hybrid formulations for moderate-pressure slurry operations.
Copper-based catalysts anchor the volume base while noble metal catalysts gain share at the steepest rate in carbon capture-integrated installations.
Application:
Cost tier stratification separates commodity glycol demand from specialty solvent applications where catalyst selectivity commands pricing premiums.
- Polyester Production:PET resin and fiber manufacturing consumes the dominant share of syngas-derived ethylene glycol output. Sinopec and private coal-chemical operators in western China specify 8,000-hour minimum durability guarantees for catalyst supply contracts.
- Antifreeze Manufacturing:Automotive and industrial coolant blending requires high-purity monoethylene glycol with strict chloride specifications. Catalyst poisoning tolerance distinguishes formulations for this application.
- Plasticizer Synthesis:Ethylene glycol serves as diol feedstock for polyester plasticizer production in flexible PVC compounding.
- Solvent Production:Specialty solvent applications demand ultra-low aldehyde byproduct profiles.
Polyester production absorbs the greatest catalyst volume while antifreeze manufacturing imposes the most stringent purity specifications on formulation selection.
End User Industry:
Customer type concentration among integrated coal-chemical operators concentrates procurement power in chemical manufacturing relative to fragmented downstream processors.
- Chemical Manufacturing:Coal-to-chemical complexes in China operate captive syngas-to-glycol units with dedicated catalyst technical service agreements. Remote site locations in western provinces elevate performance-guarantee contracting importance.
- Textile Processing:Polyester fiber producers source glycol from merchant coal-chemical suppliers or operate backward-integrated syngas assets.
- Automotive Coatings:Antifreeze blenders and coating formulators purchase refined glycol with trace contaminant specifications.
- Packaging Materials:PET bottle resin producers specify glycol purity grades for food-contact applications.
Chemical manufacturing commands the dominant procurement volume while textile processing shows the most rapid integration into captive syngas supply chains.
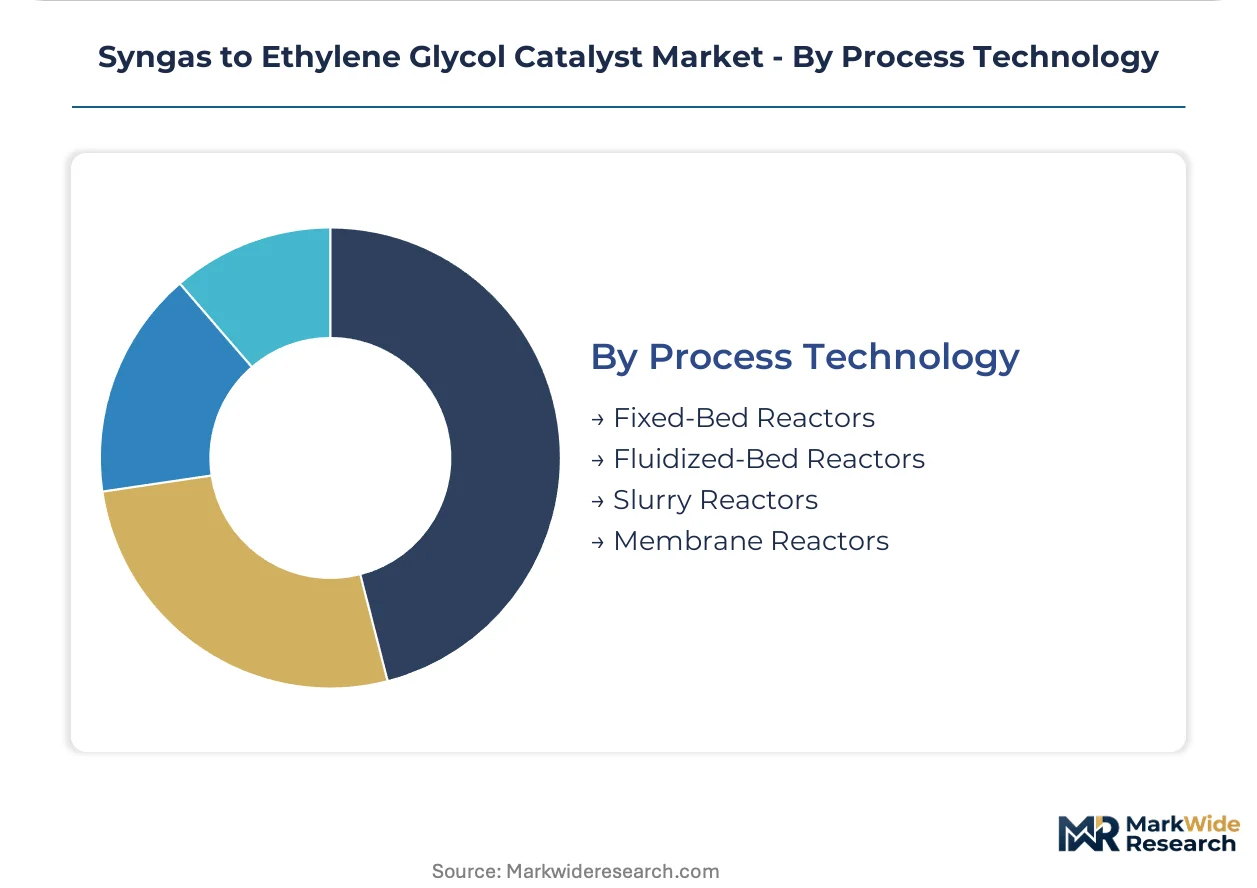
Process Technology:
Reactor configuration maturity curves separate established fixed-bed assets from slurry-phase retrofits now climbing the fastest.
- Slurry Reactors:Three-phase slurry configurations enable higher syngas throughput and superior heat removal compared to fixed-bed alternatives. Chinese operators have accelerated retrofit schedules since 2022 to exploit dual carbon policy incentives.
- Fixed-Bed Reactors:Tubular fixed-bed designs represent the legacy installed base from 2010-era coal-chemical construction. Pressure drop limitations and hot-spot formation constrain capacity expansion without vessel redesign.
- Membrane Reactors:Palladium membrane configurations achieve breakthrough carbon monoxide conversion selectivity. Thin-film deposition expertise scarcity constrains commercial deployment timelines.
- Fluidized-Bed Reactors:Gas-solid fluidized systems offer intermediate heat transfer characteristics between fixed-bed and slurry alternatives.
Fixed-bed reactors retain the largest installed base while slurry reactors expand most quickly through retrofit investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese catalyst exports flow primarily to polyester manufacturing complexes across Southeast Asia and South Asia, while European imports concentrate on high-selectivity formulations for carbon capture-integrated demonstration projects.
China
Coal-to-chemical clusters in Shaanxi and Inner Mongolia drive procurement volumes for copper-zinc oxide-alumina catalyst systems. The Ministry of Ecology and Environment enforces dual carbon emission intensity benchmarks that accelerate project approvals with integrated carbon capture. Danhua Chemical operates expanding captive catalyst-served complexes in western provinces.
India
Polyester fiber capacity expansion in Gujarat and Maharashtra creates import demand for syngas-to-glycol catalyst formulations. The Bureau of Indian Standards mandates catalyst performance disclosure for coal-gasification project licensing. Reliance Industries and other integrators evaluate biomass-syngas catalyst tolerance for agricultural residue gasification pilots.
Germany
PET resin producers pilot non-chromite catalyst trials to qualify coal-chemical glycol for carbon border adjustment mechanism compliance. ECHA REACH restrictions force retirement of hexavalent chromium-containing chromite spinel formulations. BASF anchors European demand through fixed-bed reactor optimization services for selectivity-sensitive applications.
United States
Gulf Coast petrochemical operators monitor slurry-phase retrofit economics for potential syngas-to-glycol unit additions. EPA emission standards for coal-gasification facilities influence catalyst selection criteria for any future project development. Houston-area engineering firms assess technology licensing packages from Chinese slurry reactor retrofit experience.
Saudi Arabia
SABIC and downstream partners evaluate syngas-to-glycol catalyst integration within broader gas-to-chemicals diversification strategies. The Saudi Standards, Metrology and Quality Organization develops catalyst quality specifications for non-oil feedstock chemical projects. Jubail Industrial City hosts feasibility studies for membrane reactor configurations with noble metal selectivity advantages.
Syngas to Ethylene Glycol Catalyst Market Competitive Landscape
Player mix skews toward domestic Chinese manufacturers serving captive coal-chemical demand, with European specialists defending premium positions through selectivity-focused R&D intensity. The vendor base concentrates around three strategic tiers: state-affiliated chemical conglomerates with backward-integrated catalyst production, independent domestic formulators achieving cost parity through regional manufacturing scale, and multinational specialists leveraging noble metal expertise for membrane reactor applications. Dominant competitive moves include slurry-phase technology licensing partnerships and performance-guarantee contracting with durability warranty structures.
Among Chinese state-affiliated and independent formulators, HighChem and Danhua Chemical exemplify the captive production archetype, while Ningbo FarEast Catalytic Engineering occupies a position within the independent domestic tier. BASF and Johnson Matthey represent the multinational specialist segment. Johnson Matthey exemplifies noble metal catalyst R&D intensity, while BASF anchors European demand optimization. HighChem leverages captive catalyst production to serve expanding coal-chemical complexes.
| Leading Market Players |
|---|
| HighChem |
| Danhua Chemical |
| Ningbo FarEast Catalytic Engineering |
| Shanghai Pujing Chemical |
| Haiso Technology |
| Shangqiu Guolong New Materials |
| BASF |
| Clariant |
| Johnson Matthey |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with 8,000-hour durability guarantees lock in supply access for polyester integrators while compressing price visibility for spot-market participants. Chinese coal-chemical operators in Shaanxi and Inner Mongolia exploit this contracting shift to secure copper-based catalyst volumes ahead of slurry reactor retrofit cycles.
Pricing Analysis
Fixed-bed to slurry-phase generation pricing gaps separate mature copper-zinc oxide-alumina formulations from next-generation noble metal membrane configurations. Three-tier pricing structure across premium membrane, standard slurry, and economy fixed-bed levels reflects selectivity performance and carbon capture integration status. Cost compression in copper-based tiers intensifies because domestic manufacturing scale in western China has achieved import parity. Merchant polyester producers exhibit highest price sensitivity, while carbon capture-integrated project developers absorb premium membrane catalyst costs.
Supply Chain Analysis
China dominates catalyst precursor production, with Shaanxi and Inner Mongolia housing copper-zinc oxide-alumina manufacturing clusters. Domestic formulators draw from captive alumina supplies, imported palladium for membrane formulations, and chromite ore now restricted under REACH. Single-source vulnerability concentrates in noble metal refining capacity outside the country's borders. Distribution runs through state-affiliated chemical conglomerates with backward-integrated technical service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coal-chemical capacity expansion cycles position this market for recovery, with China's dual carbon enforcement accelerating slurry reactor retrofit investment waves.
For Market Incumbents: Secure performance-guarantee contracting structures with penalty clauses to defend against emerging domestic formulators achieving cost parity. Deepen upstream control over copper precursor refining in Shaanxi manufacturing clusters to offset noble metal price volatility exposure. For New Entrants and Emerging Players: Anchor in biomass-syngas tolerance formulations for Indian and Brazilian agricultural residue gasification pilots, where impurity-load catalyst performance remains underdeveloped. Target carbon border adjustment preparation trials among German PET resin producers seeking non-chromite qualification pathways. For Investors and Strategic Acquirers: Capital is best deployed toward membrane reactor engineering specialists with thin-film palladium deposition expertise, given capability scarcity constraining commercial deployment timelines. Watch for inflection in European carbon border enforcement stringency as signal for coal-chemical glycol qualification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Slurry Reactor Retrofit Licensing | Chinese operators transfer fixed-bed conversion expertise to Indian and Southeast Asian coal-chemical project developers. |
| Backward Integration into Catalyst Precursors | Polyester integrators in Inner Mongolia secure captive copper-zinc oxide supply chains against import volatility. |
| Membrane Reactor Engineering Partnership | Palladium thin-film deposition specialists bridge expertise gaps constraining noble metal catalyst deployment. |
| Biomass-Syngas Catalyst Co-Development | Agricultural residue gasification pilots in Brazil and India demand impurity-tolerant formulation validation. |
| Carbon Capture Integration Certification | European polyester producers qualify coal-chemical glycol for CBAM-compliant supply chains ahead of enforcement. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with plant managers at coal-chemical complexes, procurement leads at polyester integrators, catalyst R&D directors, and technical service heads; and secondary validation through customs trade data, Ministry of Ecology and Environment licensing disclosures, coal-chemical industry association reports, and SEC filings from multinational catalyst suppliers. Bottom-up unit economics triangulated against top-down capacity build-out projections.
Across the projection horizon, the analytical framework modeled catalyst demand by formulation chemistry, reactor configuration, end-use application, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules, replacement cycle compression rates, and technology substitution curves. Forecast inputs incorporated slurry reactor retrofit timelines and REACH-driven chromite formulation phase-out trajectories.
Material uncertainties — policy shifts in China's dual carbon enforcement intensity, palladium price volatility spikes, and membrane reactor engineering bottleneck resolution — sit outside the modeled envelope. Recalibration cycles align with material shifts in carbon border adjustment implementation schedules and slurry-phase technology licensing diffusion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Hydro-Processing Catalysts Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Catalyst Carrier Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Catalyst Regeneration Market
Catalysts
Global Zeolites Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Middle-East and Africa Refining Catalysts Market