
 Yogurt Drink Market | 2026-2036
Yogurt Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Yogurt Drink Market Intelligence
A shift from single-source milk procurement to multi-source dairy sourcing is broadening supply resilience across the yogurt drink value chain. Danone leverages its European dairy cooperative networks to secure consistent raw milk quality across seasons. Chobani anchors its US manufacturing base through direct contracts with domestic dairy farms in upstate New York and Idaho. Yakult Honsha sustains its proprietary Lactobacillus casei strain cultivation through tightly controlled in-house fermentation laboratories.
Yogurt drinks are fermented dairy beverages containing live or heat-treated bacterial cultures, typically with milk solids content between 8% and 12% and pH ranging from 3.8 to 4.5, produced through controlled fermentation followed by homogenization and aseptic filling. Probiotic yogurt formats command premium shelf positioning due to documented gut-health benefits and higher per-unit margins. Greek yogurt drinks occupy a growing niche among sports nutrition consumers seeking elevated protein density. Tetra Pak packaging dominates ambient distribution channels while bottle formats lead refrigerated retail.
FDA standards for Grade A pasteurized milk and voluntary USDA organic certification shape product labeling and interstate commerce compliance for US manufacturers. EFSA health claim regulations govern probiotic strain-specific marketing across European Union member states, while China's SAMR enforces GB standards for fermented dairy beverages including microbiological limits and additive permissions. Stakeholders must monitor evolving strain-specific health claim approvals and shifting sugar reduction mandates as formulation reform cycles compress.
Market Dynamics
Clean-label formulation mandates and cold-chain infrastructure gaps are forcing simultaneous investment in processing transparency and logistics resilience across yogurt drink manufacturing networks.
Growth Catalysts
- EFSA strain-specific health claims:European probiotic manufacturers leverage approved gut-health assertions to justify premium positioning in functional beverage aisles.
- Sports nutrition vertical:Elevated protein density formats capture post-workout consumption occasions previously dominated by whey isolates and ready-to-drink shakes.
- China's GB standards modernization:SAMR enforcement of updated microbiological limits accelerates domestic facility upgrades and foreign brand entry compliance.
Market Restraints
- Raw milk input volatility:Seasonal dairy cooperative pricing fluctuations compress margin predictability for fermented beverage producers dependent on spot procurement.
- Fermentation capacity concentration:Proprietary strain cultivation expertise clusters in Japanese and European laboratory networks, limiting new entrant access.
- Sugar reduction technical floor:Consumer taste thresholds and FDA labeling disclosure requirements constrain formulation flexibility below certain sweetness profiles.
Strategic Opportunities
- India's FSSAI functional food pathway:Emerging probiotic health claim approval mechanisms open positioning for gut-health focused entrants in underserved urban retail.
- Aseptic carton-to-bottle format convergence:Hybrid packaging technologies bridge ambient distribution reach with refrigerated premium perception.
- Direct-to-subscription channel development:Cold-chain enabled recurring delivery models bypass traditional retail slotting fee structures for established brands.
Industry Challenges
- Live culture stability expertise:Shelf-life extension without heat treatment demands specialized microbiology talent scarce outside established fermentation hubs.
- Multi-jurisdiction label compliance:Simultaneous FDA, EFSA, and SAMR claim alignment extends product development timelines and legal review costs.
- Legacy dairy processing retrofit:Existing pasteurized milk infrastructure requires capital-intensive clean-in-place system overhauls for probiotic production segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yogurt Drink Market |
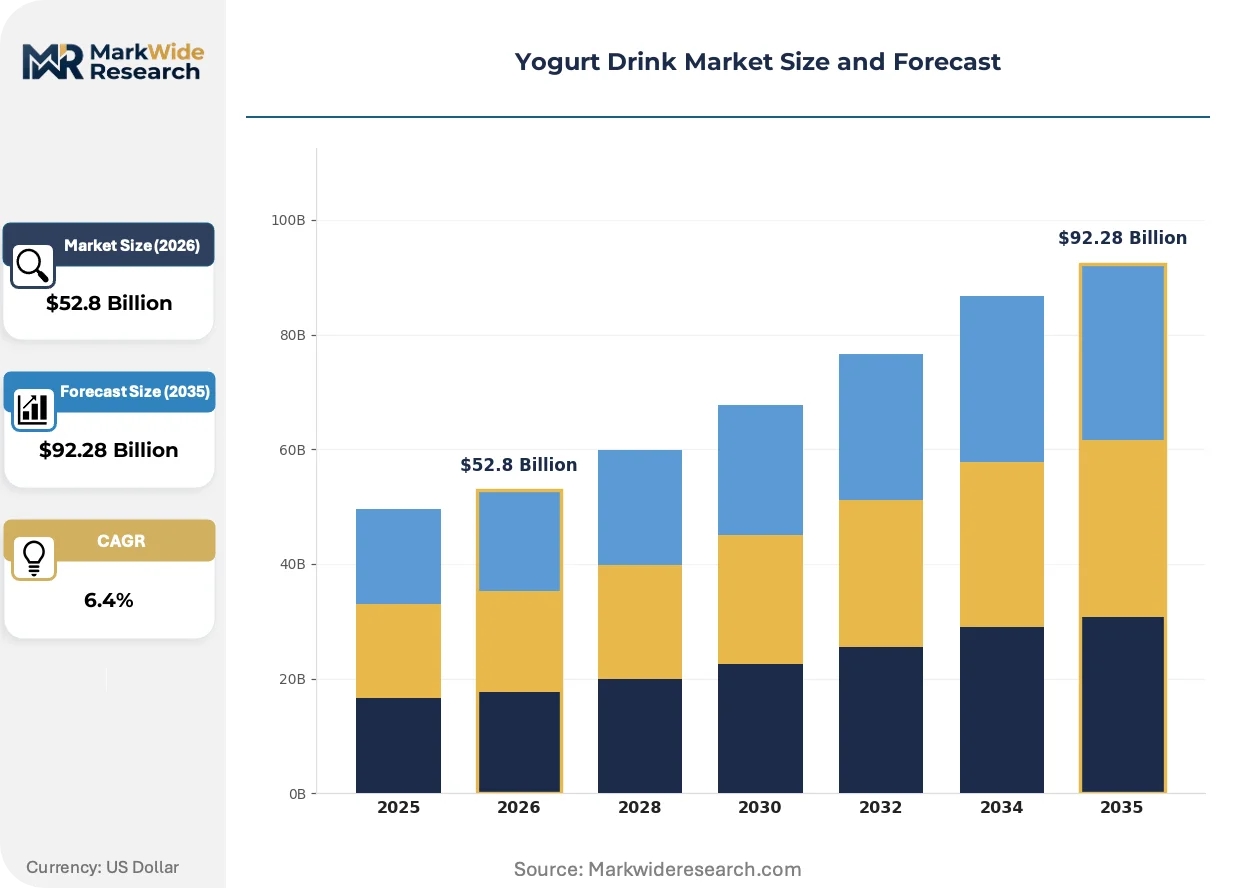
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic Yogurt, Greek Yogurt Drink, Flavored Yogurt, Organic Yogurt Packaging Type: Bottle, Tetra Pak, Pouch, Glass Jar Application: Breakfast Beverage, Snack, Sports Nutrition, Infant Nutrition Customer Type: Supermarkets, Convenience Stores, Online Retailers, Specialty Food Stores |
| Companies Covered | Chobani, Morinaga Nutritional Foods, Danone, Yili Group, Arla Foods, Yakult Honsha, Groupe Lactalis, Mengniu Dairy, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yogurt Drink Market Strategic Shifts & Innovations
Processing transparency and strain-specific efficacy documentation are compressing product development cycles while elevating technical barriers to formulation mimicry across competitive sets.
High-pressure processing technology is electrifying ambient-stable probiotic preservation by eliminating thermal degradation of live cultures. Functional beverage manufacturers in North American and European markets are accelerating adoption to bridge refrigerated and shelf-stable distribution gaps. This thermal alternative is electrifying category expansion into convenience retail channels previously inaccessible to live-culture formats.
China's SAMR implementation of GB 19302-2010 amendments for fermented milk products tightens additive permissions and microbiological enumeration methods. Domestic producers face reformulation deadlines while import brands navigate dual compliance with origin-country standards and Chinese technical barriers. Strain-specific documentation requirements are reshaping supplier qualification protocols for foreign entrants.
Subscription-based replenishment models are displacing conventional grocery replenishment for high-engagement probiotic consumers. Direct channels capture purchase data that enables personalized strain recommendations and flavor rotation. Urban clusters in Seoul, Shanghai, and São Paulo exhibit the highest concentration of platform-native yogurt drink subscribers.
Yogurt Drink Market Segmentation
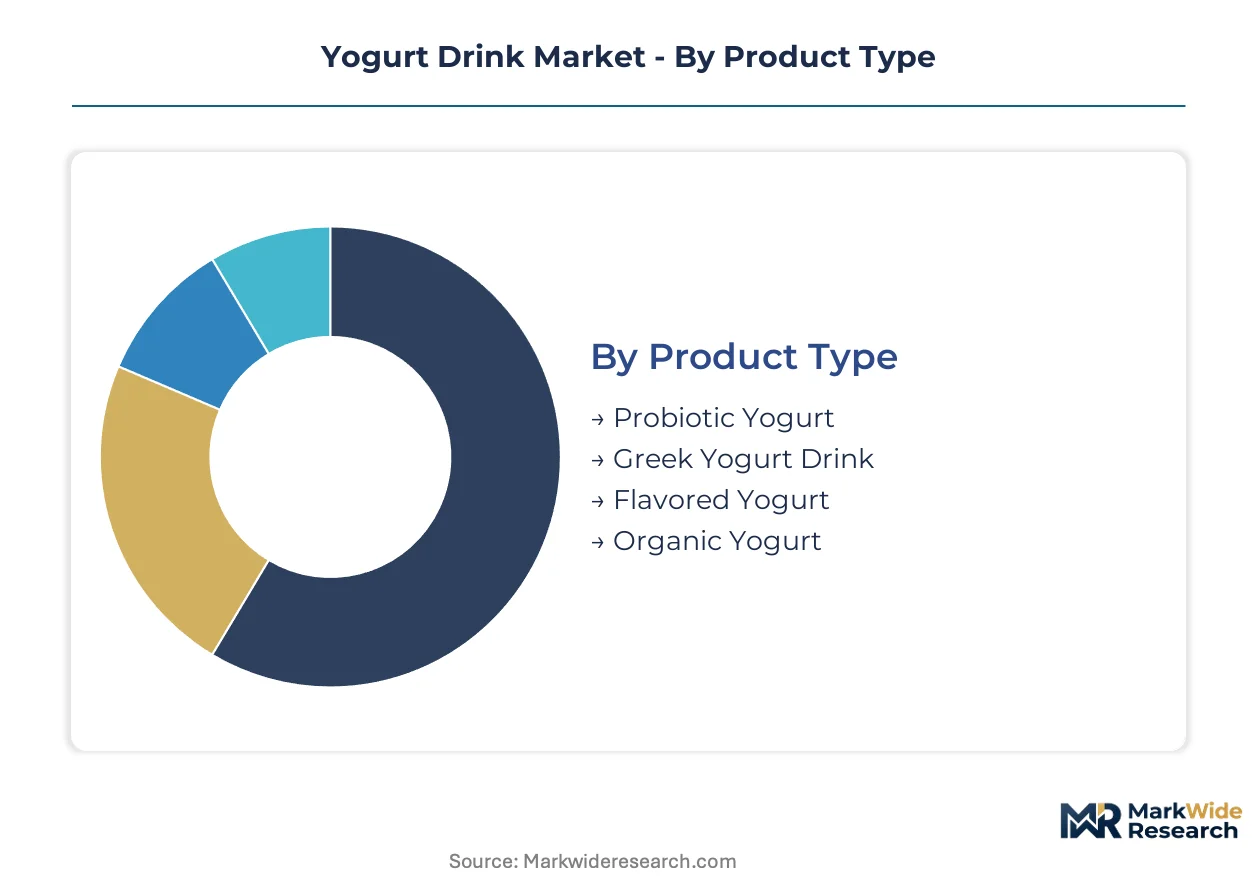
Yogurt drink segmentation reveals how regulatory requirements and distribution constraints fragment commercial opportunities across distinct product architectures. Manufacturers align formulation investments with specific certification pathways and channel access rules governing each category.
Product Type:
EFSA strain-specific approvals, USDA organic certification, and FDA Grade A standards create divergent compliance burdens across formulation categories.
- Probiotic Yogurt:Live bacterial cultures including Lactobacillus casei and Bifidobacterium strains deliver documented gut-health benefits. Demand concentrates in China's urban retail corridors where SAMR-enforced GB standards elevate domestic production costs and favor import brands with established strain documentation. Cold-chain requirements constrain ambient distribution reach.
- Greek Yogurt Drink:Strained processing yields protein density between 10-15 grams per serving, appealing to sports nutrition consumers. North American metropolitan clusters drive volume, with post-workout consumption occasions displacing whey isolate alternatives. Higher per-unit margins justify refrigerated logistics investment.
- Flavored Yogurt:Fruit-infused and sweetened variants dominate mass-market penetration. Sugar reduction mandates from FDA labeling rules and EU nutritional profiling compress formulation flexibility.
- Organic Yogurt:USDA organic and EU organic certification requirements govern feed sourcing and additive restrictions. Premium positioning targets parental purchasing for infant nutrition applications.
Leading the category by volume: Flavored Yogurt. Growing fastest: Probiotic Yogurt.
Packaging Type:
Format selection determines distribution economics through cold-chain dependency and shelf-life extension capabilities.
- Bottle:PET and HDPE formats dominate refrigerated retail with transparent product visibility. Convenience store channels in Japan and South Korea favor single-serve configurations. Higher logistics costs per unit limit rural penetration.
- Tetra Pak:Aseptic carton technology enables ambient-stable distribution without refrigeration. Emerging market expansion in India and Brazil leverages existing ambient dairy infrastructure. EFSA and FDA packaging material compliance adds qualification layers.
- Pouch:Flexible film formats reduce shipping weight and target on-the-go consumption. Limited structural integrity constrains premium positioning.
- Glass Jar:Premium perception supports specialty food store placement. Weight and breakage rates elevate supply chain costs.
Tetra Pak commands the widest geographic footprint. Bottle formats capture the highest revenue per liter.
Application:
Consumption occasion segmentation aligns product development with distinct nutritional positioning and pricing tiers.
- Breakfast Beverage:Meal replacement positioning targets time-constrained urban professionals. China's tier-one cities exhibit concentrated adoption where yogurt drinks displace traditional soy milk.
- Snack:Mid-day consumption occasions favor portable formats with moderate sweetness profiles. Convenience store distribution networks in Tokyo and Seoul drive volume.
- Sports Nutrition:Elevated protein and electrolyte fortification commands gym-adjacent retail placement. North American and Australian markets show strongest channel development.
- Infant Nutrition:Stringent microbiological limits under China's GB standards and FDA infant formula regulations govern production facility segregation. Parental premium willingness supports organic certification investment.
Breakfast Beverage anchors current volume. Sports Nutrition exhibits the steepest expansion trajectory.
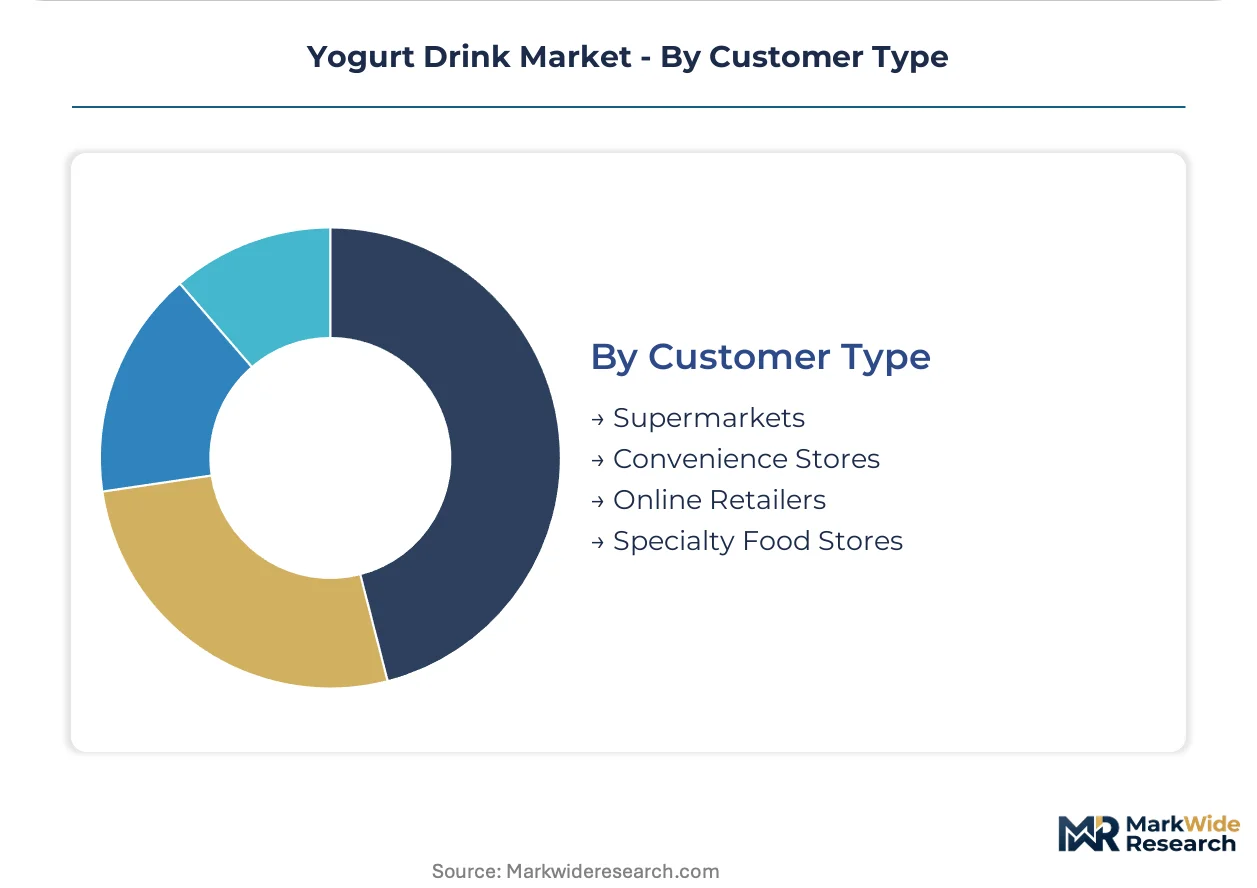
Customer Type:
Channel selection dictates margin structure through slotting fees, data access, and cold-chain investment requirements.
- Supermarkets:Multi-format shelf space accommodates full product range from economy to premium tiers. Walmart and Carrefour procurement consolidation in China and Mexico compresses supplier margins.
- Convenience Stores:7-Eleven and Lawson networks in Japan and Thailand prioritize grab-and-go formats with rapid inventory turnover. Limited refrigeration capacity favors ambient-stable variants.
- Online Retailers:Alibaba and JD.com platforms in China enable direct-to-consumer cold-chain delivery. Subscription models capture recurring purchase data for personalized strain recommendations.
- Specialty Food Stores:Whole Foods Market and regional organic chains emphasize clean-label and local sourcing narratives. Smaller order quantities elevate per-unit logistics costs.
Supermarkets maintain volume leadership. Online Retailers are climbing the fastest among channel types.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy cooperative networks in France, Wisconsin, and Hokkaido supply the milk solids that anchor yogurt drink manufacturing across three continents. Cold-chain infrastructure density and probiotic strain cultivation expertise cluster unevenly, concentrating premium production capacity in specific metropolitan corridors.
China
Urban breakfast beverage adoption in Shanghai and Beijing accelerates probiotic format penetration. SAMR enforces GB 19302-2010 amendments that tighten microbiological enumeration methods and additive permissions. Yili Group and Mengniu Dairy dominate retail shelf space through distribution networks concentrated in tier-one cities.
United States
Sports nutrition consumption occasions drive Greek yogurt drink demand in metropolitan fitness corridors. FDA Grade A pasteurized milk standards govern interstate commerce compliance and labeling disclosure. Chobani anchors manufacturing through direct dairy farm contracts in upstate New York and Idaho processing facilities.
Japan
Convenience store channels in Tokyo and Osaka sustain single-serve probiotic consumption patterns. METI oversight aligns with FOSHU functional food claim pathways for strain-specific gut-health positioning. Yakult Honsha maintains proprietary Lactobacillus casei cultivation through tightly controlled in-house fermentation laboratories in the Kanto region.
France
European dairy cooperative networks supply consistent raw milk quality across seasonal fluctuations. EFSA strain-specific health claim regulations govern probiotic marketing assertions across EU member states. Danone leverages processing infrastructure in the Normandy dairy basin for fermented beverage production.
India
Emerging urban middle-class adoption in Mumbai and Delhi-NCR expands addressable market for functional dairy formats. FSSAI functional food pathways introduce probiotic health claim approval mechanisms for gut-health positioning. Domestic producers navigate reformulation requirements while import brands establish cold-chain distribution partnerships.
Yogurt Drink Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers secure proprietary strain access and cold-chain distribution reach. The vendor base clusters around three tiers: multinational dairy conglomerates with integrated fermentation capacity, regional specialists leveraging local dairy cooperative relationships, and functional beverage entrants targeting sports nutrition verticals. Two competitive moves define current positioning: technology licensing agreements for high-pressure processing capabilities, and geographic expansion through direct-to-subscription channel development.
Among multinational dairy conglomerates, Danone, Yakult Honsha, and Nestlé occupy positions that exemplify divergent strategic archetypes. Danone represents the European cooperative-integrated model with strain-specific health claim portfolios. Yakult Honsha anchors the Japanese laboratory-centric approach with proprietary culture cultivation expertise. Nestlé sits within the diversified nutrition conglomerate tier, leveraging cross-category functional food infrastructure.
| Leading Market Players |
|---|
| Chobani |
| Morinaga Nutritional Foods |
| Danone |
| Yili Group |
| Arla Foods |
| Yakult Honsha |
| Groupe Lactalis |
| Mengniu Dairy |
| Nestlé |
| Others |
Cost & Logistics Intelligence
Breakfast beverage procurement consolidation in China's tier-one cities anchors a three-tier pricing structure across premium, standard, and economy levels. Cold-chain logistics bundling separates refrigerated probiotic formats from ambient-stable Tetra Pak variants, with subscription delivery models capturing price-insensitive urban professionals.
Pricing Analysis
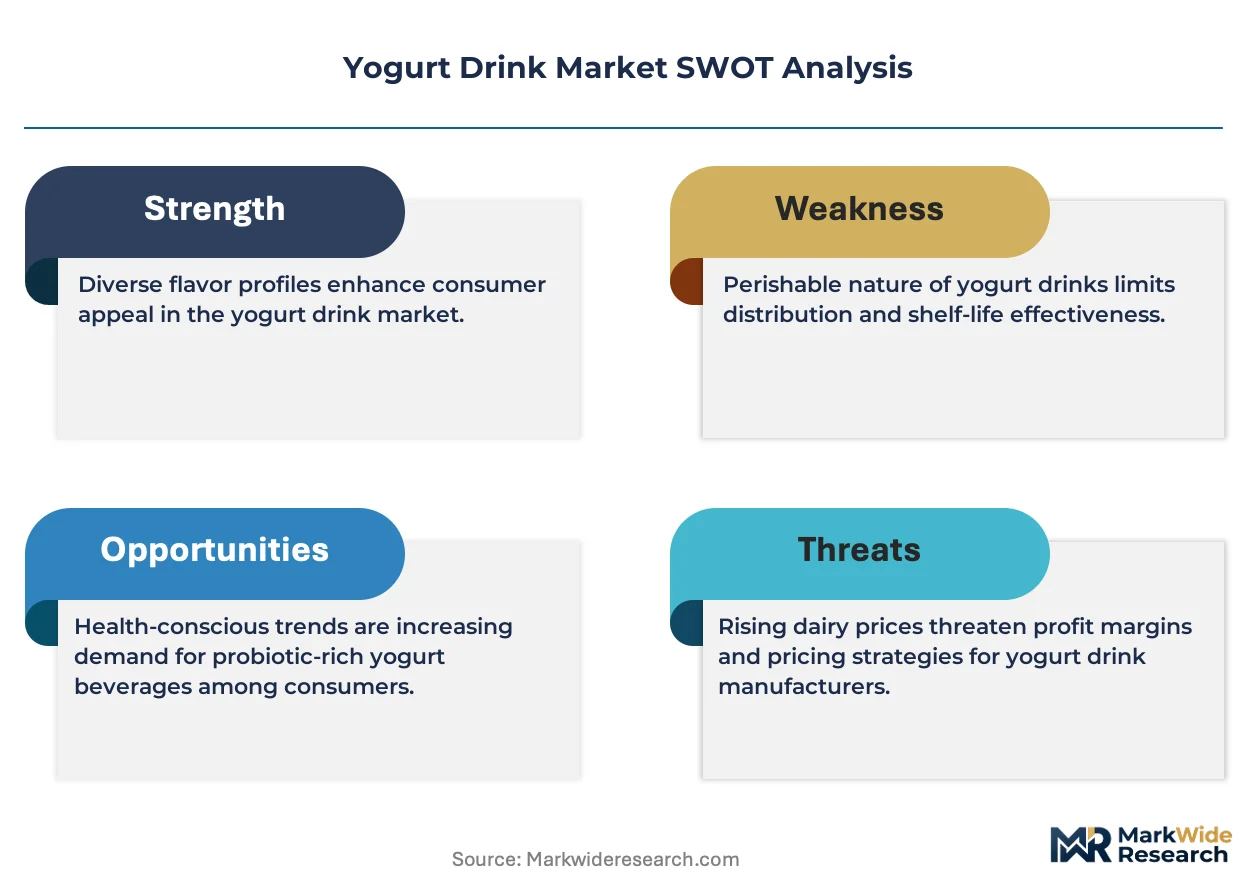
Cold-chain service bundling defines the pricing architecture, with refrigerated delivery premiums unbundled from base product costs in direct-to-consumer channels. Certification grade under Greek yogurt drink positioning, while volume scale discounts dominate supermarket procurement negotiations. Pricing pressure stems from raw milk cooperative spot pricing volatility compressing margin predictability. Mass-market flavored yogurt buyers exhibit highest price sensitivity, whereas sports nutrition consumers accept elevated per-unit costs for protein density claims.
Supply Chain Analysis
Regional distribution centers in France, Wisconsin, and Hokkaido form the warehouse backbone for fermented dairy feedstock aggregation. Probiotic strain cultivation expertise clusters in Japan and European laboratory networks, creating single-source vulnerability for live culture stability. Raw milk solids, proprietary bacterial cultures, and aseptic packaging materials constitute critical input dependencies. Distribution runs through cold-chain-enabled hub-and-spoke patterns for refrigerated formats, while ambient-stable variants leverage conventional dairy logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary strain cultivation and captive cold-chain infrastructure has become the defining competitive race, with upstream control over fermentation expertise separating margin leaders from commodity assemblers.
For Market Incumbents: Anchor manufacturing resilience through backward integration into dairy cooperative equity stakes and in-house fermentation laboratory capacity. Defend against functional beverage entrants by locking exclusive sports nutrition distribution partnerships with gym-adjacent retail chains. Prioritize SAMR strain documentation investment to maintain China market access as GB standards tighten.
For New Entrants and Emerging Players: India's FSSAI functional food pathway offers the most penetrable regulatory entry point for probiotic health claim positioning. Target underserved subscription replenishment demand in São Paulo and Seoul urban clusters through direct-to-consumer cold-chain partnerships. Pursue white-label manufacturing arrangements with established dairy processors to bypass capital-intensive fermentation infrastructure requirements.
For Investors and Strategic Acquirers: The window for entry favors laboratory-centric specialists with proprietary culture banks and documented EFSA strain-specific approvals. Long-term viability hinges on acquisition targets possessing scalable high-pressure processing capabilities for ambient-stable probiotic preservation. Monitor India's FSSAI probiotic claim approval velocity as the critical inflection signal for emerging market expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Cultivation Investment | Yakult Honsha's laboratory model demonstrates margin protection through exclusive Lactobacillus casei control. |
| High-Pressure Processing Adoption | Thermal alternative technology bridges refrigerated and ambient distribution gaps for live culture formats. |
| Direct-to-Subscription Channel Development | Recurring delivery models bypass traditional retail slotting fees while capturing personalized consumption data. |
| Cold-Chain Infrastructure Partnership | JD.com and Alibaba logistics networks enable probiotic stability guarantees in China's urban corridors. |
| Sports Nutrition Format Extension | Elevated protein density positioning captures post-workout occasions from whey isolate incumbents. |
Research Approach
Trade databases, dairy cooperative pricing records, and regulatory filing repositories formed the secondary backbone for supply-side validation. Primary interviews with fermentation technology directors, cold-chain logistics operators, supermarket category buyers, and FSSAI regulatory consultants combined with bottom-up and top-down triangulation across manufacturer production disclosures and customs import records.
Bottom-up volume modeling aggregated capacity utilization rates across probiotic, Greek, and flavored yogurt drink production lines, while top-down value estimates calibrated against Nielsen retail audit data and Circana channel shipment reports. Segmentation dimensions included product type, packaging format, consumption occasion, and customer channel across the projection horizon. CAGRs derived from historical volume trajectories and elasticity-adjusted price evolution assumptions, with strain-specific health claim approval timelines and cold-chain infrastructure buildout rates as key forecast inputs.
Revisions become necessary when SAMR enforcement intensity shifts, EFSA strain approval pathways accelerate, or high-pressure processing cost curves steepen beyond modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Whipping Cream Market
Dairy Products
Cheese Concentrate Market
Dairy Products
Global Milk Powder Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Fluid Milk Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
Organic Dairy Products Market
Dairy Products
United States Casein Market
Dairy Products
White Cheese Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Low Calorie Whipped Cream Market