
 Organic Dairy Products Market | 2026-2036
Organic Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Dairy Products Market Outlook
Subscription-based replenishment services for organic milk and yogurt is realigning how processors capture recurring revenue beyond the dairy case. Danone S.A. leverages its direct-to-consumer infrastructure to sustain repeat purchase rates in urban markets. Organic Valley anchors its cooperative model on regional sourcing transparency, while Arla Foods Group competes through controlled-channel distribution across Northern European retail networks.
Organic dairy products are derived from livestock raised under certified organic protocols requiring pasture access, antibiotic-free husbandry, and non-GMO feed regimens, with milk composition standards typically requiring fat content testing and somatic cell count thresholds below conventional limits. Organic milk occupies the largest revenue pool due to daily consumption frequency and established cold-chain logistics, though organic yogurt is recording the fastest volume trajectory as functional probiotic positioning attracts health-focused buyers. Specialty stores and online retail channels are capturing margin premiums that supermarkets struggle to match on standard organic SKUs.
The USDA National Organic Program governs certification and labeling standards in the United States, while the EU Organic Regulation enforces equivalent feed and processing rules across member states, and India's FSSAI has introduced draft organic dairy certification guidelines that will reshape import eligibility. These frameworks elevate compliance costs but simultaneously create defensible market access barriers for certified operators. Stakeholders must monitor evolving equivalency agreements between major certifying jurisdictions to anticipate supply reallocation and pricing volatility.
Market Dynamics
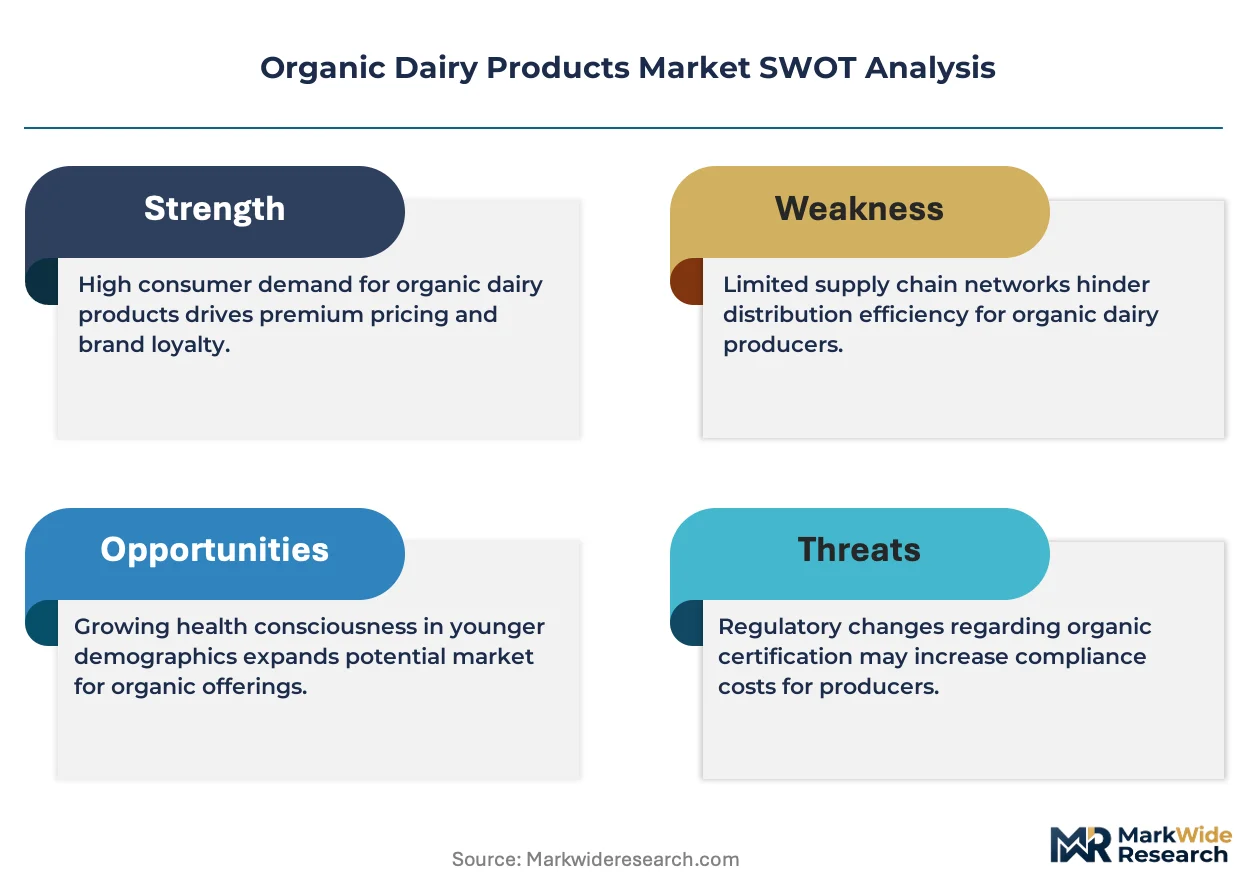
EU Organic Regulation feed-source traceability mandates are forcing processors to revalidate supplier networks, compressing procurement timelines and elevating compliance costs across the value chain.
Growth Catalysts
- Pasture-access certification standards:The EU Organic Regulation's livestock welfare protocols create defensible pricing power for certified producers in German retail channels.
- Direct-to-consumer infrastructure:Urban subscription replenishment services capture recurring revenue streams beyond traditional dairy case placements.
- Functional probiotic positioning:Health-focused buyer segments drive volume expansion in organic yogurt through gut-health marketing claims.
Market Restraints
- Organic feed input cost volatility:Non-GMO grain prices fluctuate with climate-driven harvest variability, squeezing margin structures for pasture-dependent operations.
- Supplier concentration in Northern Europe:Arla Foods Group and cooperative networks dominate controlled-channel distribution, limiting new entrant shelf access.
- Cold-chain infrastructure gaps:Temperature-controlled logistics requirements constrain geographic expansion into emerging markets with unreliable electricity grids.
Strategic Opportunities
- Indian market entry timing:FSSAI draft organic dairy certification guidelines will reshape import eligibility, creating first-mover advantages for pre-certified exporters.
- Specialty store channel premiums:Margin capture exceeds supermarket benchmarks where staff expertise justifies price positioning for certified clean-label SKUs.
- Blockchain-IoT feed traceability:Converging technologies enable real-time pasture verification that satisfies tightening EU audit requirements.
Industry Challenges
- Veterinary antibiotic-free husbandry expertise:Preventive health management skills lag demand as conventional dairy veterinarians retrain for organic protocols.
- Multi-jurisdiction equivalency navigation:USDA National Organic Program and EU Organic Regulation alignment gaps create certification duplication costs for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Dairy Products Market |
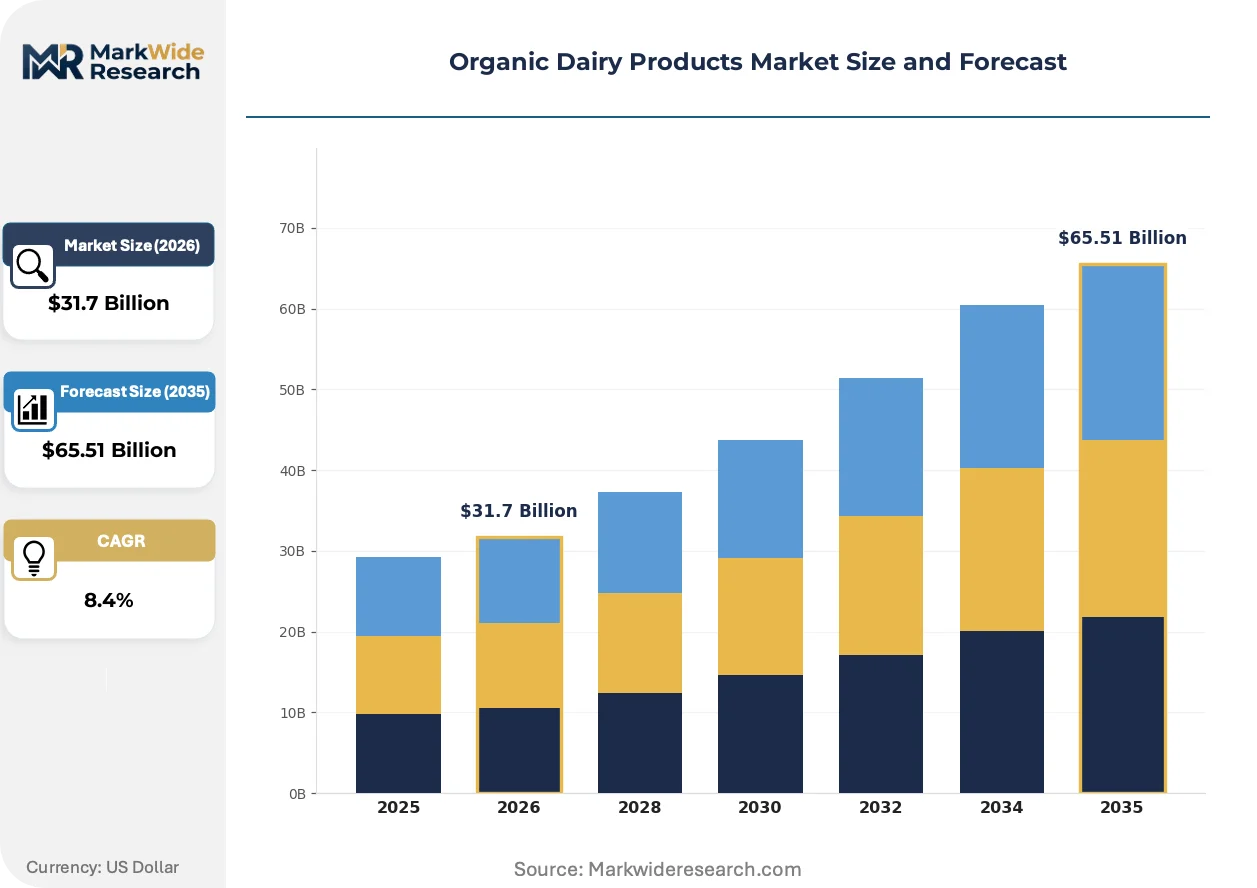
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $65.51 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Milk, Organic Cheese, Organic Yogurt, Organic Butter End User: Households, Restaurants, Cafés, Grocery Stores Distribution Channel: Online Retail, Supermarkets, Farmers' Markets, Specialty Stores Packaging Type: Bottles, Tetra Packs, Cartons, Jars |
| Companies Covered | Arla Foods Group, Aurora Organic Dairy, Organic Valley, Horizon Organic, Danone S.A., Fonterra Co-operative Group Limited, Acorn Dairy Ltd., Andechser Molkerei Scheitz GmbH, Barambah Organics Operations Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Dairy Products Market Strategic Shifts
Digital traceability infrastructure is compressing verification timelines while subscription commerce restructures purchase frequency patterns across urban consumer bases.
Blockchain-enabled feed provenance tracking is consolidating audit compliance workflows for processors facing EU Organic Regulation documentation demands. German discounters and premium chains alike now require batch-level pasture verification. This technology is consolidating supplier qualification processes that previously required separate paper trails for each certification body.
The EU Green Deal's Farm to Fork Strategy tightens methane emission benchmarks for livestock operations, accelerating manure management technology adoption. Northern European dairy cooperatives invest in anaerobic digestion systems to maintain certification eligibility. Organic Valley's regional sourcing transparency model faces pressure to quantify carbon footprint reductions beyond existing pasture-access standards.
Buyer concentration in subscription replenishment services alters volume forecasting accuracy for processors accustomed to supermarket promotional cycles. Direct-to-consumer platforms displace traditional wholesale relationships in metropolitan markets. Germany exhibits the most advanced penetration of this channel shift, where urban households prioritize convenience alongside certified origin claims.
Organic Dairy Products Market Segmentation
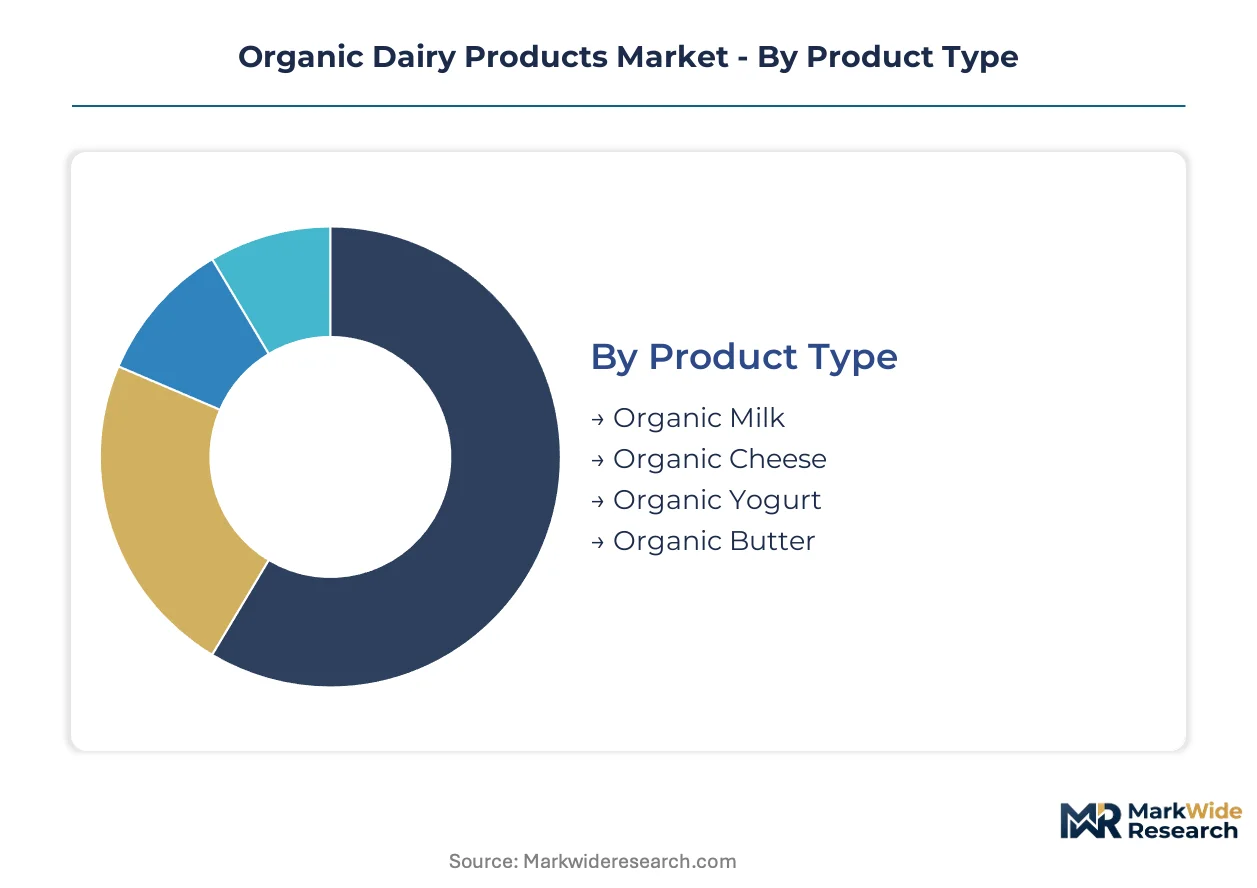
Segmentation in organic dairy reveals how certification standards, cold-chain requirements, and purchase frequency create divergent margin profiles across product formats. Understanding these divisions exposes where pricing power concentrates and where logistics constraints erode profitability.
Product Type:
Specification tiers in organic dairy separate daily-consumption staples from discretionary specialty items with distinct shelf-life and processing complexity.
- Organic Milk:Fluid milk commands the largest revenue pool due to daily consumption frequency and established cold-chain logistics networks. German discounters have normalized organic milk as a standard category, compressing premium capture for standard SKUs while specialty variants retain margin.
- Organic Yogurt:Functional probiotic positioning attracts health-focused buyers, with volume climbing fastest as gut-health marketing claims expand the addressable base beyond traditional dairy consumers.
- Organic Cheese:Aged varieties require extended inventory cycles and specialized affinage facilities, limiting producer participation to operations with sufficient scale for dedicated aging rooms.
- Organic Butter:Fat-standard specifications and seasonal cream availability create procurement complexity that favors integrated processors with captive organic cream supplies.
Mature deployment sits with organic milk. Newer deployment is concentrated in organic yogurt.
End User:
Volume concentration varies sharply between at-home consumption and foodservice channels with divergent certification documentation requirements.
- Households:Subscription replenishment services capture recurring revenue streams in urban markets, with direct-to-consumer platforms displacing traditional wholesale relationships for metropolitan buyers.
- Grocery Stores:Retail chains expand shelf space for organic SKUs as consumer willingness-to-pay for certified clean-label dairy climbs, though margin premiums lag specialty store benchmarks.
- Restaurants:Menu certification requirements and supplier audit demands limit organic dairy adoption to premium positioning establishments with dedicated procurement staff.
- Cafés:Specialty coffee culture drives organic milk demand for barista-quality foam performance, with origin transparency claims supporting price positioning.
Volume leadership belongs to households. Margin expansion concentrates in grocery stores.
Distribution Channel:
Channel selection determines traceability documentation depth and temperature-control investment requirements.
- Specialty Stores:Staff expertise justifies price positioning for certified clean-label SKUs, capturing margin premiums that supermarkets struggle to match on standard organic products.
- Online Retail:Urban subscription replenishment services restructure purchase frequency patterns, altering volume forecasting accuracy for processors accustomed to supermarket promotional cycles.
- Supermarkets:Standard organic SKUs face price compression as discounters normalize the category, pushing differentiation toward private-label partnerships and exclusive regional sourcing claims.
- Farmers' Markets:Direct producer relationships enable batch-level pasture verification that satisfies tightening EU Organic Regulation audit requirements for local buyer segments.
Established infrastructure sits with supermarkets. Channel expansion is accelerating in online retail.
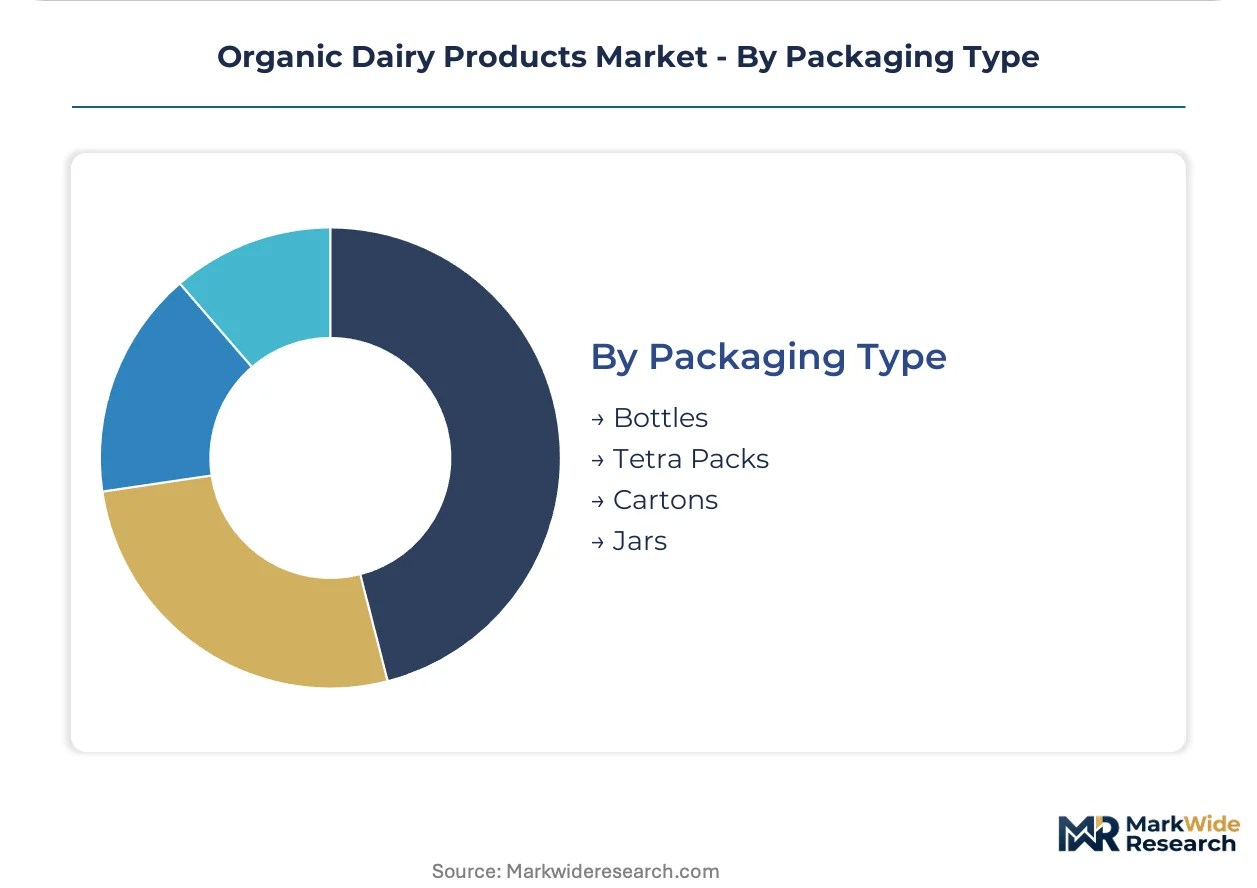
Packaging Type:
Material selection balances shelf-life extension, sustainability positioning, and cold-chain compatibility.
- Tetra Packs:Aseptic processing enables ambient distribution, reducing cold-chain dependency for processors targeting markets with unreliable electricity infrastructure.
- Bottles:HDPE and glass formats dominate fluid milk with established recycling streams, though light-protection specifications vary by regional retailer requirements.
- Cartons:Gable-top formats retain cost advantages for short-shelf-life products in high-turnover retail environments.
- Jars:Premium positioning for yogurt and specialty dairy supports higher price points, with reusable and deposit-return systems gaining traction in Northern European markets.
Volume concentration sits with bottles. Format innovation is concentrated in Tetra Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces surplus organic dairy for export while the United States imports specialty cheeses to bridge domestic supply gaps. India cultivates emerging demand through draft FSSAI certification frameworks. Cold-chain limitations constrain distribution in tropical zones regardless of production capacity.
Germany
Discounters Aldi and Lidl have normalized organic milk as a standard category, eroding premium capture for basic SKUs while specialty variants retain margin. The EU Organic Regulation enforces feed-source traceability mandates that processors must satisfy through revalidated supplier networks. Bavaria's dairy cooperatives anchor controlled-channel distribution across Northern European retail networks.
United States
Urban subscription replenishment services capture recurring revenue streams beyond traditional dairy case placements. The USDA National Organic Program governs certification and labeling standards, creating compliance costs that simultaneously erect market access barriers. Wisconsin and California dairy clusters supply fluid milk to metropolitan markets where direct-to-consumer platforms displace wholesale relationships.
India
Middle-class households in Delhi and Mumbai demonstrate willingness-to-pay for certified clean-label dairy as gut-health awareness expands. FSSAI draft organic dairy certification guidelines will reshape import eligibility, creating first-mover advantages for pre-certified exporters. Maharashtra's cooperatives invest in cold-chain infrastructure to reduce spoilage rates in ambient temperature distribution.
France
Specialty stores capture margin premiums that supermarkets struggle to match on standard organic SKUs through staff expertise and origin transparency claims. The EU Green Deal's Farm to Fork Strategy tightens methane emission benchmarks for livestock operations. Brittany's dairy processors deploy anaerobic digestion systems to maintain certification eligibility under tightening environmental protocols.
China
Functional probiotic positioning in organic yogurt attracts health-focused buyers in Shanghai and Beijing metropolitan markets. SAMR and national GB standards enforce labeling requirements that elevate compliance costs for imported products. Inner Mongolia's pastoral zones supply raw milk to processors targeting premium-tier urban distribution channels.
Organic Dairy Products Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the organic dairy value chain. Vertically integrated cooperatives control upstream feed sourcing and downstream distribution, while specialized processors outsource procurement to third-party organic grain suppliers. Three archetypes dominate: Northern European cooperative networks, multinational CPG conglomerates with direct-to-consumer infrastructure, and regional specialists emphasizing transparency claims. Competitive moves concentrate on strategic partnerships with subscription platforms and geographic expansion through equivalency certification in emerging markets.
Within the cooperative archetype, Organic Valley and Arla Foods Group exemplify member-owned structures that anchor regional sourcing transparency models. Danone S.A. occupies a position representing multinational scale advantages in direct-to-consumer urban distribution. These three entities illustrate how capital structure and channel strategy determine competitive positioning across certification-intensive markets.
| Leading Market Players |
|---|
| Arla Foods Group |
| Aurora Organic Dairy |
| Organic Valley |
| Horizon Organic |
| Danone S.A. |
| Fonterra Co-operative Group Limited |
| Acorn Dairy Ltd. |
| Andechser Molkerei Scheitz GmbH |
| Barambah Organics Operations Pty Ltd. |
| Others |
Value Chain & Pricing Dynamics
Blockchain-enabled feed traceability investments simultaneously compress audit compliance costs and consolidate supplier qualification workflows, reshaping procurement economics for processors facing EU Organic Regulation documentation demands. German discounters have normalized organic milk as a standard category, eroding premium capture for basic SKUs while specialty variants retain margin through batch-level pasture verification.
Pricing Analysis
Margin tightening in standard organic SKUs reflects discounter normalization of the category across German retail channels. Three-tier pricing structure across premium, standard, and economy levels separates specialty store SKUs with staff expertise justification from supermarket private-label partnerships. Cost-down pressure on fluid milk accelerates because Aldi and Lidl have captured volume leadership through aggressive shelf-space expansion. Household subscription services exhibit lowest price sensitivity, while restaurant procurement with menu certification requirements faces highest cost scrutiny.
Supply Chain Analysis
Direct-to-consumer platforms handle urban subscription demand, displacing traditional wholesale relationships in metropolitan markets. Geographic supply concentration centers on Germany, the United States, and France, with Northern European cooperatives dominating controlled-channel distribution. Raw material dependencies rest on non-GMO grain inputs, organic pasture acreage, and certified antibiotic-free livestock herds. Single-source vulnerability in organic feed sourcing creates exposure to climate-driven harvest variability. Distribution runs through cold-chain logistics networks with temperature-controlled requirements constraining emerging market expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around processors with pre-certified equivalency across USDA and EU Organic Regulation frameworks, as compliance cost escalation forces subscale operators toward cooperative membership or exit.
For Market Incumbents: Extend backward integration into captive organic feed production to insulate margin structures from grain price volatility. Anchor controlled-channel distribution partnerships with subscription platforms in German and US urban markets. Arla Foods Group's cooperative model demonstrates how regional sourcing transparency claims defend shelf position against multinational CPG conglomerates with direct-to-consumer infrastructure.
For New Entrants and Emerging Players: Launch via specialty store channels where staff expertise justifies price positioning and margin premiums exceed supermarket benchmarks. Target Indian market entry timing ahead of FSSAI draft certification guideline finalization to capture first-mover import eligibility advantages. Pursue blockchain-IoT feed traceability partnerships that satisfy tightening EU audit requirements without legacy paper trail conversion costs.
For Investors and Strategic Acquirers: Exit pathways concentrate in cooperative network membership conversions and multinational CPG bolt-on acquisitions of regional transparency specialists. Long-term viability across the analysis window hinges on equivalency certification breadth across USDA, EU, and emerging FSSAI frameworks. Monitor equivalency agreement negotiations between major certifying jurisdictions as the signal for supply reallocation and pricing volatility inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed Production | Captive non-GMO grain supply insulates processors from climate-driven harvest price spikes. |
| Direct-to-Consumer Platform Launch | Urban subscription services capture recurring revenue beyond traditional dairy case placements. |
| Blockchain-IoT Feed Traceability Deployment | Real-time pasture verification satisfies tightening EU Organic Regulation audit documentation demands. |
| Equivalency Certification Investment | Pre-certification across USDA and EU frameworks creates defensible market access barriers. |
| Specialty Store Channel Expansion | Staff expertise justifies price positioning where margin premiums exceed supermarket benchmarks. |
Study Parameters
Document review covered EU Organic Regulation implementation guidance, USDA National Organic Program certification standards, and FSSAI draft guidelines, complemented by interviews with dairy cooperative procurement directors, retail category buyers, and cold-chain logistics operators. Secondary validation drew from customs trade data, SEC filings of listed processors, and Nielsen retail audit information. Bottom-up volume modeling and top-down value reconciliation triangulated across primary fieldwork and secondary source verification.
Segmentation outputs reflect product type, distribution channel, and end-user dimensions modeled across the projection horizon. CAGRs were derived from historical trajectory analysis and forward-looking scenario weighting. Forecast inputs incorporated organic pasture acreage expansion rates, non-GMO grain price indices, and equivalency agreement negotiation timelines between certifying jurisdictions.
Feed-source traceability mandate delays, FSSAI certification guideline revisions, and cold-chain infrastructure buildout pace are the dominant revision risks for forecast accuracy. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Sweet Whey Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Whipping Cream Market
Dairy Products
Organic Dairy Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Cheese Color Market
Dairy Products
Japan Casein Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Cream Powder Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Fermented Dairy Products Market