
 USA Commercial Walk-In Refrigeration Market | 2026-2036
USA Commercial Walk-In Refrigeration Market Size, Share, and Industry Trends Forecast 2026-2036
USA Commercial Walk-In Refrigeration Market Analytics
Regional grocery chains and cold-storage logistics operators is redrawing the buyer landscape for commercial walk-in refrigeration. Hussmann Corporation leverages its manufacturing scale to dominate supermarket installations across the Midwest. Amerikooler specializes in custom-engineered solutions for food distribution warehouses requiring precise temperature zoning. Bally Refrigerated Boxes anchors its position through backward integration into insulated panel production, controlling material costs and delivery timelines.
Commercial walk-in refrigeration encompasses engineered cold-storage enclosures with insulated panels typically rated at R-25 to R-32 thermal resistance, designed to maintain temperatures from -10°F to 55°F for perishable inventory preservation. These systems employ vapor-compression cycles with evaporators mounted inside the conditioned space and condensing units placed remotely or on the enclosure roof. Walk-in coolers and walk-in freezers represent the mature volume core, while natural refrigerant systems using CO2 and hydrocarbon blends capture the fastest growth trajectory as operators phase out high-GWP HFCs. Modular and off-site installation categories are expanding as labor scarcity and project speed requirements reshape procurement patterns across restaurant and convenience store chains.
The EPA enforces refrigerant phaseout timelines under the AIM Act, while the DOE imposes minimum energy conservation standards on commercial refrigeration equipment, together compressing the viable product portfolio toward lower-GWP, higher-efficiency platforms. OSHA and state-level building codes govern enclosure safety, electrical integration, and ammonia detection where applicable. Stakeholders must track state-level adoption of ASHRAE standards and utility rebate programs that increasingly tie capital incentives to natural refrigerant commitments and connected monitoring capabilities.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing a wholesale equipment replacement cycle across foodservice and retail cold-chain infrastructure, compressing product lifecycles and retrofit timelines.
Growth Catalysts
- AIM Act Compliance Deadlines:The EPA's refrigerant phasedown mandates are compelling operators to accelerate replacement of high-GWP equipment, creating immediate pull-through for natural refrigerant systems in Texas and Florida foodservice corridors.
- Cold-Chain Logistics Expansion:Regional grocery chains and third-party logistics operators are building temperature-controlled distribution nodes, driving modular walk-in installations across California's Central Valley.
- CO2 Transcritical Technology:Transcritical CO2 systems are capturing specification share in supermarket and warehouse applications as operators seek future-proofed compliance paths.
Market Restraints
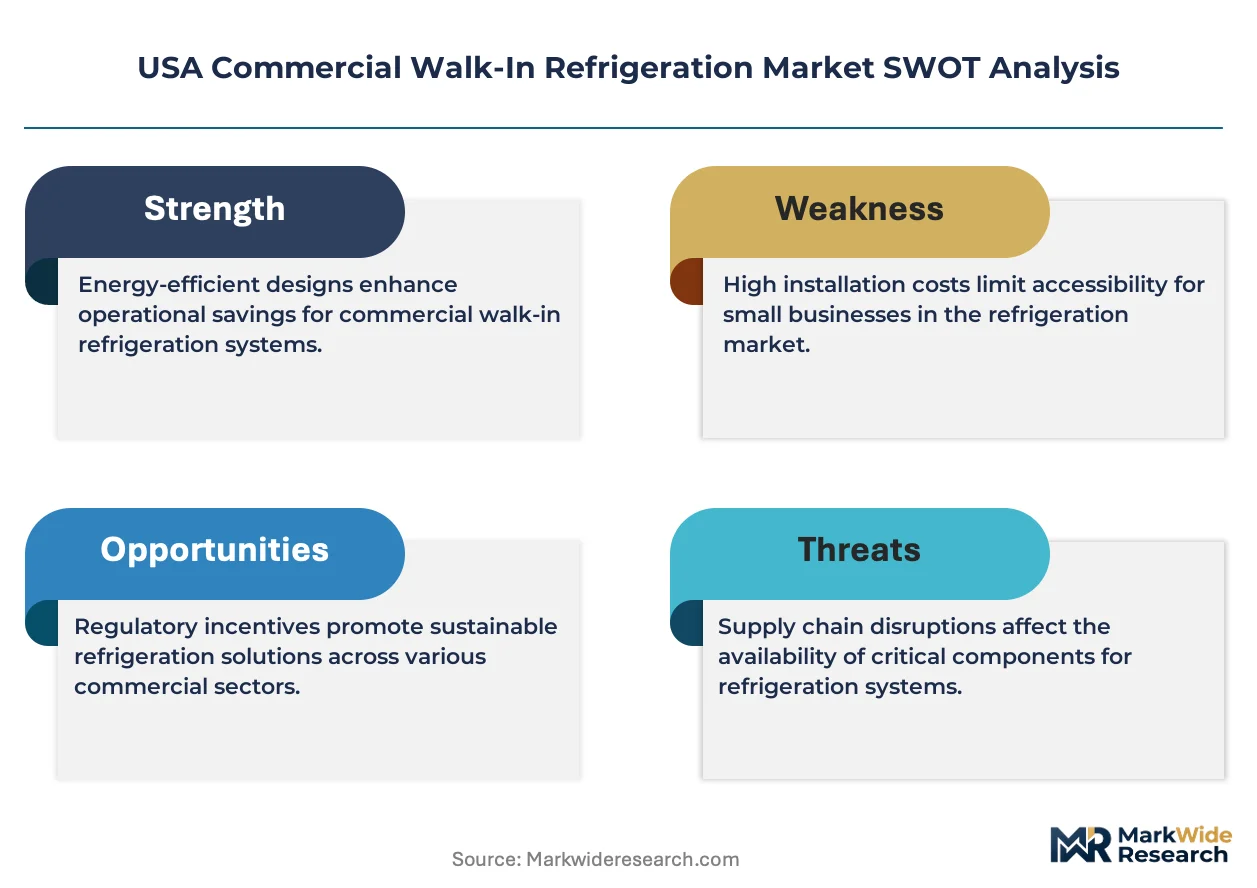
- Polyurethane Panel Cost Volatility:Insulated panel production depends on petrochemical feedstocks and blowing agents subject to price swings, compressing margins for enclosure manufacturers.
- Certified Installer Scarcity:The Southeast and Southwest states face acute shortages of technicians qualified for natural refrigerant handling and ammonia detection system integration.
- Retrofit Complexity in Legacy Buildings:Older restaurants and convenience stores in urban cores lack electrical infrastructure and physical clearances for modern high-efficiency condensing units.
Strategic Opportunities
- Utility Rebate Capture:State-level programs in California and Texas tie capital incentives to connected monitoring capabilities and natural refrigerant commitments, creating specification advantages for compliant suppliers.
- Modular Off-Site Fabrication:Factory-built walk-in modules reduce on-site labor hours and accelerate project completion for convenience store chains facing construction timeline pressure.
- Independent Restaurant Segment:Regional restaurant groups replacing legacy institutional buyers represent an underpenetrated channel with compressed decision cycles and upgrade urgency.
Industry Challenges
- Ammonia Safety Certification Bottlenecks:OSHA and state building codes mandate specialized detection and ventilation systems for industrial-scale natural refrigerant installations, extending project timelines where qualified inspectors are scarce.
- Refrigerant Transition Inventory Management:Distributors and contractors must maintain parallel stockpiles of phasedown-scheduled HFCs and emerging alternatives, complicating working capital and warranty obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Commercial Walk-In Refrigeration Market |
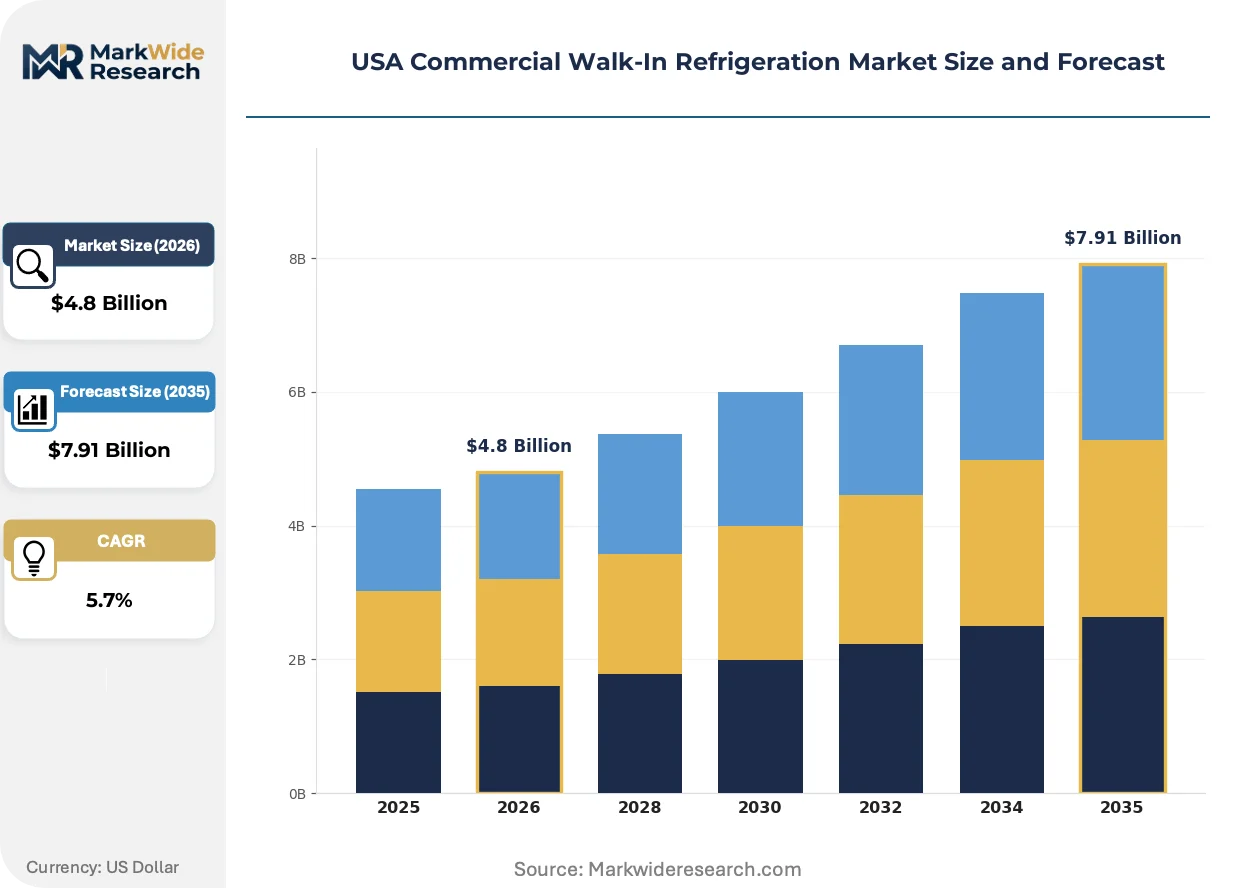
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-In Freezers, Walk-In Coolers, Reach-In Refrigerators, Display Chillers End User: Restaurants, Supermarkets, Convenience Stores, Warehouses Installation Type: On-Site, Off-Site, Modular, Custom-Built Cooling Technology: Natural Refrigerants, HFCs, CO2, Hydrocarbon Refrigerants |
| Companies Covered | Nor-Lake, Kolpak, Arctic Walk-in Coolers & Walk-in Freezers, Amerikooler, Bally Refrigerated Boxes, Hussmann Corporation, U.S. Cooler, Thermo-Kool, Master-Bilt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Commercial Walk-In Refrigeration Market Evolving Landscape
Equipment architecture and procurement patterns are diverging from legacy norms as regulatory pressure and labor scarcity force modular approaches and connected monitoring into standard specification.
Transcritical CO2 refrigeration systems are decomposing the traditional vapor-compression hierarchy in supermarket and warehouse applications. Regional grocery chains in California and Texas are specifying these platforms for new construction and major retrofits. The technology is decomposing incumbent HFC-based equipment categories by bundling regulatory compliance with energy efficiency gains that utility programs reward.
The EPA's AIM Act implementation timeline is compressing viable product portfolios and accelerating replacement cycles. Equipment manufacturers must now certify platforms for lower-GWP refrigerants ahead of production phaseout deadlines. Independent restaurants and convenience store chains in Florida and the Southwest are responding by front-loading capital expenditure to avoid stranded asset risk.
Foodservice operators are unbundling equipment procurement from installation and maintenance contracts, treating walk-in refrigeration as a configurable subsystem rather than a turnkey package. Regional grocery chains and cold-storage logistics operators are driving this shift, using modular specifications to accelerate project timelines. The pattern is most visible in Texas and California where labor scarcity and permit delays have made speed-to-operation a competitive priority.
USA Commercial Walk-In Refrigeration Market Segmentation
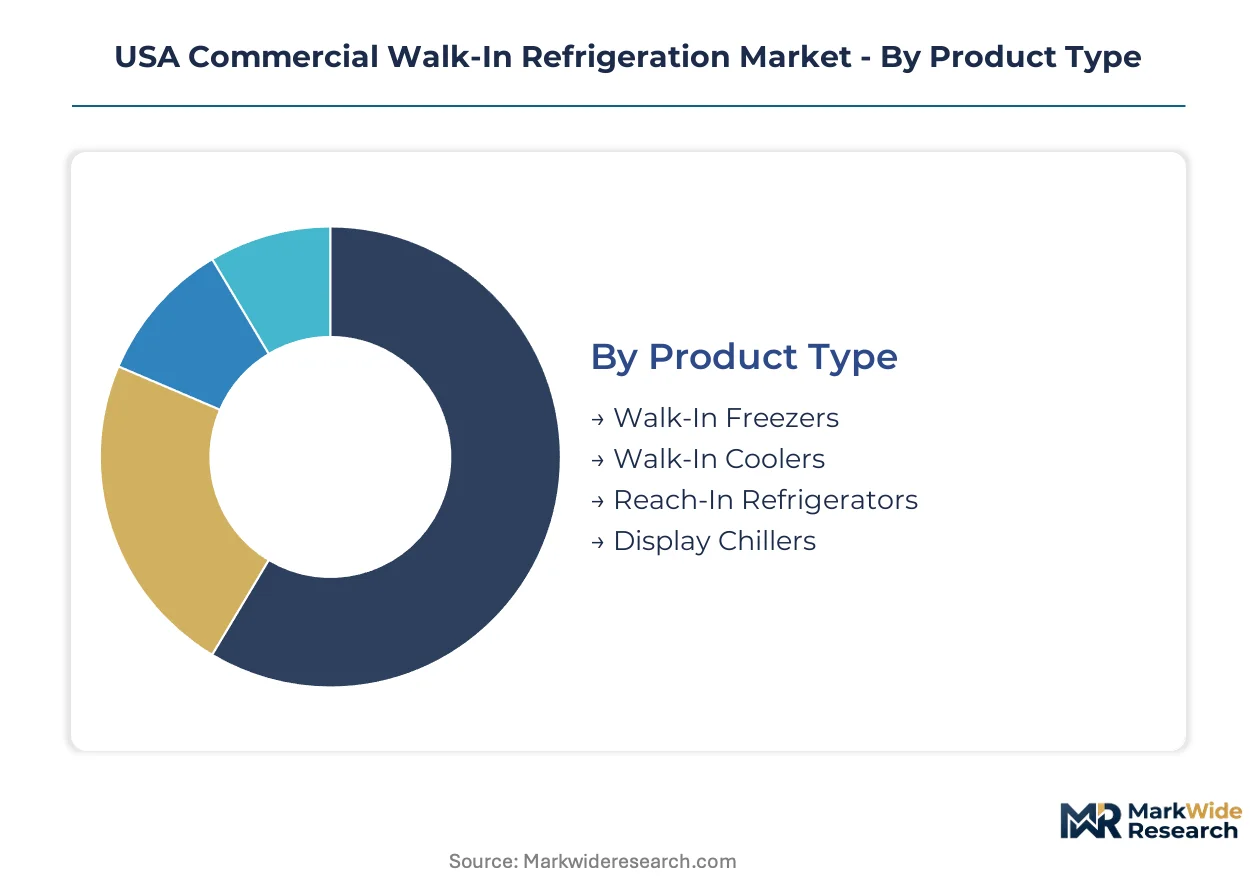
Walk-in refrigeration procurement patterns diverge sharply across customer archetypes, with independent restaurants prioritizing speed-to-installation while supermarket chains emphasize energy compliance and lifecycle cost. Understanding these segment boundaries clarifies where specification power concentrates and which technology platforms capture disproportionate margin.
Product Type:
Domestic demand for enclosure systems concentrates in temperature-specific formats, with export-relevant production limited to specialized industrial-scale units. The geographic spread of manufacturing aligns with regional foodservice density and cold-chain infrastructure investment cycles.
- Walk-In Freezers:Engineered enclosures maintain temperatures from -10°F to 0°F using high-density polyurethane insulation rated at R-32 thermal resistance. Demand clusters in Texas and Florida food distribution corridors where protein processing and frozen inventory turnover are accelerating retrofit timelines.
- Walk-In Coolers:These systems operate between 32°F and 55°F for fresh produce, dairy, and beverage preservation, representing the volume foundation of commercial foodservice refrigeration. California's Central Valley agricultural logistics operators are specifying expanded cooler capacity as regional grocery chains consolidate distribution nodes.
- Reach-In Refrigerators:Compact upright units serve back-of-house kitchen workflows where floor space constraints dominate specification decisions.
- Display Chillers:Glass-fronted merchandising enclosures bridge storage and retail presentation functions in convenience store formats.
Walk-in coolers command the established base. The steepest expansion runs through walk-in freezers.
End User:
Customer procurement authority is shifting from institutional foodservice contractors toward independent operators with compressed decision cycles and upgrade urgency.
- Restaurants:Independent restaurant groups and regional chains are replacing legacy institutional buyers as the fastest-growing customer archetype, driven by AIM Act compliance deadlines and equipment end-of-life. These operators prioritize modular installation formats that minimize kitchen downtime during retrofit.
- Supermarkets:Regional grocery chains specify transcritical CO2 systems for new construction and major retrofits, bundling regulatory compliance with utility rebate capture. Their procurement volumes justify factory-direct relationships with enclosure manufacturers.
- Convenience Stores:Petroleum retail operators and independent c-store chains require compact footprint solutions with rapid deployment timelines.
- Warehouses:Third-party logistics operators building temperature-controlled distribution nodes drive demand for large-scale custom-engineered enclosures with precise temperature zoning capabilities.
Supermarkets anchor the revenue base. The most rapid volume gains are emerging through restaurants.
Installation Type:
Project delivery methods are diverging based on labor availability and speed-to-operation priorities across customer segments.
- On-Site:Traditional stick-built assembly remains prevalent in legacy urban locations where building access constraints prevent modular delivery. The Southeast and Southwest face acute installer scarcity that extends project timelines for this format.
- Off-Site:Factory-built modules reduce on-site labor hours and accelerate completion for convenience store chains facing construction timeline pressure. California and Texas operators are specifying off-site fabrication to circumvent permit delays and labor scarcity.
- Modular:Pre-engineered panel systems with standardized connection protocols enable rapid expansion and reconfiguration.
- Custom-Built:Bespoke enclosure dimensions and refrigeration integration serve specialized warehouse applications with non-standard inventory profiles.
On-site installation retains the volume base. Off-site fabrication is climbing the fastest as labor constraints reshape procurement.
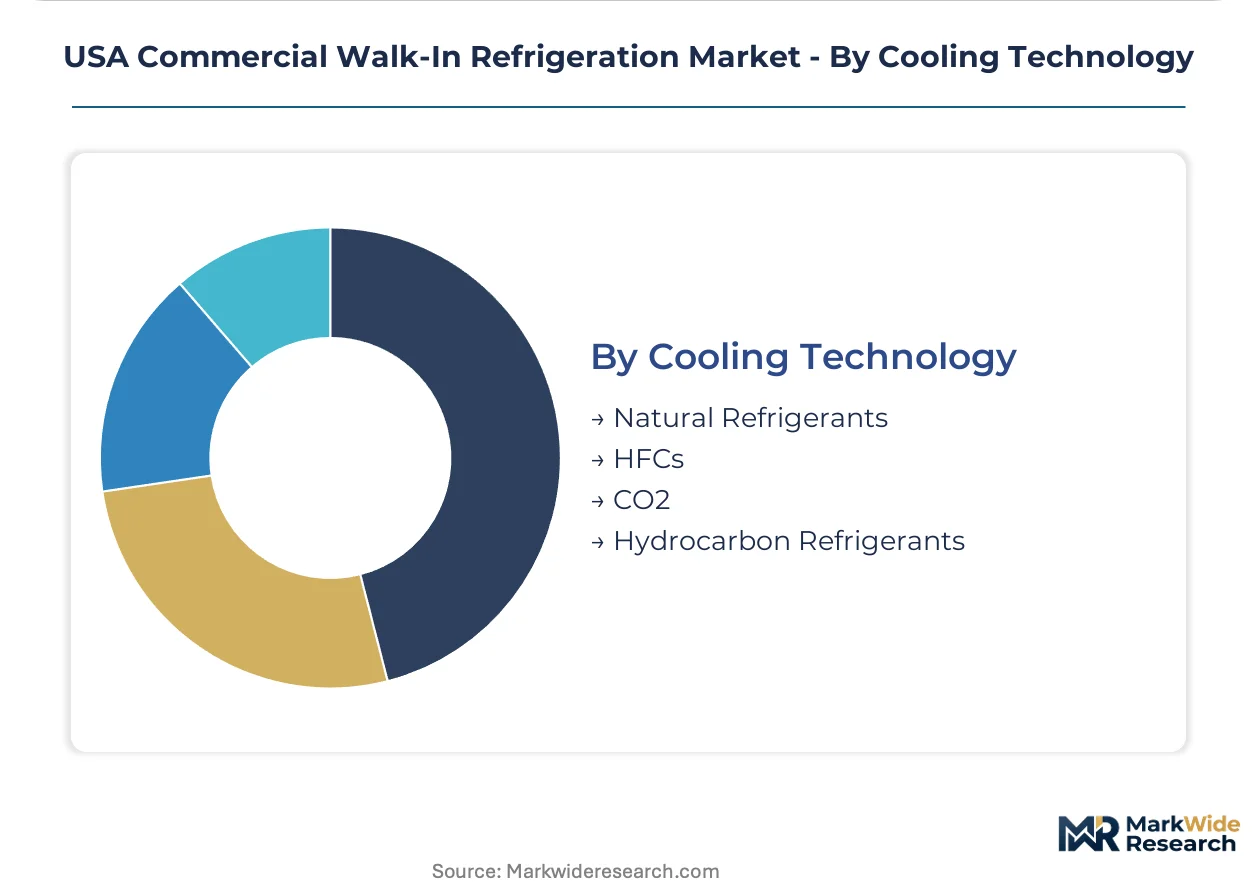
Cooling Technology:
Refrigerant selection is compressing toward lower-GWP alternatives as EPA phasedown timelines eliminate viable product portfolios.
- Natural Refrigerants:Ammonia and hydrocarbon blends serve industrial-scale applications where safety infrastructure and specialized technician availability support deployment. OSHA and state building codes mandate detection and ventilation systems that extend project timelines where qualified inspectors are scarce.
- HFCs:Hydrofluorocarbon systems face production phaseout under AIM Act mandates, forcing operators to accelerate replacement cycles and stranding existing inventory. The EPA's phasedown is compelling front-loaded capital expenditure to avoid asset risk.
- CO2:Transcritical CO2 systems capture specification share in supermarket and warehouse applications as operators seek future-proofed compliance paths with utility program rewards.
- Hydrocarbon Refrigerants:Propane and isobutane blends offer lower-GWP alternatives for smaller-capacity commercial applications with charge size limitations.
HFCs retain the installed base. CO2 systems are gaining share fastest as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing in the United States supplies walk-in refrigeration systems to foodservice operators across Texas, California, and Florida, with interstate trade flows concentrated along the Gulf Coast and Pacific logistics corridors.
Texas
Protein processing facilities and regional distribution hubs drive freezer demand across the Dallas-Fort Worth and Houston corridors. EPA AIM Act compliance deadlines are accelerating retrofit timelines for legacy HFC equipment. San Antonio and Austin foodservice clusters are specifying modular off-site fabrication to circumvent installer scarcity.
California
Central Valley agricultural logistics operators are consolidating temperature-controlled distribution nodes, expanding cooler capacity for fresh produce handling. State-level utility rebate programs tie capital incentives to natural refrigerant commitments and connected monitoring capabilities. Los Angeles and San Diego metropolitan areas are deploying transcritical CO2 systems for supermarket retrofits.
Florida
Independent restaurant groups and convenience store chains are front-loading capital expenditure to avoid stranded asset risk from refrigerant phasedown schedules. State building codes mandate ammonia detection systems for industrial-scale natural refrigerant installations. Miami and Tampa foodservice corridors face acute shortages of technicians qualified for CO2 system handling.
Southeast
Georgia and North Carolina cold-storage logistics operators are building regional distribution infrastructure to serve expanding grocery chain networks. OSHA enforcement of enclosure safety standards extends project timelines where qualified inspectors are scarce. Atlanta and Charlotte industrial clusters are driving demand for custom-engineered enclosures with precise temperature zoning.
Southwest
Arizona and Nevada convenience store chains require rapid deployment timelines for compact footprint solutions in petroleum retail formats. Federal minimum energy conservation standards from DOE are compressing viable product portfolios toward higher-efficiency platforms. Phoenix and Las Vegas construction markets are prioritizing factory-built modules to reduce on-site labor hours.
USA Commercial Walk-In Refrigeration Market Competitive Landscape
Player mix skews toward diversified refrigeration equipment manufacturers with captive panel production capabilities. Market structure concentrates specification authority among three to four vertically integrated suppliers serving supermarket and warehouse segments. Strategic archetypes include scale-driven enclosure fabricators, custom-engineered solution specialists, and regional service-integrated distributors. Competitive moves center on backward integration into insulated panel production and geographic expansion through utility rebate program capture.
Among diversified equipment manufacturers, Hussmann Corporation and Bally Refrigerated Boxes exemplify the scale-driven archetype through manufacturing breadth and material cost control. Amerikooler occupies a position within the custom-engineered tier, serving specialized warehouse applications requiring precise temperature zoning. Nor-Lake and Kolpak represent the service-integrated distributor model, anchoring regional specification channels through installation and maintenance bundling. These five companies illustrate the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Nor-Lake |
| Kolpak |
| Arctic Walk-in Coolers & Walk-in Freezers |
| Amerikooler |
| Bally Refrigerated Boxes |
| Hussmann Corporation |
| U.S. Cooler |
| Thermo-Kool |
| Master-Bilt |
| Others |
Value Network & Pricing Analysis
Manufacturing scale at Hussmann Corporation and Bally Refrigerated Boxes anchors price floors across the Midwest and Southeast, compressing margin capture for mid-tier fabricators while concentrating specification authority among vertically integrated suppliers with captive panel production.
Pricing Analysis
The pricing gap between legacy HFC-based systems and transcritical CO2 platforms spans three technology generations, with natural refrigerant equipment commanding premium positioning due to AIM Act compliance certainty and California utility rebate eligibility. Project-based pricing dominates supermarket and warehouse segments where factory-direct relationships justify volume discounts, while independent restaurants face higher per-unit costs due to fragmented procurement and compressed installation timelines. Price differentiation centers on certification grade—UL-listed ammonia detection systems and ASHRAE-compliant energy ratings—and geographic delivery cost from Midwest manufacturing hubs to Florida and Southwest corridors. Pricing pressure intensifies in the standard cooler segment as polyurethane panel cost volatility feeds through to enclosure margins, with independent restaurant operators exhibiting highest price sensitivity due to capital constraint and upgrade urgency.
Supply Chain Analysis
Inbound logistics costs from Gulf Coast petrochemical corridors shape insulated panel economics, with container availability fluctuations on Houston-to-California lanes affecting just-in-time delivery for Central Valley distribution projects. Domestic manufacturing concentrates in Ohio, Missouri, and Texas where Hussmann, Bally, and Amerikooler maintain fabrication facilities; Mexico serves as secondary source for standardized component stamping and condensing unit assembly. Raw material dependencies include isocyanate and polyol feedstocks for polyurethane insulation, aluminum coil for panel facing, and copper tubing for refrigeration circuits. Single-source vulnerability runs through specialized blowing agent suppliers subject to EPA production quotas under AIM Act implementation. Distribution runs through manufacturer-direct channels for supermarket chains, regional service-integrated distributors for independent restaurants, and petroleum retail procurement networks for convenience store deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive positioning through regulatory entrenchment: EPA refrigerant phasedown timelines create switching costs that lock operators into compliant supplier relationships and strand non-compliant competitors.
For Market Incumbents: Consolidate specification authority by deepening backward integration into insulated panel production and expanding factory-direct relationships with regional grocery chains building California and Texas distribution nodes. Defend against modular off-site fabricators by embedding connected monitoring capabilities into standard equipment packages, capturing utility rebate program eligibility as a channel control mechanism. Prioritize certification investment in ammonia safety systems to extend timeline advantages where OSHA-qualified inspectors remain scarce. For New Entrants and Emerging Players: Certified installer scarcity across Florida and the Southwest creates immediate service-layer opportunity for technicians qualified in CO2 transcritical handling and ammonia detection integration. Target independent restaurant groups in Texas urban cores where compressed decision cycles and AIM Act urgency outpace incumbent response capacity. Deploy rapid-installation modular formats with lease-to-own financing structures that reduce upfront capital barriers for capital-constrained operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-integrated distributors with maintenance contract bundling, offering superior cash flow predictability across equipment replacement cycles. Long-term viability favors acquisition targets with captive panel production and established utility rebate program relationships in California and Texas. Watch EPA enforcement acceleration in Southeast states as the inflection signal for stranded asset risk realization and replacement cycle front-loading.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Production | Captive supply of polyurethane insulation shields margin from petrochemical feedstock volatility. |
| Natural Refrigerant Certification Investment | EPA AIM Act compliance locks in specification share ahead of HFC production phaseout deadlines. |
| Utility Rebate Program Capture | California and Texas incentive alignment accelerates transcritical CO2 adoption in supermarket retrofits. |
| Modular Off-Site Fabrication Scale-Up | Factory-built modules circumvent labor scarcity and permit delays in California construction markets. |
| Connected Monitoring Platform Integration | Remote diagnostics capability satisfies state-level utility rebate requirements and extends service contract attach rates. |
Research Methodology
Initial hypotheses were tested against primary input from foodservice equipment procurement directors, refrigeration contractor operations managers, supermarket facility engineers, and EPA regulatory affairs specialists, then refined through secondary validation against DOE energy conservation standard filings, ASHRAE equipment certification databases, state utility commission rebate program documentation, and SEC 10-K disclosures from diversified refrigeration equipment manufacturers. Bottom-up triangulation across installation volume estimates and top-down reconciliation against aggregate capital expenditure patterns anchored market size and growth projections.
Variance decomposition across product type, end user, installation format, and cooling technology dimensions structured the analytical framework, with segment-level CAGRs derived from equipment replacement cycle analysis and regulatory deadline impact modeling. Input assumptions incorporated AIM Act phasedown timeline enforcement probability, polyurethane panel cost trajectory sensitivity, and certified technician availability constraints across Southeast and Southwest labor markets.
Forecasts assume regulatory continuity in EPA refrigerant management and DOE appliance efficiency regimes; material policy acceleration or delay would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Global Powder Processing Equipment Market