
 Whipping Cream Market | 2026-2036
Whipping Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Whipping Cream Market Intelligence
Single-serve aerosol canisters paired with resealable valve systems is restructuring how households and cafés allocate refrigerated dairy budgets. Fonterra Co-operative Group leverages its New Zealand milk pool to dominate long-life UHT whipping cream exports into Southeast Asia. Arla Foods sustains competitive positioning through backward integration into Scandinavian cooperative farms. Rich Products Corporation anchors North American food-service supply through frozen whipped topping distribution networks.
Whipping cream is a dairy emulsion containing minimum thirty percent milk fat, produced through centrifugal separation and standardized homogenization to achieve stable aeration under mechanical whipping. Its primary commercial purpose centers on providing structural volume and mouthfeel in finished desserts, beverages, and savory sauce applications. Liquid and UHT formats lead volume throughput due to extended shelf stability and food-service dispensing efficiency, while aerosol configurations capture premium margin pools through convenience positioning in retail channels. Powdered whipping cream occupies a mature niche concentrated in emergency pantry and outdoor recreation segments where refrigeration access is constrained.
FDA standards govern minimum butterfat declarations and pasteurization thresholds for interstate commerce, while EU health regulations through EFSA mandate front-of-pack nutritional labeling that pressures reformulation toward reduced-fat variants. The EU Green Deal agricultural sustainability criteria are tightening feed-to-fork traceability requirements that favor cooperative-structured suppliers with captive farm networks. Stakeholders must monitor divergence between clean-label consumer preferences and the functional performance demands of high-fat traditional formulations.
Market Dynamics
EU Green Deal agricultural sustainability criteria are forcing feed-to-fork traceability investments that favor cooperative-structured suppliers with captive farm networks over commodity traders.
Growth Catalysts
- Clean-label reformulation:FDA standards for minimum butterfat declarations and pasteurization thresholds create technical barriers that reward compliant domestic producers with shelf-stable UHT formats.
- Artisanal patisserie expansion:Bakery chains across France, Germany, and the United States are expanding whipped cream applications across dessert menus, pulling volume through premium positioning.
- Aerosol convenience technology:Single-serve canisters with resealable valve systems are capturing household refrigerated dairy budgets through portion control and waste reduction.
Market Restraints
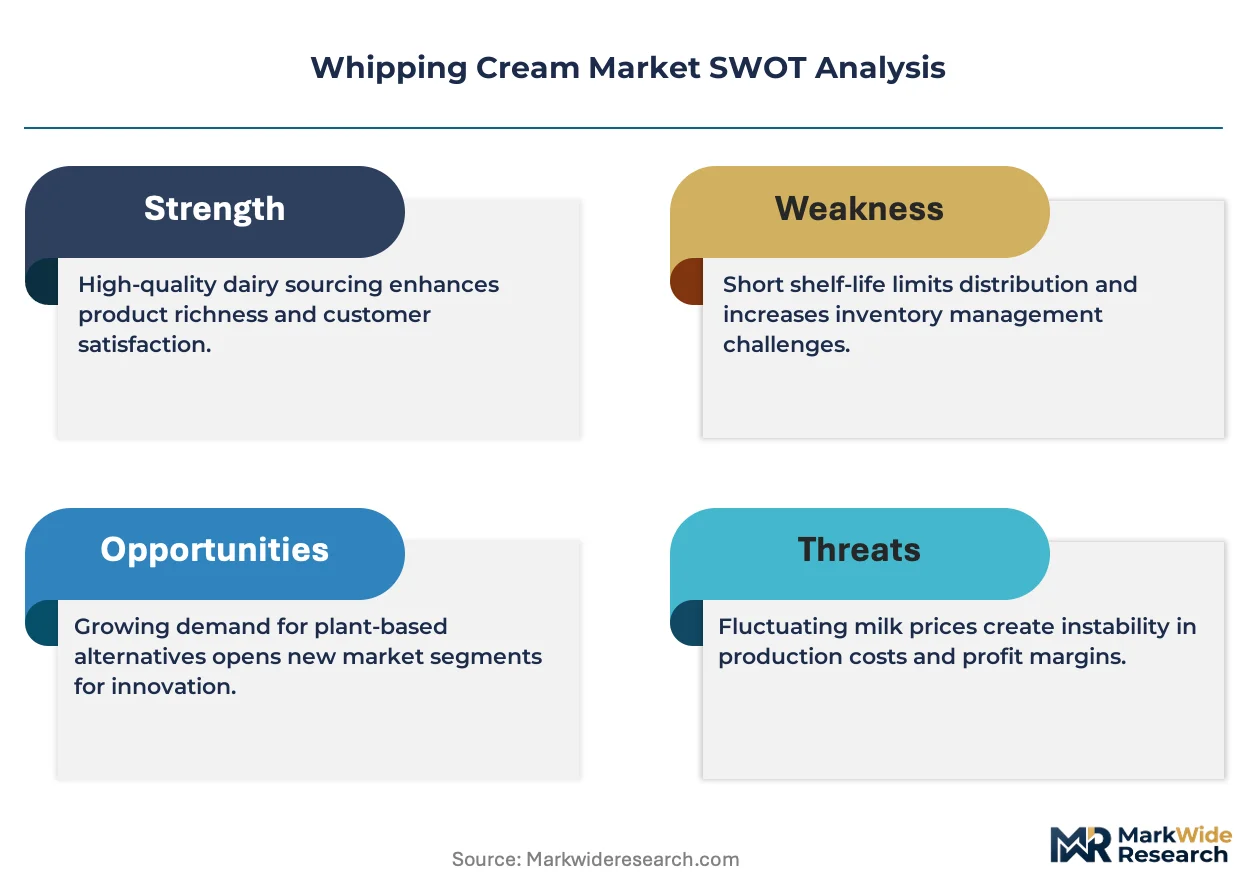
- Input cost volatility:New Zealand milk powder prices and EU dairy intervention stocks create margin compression for non-integrated processors lacking backward integration into cooperative farms.
- Regulatory friction:EFSA front-of-pack nutritional labeling mandates pressure reformulation toward reduced-fat variants that compromise functional aeration performance in traditional recipes.
- Substitution threat:Plant-based whipped toppings derived from coconut oil and oat protein are displacing conventional dairy in vegan-certified food-service channels.
Strategic Opportunities
- Emerging Southeast Asian demand:Long-life UHT whipping cream exports are penetrating Indonesian and Vietnamese bakery sectors where cold chain infrastructure remains underdeveloped.
- Outdoor recreation distribution:Powdered whipping cream occupies emergency pantry and camping segments where refrigeration access is constrained, creating margin pools through lightweight logistics.
- EU sustainability tailwind:EU Green Deal criteria favor suppliers with certified feed-to-fork traceability, creating procurement preference for Scandinavian cooperative-structured producers.
Industry Challenges
- Technical workforce scarcity:Dairy emulsion chemistry expertise for stable aeration under mechanical whipping concentrates in aging European and North American technician pools.
- Homogenization equipment capex:Centrifugal separation and standardized homogenization systems require capital-intensive stainless-steel infrastructure with long depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whipping Cream Market |
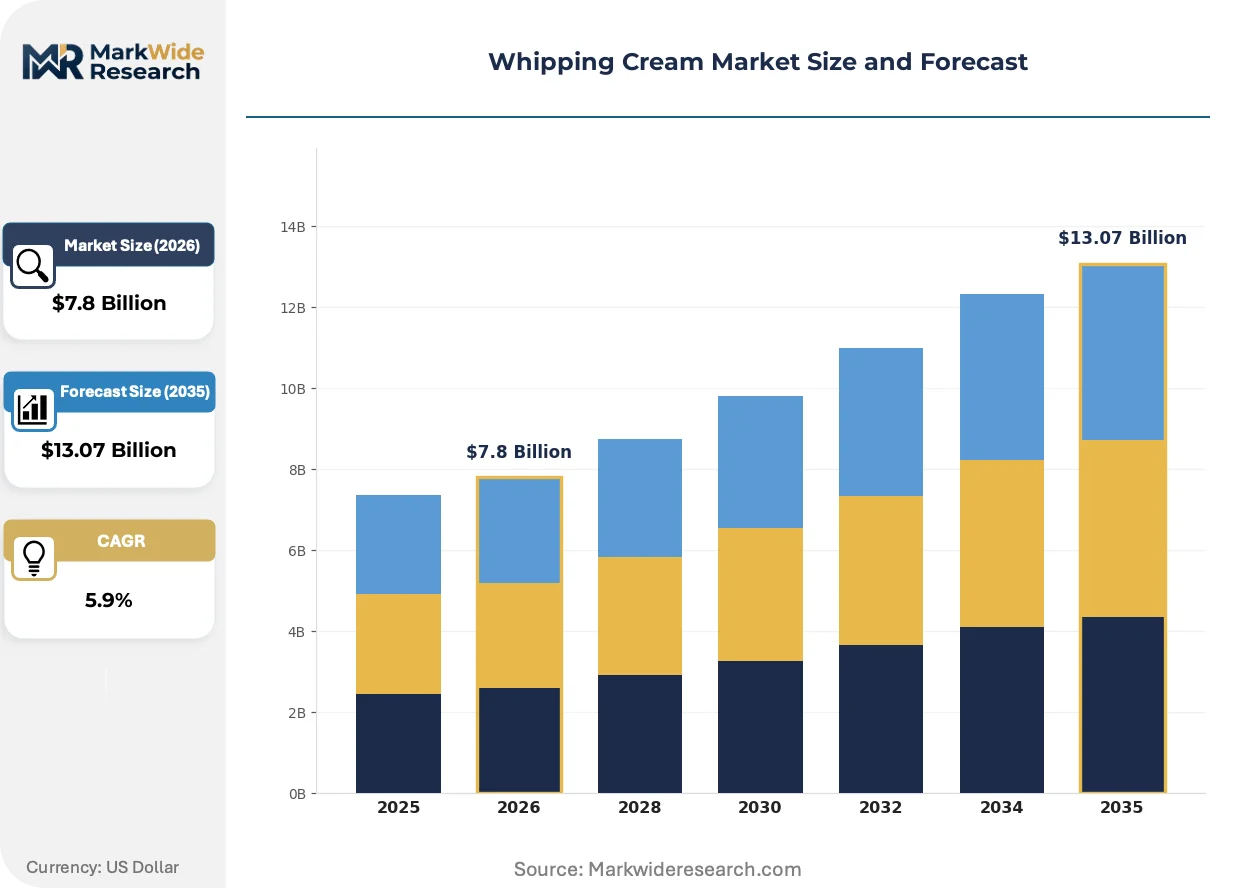
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.07 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powdered, Aerosol, UHT End User: Household, Food Service, Bakery, Dairy Industry Application: Desserts, Beverages, Sauces, Fillings Packaging Type: Carton, Bottle, Tub, Can |
| Companies Covered | Nestlé S.A., Dairy Farmers of America, Fonterra Co-operative Group, Rich Products Corporation, Kraft Heinz Company, Arla Foods, Land O'Lakes, Lactalis, FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whipping Cream Market Strategic Shifts & Innovations
Reformulation pressures from front-of-pack labeling mandates are intersecting with convenience-driven packaging evolution to reshape competitive positioning across liquid, aerosol, and powdered formats.
Plant-protein aeration technology is rewriting the functional performance baseline for non-dairy alternatives. Food-service distributors in vegan-certified channels are adopting these formulations at accelerating pace. The technology is compressing the premium margin pool that conventional high-fat dairy historically commanded in specialty coffee applications.
EFSA front-of-pack nutritional labeling requirements are mandating visible fat content disclosures that reshape product portfolio prioritization. Reformulation toward reduced-fat variants is consuming R&D resources without matching traditional aeration stability. Dairy processors in France and Germany are responding by segmenting portfolios into clean-label premium tiers and functional economy lines.
Café procurement patterns are consolidating around single-source supply agreements with frozen whipped topping distributors. Independent bakeries and small-chain coffee shops are being displaced by centralized purchasing through broadline food-service distributors. This concentration is most visible across the United States where Rich Products Corporation anchors North American supply networks.
Whipping Cream Market Segmentation
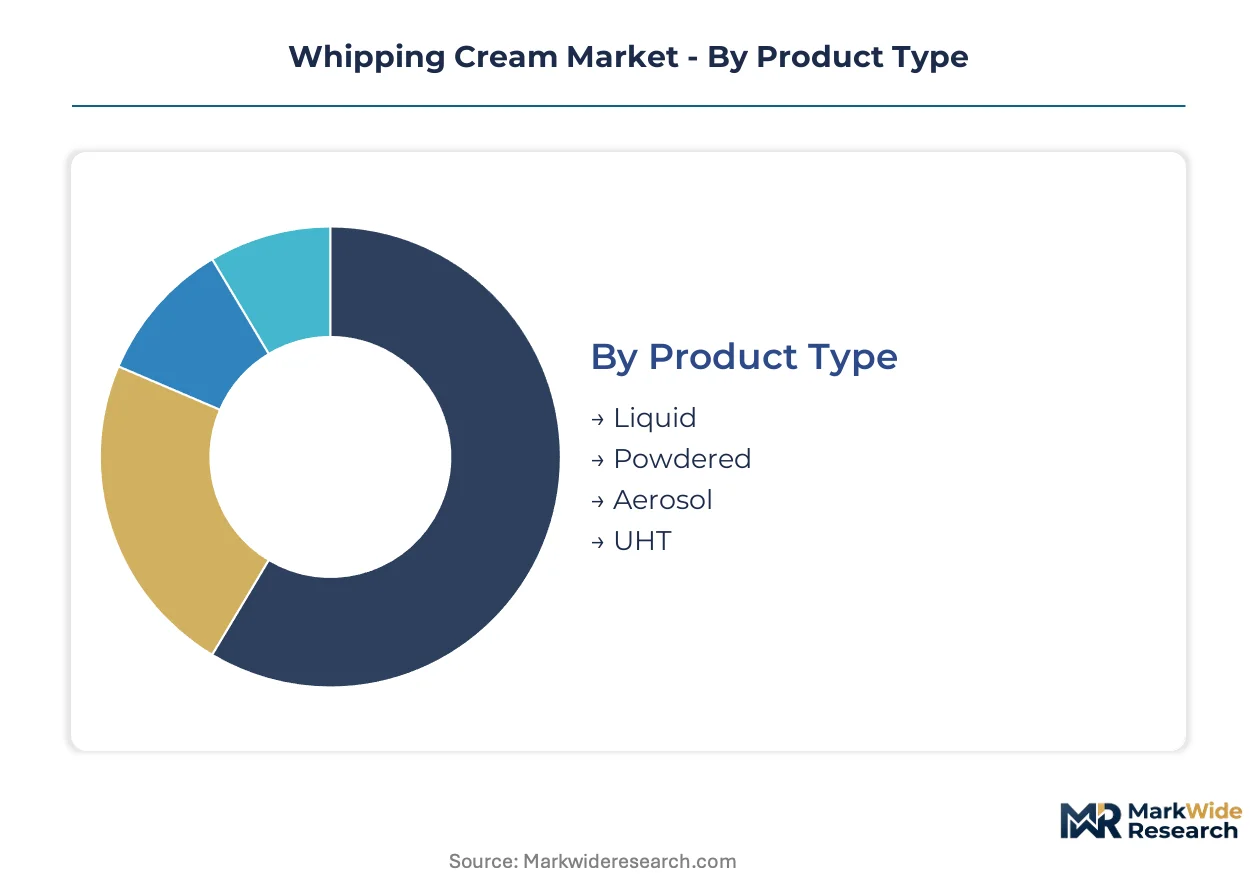
Whipping cream segmentation reveals how processing technology and distribution infrastructure shape profit pools. Product format selection determines shelf-life economics, while end-user channel alignment dictates margin capture efficiency across refrigerated and ambient supply chains.
Product Type:
Supply concentration in liquid and UHT formats reflects capital-intensive homogenization infrastructure requirements that favor processors with captive dairy supply.
- Liquid:Fresh dairy emulsion requiring continuous cold chain from processing plant to point of use. Demand concentrates in French and German artisanal patisseries where traditional recipes mandate fresh cream aeration performance.
- UHT:Ultra-high temperature sterilization extends shelf stability without refrigeration, enabling Southeast Asian bakery penetration where cold chain infrastructure remains underdeveloped. Fonterra leverages New Zealand milk pool dominance for long-life export volumes.
- Powdered:Dehydrated format occupying emergency pantry and outdoor recreation segments with lightweight logistics advantages.
- Aerosol:Single-serve canisters with resealable valve systems capturing household convenience premiums through portion control and waste reduction.
Today's leader: Liquid. Tomorrow's challenger: UHT.
End User:
Cost tier stratification separates premium artisanal channels from economy food-service procurement, with bakery chains consolidating purchasing power.
- Food Service:Broadline distributors anchor North American supply through frozen whipped topping networks. Rich Products Corporation sustains channel dominance via centralized procurement relationships with café chains.
- Bakery:Artisanal patisseries across France, Germany, and the United States pull volume through premium positioning and dessert menu expansion.
- Household:Aerosol convenience formats penetrating refrigerated dairy budgets through single-serve portioning.
- Dairy Industry:Intermediate processing segment supplying reformulated reduced-fat variants under EFSA labeling pressure.
Food service commands current volume. Bakery channels are climbing the fastest.
Application:
Volume concentration in desserts reflects premium dessert culture deepening across developed markets, with beverage applications expanding through specialty coffee proliferation.
- Desserts:Structural volume and mouthfeel provision in finished patisserie applications. French and German bakery chains drive specification requirements for stable aeration under mechanical whipping.
- Beverages:Specialty coffee applications experiencing margin compression from plant-protein aeration technology displacement.
- Sauces:Savory emulsion applications in food-service channels with functional performance demands.
- Fillings:Industrial bakery and confectionery intermediate applications.
Desserts anchor present revenue. Beverages face steepest competitive disruption.
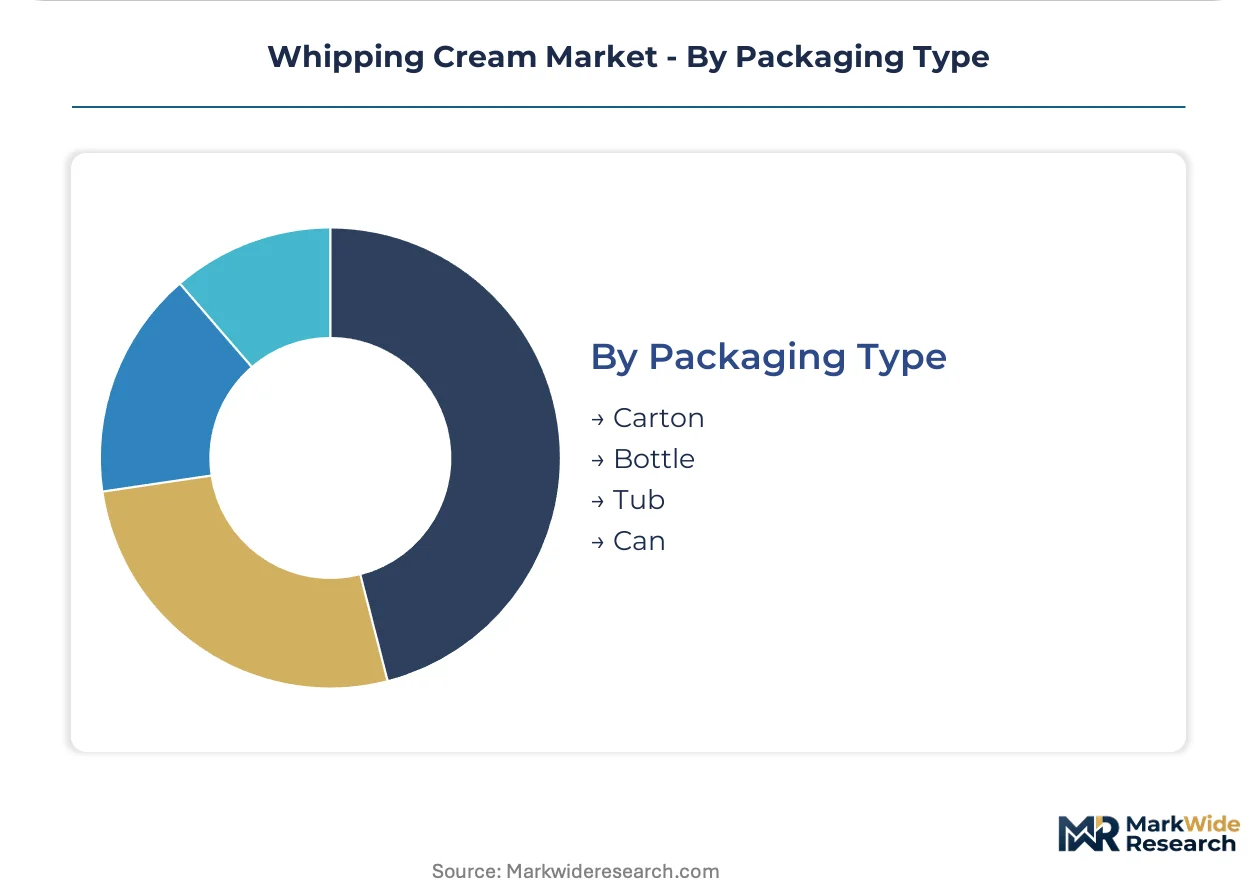
Packaging Type:
Customer type differentiation separates retail convenience formats from institutional bulk supply, with carton and bottle configurations dominating diverging channel requirements.
- Carton:Standard liquid cream retail format with refrigerated distribution efficiency.
- Bottle:Food-service dispensing configuration for high-volume bakery and café operations.
- Tub:Frozen whipped topping bulk format for institutional procurement through broadline distributors.
- Can:Aerosol convenience packaging with resealable valve technology for household portion control.
Carton leads retail penetration. Can formats are gaining share fastest through convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale dairy emulsion processing traces its modern lineage to 19th-century Danish cooperative creameries and post-war American fluid milk standardization programs. Today's whipping cream trade routes still reflect these founding geographies, with centrifugal separation expertise concentrated in Northern European and North American dairy belts.
United States
Specialty coffee chains and artisanal bakery expansion in New York, Chicago, and Los Angeles drive aerosol and liquid cream procurement. FDA pasteurization thresholds and interstate commerce standards create compliance barriers that favor domestic processors with captive milk supply. Wisconsin and California dairy cooperatives anchor fluid cream production for food-service distribution networks.
Germany
Artisanal patisserie culture in Munich, Berlin, and Hamburg sustains premium fresh cream demand for traditional dessert applications. EFSA front-of-pack nutritional labeling mandates pressure reformulation toward reduced-fat variants. Bavarian and Lower Saxon dairy cooperatives leverage EU Green Deal traceability criteria to secure bakery chain procurement contracts.
France
Appellation-linked cream specifications in Normandy and Brittany protect terroir-based premium positioning for patisserie channels. ANSM dairy hygiene regulations govern centrifugal separation facility licensing. Paris and Lyon metropolitan bakery chains consolidate purchasing power through direct cooperative relationships, bypassing commodity traders.
Indonesia
Bakery sector growth in Jakarta and Surabaya absorbs long-life UHT whipping cream volumes where cold chain infrastructure remains patchy. The country's national food and drug regulator enforces halal certification requirements for dairy imports. Fonterra leverages New Zealand milk pool dominance to supply Indonesian food-service distributors.
Vietnam
Ho Chi Minh City and Hanoi café proliferation pulls aerosol and UHT formats through modern trade retail channels. Dairy import standards administered by the Ministry of Health mandate pathogen testing protocols. European and New Zealand exporters compete for bakery sector contracts through local distributor partnerships.
Whipping Cream Market Key Industry Players
Premium-margin players sit above commodity-margin players across convenience technology and traceability certification dimensions. Cooperative-structured suppliers with captive farm networks command procurement preference under EU sustainability criteria, while integrated multinationals dominate aerosol and frozen topping distribution. Three archetypes define competitive positioning: heritage dairy cooperatives with backward integration, multinational CPG conglomerates with R&D scale, and regional UHT specialists with export logistics. Capacity expansion in Southeast Asian UHT processing and M&A consolidation among North American food-service distributors represent the dominant competitive moves.
Within the cooperative archetype, Fonterra Co-operative Group and Arla Foods exemplify the feed-to-fork traceability positioning that EU Green Deal criteria favor. Rich Products Corporation occupies a position in the North American food-service distributor tier. Among multinational CPG players, Nestlé S.A. and Kraft Heinz Company sit within the portfolio-diversified segment where aerosol technology and frozen topping formats receive centralized R&D allocation.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Dairy Farmers of America |
| Fonterra Co-operative Group |
| Rich Products Corporation |
| Kraft Heinz Company |
| Arla Foods |
| Land O'Lakes |
| Lactalis |
| FrieslandCampina |
| Others |
Cost & Logistics Intelligence
Homogenization equipment capex requirements and centrifugal separation technology diffusion are simultaneously compressing processor margins and concentrating production among cooperative-structured suppliers with captive farm networks. This technical barrier reshapes cost economics while locking out commodity traders lacking backward integration into Scandinavian or New Zealand milk pools.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates artisanal patisserie specifications from food-service procurement and retail convenience formats. Price differentiation rests on fat content certification and EU Green Deal traceability credentials. Pricing pressure stems from plant-protein aeration technology displacement in specialty coffee channels. Food-service distributors exhibit highest price sensitivity while artisanal bakeries absorb premiums for stable aeration performance.
Supply Chain Analysis
Direct-to-bakery channels handle artisanal volume through cooperative relationships in France and Germany. Raw material sourcing draws from New Zealand milk powder, EU dairy intervention stocks, and captive Scandinavian farm networks. Supply chain risk centers on single-source vulnerability to Fonterra's New Zealand milk pool dominance for UHT export volumes. Distribution runs through broadline food-service networks for frozen whipped topping and modern trade retail for aerosol formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The whipping cream market functions as a stable compounder anchored by deepening premium dessert culture across developed economies and cold chain infrastructure expansion in emerging markets.
For Market Incumbents: Anticipate plant-protein aeration technology encroachment by accelerating R&D allocation toward clean-label reformulation that preserves functional performance. Secure EU Green Deal traceability certification to defend procurement relationships with bakery chains consolidating purchasing power. Prioritize backward integration into captive farm networks to insulate margins from New Zealand milk powder volatility. For New Entrants and Emerging Players: The mid-tier price gap between aerosol convenience premiums and economy UHT formats offers white-space opportunity in Southeast Asian bakery sectors where cold chain gaps persist. Target Indonesian and Vietnamese food-service distributors with halal-certified UHT supply agreements. Pursue lightweight powdered format positioning for outdoor recreation channels as the most penetrable entry vector. For Investors and Strategic Acquirers: Valuations sit cheapest among regional UHT specialists with export logistics capabilities but limited brand equity. Long-term viability favors cooperative-structured suppliers with feed-to-fork traceability under tightening EU agricultural sustainability criteria. Watch for M&A consolidation signals among North American food-service distributors as the inflection indicator for sector repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Preserves functional aeration performance under EFSA front-of-pack labeling mandates. |
| EU Green Deal Certification Program | Secures procurement preference from bakery chains requiring feed-to-fork traceability. |
| Southeast Asian UHT Capacity Expansion | Captures Indonesian and Vietnamese bakery demand where cold chain infrastructure lags. |
| Plant-Protein Aeration Technology Licensing | Defends specialty coffee channel share against coconut oil and oat protein substitutes. |
| Aerosol Convenience Packaging Upgrade | Penetrates household refrigerated dairy budgets through resealable valve innovation. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy cooperative procurement managers, food-service distribution executives, artisanal bakery owners, and EFSA regulatory affairs specialists with secondary validation. Sources included EU dairy intervention stock reports, FDA pasteurization compliance filings, Fonterra export volume disclosures, and customs trade data for UHT cream movements. Bottom-up segment sizing and top-down macroeconomic triangulation anchored value estimates.
Segment-weighting approaches modeled liquid, UHT, powdered, and aerosol formats alongside end-user channels and application categories across the analysis window. CAGRs derived from historical volume trajectories, elasticity-adjusted price paths, and penetration rate modeling for emerging markets. Forecast inputs incorporated cold chain infrastructure development indices and EU Green Deal implementation timelines.
Caveats apply where New Zealand milk powder price volatility, plant-protein substitution acceleration, or EU regulatory enforcement intensity could materially shift the outlook. Forecasts reflect documented assumptions about bakery sector expansion rates and aerosol technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
Cheese Concentrate Market
Dairy Products
United States Camel Dairy Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
South America Flavored Milk Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Global Dairy Market
Dairy Products
United States Casein Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Europe Cheese Market
Dairy Products
Butter Powder Market