
 United States Casein Market | 2026-2036
United States Casein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Casein Market Intelligence
Modular protein blends with casein isolates is realigning buyer choice across sports nutrition and clinical nutrition channels. Fonterra Co-operative Group Limited leverages its New Zealand-origin supply chain to dominate premium micellar casein positioning in the United States. Glanbia plc anchors its competitive stance through deep specialization in whey-casein hybrid formulations for performance brands. Kerry Group plc differentiates via integrated flavor-mask technology that expands casein palatability in ready-to-drink applications.
Casein denotes a family of phosphoproteins comprising approximately 80 percent of bovine milk protein, precipitated through acidification or enzymatic rennet action to yield functional ingredients with slow gastric emptying properties and gel-forming capacity. Micellar casein commands the highest purity tier and associated margin pools, while caseinates deliver superior solubility and dominate beverage and infant formula applications. Rennet casein retains stronghold positions in processed cheese manufacturing where melt elasticity requirements persist, though acid casein faces substitution pressure from plant proteins in lower-specification bakery binders.
FDA food additive regulations and USDA organic certification standards govern casein ingredient claims, labeling, and interstate commerce compliance, with the Dairy Grading Branch enforcing quality benchmarks that influence processor procurement decisions. The FDA's evolving stance on protein content verification methods creates compliance planning complexity for importers and domestic manufacturers alike. Stakeholders must monitor pending FSMA traceability mandates and state-level clean-label legislation that could redefine acceptable processing aids and allergen disclosure thresholds.
Market Dynamics
Protein enrichment mandates in school nutrition programs and military rations are restructuring procurement specifications, forcing casein suppliers to reformulate for sodium reduction and allergen labeling compliance under FDA jurisdiction.
Growth Catalysts
- FSMA traceability mandates:The FDA's enhanced record-keeping requirements for dairy ingredients are accelerating blockchain adoption across Wisconsin and California processing clusters.
- Clinical nutrition expansion:Enteral feeding protocols in Medicare-reimbursed long-term care facilities now specify slow-digesting protein sources, elevating micellar casein inclusion rates.
- Midwest dairy belt concentration:Proximity of Wisconsin cheese plants to casein extraction facilities reduces whey permeate logistics costs and tightens ingredient freshness windows.
Market Restraints
- Skim milk powder price volatility:New Zealand and EU dairy auction cycles transmit directly to US casein input costs, compressing processor margins during GDT price spikes.
- Plant protein substitution:Pea and fava protein isolates achieve functional parity in bakery binders and meat extenders at lower clean-label price points.
- USDA organic certification scarcity:Limited certified organic dairy herds constrain supply expansion for premium-tier casein ingredients.
Strategic Opportunities
- Senior nutrition channel penetration:Sarcopenia-focused medical foods in Florida and Arizona retirement corridors remain undersupplied with specialized protein matrices.
- IRA clean manufacturing incentives:Energy-efficient membrane filtration retrofits qualify for tax credits, lowering capital barriers for domestic micellar casein expansion.
- Hybrid protein convergence:Whey-casein blends with timed-release kinetics are capturing formulation slots in overnight recovery products.
Industry Challenges
- Specialized dairy protein technologist scarcity:Membrane filtration and enzymatic precipitation expertise concentrates among retiring Wisconsin plant operators.
- Dual certification complexity:Simultaneous FDA food additive and USDA organic approvals extend product launch timelines by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Casein Market |
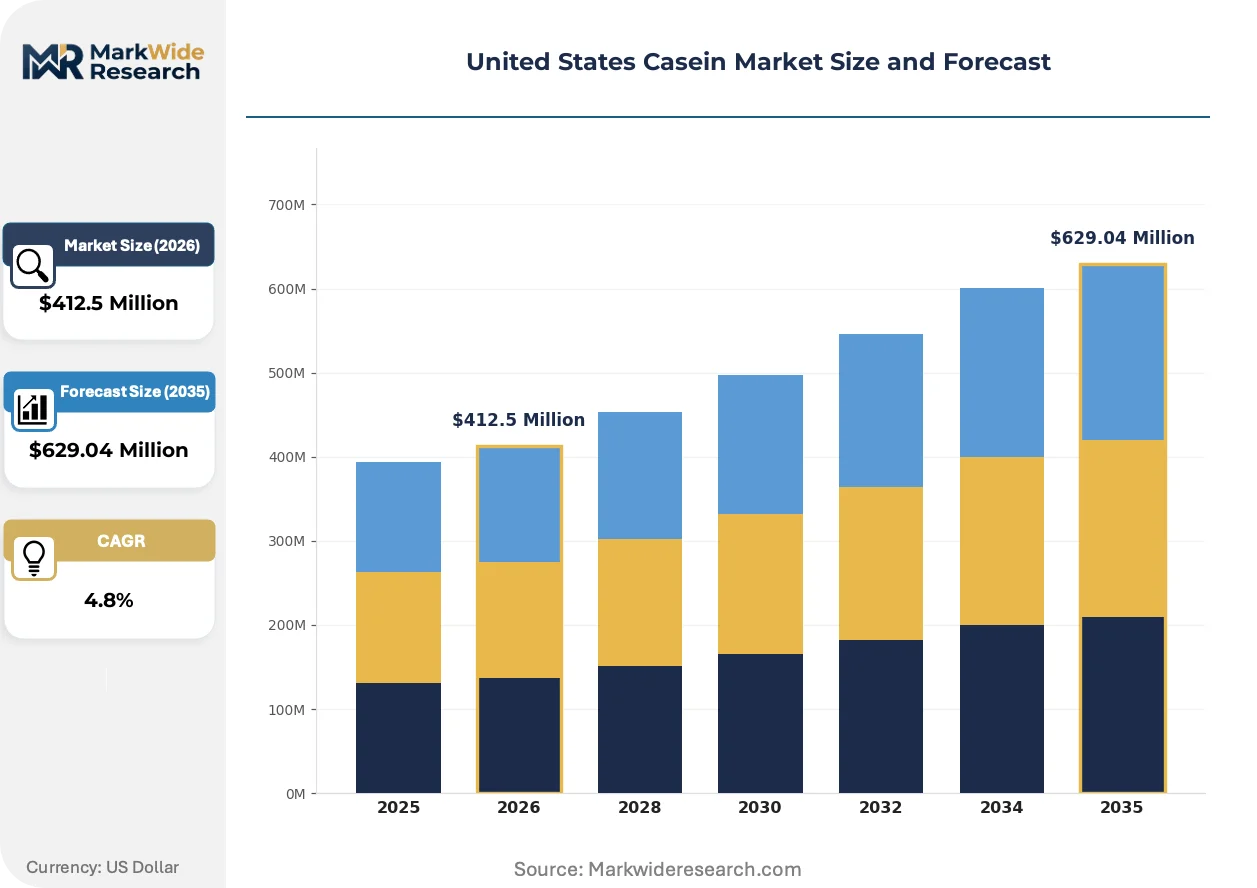
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micellar Casein, Caseinates, Rennet Casein, Acid Casein Application: Dairy Products, Infant Formula, Nutritional Supplements, Bakery Products End User: Food & Beverage Industry, Pharmaceutical Industry, Nutraceuticals, Animal Feed Distribution Channel: Online Sales, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Fonterra Co-operative Group Limited, Arla Foods Ingredients Group P/S, FrieslandCampina Ingredients, Lactalis Ingredients, Kerry Group plc, AMCO Proteins, Farbest Brands, Erie Foods International Inc., Glanbia plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Casein Market Strategic Shifts & Innovations
Precision fermentation and enzymatic modification are rewriting protein functionality standards, while regulatory scrutiny of protein content claims intensifies label verification protocols.
Membrane filtration advances are electrifying micellar casein isolation efficiency. Dairy processors in California's Central Valley deploy ceramic microfiltration systems that preserve native protein structure without acid denaturation. Sports nutrition brands specify these higher-purity grades for overnight release formulations, compressing commodity caseinate price premiums.
FDA protein content verification rulemaking is tightening analytical method standards. The agency's pending guidance on nitrogen-to-protein conversion factors threatens historical Kjeldahl assumptions for dairy ingredients. Infant formula manufacturers face reformulation costs as amino acid profiling supplants crude protein metrics.
Direct-to-practitioner sampling is displacing traditional ingredient broker networks. Registered dietitians in Texas and Colorado receive micellar casein clinical trial data through specialized nutrition science platforms. This channel shift concentrates specification authority with metabolic health specialists rather than procurement departments.
United States Casein Market Segmentation
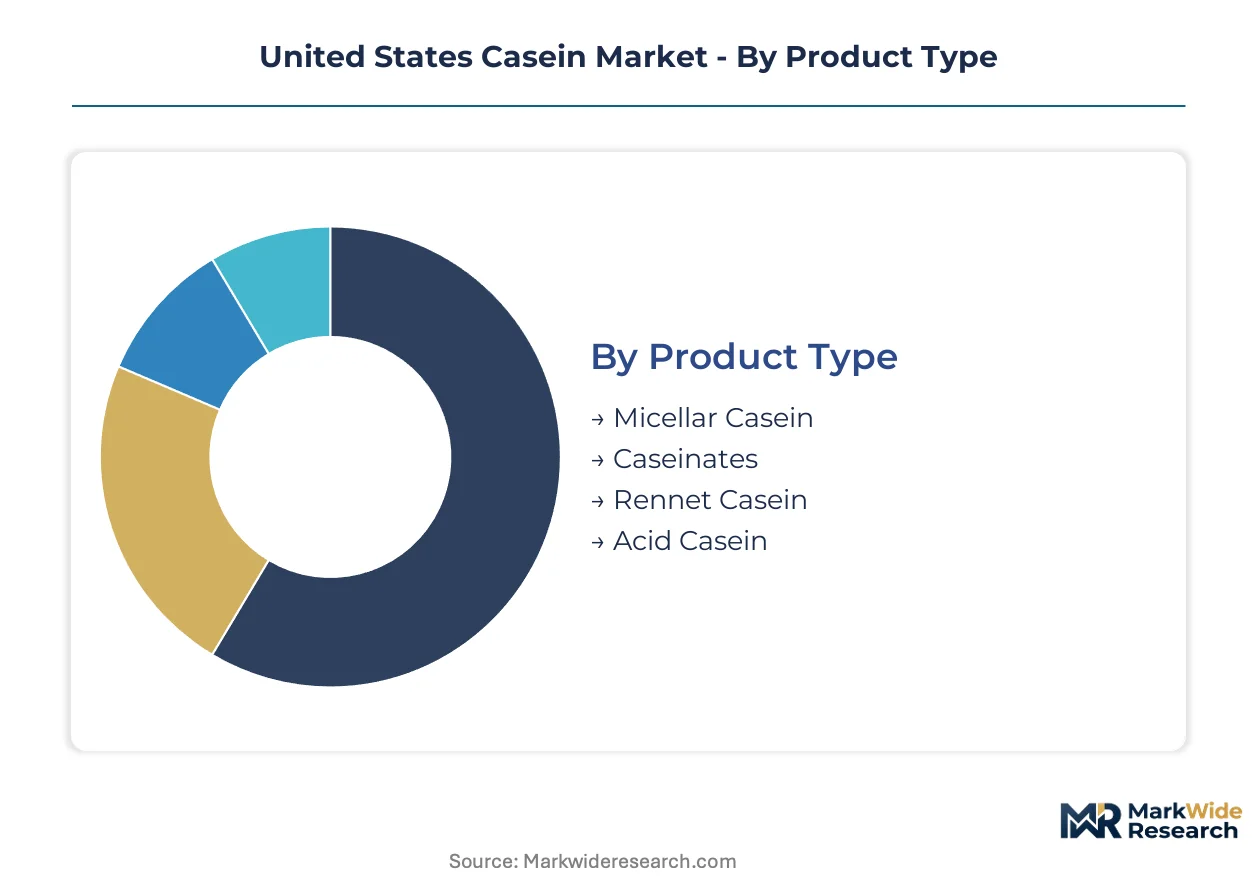
Casein procurement decisions hinge on protein purity requirements, functional specifications, and regulatory compliance burdens that vary sharply across end-use applications. Manufacturers must align grade selection with processing constraints and label claim ambitions.
Product Type:
Purity thresholds and solubility profiles drive buyer sorting between native protein structures and chemically modified derivatives.
- Micellar Casein:Native phosphoprotein micelles retain structural integrity through gentle membrane filtration, preserving slow gastric emptying kinetics prized by sports nutrition formulators. Medicare-reimbursed long-term care facilities in Florida and Arizona corridors specify this grade for enteral feeding protocols.
- Caseinates:Alkali-treated derivatives deliver superior cold-water solubility and emulsion stability, dominating ready-to-drink beverage applications and infant formula matrices where suspension uniformity is non-negotiable.
- Rennet Casein:Enzymatic precipitation yields superior melt elasticity and stretch characteristics essential to processed cheese manufacturing.
- Acid Casein:Mineral acid precipitation produces lower-cost binders facing substitution pressure from plant proteins in bakery applications.
Volume sits with caseinates; growth tilts toward micellar casein.
Application:
Formulation complexity and regulatory scrutiny intensity determine margin capture potential across consumption occasions.
- Nutritional Supplements:Overnight recovery products and clinical nutrition matrices command premium positioning through timed-release protein kinetics. Fitness-conscious consumers in Texas and Colorado drive specification authority shifts toward registered dietitians.
- Infant Formula:FDA protein content verification rulemaking threatens historical Kjeldahl assumptions, forcing amino acid profiling investments that favor suppliers with analytical capabilities.
- Dairy Products:Processed cheese manufacturing anchors steady demand for melt-functional grades.
- Bakery Products:Clean-label price competition from pea and fava isolates erodes acid casein share in binder applications.
Revenue concentrates in nutritional supplements; infant formula carries the steepest compliance burden.
End User:
Procurement sophistication and specification authority vary dramatically between commodity buyers and clinical-grade purchasers.
- Nutraceuticals:Direct-to-practitioner sampling platforms displace traditional broker networks, concentrating buying power with metabolic health specialists who demand clinical trial documentation.
- Pharmaceutical Industry:Dual FDA food additive and USDA organic certification requirements extend product launch timelines, favoring established suppliers with regulatory affairs infrastructure.
- Food & Beverage Industry:Volume procurement emphasizes cost optimization and supply security.
- Animal Feed:Commodity-grade specifications prioritize protein content per dollar over functional properties.
Specification complexity peaks with pharmaceuticals; volume scales with food and beverage.
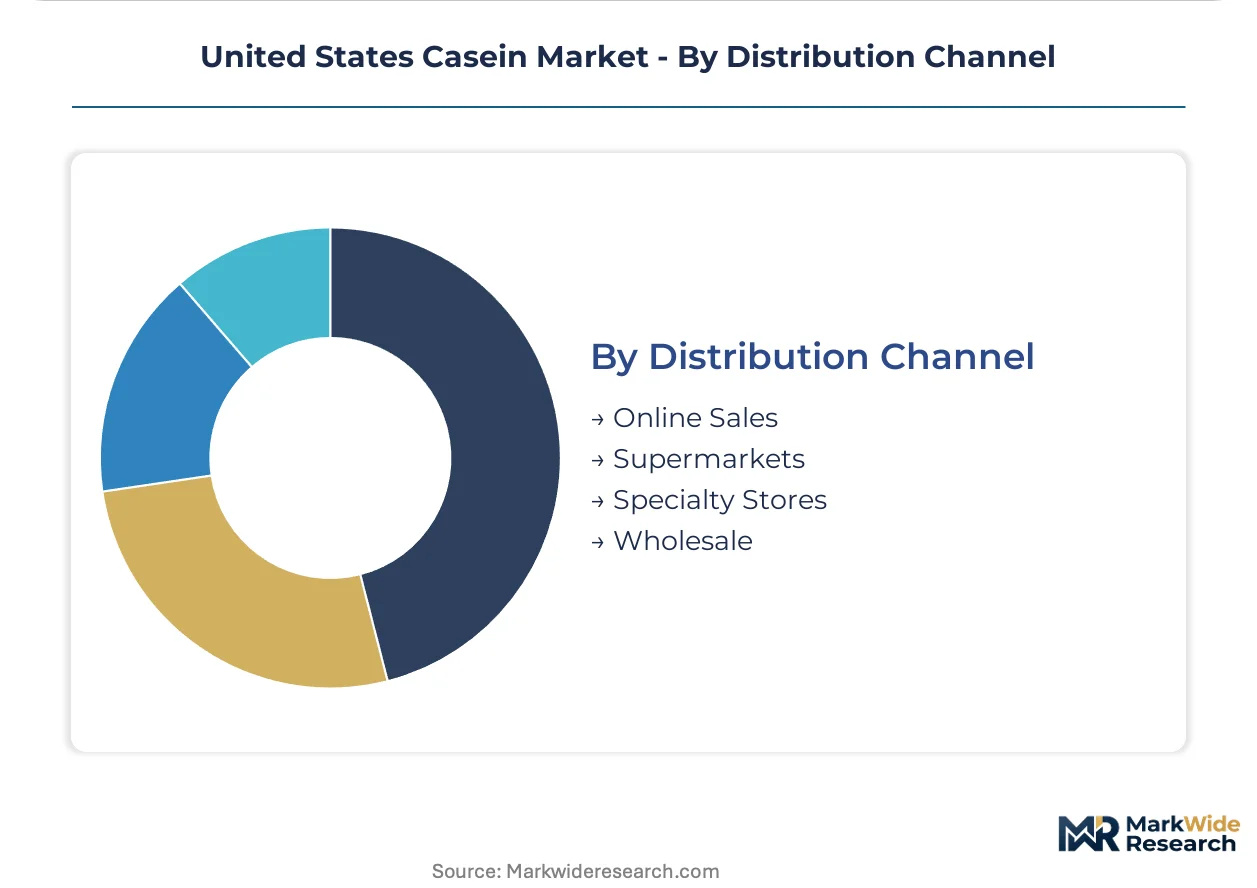
Distribution Channel:
Customer education requirements and order fragmentation patterns shape channel economics and service level investments.
- Online Sales:Specialized nutrition science platforms deliver technical documentation and clinical trial data to registered dietitians, bypassing traditional procurement departments. This channel captures formulation specification authority in sports and clinical nutrition segments.
- Wholesale:Bulk ingredient procurement by Wisconsin and California processing clusters emphasizes logistics efficiency and freshness windows.
- Supermarkets:Branded finished goods distribution dominates consumer-facing protein products.
- Specialty Stores:Premium positioning opportunities exist in organic and clean-label product lines constrained by certified herd scarcity.
Transaction volume flows through wholesale; influence and margin expansion track with online sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic casein production concentrates in the Upper Midwest dairy belt while consumption disperses across coastal population centers and Sun Belt retirement corridors. Wisconsin and California processing clusters anchor supply-side capacity. Demand-side pull concentrates in Texas, Florida, and Arizona where sports nutrition and clinical nutrition channels expand fastest.
Wisconsin
Cheese plant proximity to casein extraction facilities reduces whey permeate logistics costs and tightens ingredient freshness windows. USDA Dairy Grading Branch enforcement of quality benchmarks influences processor procurement decisions statewide. The Fox River Valley hosts membrane filtration operations supplying micellar casein to Medicare-reimbursed long-term care facilities.
California
Fitness-conscious consumers in Los Angeles and San Diego metro areas drive protein enrichment trends across sports nutrition retail channels. FDA food additive regulations govern interstate commerce compliance for Central Valley processors. The Central Valley deploys ceramic microfiltration systems that preserve native protein structure without acid denaturation.
Texas
Registered dietitians in Dallas-Fort Worth and Houston receive micellar casein clinical trial data through specialized nutrition science platforms. State-level clean-label legislation could redefine acceptable processing aids and allergen disclosure thresholds. The Austin-San Antonio corridor captures formulation specification authority in overnight recovery product development.
Florida
Sarcopenia-focused medical foods in retirement corridors remain undersupplied with specialized protein matrices. FSMA traceability mandates accelerate blockchain adoption across distribution networks serving Tampa and Miami markets. The I-4 corridor connects Gulf Coast dairy processing to Atlantic seaboard clinical nutrition channels.
Arizona
Medicare-reimbursed long-term care facilities in Phoenix and Tucson metro areas specify slow-digesting protein sources for enteral feeding protocols. IRA clean manufacturing incentives lower capital barriers for energy-efficient membrane filtration retrofits. The Salt River Valley anchors Sun Belt demand for timed-release protein kinetics in senior nutrition applications.
United States Casein Market Key Industry Players
The competitive structure tilts toward dairy cooperative and multinational ingredient conglomerate archetypes with divergent supply chain strategies. Fonterra Co-operative Group Limited and FrieslandCampina Ingredients leverage southern hemisphere milk pool access against domestic Midwest processing advantages. Three strategic archetypes dominate: ocean-spanning dairy cooperatives with integrated farm-to-ingredient control, European-headquartered nutrition ingredient specialists with flavor-mask technology portfolios, and North American protein blenders with whey-casein hybrid formulation expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with membrane filtration technology licensing representing a secondary vector.
Within the cooperative tier, Fonterra Co-operative Group Limited exemplifies farm-gate-to-ingredient vertical integration, while Arla Foods Ingredients Group P/S occupies a comparable position in European-origin supply. Among North American protein specialists, Glanbia plc represents the whey-casein hybrid formulation archetype, and Kerry Group plc sits within the integrated flavor technology tier. These three named entities anchor distinct competitive positioning vectors without exhaustive market coverage claims.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Arla Foods Ingredients Group P/S |
| FrieslandCampina Ingredients |
| Lactalis Ingredients |
| Kerry Group plc |
| AMCO Proteins |
| Farbest Brands |
| Erie Foods International Inc. |
| Glanbia plc |
| Others |
Cost & Logistics Intelligence
Medicare-reimbursed enteral feeding protocol specifications for slow-digesting protein sources are compressing procurement flexibility, forcing Wisconsin and California processors to absorb membrane filtration cost premiums while acid casein substitution by plant proteins erodes commodity-grade pricing power.
Pricing Analysis
Margin tightening in commodity acid casein reflects pea and fava protein functional parity at lower clean-label price points. Three-tier pricing structure across premium micellar, standard caseinate, and economy acid grades tracks USDA organic certification scarcity and FDA protein content verification compliance burden. Cost-down pressure on acid casein accelerates because bakery binder buyers prioritize plant-derived alternatives. Food and beverage manufacturers exhibit highest price sensitivity; pharmaceutical and clinical nutrition purchasers accept premium positioning for dual-certified ingredients.
Supply Chain Analysis
Regional distribution centers in Wisconsin's Fox River Valley and California's Central Valley operate hub-and-spoke patterns serving Texas, Florida, and Arizona demand corridors. Domestic supply concentrates in Wisconsin cheese plant clusters and California membrane filtration operations, with New Zealand-origin micellar casein filling premium tier gaps. Raw material flows draw from Upper Midwest dairy herds, southern hemisphere milk pools, and alkali treatment chemicals for caseinate production. Tariff exposure on New Zealand dairy auction cycles transmits GDT price volatility directly to US processor margins. Distribution runs through wholesale ingredient brokers and direct-to-practitioner nutrition science platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSMA traceability mandates and dual certification complexity are accelerating exit pressure on smaller processors lacking regulatory affairs infrastructure, concentrating volume with cooperative and multinational archetypes.
For Market Incumbents: Deploy membrane filtration technology licensing to capture premium micellar casein margin pools while plant protein substitution threatens acid casein revenue. Secure backward integration into certified organic dairy herds to constrain supply expansion for premium-tier competitors. Fortify regulatory affairs teams to compress 14-18 month dual FDA-USDA approval timelines. For New Entrants and Emerging Players: The mid-tier price gap between premium micellar and economy acid casein creates white-space opportunity for whey-casein hybrid formulations with timed-release kinetics. Target the senior nutrition channel in Florida and Arizona retirement corridors where sarcopenia-focused medical foods remain undersupplied. Pursue direct-to-practitioner sampling platforms to bypass entrenched broker networks and capture registered dietitian specification authority. For Investors and Strategic Acquirers: Re-rating potential sits with membrane filtration-equipped processors given IRA clean manufacturing incentives lowering capital barriers for domestic expansion. Long-term viability favors operators with Wisconsin or California geographic anchoring and established FDA food additive compliance infrastructure. Monitor FSMA blockchain adoption velocity across distribution networks as inflection indicator for traceability-compliant supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Ceramic microfiltration retrofits in California's Central Valley preserve native protein structures for overnight release formulations. |
| Backward Integration into Organic Herds | Captive supply of USDA-certified dairy constrains competitor premium-tier expansion amid certified herd scarcity. |
| Dual Certification Investment | Simultaneous FDA food additive and USDA organic approvals extend competitive moats through 14-18 month launch barriers. |
| Direct-to-Practitioner Platform Launch | Specialized nutrition science platforms concentrate buying power with Texas and Colorado registered dietitians. |
| Hybrid Protein R&D Partnership | Whey-casein blend development captures overnight recovery product slots in Austin-San Antonio corridor. |
Research Approach
Document review covered FDA food additive regulations, USDA Dairy Grading Branch quality benchmarks, and GDT auction cycle data, complemented by interviews with membrane filtration plant operators, registered dietitians in Texas and Colorado, and infant formula procurement managers. Secondary validation drew from SEC filings of protein ingredient specialists, customs records of New Zealand dairy imports, and Medicare reimbursement protocol documentation. Bottom-up volume modeling across product type, application, and end user segments was triangulated against top-down industry aggregation.
Historical shipment data from Wisconsin and California processing clusters was cross-referenced against panel input from sports nutrition formulators and clinical nutrition specialists. The analytical framework modeled product type purity tiers, application regulatory intensity, end user procurement sophistication, and distribution channel influence concentration across the projection horizon. CAGRs were derived from segment-level growth rate synthesis incorporating IRA clean manufacturing incentive uptake and FSMA traceability mandate compliance velocity.
Inputs from Medicare reimbursement databases and GDT auction clearing data were available through the study window; gaps in real-time blockchain traceability adoption metrics introduce uncertainty bands around supply chain risk assessments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Flavored Yogurt Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Low Calorie Whipped Cream Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Cheese Concentrate Market
Dairy Products
North America Milk Powder Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Fluid Milk Market