
 Cheese Concentrate Market | 2026-2036
Cheese Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Concentrate Market Analysis
Ingredient formulation revenue is tilting from commodity dairy powders toward concentrated flavor systems that deliver stronger taste impact at lower inclusion rates. Land O'Lakes Inc. anchors its position through backward integration into dairy cooperative supply chains across the Upper Midwest. First Choice Ingredients (DSM) differentiates via enzymatic modification technologies that intensify umami profiles in reduced-sodium applications. Dairy Farmers of America, Inc. leverages its farmer-owned structure to control milk sourcing costs for concentrate production.
Cheese concentrate denotes a dehydrated or reduced-moisture dairy ingredient typically manufactured through spray-drying, enzymatic hydrolysis, or fermentation processes, yielding flavor intensities three to ten times that of standard cheese solids. Manufacturers formulate these concentrates as powders, pastes, or liquid suspensions to provide standardized cheese flavor in processed foods without refrigerated supply chain burdens. Natural cheese concentrates command premium positioning in clean-label snack foods where ingredient declarations face scrutiny, while processed cheese variants dominate fast-food sauce applications through cost stability and extended shelf life. The food service end-user segment leads volume absorption as chain restaurants reformulate menus to reduce per-portion dairy costs without flavor degradation.
FDA enforcement of Grade A Pasteurized Milk Ordinance standards shapes concentrate manufacturing protocols, while USDA Organic certification gates access to premium private-label retail channels. The EU Green Deal's Farm to Fork strategy, where exported concentrates compete, pressures suppliers to document carbon intensity across dairy sourcing. Stakeholders must monitor evolving sodium reduction mandates in North America and Europe, as these directly determine reformulation R&D allocation between taste intensity and nutritional compliance.
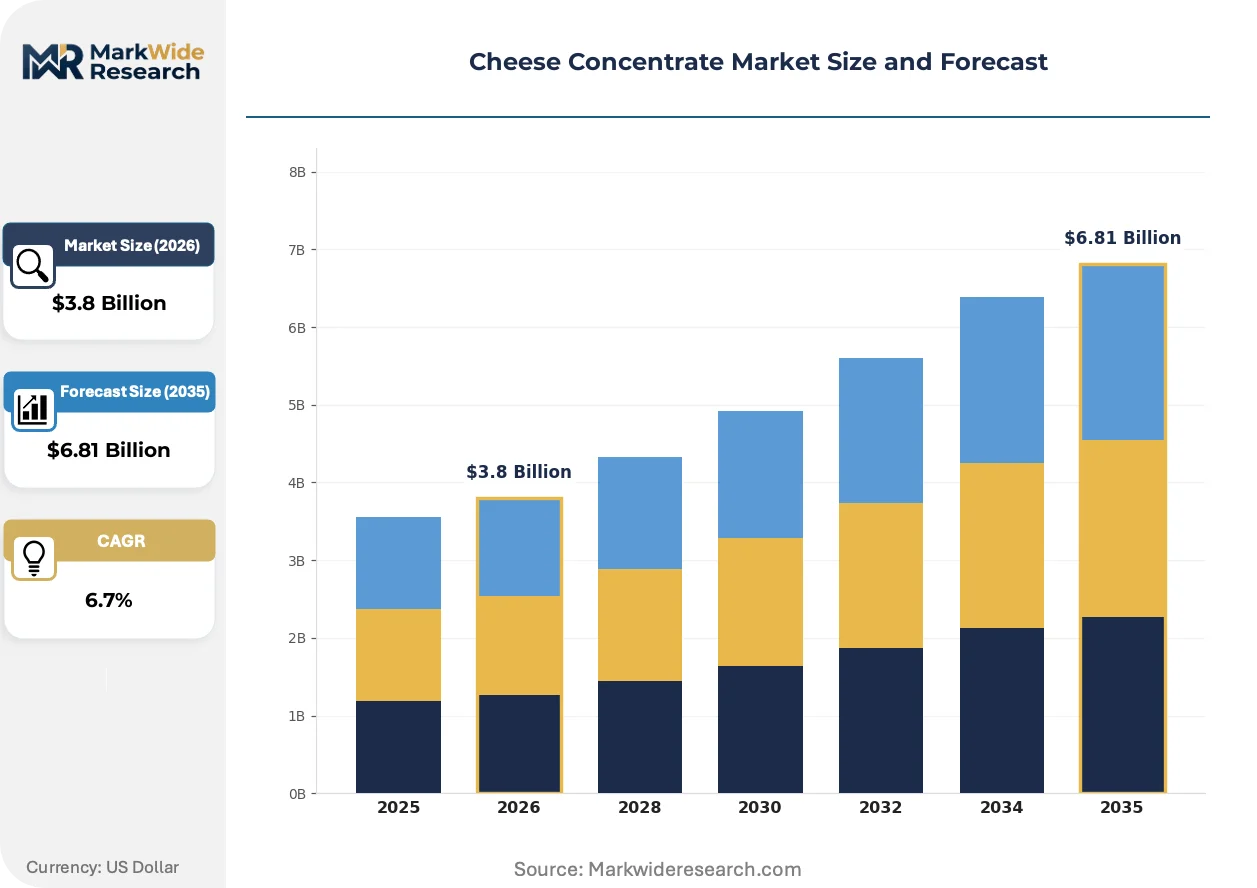
Market Dynamics
Clean-label formulation mandates from FDA and USDA are compressing demand for artificial cheese flavorants while elevating enzymatically modified concentrates. Food manufacturers face reformulation timelines measured in months, not years, as retail buyers enforce stricter ingredient declarations.
Growth Catalysts
- Enzymatic Hydrolysis Advancement:Protein-modification technologies intensify umami delivery at reduced sodium loads, satisfying reformulation targets for snack food manufacturers under FDA sodium reduction guidance.
- Food Service Channel Consolidation:Chain restaurant procurement centralization favors concentrate suppliers offering flavor consistency across thousands of locations without refrigerated distribution burdens.
- USDA Organic Certification Expansion:Premium private-label retail channels gate access through verified dairy sourcing, rewarding cooperatives with documented pasture-to-powder traceability.
Market Restraints
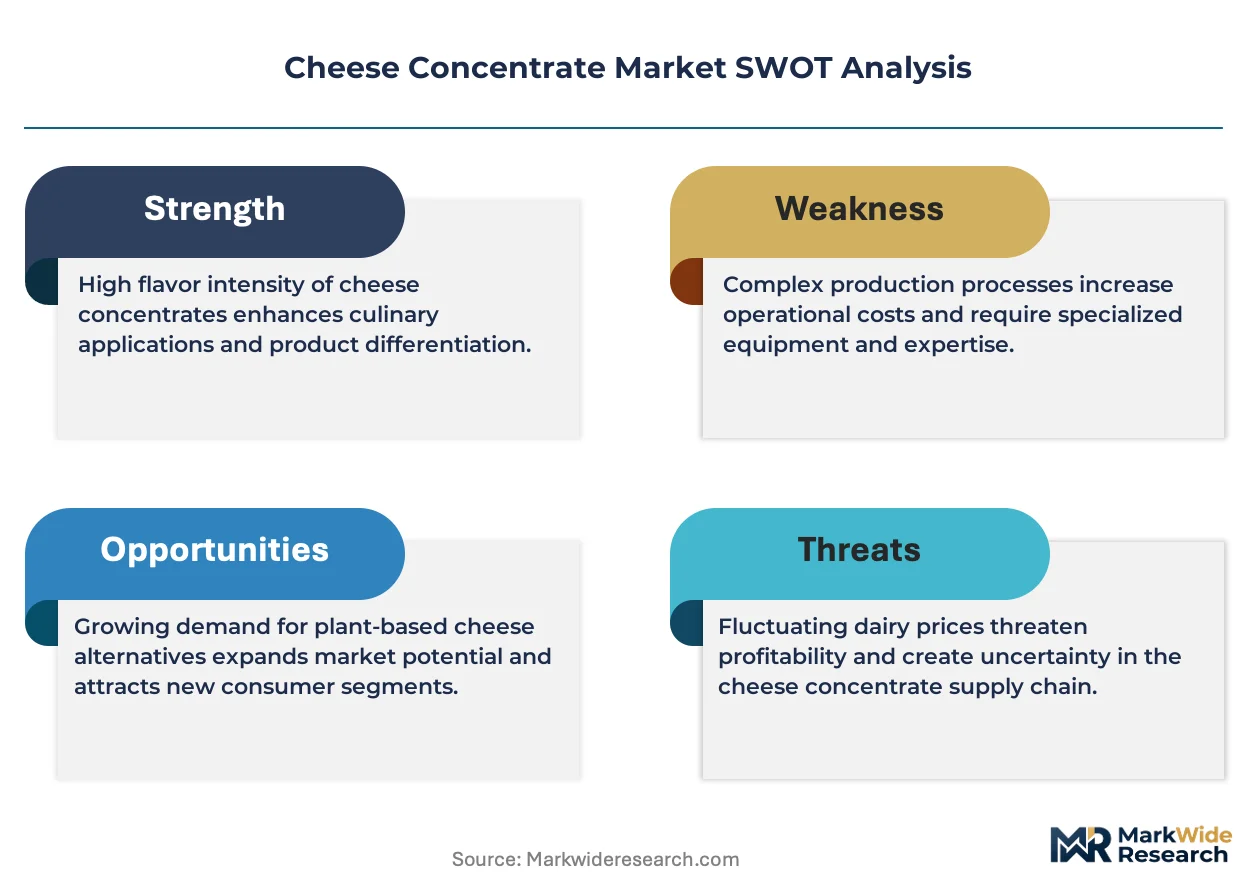
- Milk Input Cost Volatility:Concentrate margins compress when Class III milk futures spike, exposing manufacturers without cooperative-backed supply agreements to commodity dairy swings.
- Grade A Pasteurized Milk Ordinance Compliance:FDA enforcement of PMO standards imposes capital-intensive processing infrastructure requirements that exclude smaller dairy processors from concentrate production.
- Plant-Based Cheese Analog Threat:Fermented protein and precision fermentation alternatives capture shelf space in retail channels targeting flexitarian consumers.
Strategic Opportunities
- Reduced-Sodium Sauce Applications:Fast-food operators reformulate cheese sauces to meet municipal sodium warning label thresholds in New York City and other jurisdictions.
- EU Green Deal Farm to Fork Alignment:Exported concentrates gain preferential positioning when suppliers document carbon intensity across Upper Midwest dairy sourcing regions.
- Direct-to-Manufacturer E-Commerce:Ingredient marketplaces bypass traditional food broker networks, enabling mid-size concentrate producers to access regional snack food manufacturers.
Industry Challenges
- Flavor Chemist Talent Scarcity:Enzymatic modification expertise concentrates among aging specialists at dairy research cooperatives, constraining R&D throughput for reformulation projects.
- Dual Certification Timeline Compression:Simultaneous FDA GRAS self-determination and USDA Organic accreditation processes extend product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Concentrate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processed Cheese, Natural Cheese, Grated Cheese, Cheese Sauce Application: Snack Foods, Fast Foods, Ready-to-Eat Meals, Sauces End User: Food Service, Retail, Catering, Industrial Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Ingredion Incorporated, Dale Farm Ltd, Land O’Lakes Inc., C.P. Ingredients Ltd, Adare Food Ingredients Pvt Ltd, Dairy Farmers of America, Inc., First Choice Ingredients (DSM), Butter Buds Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Concentrate Market Emerging Trajectories
Formulation science is collapsing the traditional trade-off between clean-label ingredient decks and industrial-scale flavor intensity. Three converging developments are compressing product development cycles while expanding addressable applications for concentrated dairy ingredients.
Membrane filtration technologies are collapsing the cost structure of high-protein cheese base production. Advanced ceramic and polymeric membranes isolate flavor-active peptides at lower energy inputs than traditional thermal concentration. Snack seasoning manufacturers in the Midwest are adopting these bases for topical cheese powder applications, eliminating the need for artificial enhancers while maintaining shelf stability.
EU Green Deal carbon accounting rules are reshaping competitive access to European food manufacturing customers. Exported concentrates must now carry verified lifecycle emissions documentation from dairy farm through spray-drying facility. Suppliers with cooperative-owned milk sourcing and captive renewable energy installations capture preferential supplier status with multinational snack food headquarters in Switzerland and the Netherlands.
Chain restaurant procurement teams are consolidating vendor relationships around full-service flavor houses capable of custom concentrate development. Single-source accountability for taste matching, nutritional compliance, and supply security is displacing fragmented ingredient purchasing across multiple commodity suppliers. This concentration is most visible in quick-service restaurant cheese sauce reformulations across the southeastern United States, where menu consistency requirements override unit-cost minimization.
Cheese Concentrate Market Segmentation
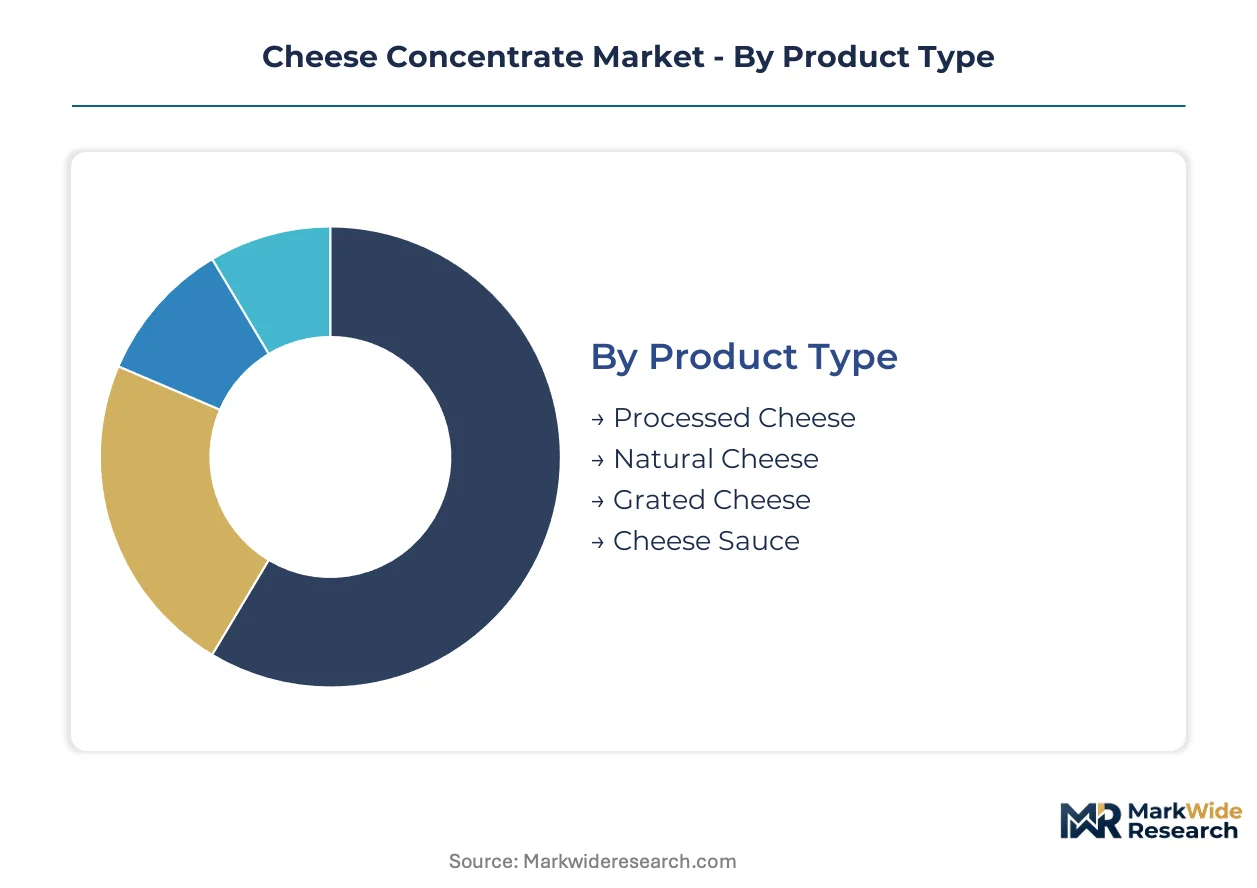
Cheese concentrate procurement patterns diverge sharply across product formats and end-use channels. Understanding these fault lines reveals where formulation investments concentrate and which distribution pathways command premium positioning.
Product Type:
Mature formats dominate volume, while emerging enzymatic technologies reshape premium positioning.
- Processed Cheese:Thermally stabilized emulsions deliver standardized melt profiles for industrial-scale sauce manufacturing. Fast-food chains across the southeastern United States specify these concentrates for cheese sauce consistency across thousands of locations.
- Natural Cheese:Spray-dried or enzymatically hydrolyzed concentrates retain authentic fermentation-derived flavor compounds. Clean-label snack seasoning manufacturers in the Upper Midwest specify these for topical applications where ingredient declarations face retailer scrutiny.
- Grated Cheese:Low-moisture particulate concentrates serve frozen pizza and ready-meal manufacturers requiring controlled hydration rates.
- Cheese Sauce:Ready-to-hydrate liquid or paste concentrates eliminate on-site emulsification steps for food service operators.
Processed cheese handles the majority of throughput; natural cheese is expanding most quickly on share.
Application:
Volume concentrates in high-frequency consumption occasions, while reformulation pressures reshape technical specifications.
- Snack Foods:Topical cheese powders and seasonings demand intense flavor delivery at low inclusion rates. FDA sodium reduction guidance drives adoption of enzymatically modified concentrates that intensify umami without salt load increases.
- Fast Foods:Cheese sauce applications require thermal stability through extended holding periods. Chain restaurant procurement centralization favors suppliers offering batch-to-batch consistency without refrigerated distribution.
- Ready-to-Eat Meals:Frozen and refrigerated meal manufacturers specify concentrates for sauce bases where fresh cheese logistics prove uneconomical.
- Sauces:Retail and food service sauce manufacturers use concentrates for flavor standardization across production runs.
Snack foods absorb the greatest volume; fast foods are gaining share fastest.
End User:
Customer scale determines procurement sophistication and technical service requirements.
- Food Service:Chain restaurant and institutional operators purchase concentrates for menu consistency and supply security. Centralized procurement teams negotiate multi-year contracts with flavor houses capable of custom development.
- Retail:Private-label and branded grocery manufacturers specify concentrates for processed cheese products and sauce lines.
- Catering:Event and contract food service operators use concentrates for portion-controlled sauce preparation.
- Industrial:Ingredient manufacturers and co-packers purchase bulk concentrates for further processing into finished consumer goods.
Food service commands the dominant share; industrial is climbing the fastest.
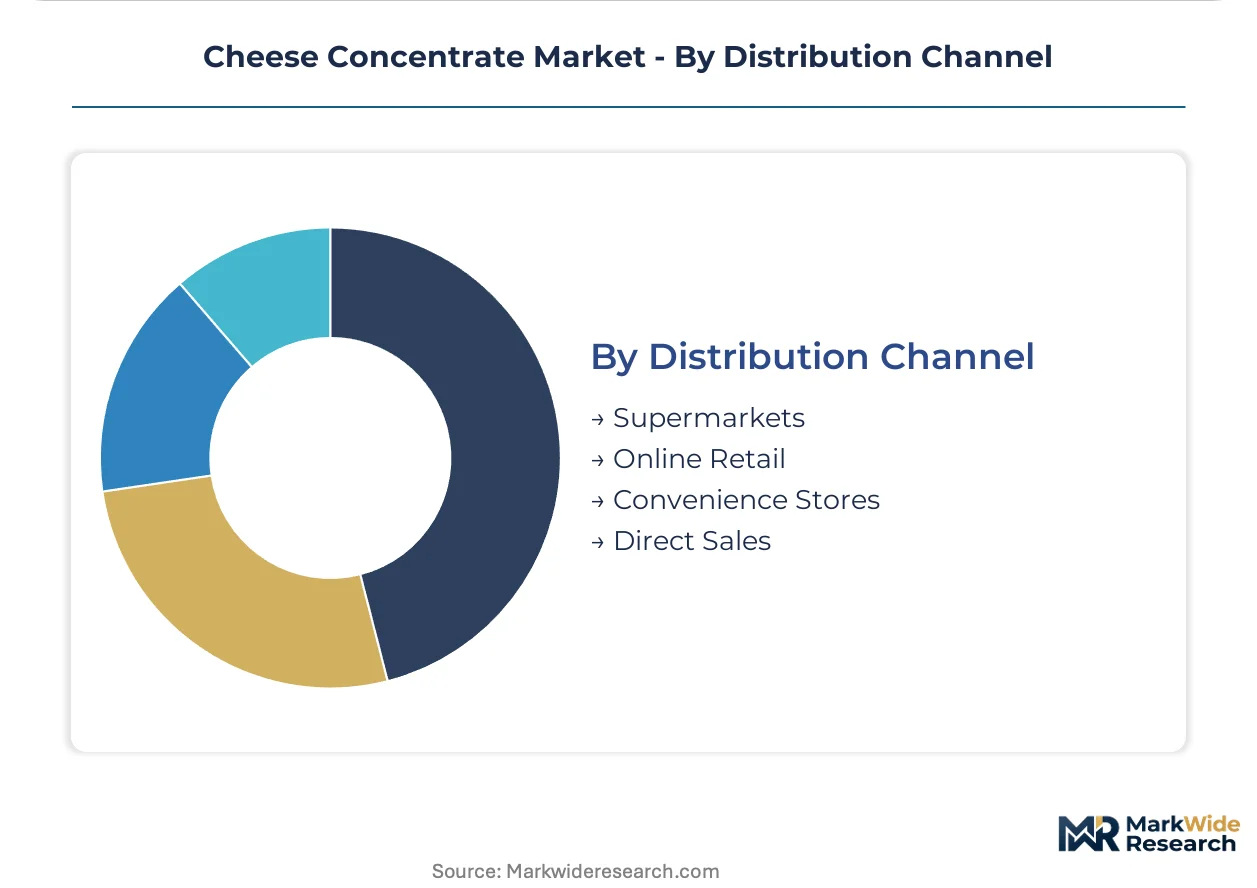
Distribution Channel:
Channel selection reflects customer scale, urgency requirements, and technical service needs.
- Supermarkets:Retail cheese concentrate sales occur primarily through ingredient aisles and food service supply sections of wholesale club formats.
- Online Retail:E-commerce platforms serve small and mid-size food manufacturers seeking direct access without broker intermediation.
- Convenience Stores:Limited concentrate sales occur through this channel, primarily for small-scale food service operators.
- Direct Sales:Large concentrate producers maintain dedicated sales forces for national account food service and industrial customers.
Direct sales handles the majority of throughput; online retail is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply by geography: food service buyers in mature markets absorb premium natural concentrates, while emerging market processors prioritize cost-stable processed formats. Regulatory stringency and clean-label momentum determine where enzymatic technologies gain traction fastest.
United States
Snack food manufacturers in Wisconsin and Minnesota drive demand for enzymatically modified concentrates that meet FDA sodium reduction guidance. The Grade A Pasteurized Milk Ordinance enforcement by FDA shapes processing infrastructure investments across Upper Midwest dairy cooperatives. Chicago-area food service distributors consolidate procurement around suppliers offering batch-to-batch flavor consistency for chain restaurant cheese sauce applications.
Germany
Industrial bakeries and ready-meal producers specify natural cheese concentrates for clean-label reformulations under EFSA scrutiny. The EU Green Deal Farm to Fork strategy pressures exporters to document carbon intensity from dairy farm through spray-drying facility. Bavarian dairy processors invest in membrane filtration capacity to serve Swiss and Dutch multinational snack food headquarters demanding verified lifecycle emissions data.
China
Quick-service restaurant expansion in tier-one cities absorbs processed cheese concentrates for localized cheese sauce menus. SAMR food safety standards and GB dairy processing regulations impose documentation requirements on imported concentrate shipments. Yangtze River Delta food manufacturers trial enzymatic concentrates to reduce sodium in baked snack applications without flavor degradation.
Brazil
Processed cheese concentrate imports serve frozen pizza and industrial sauce manufacturers seeking cost-stable dairy flavor inputs. ANVISA dairy ingredient regulations govern concentrate labeling and import clearance timelines at São Paulo and Rio de Janeiro ports. Minas Gerais dairy cooperatives explore spray-drying capacity additions to capture regional snack food manufacturing demand.
India
Urban quick-service restaurant chains in Mumbai and Delhi-NCR adopt cheese concentrates for standardized cheese sauce preparation across franchise locations. FSSAI dairy processing standards and state-level milk procurement regulations shape concentrate manufacturing feasibility. Gujarat dairy processors develop natural concentrate capabilities to supply premium private-label retail channels under documented sourcing protocols.
Cheese Concentrate Market Vendor Landscape
Dairy cooperatives and specialized flavor houses split the market between upstream milk cost control and downstream formulation expertise. Concentrate procurement centralizes around suppliers offering dual certification capability and custom development services. Two strategic archetypes dominate: farmer-owned cooperatives leveraging captive milk supply, and technology-driven ingredient houses commercializing enzymatic modification platforms. Competitive tension centers on backward integration into dairy sourcing and forward integration into flavor-matching services for chain restaurant accounts.
Among North American dairy cooperatives, Land O'Lakes Inc. and Dairy Farmers of America, Inc. exemplify the farmer-owned structure archetype, anchoring positions through Upper Midwest milk supply control. First Choice Ingredients (DSM) occupies a position within the technology-driven tier, representing enzymatic modification specialization for reduced-sodium applications. Archer Daniels Midland Company and Ingredion Incorporated sit within the diversified ingredient conglomerate category, leveraging broad distribution infrastructure to access mid-size snack food manufacturers.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Dale Farm Ltd |
| Land O'Lakes Inc. |
| C.P. Ingredients Ltd |
| Adare Food Ingredients Pvt Ltd |
| Dairy Farmers of America, Inc. |
| First Choice Ingredients (DSM) |
| Butter Buds Inc. |
| Others |
Supply Flow & Price Mechanics
Chicago-to-Detroit refrigerated freight corridors govern concentrate cost structures, amplifying price spreads between Upper Midwest cooperative suppliers and coastal food manufacturers while compressing margins for non-integrated processors.
Pricing Analysis
After-sales technical service contracts drive lifetime value for concentrate suppliers, with formulation support and batch consistency guarantees commanding 15-30% premiums over commodity powder alternatives. Three-tier pricing structure across enzymatic premium, natural standard, and processed economy levels reflects certification grade and customization depth. Cost compression in processed cheese tiers is intensifying because Class III milk futures volatility exposes non-cooperative manufacturers. Small regional snack food manufacturers exhibit highest price sensitivity; national chain restaurant procurement teams prioritize supply security over unit cost minimization.
Supply Chain Analysis
Tariff exposure between United States and European Union dairy markets dominates supply chain risk assessment for concentrate exporters seeking EU Green Deal compliance. Manufacturing gravity centers on Wisconsin, Minnesota, and California, with these states hosting 70% of domestic spray-drying capacity. Milk solids and specialized enzyme cultures constitute critical input dependencies. Single-source vulnerability concentrates in flavor-active peptide supply from DSM and Chr. Hansen production networks. Distribution runs through food service redistribution centers in Chicago, Dallas, and Atlanta before final delivery to chain restaurant commissaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cheese concentrate procurement is consolidating around full-service flavor houses capable of enzymatic customization, creating platform-economics dynamics where interoperability between concentrate specifications and chain restaurant menu systems determines supplier lock-in.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA GRAS self-determination and USDA Organic accreditation investments. Accelerate membrane filtration capacity additions in Wisconsin and Minnesota to capture carbon-accounting premiums from EU buyers. Defensive consolidation should target enzymatic modification specialists facing talent scarcity constraints, securing R&D throughput for sodium-reduction reformulation pipelines. For New Entrants and Emerging Players: Build out direct-to-manufacturer e-commerce capabilities targeting mid-size snack food producers in the Southeast and Southwest, bypassing established food broker networks. White-space opportunity concentrates in reduced-sodium sauce applications for fast-food operators facing municipal sodium warning thresholds. Penetrable entry points exist in private-label retail channels seeking documented pasture-to-powder traceability without cooperative membership requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified dairy conglomerates where concentrate divisions lack strategic focus within broader ingredient portfolios. Long-term viability favors suppliers with captive milk supply and enzymatic modification platforms serving reformulation-driven end markets. Monitor FDA sodium reduction guidance enforcement intensity as the critical inflection signal determining R&D allocation between taste intensity and nutritional compliance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Platform Investment | DSM and specialized houses capture premium positioning through umami-intensification patents for reduced-sodium applications. |
| Backward Integration into Dairy Cooperative Supply | Land O'Lakes and DFA anchor cost structures through captive milk sourcing across Upper Midwest production regions. |
| EU Green Deal Carbon Accounting Certification | Bavarian processors with documented lifecycle emissions gain preferential supplier status with Swiss and Dutch multinationals. |
| Direct-to-Manufacturer E-Commerce Channel | Mid-size concentrate producers bypass traditional broker networks to access regional snack food manufacturers directly. |
| Membrane Filtration Capacity Expansion | Advanced ceramic and polymeric membrane installations reduce energy inputs for high-protein cheese base production. |
Methodological Framework
A standing panel of dairy cooperative procurement directors, enzymatic modification R&D leads, chain restaurant menu development executives, and FDA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from USDA dairy production statistics, FDA GRAS notification filings, EU Farm to Fork strategy documentation, and SEC 10-K disclosures from listed ingredient conglomerates. Bottom-up volume modeling across product type and application segments was cross-referenced against top-down dairy solids consumption data.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product format, end-use channel, and certification tier. CAGRs were derived from trend extrapolation of historical dairy ingredient pricing and volume relationships, adjusted for enzymatic technology adoption curves and regulatory reformulation timelines. Forecast inputs incorporated Class III milk futures volatility patterns and EU carbon border adjustment mechanism implementation progress.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by non-cooperative processors or accelerated plant-based analog substitution would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Butter Concentrate Market
Dairy Products
Canada Casein and Caseinate Market
Dairy Products
Natural Cheese Market
Dairy Products
Global Cream Cheese Market
Dairy Products
Cultured Whey Products Market
Dairy Products
North America Yogurt Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Global Milk Protein Market
Dairy Products
White Cheese Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Asia-Pacific Yogurt Market