
 Lactose Free Probiotic Yogurt Market | 2026-2036
Lactose Free Probiotic Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose Free Probiotic Yogurt Market Foresight
Retail consumer demand for digestive wellness solutions is rebalancing the end-use vertical mix away from food services and toward direct household purchasing. Danone leverages its European cold-chain infrastructure to sustain refrigerated probiotic viability across multiple lactose-free SKUs. Nestlé anchors its portfolio through specialized fermentation protocols that preserve live cultures in reduced-lactose matrices. Chobani competes by controlling premium shelf placement in North American supermarket dairy aisles.
Lactose free probiotic yogurt denotes a fermented dairy product enzymatically treated with beta-galactosidase to hydrolyze lactose below 0.5 grams per serving, then inoculated with live bacterial strains such as Lactobacillus acidophilus and Bifidobacterium lactis to deliver defined colony-forming unit counts. The category serves consumers with primary or secondary lactase deficiency who require digestible protein and calcium sources without gastrointestinal distress. Drink-format products lead volume throughput due to convenience positioning, while cup and tub segments capture margin pools through premium positioning and multi-serve household packs. Online stores represent the fastest-growing distribution channel as direct-to-consumer subscription models reduce retail intermediary costs for specialty probiotic lines.
The FDA enforces dairy identity standards and live culture labeling requirements that determine whether products qualify for probiotic health claims in the United States. EFSA evaluates substantiation dossiers for gut health and immune function claims under EU nutrition and health claims regulation, creating divergent approval pathways for cross-border marketers. India's FSSAI mandates lactose threshold declarations and microbial count standards for functional dairy imports. Stakeholders must monitor evolving strain-specific approval criteria and cold-chain traceability mandates to secure market access across jurisdictions.
Market Dynamics
EU F-Gas Regulation mandates are forcing cold-chain fermentation equipment upgrades across European dairy processing facilities, compressing operating margins while accelerating capital redeployment toward compliant refrigeration systems.
Growth Catalysts
- Digestive wellness prioritization:Retail consumers with lactase deficiency are expanding household purchasing of functional dairy alternatives over conventional yogurt formats.
- REACH framework compliance:Stricter chemical safety standards for processing equipment materials are filtering out subscale operators and consolidating viable supply bases.
- Beta-galactosidase enzyme optimization:Improved hydrolysis protocols are reducing lactose residual thresholds below 0.5 grams per serving while preserving protein integrity.
Market Restraints
- Live culture viability costs:Cold-chain maintenance for probiotic preservation requires continuous refrigeration expenditure that elevates unit economics above conventional yogurt.
- Strain approval bottlenecks:EFSA's substantiation requirements for gut health claims create multi-year dossier timelines that delay product launches.
- Plant-based substitution:Oat and almond fermented alternatives are capturing price-sensitive consumers seeking dairy-free positioning without enzymatic processing complexity.
Strategic Opportunities
- Direct-to-consumer subscription models:Online stores are reducing retail intermediary costs for specialty probiotic lines with defined CFU counts.
- Drink-format convenience positioning:Portable consumption occasions in commuter corridors and fitness channels remain underpenetrated relative to cup formats.
- India FSSAI import pathways:Microbial count standard harmonization for functional dairy imports is opening formal market access for compliant exporters.
Industry Challenges
- Fermentation technician scarcity:Specialized expertise in maintaining live culture viability during lactose hydrolysis is concentrated among aging workforce cohorts in traditional dairy regions.
- Cross-jurisdiction label compliance:Divergent FDA and EFSA probiotic health claim thresholds force SKU fragmentation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose Free Probiotic Yogurt Market |
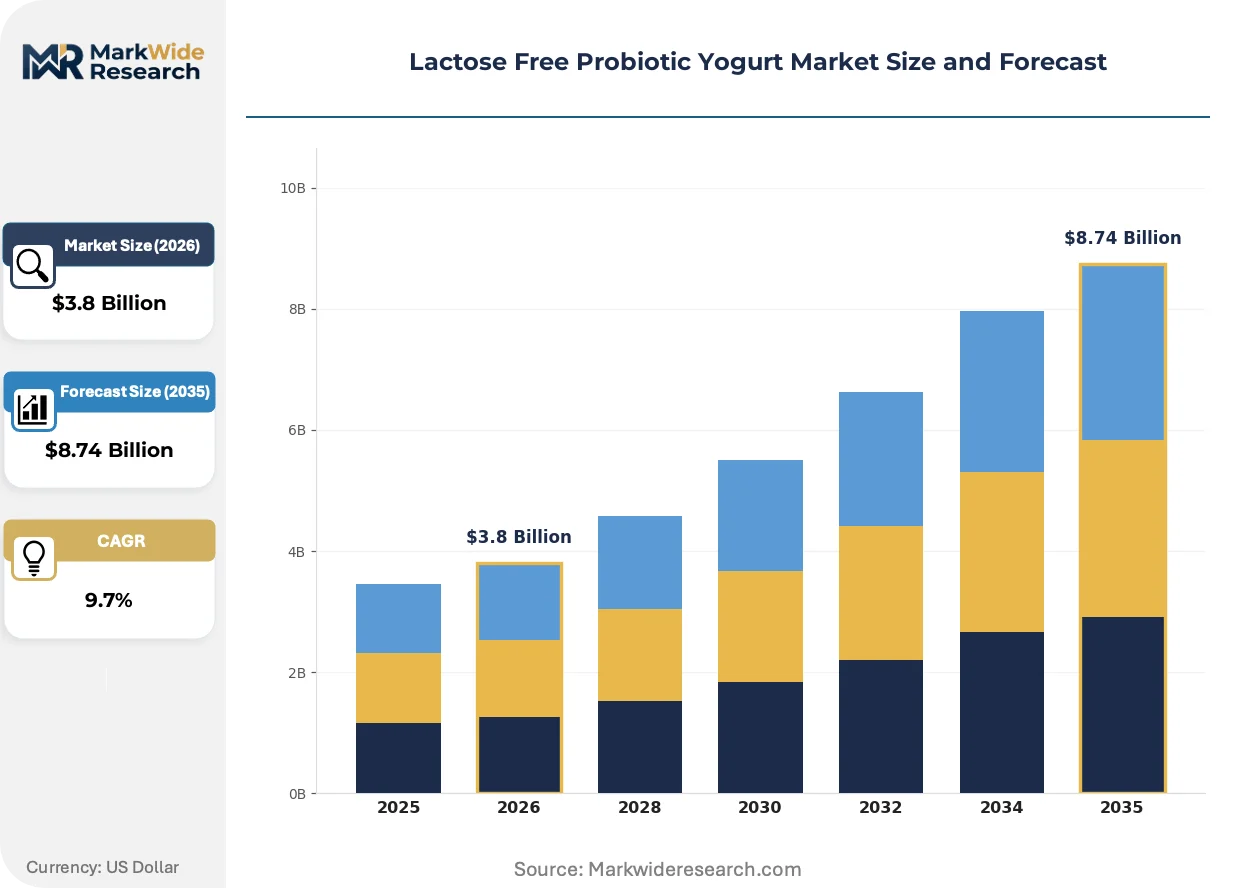
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drinks, Cups, Pouches, Tubs End User: Retail Consumers, Food Services, Health Clubs, Educational Institutions Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores Flavor: Plain, Strawberry, Blueberry, Mango |
| Companies Covered | Danone, Nestlé, Chobani, General Mills, Yakult Honsha, Lifeway Foods, Valio, Lactalis Group, Fage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose Free Probiotic Yogurt Market Shifts & Advancements
Processing technology and distribution architecture are actively reconfiguring how lactose-free probiotic yogurt reaches end consumers, with implications for shelf stability, regulatory compliance, and margin capture.
Single-serve aseptic filling systems are decentralizing production geography by enabling smaller-batch fermentation at distributed dairy facilities rather than centralized plants. Regional cooperatives in Bavaria and Lombardy are adopting these systems to supply local retail networks without intercontinental cold-chain dependency. This compression of production-to-shelf distance is reducing spoilage rates and expanding viable distribution radii for live-culture products.
EFSA's evolving strain-specific approval criteria under EU nutrition and health claims regulation are tightening substantiation requirements for immune function positioning. Manufacturers must now submit clinical dossiers for individual bacterial combinations rather than generic probiotic categories. German and Dutch processors are responding by consolidating R&D partnerships with academic microbiome research centers to preempt regulatory rejection.
Subscription-based replenishment models are displacing conventional supermarket dairy aisle purchasing among health-conscious households seeking consistent CFU delivery. Direct-to-consumer platforms in urban clusters are capturing recurring revenue streams that bypass traditional retail slotting fees. This channel rotation is most visible in metropolitan Germany where premium probiotic SKU velocity already exceeds conventional yogurt growth rates.
Lactose Free Probiotic Yogurt Market Segmentation
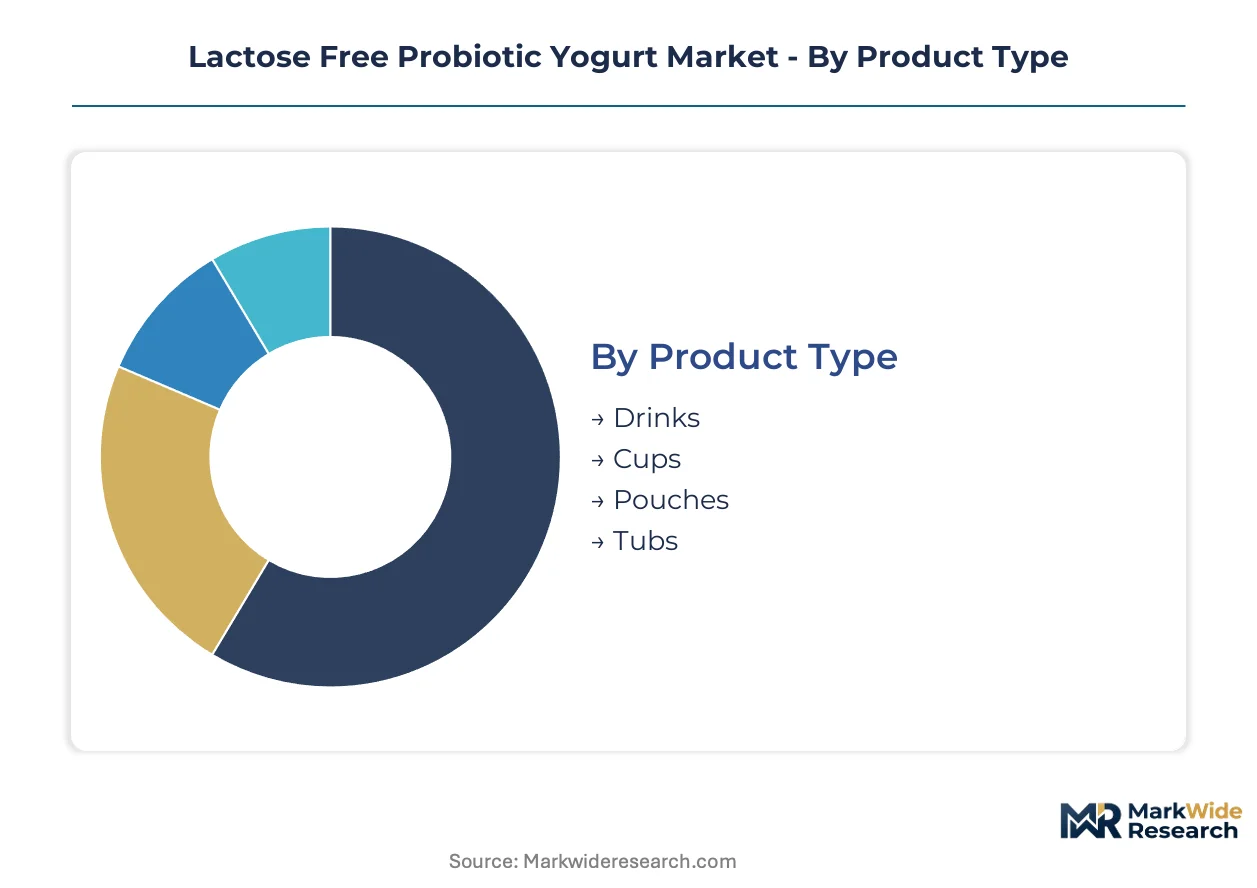
Format fragmentation in lactose-free probiotic yogurt reflects divergent consumption occasions and cold-chain capabilities. Manufacturers must align viscosity, packaging integrity, and live culture stability with specific channel requirements and end-user refrigeration access.
Product Type:
Reformulation cycles for enzymatic hydrolysis and probiotic viability are shortening as processors compete on convenience and portion control.
- Drinks:Fluid formulations enable rapid consumption without utensil requirements. German commuter corridors and fitness channels are absorbing volume as on-the-go digestive wellness positioning gains traction among urban professionals.
- Cups:Single-serve rigid packaging preserves texture integrity for spoonable formats. Premium household penetration in metropolitan clusters depends on refrigerated shelf placement and multi-pack bundling strategies.
- Pouches:Flexible packaging reduces material cost and shipping weight for child-oriented SKUs. Lunchbox convenience drives adoption in educational feeding programs with limited refrigeration.
- Tubs:Multi-serve containers target family replenishment and food service portioning. Extended shelf-life requirements after opening challenge probiotic count maintenance.
Volume placements concentrate in Cups; the faster expansion belongs to Drinks.
End User:
Procurement authority and refrigeration infrastructure determine margin capture across distinct consumption environments.
- Retail Consumers:Direct household purchasing dominates absolute volume as subscription models bypass retail intermediaries. German health-conscious shoppers drive premium SKU velocity through online replenishment.
- Food Services:Cafeteria and hospitality procurement requires bulk format compatibility and extended holding stability. Live culture degradation during service holding limits menu penetration.
- Health Clubs:Post-workout protein and digestive positioning targets recovery-oriented consumption. Grab-and-go cooler placement depends on exclusive distribution agreements with facility operators.
- Educational Institutions:School feeding programs mandate portion-controlled packaging and allergen labeling compliance. Public procurement tenders prioritize cost efficiency over probiotic strain diversity.
Absolute volume concentrates with Retail Consumers; Health Clubs are climbing the fastest.
Distribution Channel:
Cold-chain investment requirements and slotting fee structures filter channel access for live-culture product lines.
- Supermarkets:Refrigerated dairy aisle placement remains the primary volume conduit despite high trade spending. Bavarian and Lombardy retail cooperatives are compressing production-to-shelf distance through distributed fermentation.
- Online Stores:Direct-to-consumer platforms eliminate retail intermediary margins and enable subscription-based CFU consistency. Urban German clusters show highest conversion for specialty probiotic lines.
- Specialty Stores:Health food and organic retailers command premium positioning for defined strain counts and clean-label positioning. Limited geographic footprint constrains national scale.
- Convenience Stores:Impulse purchase occasions favor drink-format portability and single-serve pricing. Refrigerated space competition with conventional dairy limits SKU breadth.
Supermarkets retain volume dominance; Online Stores are gaining share fastest.
Flavor:
Flavor development must mask residual enzymatic processing notes while preserving clean-label positioning.
- Plain:Unflavored bases serve ingredient applications and sugar-conscious positioning. Functional food manufacturers value neutral profiles for smoothie and bowl assembly.
- Strawberry:Classic fruit positioning commands highest recognition across age demographics. German retail data shows consistent velocity in family-oriented multi-packs.
- Blueberry:Antioxidant association reinforces digestive wellness marketing claims. Premium pricing acceptance depends on visible fruit particulate inclusion.
- Mango:Tropical profiles target ethnic grocery channels and experimental flavor seekers. Supply seasonality constrains year-round formulation consistency.
Strawberry maintains volume leadership; Mango shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Bavaria and North Rhine-Westphalia concentrate European lactose-free probiotic yogurt capacity through cold-chain infrastructure incentives. German health-conscious shoppers drive premium SKU velocity through subscription replenishment models.
Germany
Urban professionals in Berlin and Munich prioritize digestive wellness positioning in commuter corridors. The EU F-Gas Regulation mandates refrigeration equipment upgrades across Bavarian dairy processing facilities. Regional cooperatives in Lower Bavaria deploy single-serve aseptic filling systems to compress production-to-shelf distance for live-culture products.
United States
Health club procurement and fitness channel placement expand drink-format consumption among recovery-oriented consumers. FDA dairy identity standards and live culture labeling requirements determine probiotic health claim eligibility. Chobani controls premium shelf placement in Northeast corridor supermarket dairy aisles through exclusive distribution agreements.
India
Educational feeding programs and school lunchbox applications drive pouch-format demand for child-oriented SKUs. FSSAI mandates lactose threshold declarations and microbial count standards for functional dairy imports. Maharashtra-based processors navigate import pathway harmonization to secure formal market access for compliant exporters.
Japan
Aging demographics with secondary lactase deficiency expand household purchasing of spoonable cup formats. METI guidelines influence functional food substantiation protocols for gut health positioning. Kanto region processors partner with academic microbiome research centers to preempt strain-specific approval bottlenecks.
Netherlands
Organic and clean-label positioning commands premium pricing in Randstad metropolitan retail networks. REACH framework compliance filters subscale operators from viable processing equipment supply bases. Eindhoven region dairy cooperatives adopt distributed fermentation architecture to supply local retail without intercontinental cold-chain dependency.
Lactose Free Probiotic Yogurt Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational dairy conglomerates controlling refrigerated distribution infrastructure while regional cooperatives capture localized fermentation efficiency. The vendor base concentrates among three strategic archetypes: cold-chain integrators with pan-regional logistics networks, enzyme optimization specialists preserving protein integrity during hydrolysis, and direct-to-consumer platforms bypassing retail slotting fees. Dominant competitive moves include backward integration into beta-galactosidase enzyme sourcing and strategic partnerships with academic microbiome research centers for strain-specific dossier preparation.
Among European cold-chain integrators, Danone and Nestlé occupy positions exemplifying multinational infrastructure leverage, while Chobani anchors the premium-tier vector in North American supermarket dairy aisles. These three entities represent divergent geographic concentration strategies: Danone leverages distributed fermentation across Bavarian and Lombardy cooperatives, Nestlé anchors specialized fermentation protocols for reduced-lactose matrices, and Chobani exemplifies shelf-placement dominance through exclusive retail agreements.
| Leading Market Players |
|---|
| Danone |
| Nestlé |
| Chobani |
| General Mills |
| Yakult Honsha |
| Lifeway Foods |
| Valio |
| Lactalis Group |
| Fage |
| Others |
Supply & Pricing Matrix
Specialized fermentation technicians concentrated in Bavaria and Lower Saxony drive labor-cost differentials that widen pricing-tier spreads between artisanal cooperative brands and multinational dairy conglomerates. Cold-chain maintenance requirements under EU F-Gas Regulation compress margins at economy tiers while premium subscription models absorb skilled-labor premiums through direct-to-consumer pricing power.
Pricing Analysis
Short lead-time premiums for live-culture freshness command pricing power in subscription replenishment channels, while extended-holding spot inventory discounts penetrate conventional retail. Three-tier pricing structure across premium, standard, and economy levels stratifies by strain diversity certification and cold-chain integrity guarantees. Pricing pressure stems from plant-based oat and almond fermented alternatives capturing price-sensitive consumers. Retail consumers seeking defined CFU counts show least price sensitivity; educational institutional procurement tenders exhibit highest elasticity.
Supply Chain Analysis
Beta-galactosidase enzyme supply rests on Danish and Dutch specialty biotech producers, while live culture strain banks concentrate in German and Japanese academic microbiome research centers. Aseptic filling equipment draws from Italian and Swiss precision engineering manufacturers; cold-chain refrigeration hinges on German and French industrial cooling specialists. Single-source vulnerability in proprietary strain licensing creates supply risk for immune-function positioning claims. Distribution runs through regional dairy cooperatives with compressed production-to-shelf radii, supplemented by direct-to-consumer cold-chain logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU F-Gas Regulation and REACH framework mandates erect barrier-to-entry moats favoring capitalized incumbents with distributed fermentation infrastructure.
For Market Incumbents: Deepen backward integration into beta-galactosidase enzyme sourcing to secure hydrolysis protocol cost control against specialty biotech supplier pricing power. Expand single-serve aseptic filling capacity in Bavarian and Lombardy regional cooperatives to compress production-to-shelf distance and defend margin position against plant-based fermented alternative substitution.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium subscription probiotic lines and economy conventional yogurt creates white-space opportunity in health club grab-and-go cooler placement and educational institutional pouch-format feeding programs. Target underpenetrated commuter corridor drink-format channels with portable digestive wellness positioning, leveraging direct-to-consumer platform launch to bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with enzyme optimization specialists possessing proprietary lactose hydrolysis protocols given escalating EFSA strain-specific substantiation requirements. Long-term viability over a multi-year horizon favors targets with captive strain banks and academic microbiome research center partnerships. Watch EFSA immune-function claim approval timelines as inflection indicator for premium pricing power expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Sourcing | Captive beta-galactosidase supply secures hydrolysis cost control against Danish and Dutch biotech supplier concentration. |
| Distributed Fermentation Architecture | Single-serve aseptic filling systems in Bavaria and Lombardy reduce cold-chain spoilage and expand viable distribution radii. |
| Strain-Specific Dossier Partnerships | Academic microbiome research center collaborations preempt EFSA immune-function claim rejection and accelerate approval timelines. |
| Direct-to-Consumer Subscription Launch | Online platform replenishment models bypass supermarket slotting fees and capture recurring revenue from German health-conscious households. |
| Drink-Format Convenience Expansion | Portable commuter corridor and health club cooler placement targets underpenetrated on-the-go digestive wellness occasions. |
Research Methodology
Multi-period observation of refrigerated probiotic SKU velocity, cold-chain infrastructure deployment, and regulatory approval timelines anchored the trend analysis, supplemented by interviews with fermentation technicians, dairy cooperative procurement leads, supermarket category buyers, and functional food R&D directors. Secondary validation drew from EU F-Gas Regulation implementation filings, EFSA health claims substantiation dossiers, FSSAI import standard notifications, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across product format, end-user vertical, distribution channel, and flavor profile informed the analytical framework across the analysis window. CAGRs were derived from fitted growth curves applied to historical trajectory patterns and projected regulatory compliance cost absorption rates. Forecast inputs included beta-galactosidase enzyme cost indices, live culture viability maintenance expenditure trends, and strain-specific approval probability assessments.
Underlying measurement precision varies by segment; online store and subscription channel data carry tighter precision than fragmented food service procurement estimates. Forecasts reflect documented assumptions regarding EFSA regulatory timelines, cold-chain equipment upgrade adoption curves, and plant-based substitution elasticity. Strain approval bottlenecks, REACH framework material compliance shifts, and fermentation technician workforce demographics warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Filled Cheese Market
Dairy Products
Cultured Whey Products Market
Dairy Products
Probiotic Cheese Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
Cheese Packaging Market
Dairy Products
Condensed Whey Market
Dairy Products
Middle East Dairy Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Japan Casein Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Dairy Blends Market