
 Reduced Lactose Whey Market | 2026-2036
Reduced Lactose Whey Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Lactose Whey Market Analytics
Buyer concentration among large sports nutrition brands and infant formula manufacturers is realigning procurement volumes toward specialized dairy ingredient suppliers. Fonterra Inc. leverages its New Zealand dairy infrastructure to sustain long-term supply contracts with global nutrition companies. Glanbia plc anchors its competitive stance through deep specialization in whey protein isolate production. Arla Foods competes aggressively on European dairy cooperative scale, while Leprino Foods Company dominates North American mozzarella whey streams that feed reduced lactose processing lines.
Reduced lactose whey refers to dairy-derived protein fractions where enzymatic hydrolysis or membrane filtration has lowered lactose content below standard whey thresholds, typically achieving less than 60% lactose retention while preserving functional protein integrity for human consumption. The primary commercial purpose centers on delivering digestible, high-bioavailability protein to lactose-sensitive populations across sports nutrition, clinical nutrition, and early-life feeding applications. Whey protein isolate commands the deepest margin pools due to its superior protein concentration and minimal residual lactose, while sports nutrition represents the fastest-expanding application segment as fitness-oriented consumers reject bloating associated with conventional whey concentrates. Delactosed whey maintains steady volume in processed food manufacturing where cost-sensitive formulations require functional dairy solids without full protein isolation.
The FDA enforces dairy allergen labeling through FALCPA and monitors nutritional content claims under FSMA, directly shaping how reduced lactose whey products enter US commerce and what health assertions manufacturers may communicate. EFSA in Europe evaluates novel food applications and protein health claims, creating divergent approval pathways that segment market access between regulatory jurisdictions. Stakeholders must monitor evolving lactose threshold definitions across national food codes, as shifting classification standards will determine which products qualify for reduced lactose designation and where formulation investments yield compliant market entry.
Market Dynamics
Enzymatic hydrolysis and membrane filtration technologies are compressing production costs for reduced lactose whey while FDA labeling mandates force manufacturers toward transparent lactose content declarations. Sports nutrition procurement teams now demand certified low-lactose protein streams at scale, rewiring supplier relationships across the dairy ingredient value chain.
Growth Catalysts
- FALCPA allergen disclosure rules:FDA enforcement of clear dairy allergen labeling pushes brands toward reduced lactose whey to simplify compliance and reduce liability exposure in US commerce.
- Sports nutrition formulation:Lactose-intolerant athletes reject conventional whey concentrates, creating procurement pull for hydrolyzed protein fractions that eliminate digestive discomfort during high-intensity training.
- Membrane filtration advances:Nanofiltration and ultrafiltration systems now achieve sub-60% lactose retention at commercial scale, unlocking cost-efficient production of whey protein isolate grades.
Market Restraints
- Fresh whey supply concentration:Mozzarella and cheddar production clusters in Wisconsin and California control raw material flows, creating geographic chokepoints for North American processors.
- Enzyme cost volatility:Lactase enzyme prices fluctuate with microbial fermentation substrate markets, squeezing margins on hydrolysis-dependent product lines.
- Plant protein substitution:Pea and rice protein isolates achieve comparable amino acid profiles at lower price points in mass-market sports nutrition applications.
Strategic Opportunities
- Clinical nutrition expansion:Hospital and long-term care facilities in Germany adopt reduced lactose whey for post-surgical protein delivery, opening institutional procurement channels beyond retail.
- EFSA novel food pathways:European protein health claim approvals create regulatory tailwinds for whey isolate positioning in medical foods and specialized infant nutrition.
- Direct-to-consumer channels:Subscription protein brands bypass traditional distribution, capturing margin and consumer data through proprietary e-commerce platforms.
Industry Challenges
- Clean-in-place validation:Dairy processors face extended downtime for lactose cross-contamination verification, compressing effective production hours on multi-product lines.
- ISO 22000 certification timelines:Food safety management system audits for reduced lactose facilities average 14-18 months, delaying market entry for new manufacturing investments.
- Skilled membrane technician scarcity:Operating nanofiltration skids requires specialized training that outpaces vocational program output in major dairy-producing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Lactose Whey Market |
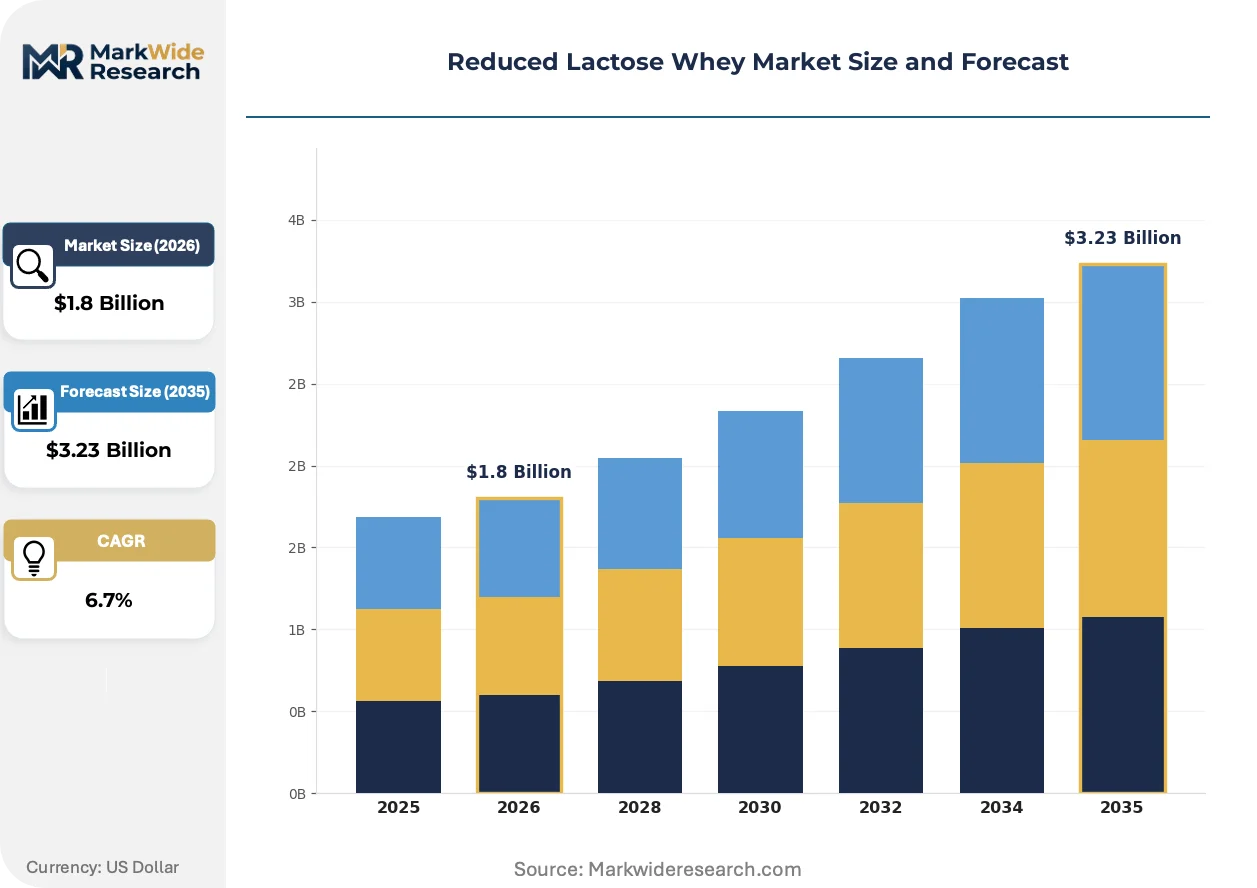
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Theoretical Whey, Delactosed Whey, Whey Protein Isolate, Whey Protein Concentrate Application: Food & Beverages, Sports Nutrition, Infant Formula, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Fitness Enthusiasts, Health-Conscious Consumers, Parents, Older Adults |
| Companies Covered | Fonterra Inc., Glanbia plc, Arla Foods, Land O'Lakes Inc., Agropur Inc., Leprino Foods Company, Hilmar Cheese Company Inc., FrieslandCampina, Carbery Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Lactose Whey Market Evolving Landscape
Continuous processing systems and single-use filtration technologies are displacing batch manufacturing in reduced lactose whey production. Clean-label positioning now extends to processing transparency, with brands marketing enzymatic versus mechanical lactose reduction methods.
Membrane filtration cascades combining ultrafiltration with diafiltration steps are decentralizing production economics for whey protein isolate. Mid-scale dairy processors in the Netherlands and Denmark adopt these systems to bypass tolling arrangements with large ingredient houses. The technology compresses capital requirements for 90%+ protein concentration, fragmenting supply concentration among cooperative and private-label producers.
EFSA's evolving framework for protein digestibility claims is reshaping how European manufacturers communicate reduced lactose whey benefits. Brands must now substantiate amino acid bioavailability through clinical studies rather than relying on compositional data alone. Sports nutrition products targeting German and French markets face the steepest compliance burdens, driving reformulation toward isolate grades with documented PDCAAS scores.
Subscription replenishment models are capturing endurance athletes and CrossFit practitioners who prioritize digestive comfort in protein sourcing. Direct brands bypass retail slotting fees and capture lifetime value through personalized flavor and texture profiles. This channel shift concentrates in US metropolitan markets where fitness culture and e-commerce penetration overlap most densely.
Reduced Lactose Whey Market Segmentation
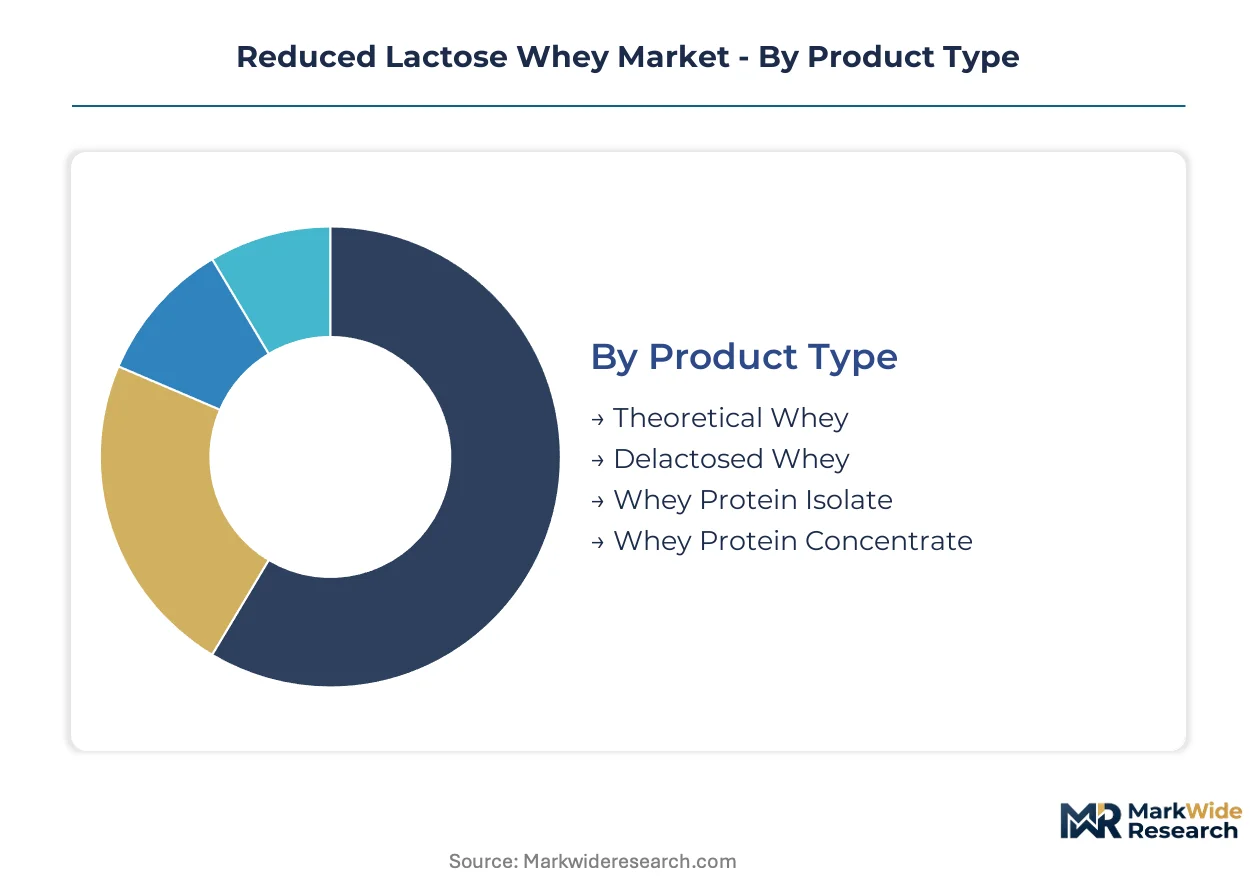
Reduced lactose whey serves distinct performance requirements across protein concentration grades and consumer tolerance thresholds. Segmentation reveals where enzymatic hydrolysis investments yield premium returns versus commodity positioning.
Product Type:
Standalone protein isolates command formulation autonomy, while concentrates and modified wheys embed into multi-ingredient systems.
- Whey Protein Isolate:Achieves 90%+ protein concentration with residual lactose below 1% through ion exchange or crossflow microfiltration. Sports nutrition brands in the United States specify this grade for lactose-intolerant athlete segments unwilling to compromise on amino acid density.
- Whey Protein Concentrate:Retains 25-89% protein with moderate lactose reduction, delivering cost-efficient functionality for bars and ready-to-drink applications. Processed food manufacturers in Wisconsin and California procurement networks favor this tier for margin-sensitive formulations.
- Delactosed Whey:Lactose content reduced to 60% or below of standard whey solids through enzymatic treatment, serving as a functional dairy ingredient in bakery and confectionery applications where complete protein isolation is unnecessary.
- Theoretical Whey:Conceptual category encompassing experimental fractionation methods not yet scaled commercially, including emerging chromatographic separation techniques under evaluation at European dairy research institutes.
Whey protein concentrate leads volumes today; whey protein isolate is gaining share fastest.
Application:
Cost tier separation distinguishes premium clinical positioning from mass-market functional food integration.
- Sports Nutrition:Protein powders, ready-to-drink beverages, and recovery formulations targeting lactose-intolerant athletes. CrossFit practitioners and endurance runners in US metropolitan markets drive procurement specifications for sub-2% lactose thresholds.
- Infant Formula:Specialized nutrition for lactose-sensitive neonates requiring hydrolyzed protein fractions with documented digestibility scores. German hospital procurement channels increasingly specify reduced lactose whey for post-surgical pediatric feeding protocols.
- Food & Beverages:Functional dairy solids in processed foods, beverages, and bakery applications where partial lactose reduction meets labeling requirements without full isolate cost burdens.
- Dietary Supplements:Capsule and tablet formats targeting older adults with declining lactase production, positioned alongside digestive enzyme co-formulations in health food retail channels.
Sports nutrition leads volumes today; infant formula is gaining share fastest.
Distribution Channel:
Customer type fragmentation separates subscription-driven direct relationships from retail intermediation.
- Online Retail:Direct-to-consumer platforms capturing endurance athletes through personalized flavor profiles and replenishment algorithms. Subscription models bypass traditional distributor markups in US fitness-dense metropolitan markets.
- Health Food Stores:Specialty retail channels where educated consumers evaluate enzymatic versus mechanical lactose reduction claims. Staff consultation drives premium isolate conversions in German and French urban centers.
- Supermarkets:Mass-market placement for concentrate-grade products in conventional grocery, competing with plant protein alternatives on shelf price positioning.
- Specialty Stores:Sports-specific retailers and clinical nutrition suppliers serving institutional procurement for hospital and long-term care facilities.
Supermarkets lead volumes today; online retail is gaining share fastest.
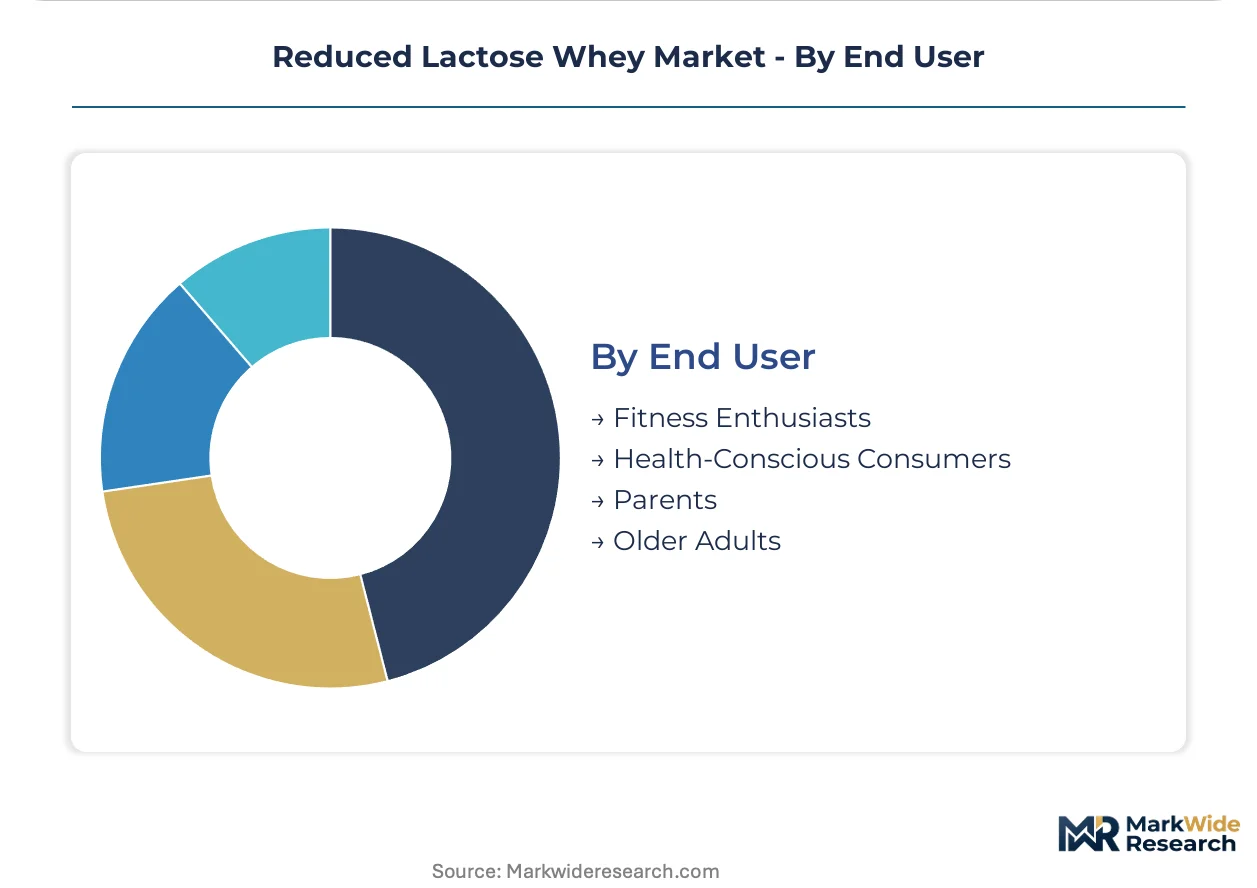
End User:
Maturity differentiation separates established fitness segments from emerging demographic expansions.
- Fitness Enthusiasts:High-frequency protein consumers prioritizing digestive comfort during intensive training cycles. Lactose intolerance self-diagnosis drives premium isolate specification in CrossFit and triathlon communities.
- Health-Conscious Consumers:Broad wellness-oriented purchasers evaluating clean-label positioning and processing transparency claims in reduced lactose whey selection.
- Parents:Infant formula decision-makers seeking hypoallergenic dairy protein options for lactose-sensitive children, influenced by pediatrician recommendations and EFSA novel food approvals.
- Older Adults:Aging populations with acquired lactase deficiency requiring high-bioavailability protein for sarcopenia prevention, increasingly targeted through clinical nutrition channels in German healthcare systems.
Fitness enthusiasts lead volumes today; older adults are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Germany in reduced lactose whey innovation, while New Zealand's dairy infrastructure supplies Asian markets with specialized protein fractions. Regulatory divergence between FDA and EFSA frameworks creates distinct compliance pathways that reshape regional investment priorities.
United States
CrossFit practitioners and endurance athletes in metropolitan markets drive isolate-grade procurement specifications. FDA enforcement of FALCPA allergen disclosure rules pushes brands toward transparent lactose content labeling. Wisconsin and California cheese production clusters control fresh whey flows that feed reduced lactose processing lines.
Germany
Hospital procurement channels increasingly specify reduced lactose whey for post-surgical pediatric and geriatric feeding protocols. EFSA novel food approval pathways create regulatory tailwinds for whey isolate positioning in medical foods. Bavarian dairy cooperatives expand membrane filtration capacity to serve institutional nutrition contracts.
New Zealand
Fonterra leverages national dairy infrastructure to sustain long-term supply contracts with global sports nutrition companies. The country's food safety regulator maintains stringent dairy export standards that align with major import market requirements. Canterbury Plains processing facilities concentrate whey protein isolate production for Asia-Pacific distribution.
Netherlands
Mid-scale dairy processors adopt continuous membrane filtration systems to bypass tolling arrangements with large ingredient houses. REACH chemical safety regulations influence enzyme sourcing for lactose hydrolysis operations. FrieslandCampina's cooperative structure anchors innovation in dairy protein fractionation technologies.
Denmark
Arla Foods competes aggressively on European dairy cooperative scale across reduced lactose whey product lines. Danish veterinary and food administration standards enforce strict residue monitoring for enzymatic processing aids. Jutland processing facilities specialize in clean-label positioning for enzymatic versus mechanical lactose reduction methods.
Reduced Lactose Whey Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Cooperative structures dominate European supply while investor-owned corporations control North American capacity. Strategic archetypes include dairy cooperative giants, specialized whey protein houses, and integrated cheese processors with captive whey streams. Competitive moves concentrate on membrane filtration technology licensing and backward integration into fresh whey supply.
Among New Zealand and Irish dairy cooperatives, Fonterra Inc. and Glanbia plc occupy positions that exemplify scale-driven export orientation. Arla Foods represents the European cooperative archetype with integrated processing across multiple protein grades. These three entities anchor competitive dynamics through divergent ownership structures that shape investment horizons and market access strategies.
| Leading Market Players |
|---|
| Fonterra Inc. |
| Glanbia plc |
| Arla Foods |
| Land O'Lakes Inc. |
| Agropur Inc. |
| Leprino Foods Company |
| Hilmar Cheese Company Inc. |
| FrieslandCampina |
| Carbery Group |
| Others |
Value Network & Pricing Analysis
Lactase enzyme costs cascade through reduced lactose whey production tiers, with substrate price volatility in microbial fermentation markets compressing margins on hydrolysis-dependent isolates while membrane filtration advances reset price floors for concentrate grades.
Pricing Analysis
Capacity additions in the Netherlands and Denmark are reshaping price floors for whey protein isolate grades as mid-scale processors bypass tolling arrangements with large ingredient houses. Three-tier pricing structure across premium isolate, standard concentrate, and economy delactosed levels stratifies by protein concentration and residual lactose thresholds. Pricing pressure stems from plant protein substitution in mass-market sports nutrition, where pea and rice isolates achieve comparable amino acid profiles at lower price points. Mass-market sports nutrition buyers exhibit highest price sensitivity, while clinical nutrition procurement teams in German hospital systems prioritize documented digestibility scores over unit cost.
Supply Chain Analysis
ISO 22000 certification timelines averaging 14-18 months gate market entry for new manufacturing investments, compressing effective production hours on multi-product lines. Fresh whey supply concentrates in Wisconsin, California, and New Zealand, with mozzarella and cheddar production clusters controlling raw material flows. Processing depends on lactase enzymes, membrane filtration skids, and ion exchange resins. Single-source vulnerability runs through skilled membrane technician scarcity, as specialized training outpaces vocational program output in major dairy-producing regions. Distribution runs through cooperative structures in Europe and investor-owned corporations in North America, with direct-to-consumer channels fragmenting traditional retail intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reduced lactose whey market functions as a regulatory compounder, with FDA's updated FALCPA enforcement and EFSA novel food approval pathways simultaneously expanding addressable demand and compliance investment requirements.
For Market Incumbents: Deepen backward integration into fresh whey supply through captive mozzarella and cheddar production streams, securing geographic chokepoints in Wisconsin and California against emerging membrane filtration competitors. Invest in continuous processing systems to compress enzymatic hydrolysis costs and defend margin position against plant protein substitution threats in mass-market sports nutrition. For New Entrants and Emerging Players: Subscription protein brands represent the most penetrable channel, with direct-to-consumer platforms capturing endurance athletes and CrossFit practitioners who prioritize digestive comfort over retail shelf presence. Target German hospital procurement channels for clinical nutrition contracts, where EFSA novel food approvals create regulatory tailwinds for whey isolate positioning in medical foods and post-surgical feeding protocols. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale membrane filtration specialists because fragmented cooperative structures in Europe and private-label producers in North America lack capital depth for continuous processing system adoption. Watch EFSA protein digestibility claim substantiation requirements as the inflection indicator, with clinical study investments separating acquirable targets from stranded asset risks.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Mid-scale processors in the Netherlands bypass tolling arrangements through nanofiltration cascade adoption. |
| Backward Integration into Fresh Whey Supply | Mozzarella production clusters in Wisconsin secure raw material flows for reduced lactose processing lines. |
| Direct-to-Consumer Channel Expansion | Subscription brands capture lifetime value through personalized flavor profiles in US metropolitan fitness markets. |
| Clinical Nutrition Partnership Development | German hospital procurement channels specify reduced lactose whey for post-surgical protein delivery protocols. |
| EFSA Novel Food Approval Investment | European manufacturers substantiate amino acid bioavailability through clinical studies for medical food positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy processing executives, sports nutrition procurement managers, membrane filtration equipment specialists, and clinical nutrition formulary directors with secondary validation against FDA enforcement records, EFSA novel food registers, USDA dairy production statistics, and cooperative financial disclosures. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
The forecast window anchored to historical reference periods across protein concentration grades, application segments, and distribution channel evolution. Segmentation dimensions modeled include product type tier, end-use application, customer archetype, and regional regulatory cluster. CAGRs derived from installed base growth rates, technology substitution curves, and procurement pattern shifts. Industry-specific inputs encompassed lactase enzyme cost trajectories and membrane filtration capacity expansion timelines.
Revisions become necessary when regulatory threshold definitions shift across national food codes, enzyme substrate markets experience sustained volatility, or plant protein amino acid profiles achieve cost parity with whey isolates. Deviation in FDA or EFSA lactose classification standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Blue Cheese Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Clotted Cream Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Organic Milk Powder Market
Dairy Products
Cream Powder Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Lactose and Derivative Market
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Colombia Dairy Market
Dairy Products
Paneer Market
Dairy Products
Cheese Shreds Market