
 Milk Protein Hydrolysate Market | 2026-2036
Milk Protein Hydrolysate Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Protein Hydrolysate Market Analysis
Single-source whey procurement is shifting toward multi-source enzymatic supply contracts across European and Oceania dairy processors. Fonterra Co-operative Group anchors its position through backward integration into grass-fed milk pools across New Zealand. Glanbia PLC differentiates via R&D intensity in fractionation technology at its Irish innovation campus. Arla Foods Ingredients dominates specialized casein hydrolysate output for medical nutrition channels.
Milk protein hydrolysates comprise dairy proteins enzymatically cleaved into peptides and free amino acids, typically achieving molecular weights below 10 kDa for enhanced bioavailability and reduced allergenicity. Manufacturers deploy controlled enzymatic hydrolysis followed by membrane filtration to achieve specific peptide profiles for clinical and performance applications. Whey hydrolysates lead the product type landscape due to faster gastric emptying rates prized by sports nutrition formulators. Casein hydrolysates command premium positioning in infant formula segments where hypoallergenic claims require extensive clinical validation. Functional foods represent the fastest-growing application channel as CPG brands embed protein fortification into mainstream beverage and snack formats.
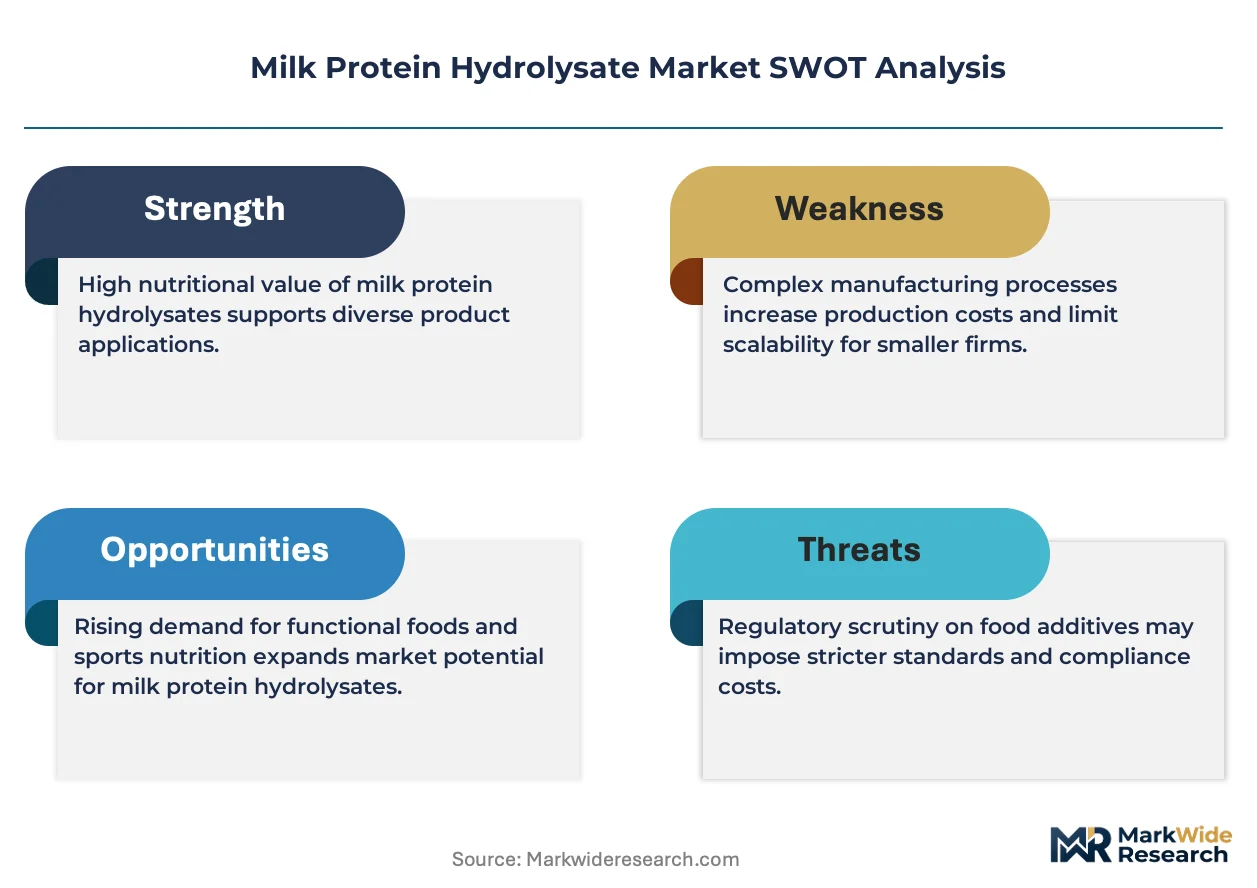
EFSA novel food evaluations and FDA GRAS notifications shape hydrolysate approval pathways for infant and clinical nutrition claims. REACH compliance for enzymatic processing aids and EU MDR requirements for medical-grade enteral formulations tighten manufacturing documentation standards. Stakeholders must monitor peptide characterization methodologies as regulatory bodies tighten substantiation requirements for bioactive health claims.
Market Dynamics
Enzymatic fractionation technology is compressing production timelines for peptide-specific hydrolysates, while EFSA novel food evaluations and FDA GRAS pathways tighten substantiation requirements for clinical and infant nutrition claims.
Growth Catalysts
- Precision fermentation scale-up:Bioreactor capacity expansion in German dairy clusters is reducing enzymatic processing costs for hypoallergenic infant formula ingredients.
- EFSA novel food frameworks:Streamlined evaluation pathways for bioactive peptide claims are accelerating clinical nutrition product launches across European markets.
- Sports nutrition formulation:Rapid amino acid delivery requirements from endurance and strength athletes are pulling whey hydrolysate demand toward higher peptide specificity.
Market Restraints
- Grass-fed milk pool concentration:Fonterra's backward integration into New Zealand pasture-based supply constrains independent processor access to premium raw material streams.
- Clinical validation timelines:EFSA health claim substantiation requires 12-18 month peptide characterization studies that delay product commercialization.
- Plant protein substitution:Fermented pea and fungal protein isolates are capturing clean-label positioning in sports nutrition segments.
Strategic Opportunities
- Medical nutrition penetration:Enteral formula channels in German hospital systems present underdeveloped casein hydrolysate volume.
- Membrane filtration convergence:Integration of nanofiltration with electrodialysis is enabling custom peptide molecular weight cutoffs for targeted bioactivity.
- Direct-to-practitioner distribution:Sports dietitian and clinical nutritionist channels bypass traditional ingredient broker networks.
Industry Challenges
- Enzymologist talent scarcity:Specialized protein biochemists command premium compensation in European precision fermentation hubs.
- EU MDR documentation:Medical-grade enteral formulation certification requires extensive peptide batch tracking and stability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Protein Hydrolysate Market |
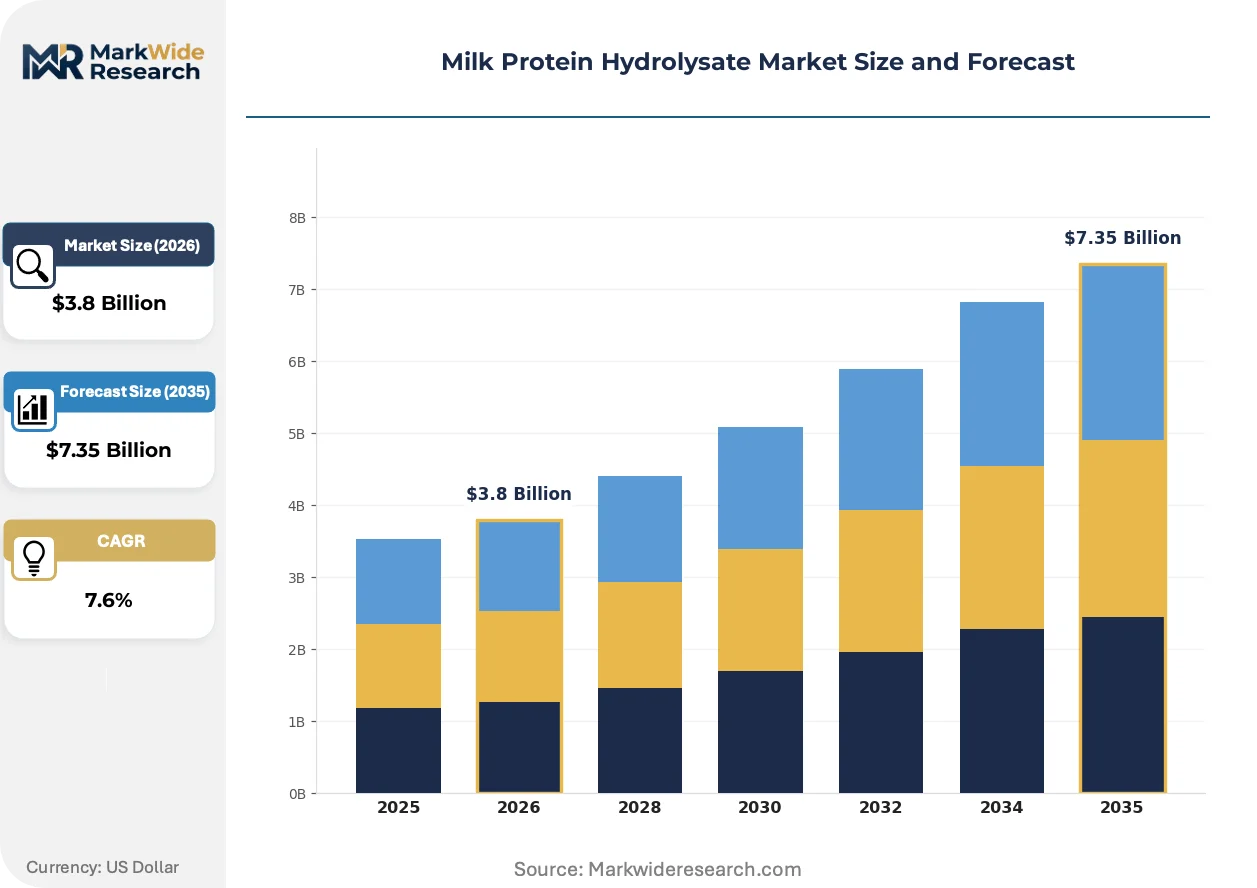
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Hydrolysates, Casein Hydrolysates, Gelatin Hydrolysates, Others Application: Sports Nutrition, Clinical Nutrition, Infant Formula, Functional Foods End User: Food & Beverage, Pharmaceuticals, Dietary Supplements, Cosmetics Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Fonterra Co-operative Group, Glanbia PLC, Arla Foods Ingredients, Danone Nutricia, Cargill Incorporated, Royal FrieslandCampina N.V., Archer Daniels Midland Company, Koninklijke DSM N.V., Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Protein Hydrolysate Market Emerging Trajectories
Continuous processing systems and peptide characterization analytics are compressing development cycles, while regulatory substantiation requirements and procurement centralization reshape competitive positioning across value chain tiers.
Membrane cascade filtration is decentralizing hydrolysate production economics by enabling smaller-batch, peptide-specific output without dedicated industrial-scale infrastructure. Mid-sized European dairy processors are adopting skid-mounted systems to serve regional clinical nutrition formulators. This technology is compressing minimum efficient scale thresholds and fragmenting supply concentration.
REACH compliance for enzymatic processing aids is tightening manufacturing documentation standards across European hydrolysate facilities. Industrial consequence includes mandatory peptide residue testing and supply chain chemical inventory audits. Infant formula manufacturers in Germany and Ireland are consolidating supplier qualification protocols to preempt regulatory friction.
Buyer consortium procurement is consolidating ingredient sourcing decisions among multinational sports nutrition brands. Traditional distributor networks face disintermediation as direct supply contracts with fractionation specialists capture volume commitments. This pattern concentrates most visibly in North American and German markets where brand concentration exceeds processor fragmentation.
Milk Protein Hydrolysate Market Segmentation
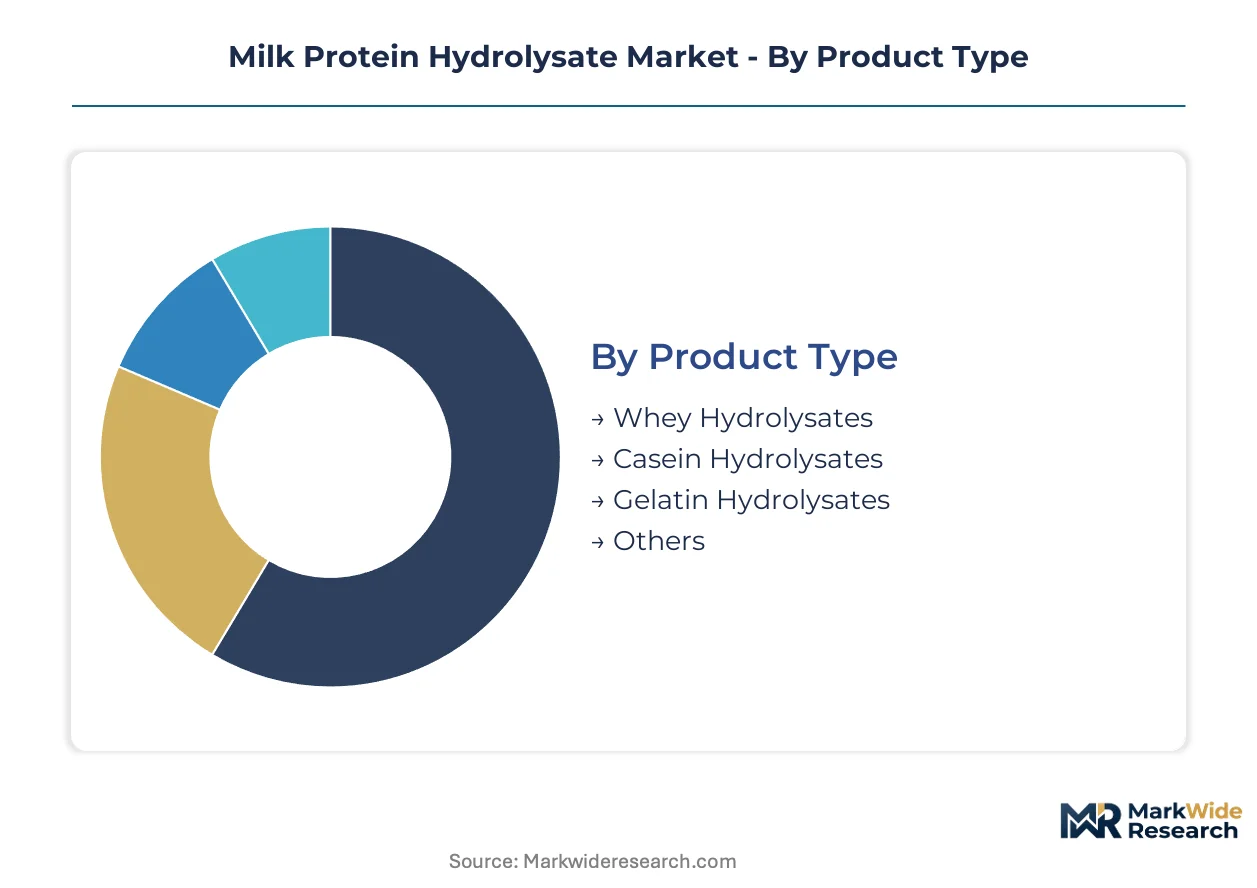
Peptide molecular weight profiles and enzymatic processing specifications determine formulation suitability across clinical, performance, and infant nutrition channels. Manufacturers configure hydrolysis degree and fractionation methods to match end-use bioavailability requirements and regulatory claim substantiation pathways.
Product Type:
Enzymatic cleavage specificity and resulting peptide chain length distributions define functional performance across gastric emptying rates and allergenicity reduction targets.
- Whey Hydrolysates:Rapid gastric emptying kinetics deliver amino acids to skeletal muscle within 30-60 minutes post-ingestion. Sports nutrition formulators in Germany and Ireland prioritize degree-of-hydrolysis specifications above 15% for post-workout recovery applications. EFSA novel food evaluations for bioactive peptide claims concentrate validation investment here.
- Casein Hydrolysates:Sustained amino acid release profiles suit overnight recovery and medical enteral feeding protocols. Arla Foods Ingredients anchors specialized output for hypoallergenic infant formula segments requiring extensive clinical validation. FDA GRAS notifications for medical nutrition claims demand batch-to-batch peptide consistency documentation.
- Gelatin Hydrolysates:Collagen-derived peptides target joint and connective tissue positioning in dietary supplement channels.
- Others:Emerging milk protein fractions including lactoferrin hydrolysates occupy niche antimicrobial positioning.
Mature deployment sits with Whey Hydrolysates. Newer deployment is concentrated in Casein Hydrolysates for medical nutrition penetration.
Application:
End-use channels diverge sharply on regulatory substantiation burden and peptide characterization requirements.
- Sports Nutrition:Rapid amino acid delivery specifications pull demand toward higher degree-of-hydrolysis formulations. Endurance and strength athlete segments in North America and Germany drive peptide specificity requirements above standard commodity grades.
- Clinical Nutrition:Enteral formula applications require EU MDR medical-grade certification with extensive stability protocols. German hospital systems present underdeveloped casein hydrolysate volume for post-surgical and geriatric feeding.
- Infant Formula:Hypoallergenic claims mandate 12-18 month EFSA peptide characterization studies that constrain supplier qualification pools.
- Functional Foods:Mainstream beverage and snack fortification applications are expanding most quickly as CPG brands embed protein positioning into clean-label formats.
Volume concentration sits with Sports Nutrition. Margin expansion is concentrated in Clinical Nutrition.
End User:
Procurement sophistication and peptide documentation requirements stratify across buyer sophistication tiers.
- Food & Beverage:Clean-label fortification demands drive whey hydrolysate incorporation into mainstream dairy alternatives and ready-to-drink formats.
- Pharmaceuticals:Medical-grade enteral formulations require REACH-compliant enzymatic processing aid documentation and peptide batch tracking protocols.
- Dietary Supplements:Direct-to-practitioner distribution channels bypass traditional broker networks for sports dietitian and clinical nutritionist prescribing.
- Cosmetics:Bioactive peptide positioning in topical applications occupies emerging demand with limited regulatory precedent.
Documentation burden sits with Pharmaceuticals. Channel fragmentation is concentrated in Dietary Supplements.
Distribution Channel:
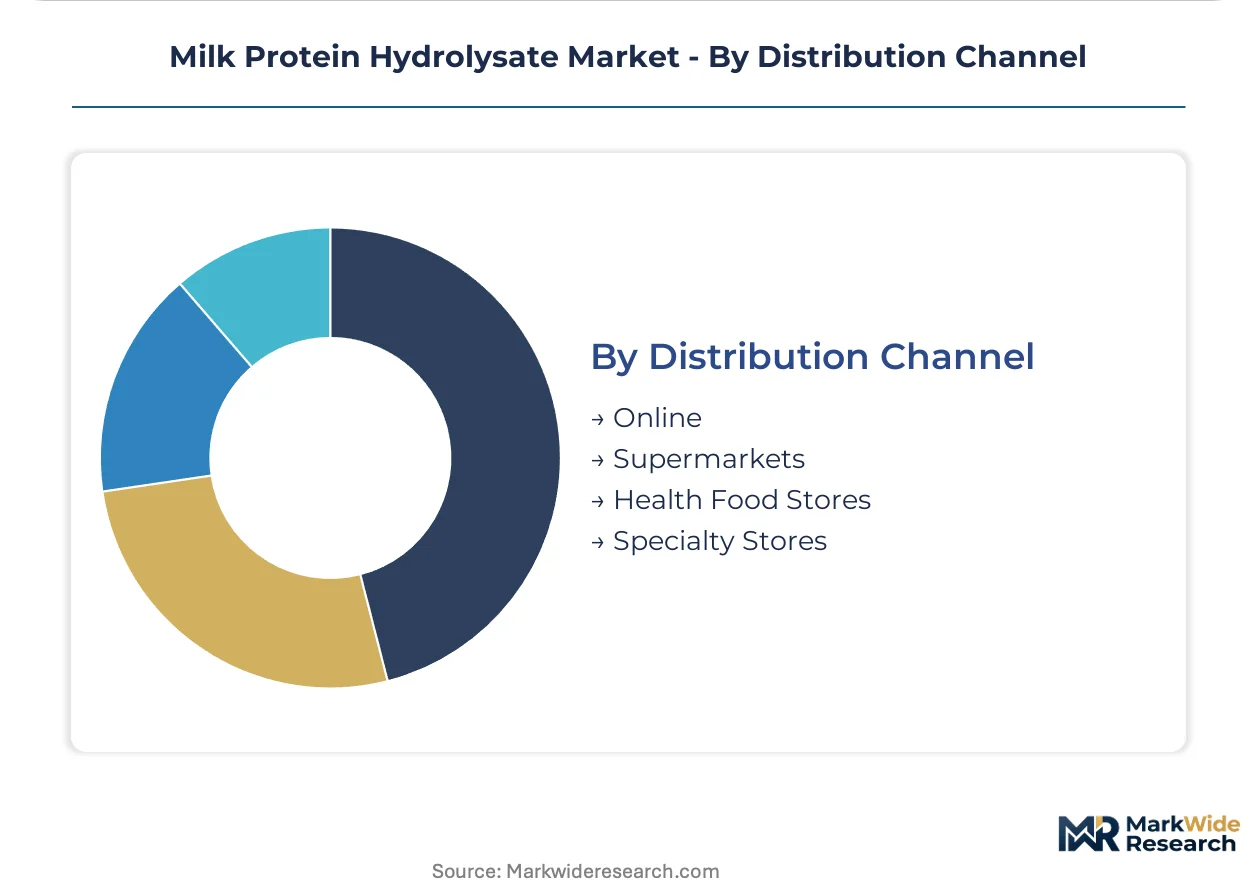
Buyer consolidation and disintermediation pressures reshape route-to-market economics across brand scale tiers.
- Online:Direct supply contracts between fractionation specialists and multinational sports nutrition brands concentrate volume commitments away from distributor networks.
- Supermarkets:Mass-market functional food placement requires economy-grade hydrolysate specifications with compressed peptide characterization.
- Health Food Stores:Regional clinical nutrition formulators in Europe source mid-tier whey hydrolysates through qualified supplier programs.
- Specialty Stores:Premium positioning channels capture medical nutrition and infant formula segments with full documentation packages.
Volume consolidation sits with Online. Relationship dependency is concentrated in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where precision fermentation clusters and infant formula manufacturers anchor supply chain investment. Clinical nutrition procurement in German hospital systems drives specialized casein hydrolysate volumes. Sports nutrition formulation in North America and Ireland pulls whey hydrolysate demand toward higher peptide specificity.
Germany
Precision fermentation scale-up in Bavarian dairy clusters reduces enzymatic processing costs for hypoallergenic infant formula ingredients. EFSA novel food evaluations streamline bioactive peptide claim pathways across European markets. Frankfurt-Rhine-Main anchors medical nutrition distribution networks serving enteral formula channels.
United States
FDA GRAS notifications for whey hydrolysate sports nutrition claims accelerate product commercialization timelines. Buyer consortium procurement consolidates ingredient sourcing decisions among multinational brands. Chicago and Wisconsin dairy processing corridors concentrate fractionation capacity for rapid amino acid delivery formulations.
New Zealand
Grass-fed milk pool backward integration constrains independent processor access to premium raw material streams. Fonterra's pasture-based supply chain dominance shapes regional procurement economics. Canterbury region anchors whey hydrolysate export capacity serving Asia-Pacific sports nutrition markets.
Ireland
R&D intensity in fractionation technology drives peptide-specific hydrolysate development for clinical applications. Glanbia's innovation campus in Kilkenny exemplifies enzymatic processing advancement. Cork and Waterford dairy processors specialize in degree-of-hydrolysis specifications above 15% for post-workout recovery segments.
Netherlands
Membrane cascade filtration adoption decentralizes production economics for mid-sized regional clinical nutrition formulators. REACH compliance for enzymatic processing aids tightens manufacturing documentation standards. Wageningen food technology cluster advances nanofiltration integration with electrodialysis for custom peptide molecular weight cutoffs.
Milk Protein Hydrolysate Market Vendor Landscape
Capacity expansion dominates the current landscape as bioreactor investments compress production timelines for peptide-specific hydrolysates. The vendor base stratifies across integrated dairy cooperatives, specialized fractionation technology firms, and multinational ingredient distributors. Three archetypes define competitive positioning: backward-integrated milk pool controllers, R&D-intensive peptide specialists, and medical-grade certification holders. M&A activity and direct-to-brand supply contracting disintermediate traditional distributor networks.
Within the integrated cooperative tier, Fonterra Co-operative Group and Royal FrieslandCampina N.V. represent milk pool control archetypes securing pasture-based raw material streams. Glanbia PLC exemplifies the R&D-intensive specialist model through Irish innovation campus investment. Arla Foods Ingredients occupies the medical-grade certification position serving hypoallergenic infant formula segments requiring extensive clinical validation.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Glanbia PLC |
| Arla Foods Ingredients |
| Danone Nutricia |
| Cargill Incorporated |
| Royal FrieslandCampina N.V. |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Kerry Group plc |
| Others |
Supply Flow & Price Mechanics
Specialized enzymologist concentration in Bavarian precision fermentation clusters widens pricing-tier spreads between medical-grade and commodity hydrolysate grades. Labor-cost differentials between German bioprocessing hubs and Irish dairy corridors feed into three-tier pricing stratification across premium clinical nutrition, standard sports nutrition, and economy functional food segments.
Pricing Analysis
Service-bundling separates peptide characterization documentation from base ingredient supply, with EFSA validation packages commanding substantial premiums over unbundled commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with EU MDR medical-grade documentation and FDA GRAS notification status as primary differentiation drivers. Pricing pressure stems from plant protein substitution in sports nutrition, compressing mid-tier whey hydrolysate margins. Mass-market functional food buyers exhibit highest price sensitivity, while infant formula manufacturers prioritize batch consistency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with New Zealand grass-fed milk pools controlled by backward-integrated cooperatives, constraining independent processor access to premium raw material streams. Supply concentration spans Germany, Ireland, and New Zealand as dominant production geographies. Enzymatic processing aids, membrane filtration equipment, and clinical validation services constitute critical input dependencies. Tariff exposure on whey protein concentrate imports threatens cost structures for European fractionators. Distribution runs through direct supply contracts between fractionation specialists and multinational sports nutrition brands, bypassing traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH compliance documentation burdens and clinical validation timelines force sub-scale processors toward exit or acquisition. EFSA novel food substantiation requirements disproportionately burden smaller entrants lacking dedicated regulatory affairs infrastructure.
For Market Incumbents: Acquire specialized enzymology talent pools in Bavarian and Wageningen biotech clusters to secure biocatalysis capabilities. Consolidate membrane filtration capacity in Ireland and the Netherlands to capture mid-sized clinical nutrition formulator volumes. Plant protein substitution in sports nutrition segments threatens whey hydrolysate positioning, demanding peptide specificity investments above 15% degree-of-hydrolysis thresholds to defend differentiation.
For New Entrants and Emerging Players: Begin with medical nutrition penetration in German hospital enteral feeding channels, where casein hydrolysate volumes remain underdeveloped relative to sports nutrition saturation. Target direct-to-practitioner distribution through sports dietitian and clinical nutritionist networks, bypassing consolidated buyer consortium procurement that disadvantages unproven suppliers. White-space availability concentrates in peptide-specific customization for post-surgical recovery formulations.
For Investors and Strategic Acquirers: Re-rating potential sits with R&D-intensive fractionation specialists given membrane cascade filtration adoption decentralizing production economics. Long-term viability favors processors with captive enzymatic processing aid qualification under REACH frameworks, securing regulatory moats across the analysis window. Acquisition target archetype: mid-sized European dairy processors with skid-mounted nanofiltration systems and existing clinical nutrition customer relationships. Signal to watch: EFSA health claim substantiation backlog clearance rates as inflection indicator for bioactive peptide product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grass-Fed Milk Pools | Fonterra's pasture-based supply chain control secures premium raw material access for hypoallergenic infant formula grades. |
| Membrane Cascade Filtration Adoption | Skid-mounted systems at Dutch and Irish processors enable smaller-batch peptide-specific output without industrial-scale infrastructure. |
| EFSA Novel Food Validation Investment | Twelve-to-eighteen month peptide characterization studies open bioactive health claim pathways for clinical nutrition commercialization. |
| Direct-to-Practitioner Distribution Buildout | Sports dietitian and clinical nutritionist channels bypass disintermediated broker networks concentrated in North American and German markets. |
| Precision Fermentation Capacity Expansion | Bavarian bioreactor scale-up reduces enzymatic processing costs for hypoallergenic infant formula ingredient production. |
Methodological Framework
Document review covered EFSA novel food evaluation databases, FDA GRAS notification filings, and REACH enzymatic processing aid compliance records, complemented by interviews with dairy processing plant managers, infant formula regulatory affairs leads, sports nutrition brand procurement directors, and membrane filtration technology specialists. Secondary validation drew from customs trade data on whey protein concentrate flows, SEC filings of publicly traded ingredient companies, and European dairy cooperative sustainability reports. Bottom-up volume estimates from fractionation capacity installations were triangulated against top-down demand projections from end-use segment consumption patterns.
Cross-referencing historical capacity expansion timelines against expert panel input on precision fermentation adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include hydrolysate product type, application channel, end-user industry, and peptide molecular weight cutoff specifications. CAGRs were derived from slope analysis of installed bioreactor capacity versus peptide-specific output growth rates. Industry-specific forecast inputs incorporated EFSA evaluation pipeline clearance velocities and German hospital enteral nutrition procurement data.
Regulatory timeline delays, plant protein substitution acceleration, and enzymologist talent pool constraints are the dominant revision risks to modeled outputs. Forecasts reflect assumptions on EFSA streamlining efficiency, REACH enforcement consistency, and sports nutrition brand consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
GCC UHT Milk Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Global Fresh Milk Market
Dairy Products
South America Dairy Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Paneer Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Flavoured Milk Market