
 Low Calorie Whipped Cream Market | 2026-2036
Low Calorie Whipped Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Whipped Cream Market Analytics
Food service buyer concentration is pivoting as bakery chains and quick-service dessert concepts consolidate procurement volumes, while specialty cafés fragment demand through smaller-batch purchasing. Conagra Brands leverages its retail distribution infrastructure to sustain shelf presence across mass-market channels. Arla Foods anchors its position through dairy-based formulation expertise and European sourcing networks. Lactalis competes by extending its fresh dairy capabilities into reduced-calorie aerosol and tub formats.
Low calorie whipped cream denotes an aerated emulsion containing reduced fat or sugar content, typically stabilized with vegetable gums or proteins and whipped to overrun levels of 80–120% to achieve characteristic texture and volume. The product serves commercial food service and retail consumers seeking dessert toppings with controlled caloric density. Dairy-based formulations occupy the dominant share of current production volumes, while non-dairy alternatives are capturing accelerated growth as plant-based ingredient technology matures. Aerosol can packaging dominates household convenience channels, though food service operators increasingly specify bulk tub formats for operational efficiency in restaurant and café environments.
FDA nutrition labeling standards and WHO sugar reduction frameworks shape formulation requirements and disclosure obligations for manufacturers operating in North American markets. The European Food Safety Authority and national regulators under EU food law enforce additive restrictions and clean-label expectations that influence export product specifications. Stakeholders must monitor evolving protein stabilization technologies and shifting food service procurement consolidation to align capacity investments with the next wave of category demand.
Market Dynamics
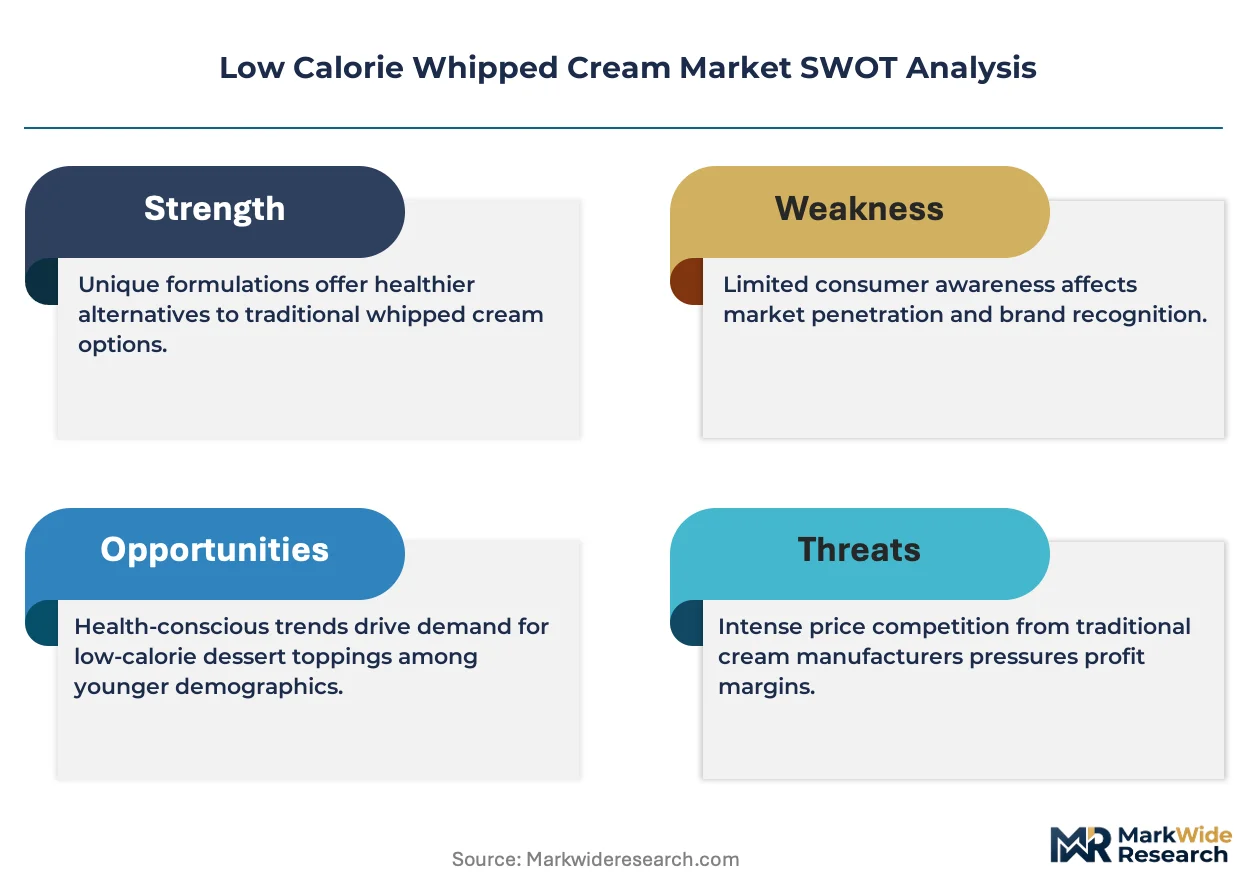
Bakery chains and specialty cafés are consolidating procurement volumes while demanding cleaner-label formulations, creating simultaneous pressure on manufacturers to scale production and reformulate recipes. This structural tension between volume concentration and ingredient transparency is reshaping competitive positioning across the category.
Growth Catalysts
- WHO Sugar Reduction Guidelines:Global health frameworks are mandating reduced sugar content in dessert toppings, forcing manufacturers to accelerate clean-label reformulation and opening shelf space for compliant low-calorie alternatives.
- Aerosol Packaging Innovation:Nitrous oxide propellant systems and valve technologies are improving product stability and extending shelf life, driving household adoption through convenience-oriented retail channels.
- Food Service Procurement Consolidation:Quick-service dessert chains are centralizing purchasing decisions, creating volume commitments that justify dedicated production lines for reduced-calorie formulations.
Market Restraints
- Dairy Input Cost Volatility:Butterfat and milk protein prices fluctuate with feed grain markets and climate conditions, compressing margins for dairy-based low-calorie formulations during commodity spikes.
- Clean-Label Technical Limitations:Removing artificial stabilizers while maintaining 80-120% overrun aeration requires expensive protein-hydrocolloid systems that raise unit costs versus conventional formulations.
- Plant-Based Substitution Threat:Coconut cream and oat-based whipped alternatives are capturing health-conscious consumers seeking dairy-free options, fragmenting demand within the reduced-calorie segment itself.
Strategic Opportunities
- European Export Expansion:EFSA clean-label standards and EU additive restrictions are creating premium positioning for US manufacturers with advanced natural stabilization capabilities.
- Bulk Tub Food Service Channel:Restaurant and café operators are specifying larger-format packaging to reduce labor and waste, opening dedicated supply relationships outside retail-centric distribution.
- Protein-Stabilizer Technology Convergence:Pea protein and fava bean protein systems are converging with enzymatic hydrocolloid processing, enabling stable foam structures without synthetic additives.
Industry Challenges
- Reformulation Talent Scarcity:Food scientists with expertise in aerated emulsion physics and natural stabilization chemistry command premium compensation, constraining R&D bandwidth at mid-tier manufacturers.
- Dual Certification Timelines:Securing both FDA nutrition label compliance and third-party clean-label certifications requires 18-24 month validation cycles that delay product launches.
- Legacy Equipment Retrofit Costs:Conventional dairy whipping lines require capital-intensive modifications to handle lower-viscosity reduced-fat formulations without compromising overrun consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Whipped Cream Market |
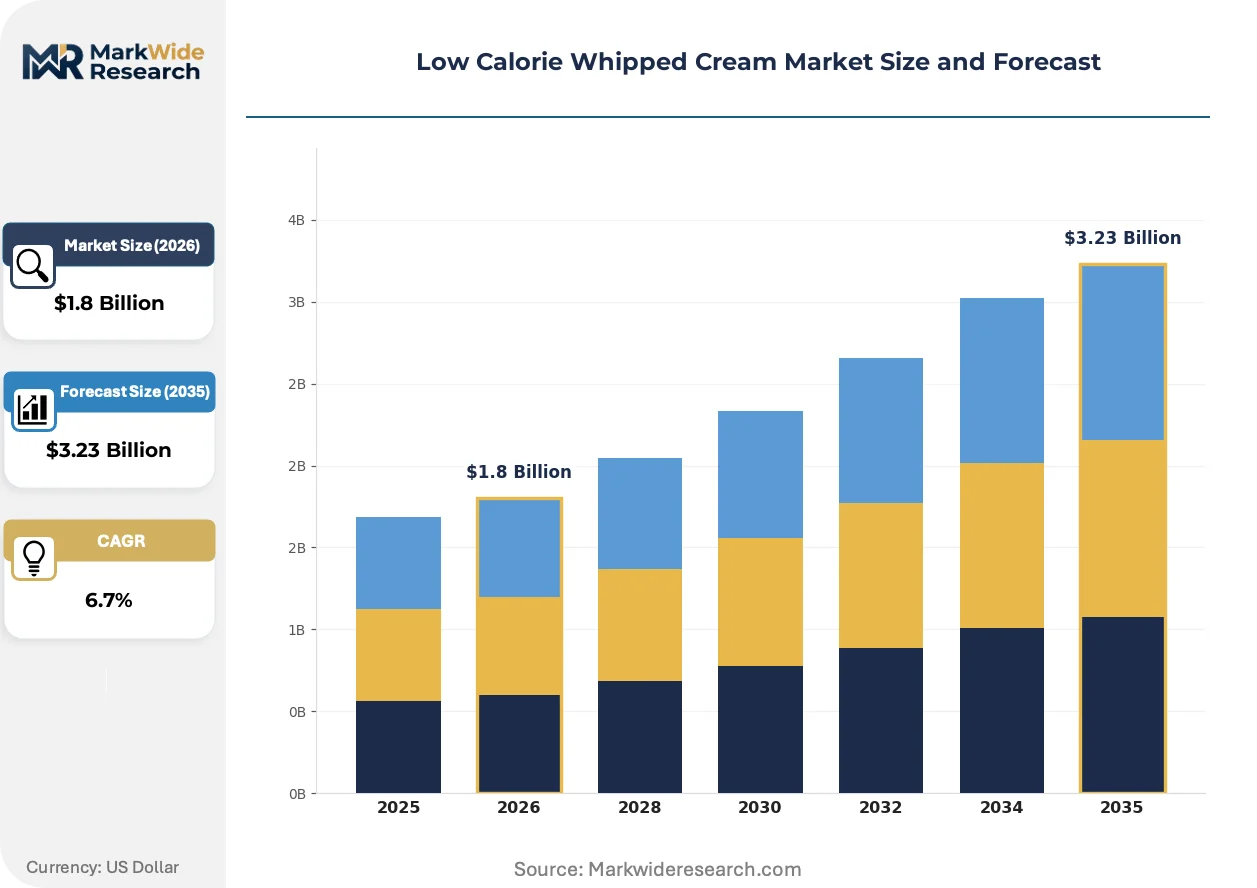
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar-Free, Dairy-Based, Non-Dairy, Flavored Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service End User: Households, Restaurants, Cafés, Bakeries Packaging Type: Aerosol Can, Tub, Carton, Bottle |
| Companies Covered | Conagra Brands, Arla Foods, Lactalis, Hanan Products Co., Cabot Creamery, Rich Products & Solutions Pvt Ltd, GCMMF, Land O'Lakes, FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Whipped Cream Market Evolving Landscape
Protein-hydrocolloid stabilization systems are displacing traditional synthetic additives, while regulatory pressure on sugar disclosure and food service operational efficiency are reshaping formulation priorities and packaging specifications simultaneously.
Enzyme-modified protein stabilization is converging with high-pressure processing to create aerated structures that maintain volume without artificial gums or carrageenan. Specialty cafés in urban clusters are piloting these systems for signature dessert programs. The technology is converging with premium positioning strategies that justify higher price points through ingredient transparency claims.
FDA nutrition labeling standards now mandate added sugar disclosure lines that expose conventional whipped topping formulations, accelerating manufacturer investment in alternative sweetener systems. The industrial consequence is a bifurcation between mass-market products accepting visible sugar content and reformulated lines targeting health-claim eligibility. Food service operators in the United States are responding by splitting menu placements between indulgent and reduced-sugar dessert options.
Direct procurement relationships between bakery chains and co-manufacturers are disintermediating traditional dairy distributors for bulk low-calorie whipped cream. This channel compression is replacing multi-tier distribution with dedicated supply agreements carrying volume commitments and quality audits. The shift is most visible in the United States, where national dessert chains are consolidating regional suppliers into single-source national contracts with reformulation collaboration clauses.
Low Calorie Whipped Cream Market Segmentation
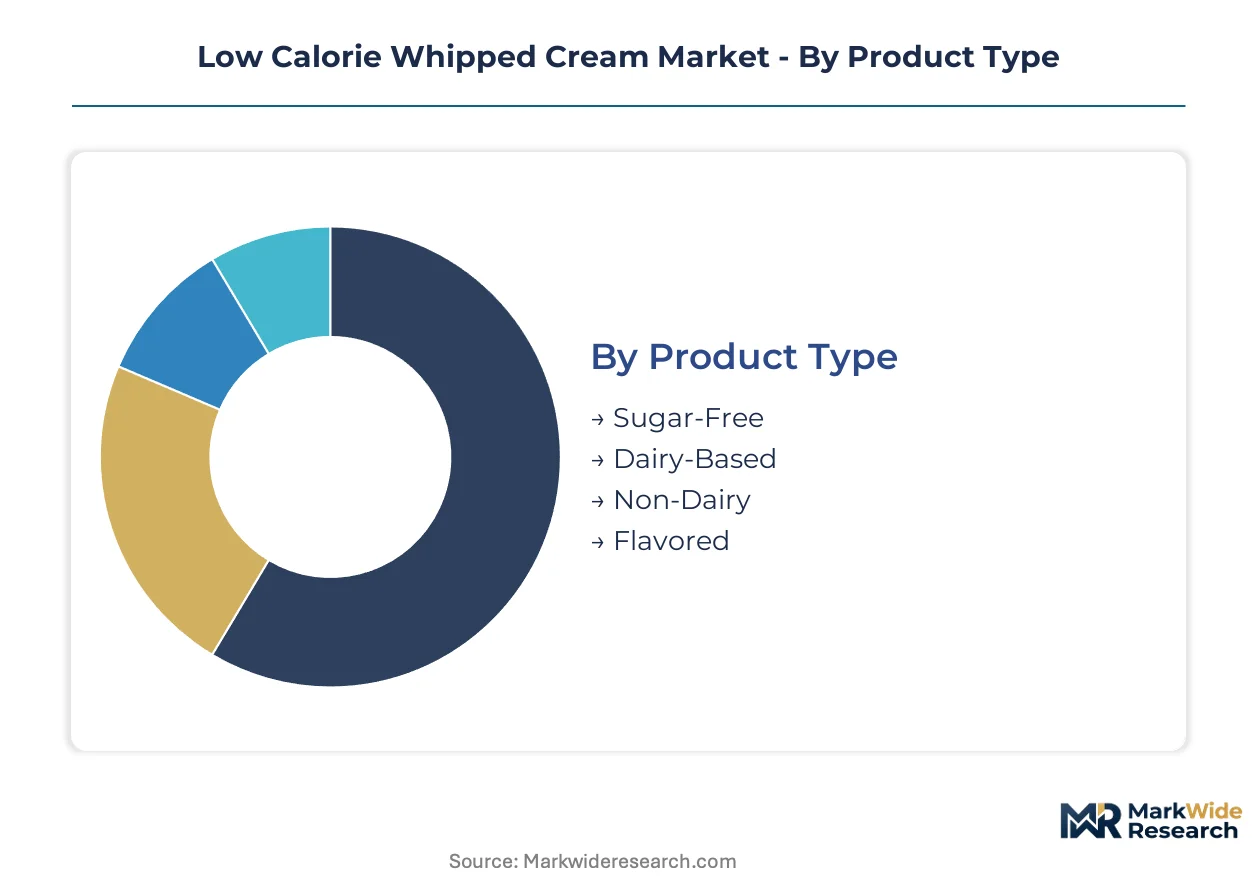
Low calorie whipped cream buyers fragment sharply across preparation settings, procurement scale, and ingredient transparency requirements. Understanding these divides reveals where manufacturers must deploy distinct formulation, packaging, and channel strategies.
Product Type:
Dairy-based formulations anchor current production volumes, while plant-based alternatives and sugar-free lines attract reformulation investment from health-claim seekers.
- Dairy-Based:Reduced-fat milk and cream emulsions stabilized with vegetable gums maintain the dominant share of commercial output. Bakery chains in the United States specify these formulations for premium dessert programs where clean-label dairy credentials support menu positioning.
- Non-Dairy:Coconut cream, oat, and fava bean protein systems are capturing accelerated growth as enzymatic hydrocolloid technology matures. Specialty cafés in urban clusters pilot these for signature offerings targeting dairy-free and vegan consumer segments.
- Sugar-Free:Alternative sweetener systems replace sucrose to meet WHO reduction guidelines and FDA added-sugar disclosure requirements.
- Flavored:Vanilla, chocolate, and seasonal variants extend application breadth for retail dessert kits and food service seasonal menus.
Volume sits with Dairy-Based; growth tilts toward Non-Dairy.
Distribution Channel:
Channel selection determines packaging format, pricing architecture, and relationship depth with downstream buyers.
- Food Service:Direct procurement agreements with bakery chains and quick-service dessert concepts are consolidating volumes and disintermediating traditional dairy distributors. National contracts now carry reformulation collaboration clauses and dedicated quality audit protocols.
- Supermarkets:Mass-market retail placement demands aerosol convenience and competitive unit economics. Shelf space competition intensifies as FDA nutrition labels expose added sugar content in conventional formulations.
- Online Retail:Subscription and direct-to-consumer models serve health-conscious households seeking specialized clean-label or allergen-free variants unavailable in conventional retail.
- Convenience Stores:Impulse-oriented single-serve formats target immediate consumption occasions with limited flavor and formulation range.
Procurement scale concentrates in Food Service; channel expansion is climbing fastest in Online Retail.
End User:
Operational requirements diverge between at-home preparation and professional kitchen environments.
- Restaurants:Full-service operators specify bulk tub formats to reduce labor and waste, prioritizing overrun consistency across dessert plating volumes.
- Cafés:Specialty coffee chains fragment demand through smaller-batch purchasing with emphasis on signature drink differentiation and ingredient transparency claims.
- Bakeries:Production-scale users integrate whipped toppings into finished dessert manufacturing, requiring stable foam structures through baking and freezing cycles.
- Households:Convenience-driven consumers favor aerosol packaging for immediate dessert finishing with minimal preparation time.
Operational complexity peaks with Restaurants; steepest expansion trajectory belongs to Cafés.
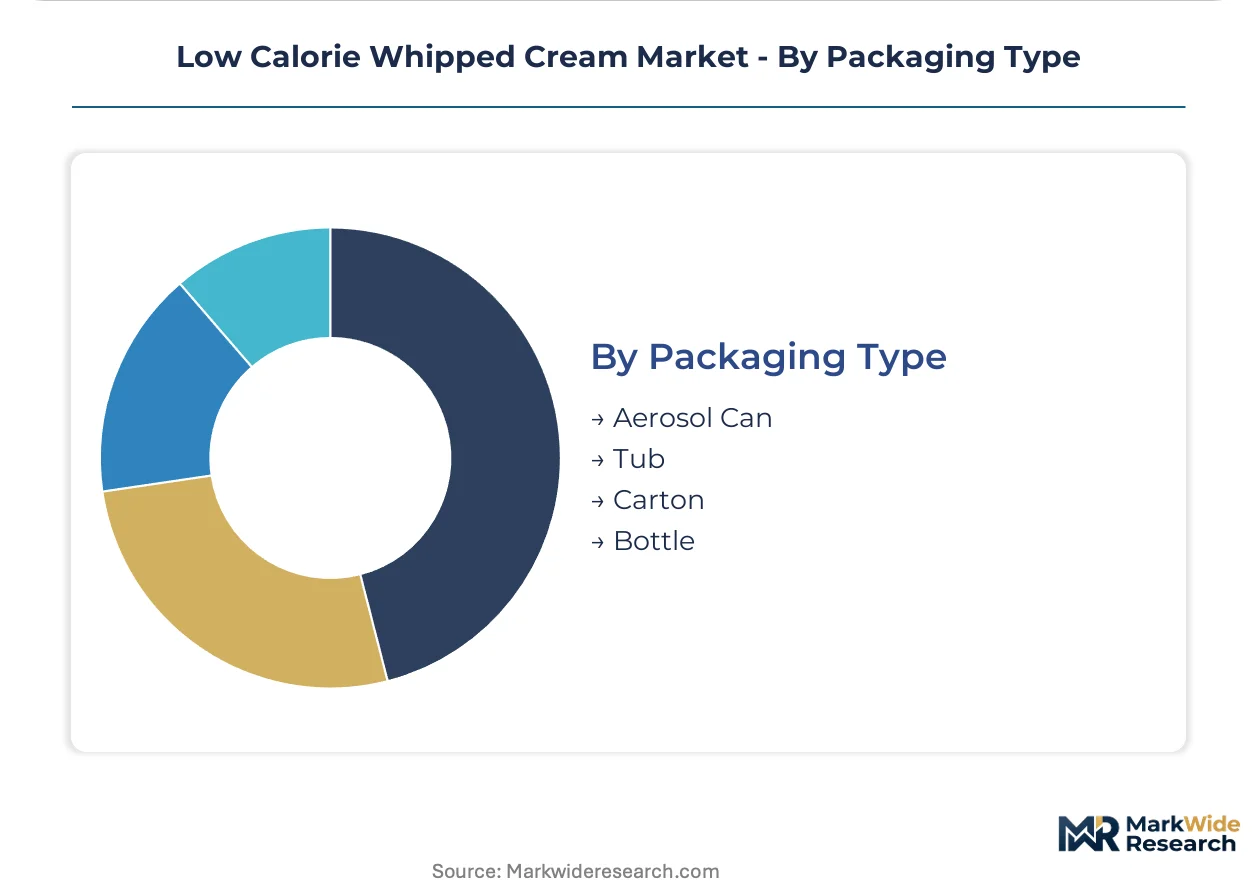
Packaging Type:
Format selection balances shelf stability, dispensing efficiency, and environmental compliance pressures.
- Aerosol Can:Nitrous oxide propellant systems dominate household channels through portion control and extended shelf life. Valve technology improvements are reducing product degradation during storage.
- Tub:Larger-format rigid containers serve food service operators seeking to minimize packaging waste and labor in high-volume dessert assembly.
- Carton:Refrigerated liquid formats appeal to commercial kitchens with in-house whipping equipment and batch flexibility requirements.
- Bottle:Squeeze dispensers target hybrid retail-food service applications where controlled portioning meets portability needs.
Household penetration favors Aerosol Can; food service operational efficiency is driving fastest uptake in Tub.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers and food service procurement consolidation concentrate demand in the United States, while European clean-label standards and Asian dairy market maturation create distinct regional trajectories for low calorie whipped cream expansion.
United States
Bakery chains and quick-service dessert concepts drive procurement volume concentration, with national contracts replacing regional supplier fragmentation. FDA nutrition labeling standards mandating added sugar disclosure lines expose conventional formulations, accelerating manufacturer investment in alternative sweetener systems. Specialty café clusters in New York, Los Angeles, and Chicago pilot enzyme-modified protein stabilization for signature dessert programs.
Germany
EFSA clean-label standards and EU additive restrictions shape formulation requirements for export-oriented manufacturers. The country's dairy processing infrastructure supports advanced natural stabilization capabilities targeting premium positioning. Industrial dairy clusters in Bavaria and North Rhine-Westphalia host co-manufacturing partnerships with US brands seeking European market entry.
United Kingdom
Specialty coffee chains fragment demand through smaller-batch purchasing with emphasis on ingredient transparency claims. UK Food Standards Agency enforcement of post-Brexit labeling divergence creates compliance complexity for multinational suppliers. London's café density and Manchester's bakery manufacturing base anchor regional demand concentration.
France
Traditional dairy heritage intersects with reformulation pressures as ANSM enforces strict additive oversight for aerosol propellant systems. Lactalis extends fresh dairy capabilities into reduced-calorie formats from its Normandy and Brittany production bases. Parisian dessert concepts and Lyon food service distributors specify bulk tub formats for operational efficiency.
Japan
Health-conscious aging demographics and convenience store channel density create distinct packaging preferences. METI guidelines on functional food claims influence reduced-calorie product positioning. Tokyo and Osaka metropolitan clusters demonstrate concentrated adoption of aerosol convenience formats for household dessert finishing.
Low Calorie Whipped Cream Market Competitive Landscape
United States producers anchor one tier through retail distribution infrastructure and food service procurement relationships; European specialists hold another through dairy-based formulation expertise and clean-label certification capabilities. The vendor base separates into three strategic archetypes: diversified consumer packaged goods conglomerates with aerosol manufacturing scale, dairy cooperatives with backward integration into milk protein supply, and regional co-manufacturers serving private-label contracts. Competitive moves concentrate on M&A to secure natural stabilization technology and capacity expansion for bulk tub food service formats.
Within the diversified conglomerate tier, Conagra Brands exemplifies mass-market shelf presence across aerosol convenience channels, while Arla Foods occupies a position anchored through European sourcing networks and dairy-based specialization. Lactalis sits within the fresh dairy extension archetype, representing competitive pressure from integrated milk processing capabilities applied to reduced-calorie aerosol and tub formats.
| Leading Market Players |
|---|
| Conagra Brands |
| Arla Foods |
| Lactalis |
| Hanan Products Co. |
| Cabot Creamery |
| Rich Products & Solutions Pvt Ltd |
| GCMMF |
| Land O'Lakes |
| FrieslandCampina |
| Others |
Value Network & Pricing Analysis
Enzyme-modified protein stabilization systems are compressing unit economics for clean-label formulations while concentrating production capability among manufacturers with advanced R&D infrastructure. This technological transition simultaneously raises reformulation costs and consolidates supply relationships toward co-manufacturers with dedicated aerated emulsion expertise.
Pricing Analysis
Volume commitments from bakery chains and quick-service dessert concepts trade against margin compression from natural stabilization ingredient costs. Three-tier pricing structure across premium clean-label, standard reduced-calorie, and economy conventional formulations separates buyers by certification requirements and overrun consistency specifications. Pricing pressure stems from dairy input cost volatility and the technical expense of protein-hydrocolloid systems. Food service operators demonstrate highest price sensitivity due to operational scale requirements, while specialty cafés absorb premium positioning costs for signature menu differentiation.
Supply Chain Analysis
Clean-label certification and FDA nutrition label compliance requirements gate supplier participation and consolidate procurement toward qualified co-manufacturers. Raw material sourcing concentrates in the United States, Germany, and France, with butterfat and milk protein inputs drawing from regional dairy cooperatives. Nitrous oxide propellant systems and vegetable gum stabilizers create dependencies on specialty chemical suppliers. Single-source vulnerability runs through concentrated aerosol valve and can manufacturing capacity. Distribution runs through direct procurement agreements disintermediating traditional dairy distributors for bulk food service formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around reformulation talent and dual certification timelines prop pricing power for qualified manufacturers, creating a capacity-scarce environment where production capability outpaces demand growth.
For Market Incumbents: Hedge against plant-based substitution threats by securing captive supply of pea protein and fava bean protein through backward integration into ingredient processing. Expand bulk tub production capacity in the United States to capture food service procurement consolidation, while investing in enzymatic hydrocolloid R&D to defend clean-label positioning against emerging natural stabilization specialists. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable entry vector for allergen-free and specialty diet variants underserved by mass retail. Target urban café clusters in New York, Los Angeles, and Chicago with co-manufactured small-batch offerings emphasizing ingredient transparency claims, bypassing established distributor relationships through digital-native brand building and social proof marketing. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified consumer packaged goods conglomerates seeking aerosol manufacturing scale and natural stabilization technology. Long-term viability hinges on five-to-ten year capacity to serve reformulation collaboration clauses in national food service contracts. Monitor FDA enforcement patterns on added sugar disclosure as the critical inflection signal for alternative sweetener system investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Stabilization Technology Acquisition | Protein-hydrocolloid capabilities secure clean-label positioning under EFSA additive restrictions. |
| Bulk Tub Food Service Capacity Expansion | Dedicated production lines capture procurement consolidation from national dessert chains. |
| Direct Procurement Relationship Development | Bypassing distributors enables reformulation collaboration and quality audit integration. |
| Alternative Sweetener System Investment | FDA added sugar disclosure mandates accelerate compliant formulation pipelines. |
| European Export Certification Pathway | EFSA clean-label standards unlock premium positioning in German and French markets. |
Research Methodology
Multi-period observation of reformulation investment cycles, procurement contract structures, and aerosol packaging technology adoption anchored the trend analysis, supplemented by interviews with food service procurement directors, dairy cooperative supply managers, co-manufacturer operations heads, and retail category buyers. Secondary validation drew from FDA nutrition labeling guidance documents, EFSA additive safety assessments, USDA dairy production statistics, and food service distributor trade publications. Bottom-up volume modeling across product type, distribution channel, and end-user segments was triangulated against top-down category value estimates from customs and trade data.
Input-output matrices mapped ingredient cost structures through production economics to end-user pricing across dairy-based, non-dairy, sugar-free, and flavored product categories. Segmentation dimensions included preparation setting, procurement scale, packaging format, and geographic regulatory cluster throughout the forecast period. CAGRs were derived from regression analysis of historical volume trajectories adjusted for structural shifts in food service procurement consolidation and clean-label regulatory enforcement intensity. Forecast inputs incorporated dairy commodity price volatility indices and protein stabilization technology maturation curves.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time co-manufacturer capacity utilization data introduce uncertainty bands around food service channel growth assumptions. Forecasts reflect documented assumptions regarding WHO sugar reduction guideline adoption timelines and FDA enforcement consistency. A model refresh is warranted upon material change in dairy input cost volatility or breakthrough developments in plant-based aeration technology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactic Butter Market
Dairy Products
Japan Dairy Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Flavoured Milk Market
Dairy Products
North America Dairy Market
Dairy Products
Condensed Whey Market
Dairy Products
Cheese Shreds Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Lactose Market
Dairy Products
North America A2 Milk Market
Dairy Products
North America Yogurt Market
Dairy Products
Donkey Milk Market
Dairy Products
Sweet Whey Market
Dairy Products
Recombined Milk Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market