
 United Kingdom Milk Protein Market | 2026-2036
United Kingdom Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Milk Protein Market Analytics
FSA enforcement on protein content verification is pivoting the cost-of-entry calculus for new suppliers. Kerry Group plc leverages its integrated dairy processing network to sustain margin advantages. Arla Foods Group anchors its position through farmer-owned cooperative structure and domestic sourcing control. Glanbia PLC differentiates via specialized whey protein isolate capabilities serving performance nutrition contracts.
Milk protein encompasses whey and casein fractions extracted through membrane filtration, spray drying, and ion-exchange chromatography, yielding concentrates with protein content ranging from 35% to 90% by dry weight for functional food fortification. Whey protein dominates volume flows due to superior amino acid bioavailability and rapid absorption kinetics favored by sports nutrition formulators. Casein protein occupies premium positioning in overnight recovery applications where sustained amino acid release delivers measurable performance outcomes. Infant nutrition represents the fastest-growing application segment as clean-label demands reshape maternal purchasing criteria.
Food Standards Agency protocols, EU-retained REACH chemical safety standards, and Dairy UK quality assurance frameworks collectively enforce compositional integrity and allergen labeling precision across the value chain. Trading Standards officers conduct routine protein content audits at manufacturing sites, creating compliance-driven demand for certified analytical testing services. Stakeholders must monitor divergence between UK-specific labeling requirements and evolving EU nutrition claims legislation to avoid dual-certification cost burdens.
Market Dynamics
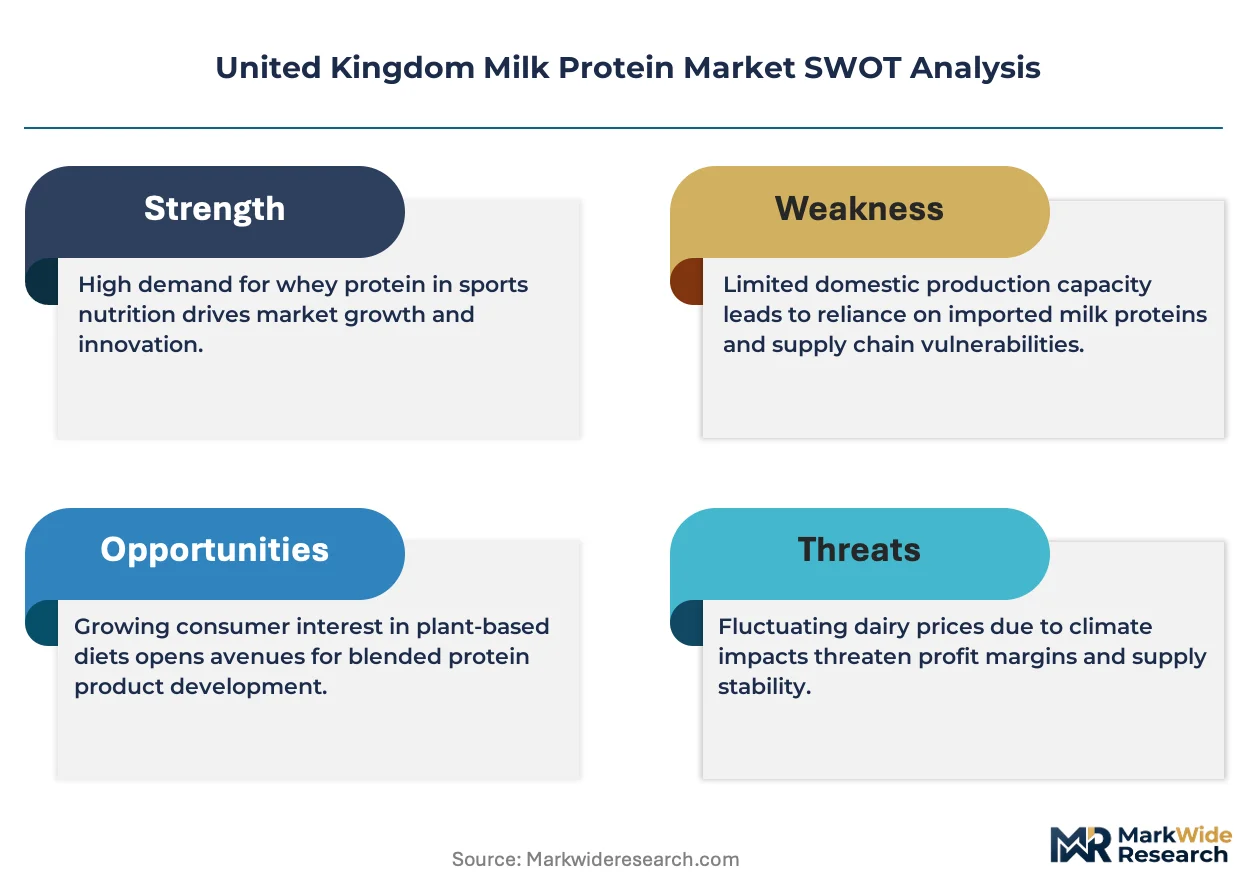
FSA protein content verification mandates are restructuring supplier economics, forcing capital deployment into certified analytical infrastructure and compressing margins for non-compliant processors.
Growth Catalysts
- Sports Nutrition Formulation:Performance nutrition brands are scaling whey protein isolate procurement for amino acid density advantages in recovery products.
- Clean-Label Infant Nutrition:Maternal purchasing criteria are pivoting toward minimally processed casein fractions with documented provenance.
- FSA Novel Food Guidance:Tightened purity benchmarks are creating certified-supplier premiums that reward early compliance investments.
Market Restraints
- Input Cost Volatility:Raw milk price fluctuations at farm-gate level transmit directly to concentrate production economics.
- Supply Concentration Risk:England's M62 corridor processing cluster creates geographic single-point vulnerability for national distribution.
- Substitution Threat:Plant-derived protein isolates from pea and fava bean sources are capturing share in mass-market sports nutrition.
Strategic Opportunities
- Scotland Dairy Belt:Underutilized processing capacity in Aberdeenshire and Ayrshire offers expansion headroom with lower land costs.
- Medical Nutrition:Enteral and clinical nutrition applications remain penetration-light relative to sports and infant segments.
- Membrane Filtration Convergence:Ceramic microfiltration paired with inline spectroscopy enables real-time protein fraction standardization.
Industry Challenges
- Analytical Chemist Shortage:FSA-mandated protein verification protocols require specialized HPLC and Dumas method expertise that outpaces graduate pipeline output.
- Legacy System Integration:ERP upgrades for batch traceability under Dairy UK quality frameworks demand capital outlays that strain mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Milk Protein Market |
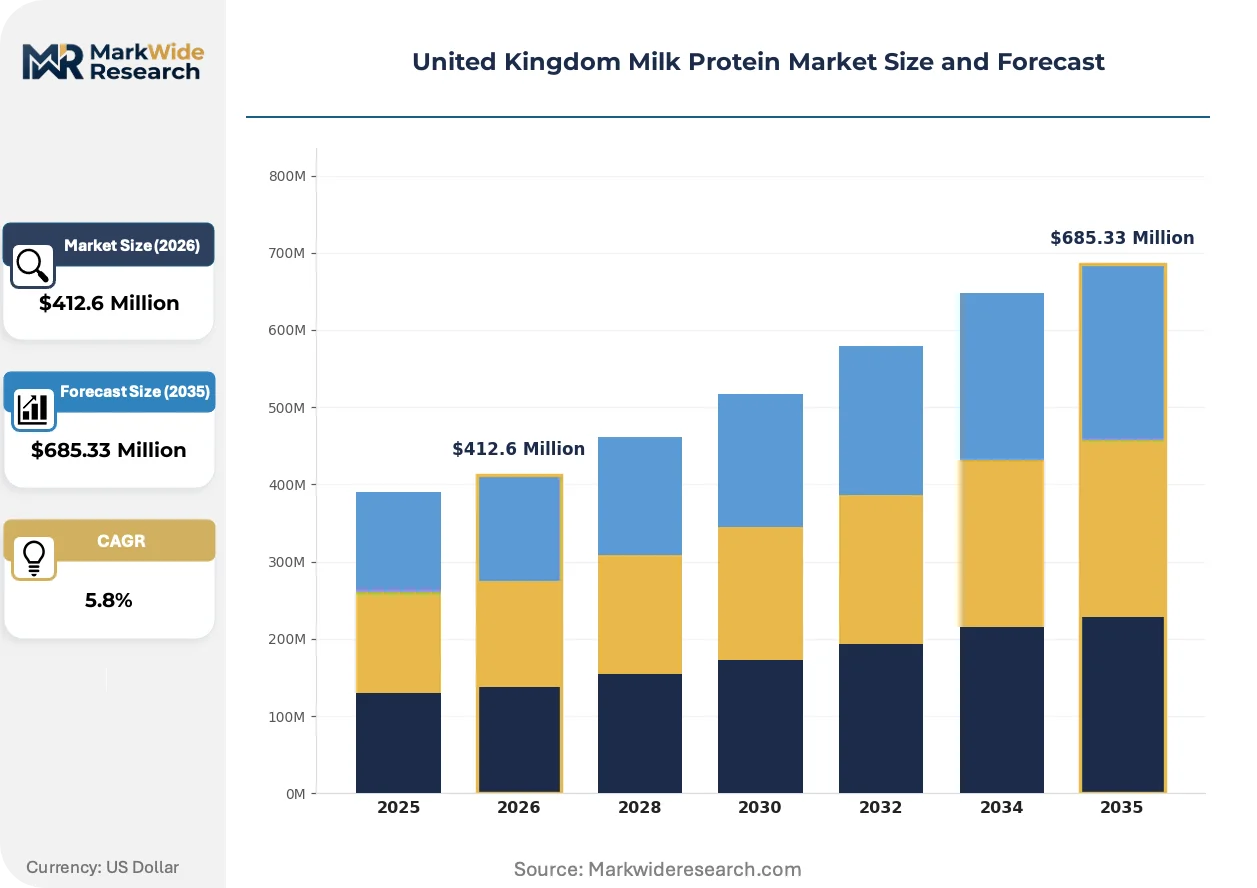
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Milk Protein Isolate Application: Functional Foods, Sports Nutrition, Dietary Supplements, Infant Nutrition End User: Athletes, Fitness Enthusiasts, Dietary-Sensitive Consumers, Children Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops |
| Companies Covered | Kerry Group plc, Royal FrieslandCampina NV, Arla Foods Group, Saputo Inc., Lactalis Group, Fonterra Co-operative Group Limited, Lactoprot Deutschland GmbH, AMCO Proteins, Glanbia PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Milk Protein Market Evolving Landscape
Membrane technology advances and regulatory precision requirements are compressing the gap between commodity whey and specialized isolate production, reshaping capital allocation across the value chain.
Cross-flow ceramic microfiltration is unifying protein fractionation with inline quality control, eliminating offline testing delays. Sports nutrition contract manufacturers are adopting these systems at replacement cycle points. The technology is unifying previously separate concentration and standardization steps into continuous processing lines that reduce energy intensity and labor headcount.
FSA enforcement on allergen labeling precision is mandating DNA-species verification for milk protein concentrates. Trading Standards audit frequency has intensified at manufacturing sites. Infant formula producers are responding with blockchain-enabled batch documentation that satisfies both domestic and export market requirements.
Direct-procurement relationships between protein processors and performance nutrition brands are displacing traditional dairy trader intermediaries. Bulk buyers are negotiating multi-year volume commitments with price collars tied to milk futures. This pattern concentrates most visibly in England's M62 corridor, where co-located processing and formulation facilities enable just-in-time ingredient flows.
United Kingdom Milk Protein Market Segmentation
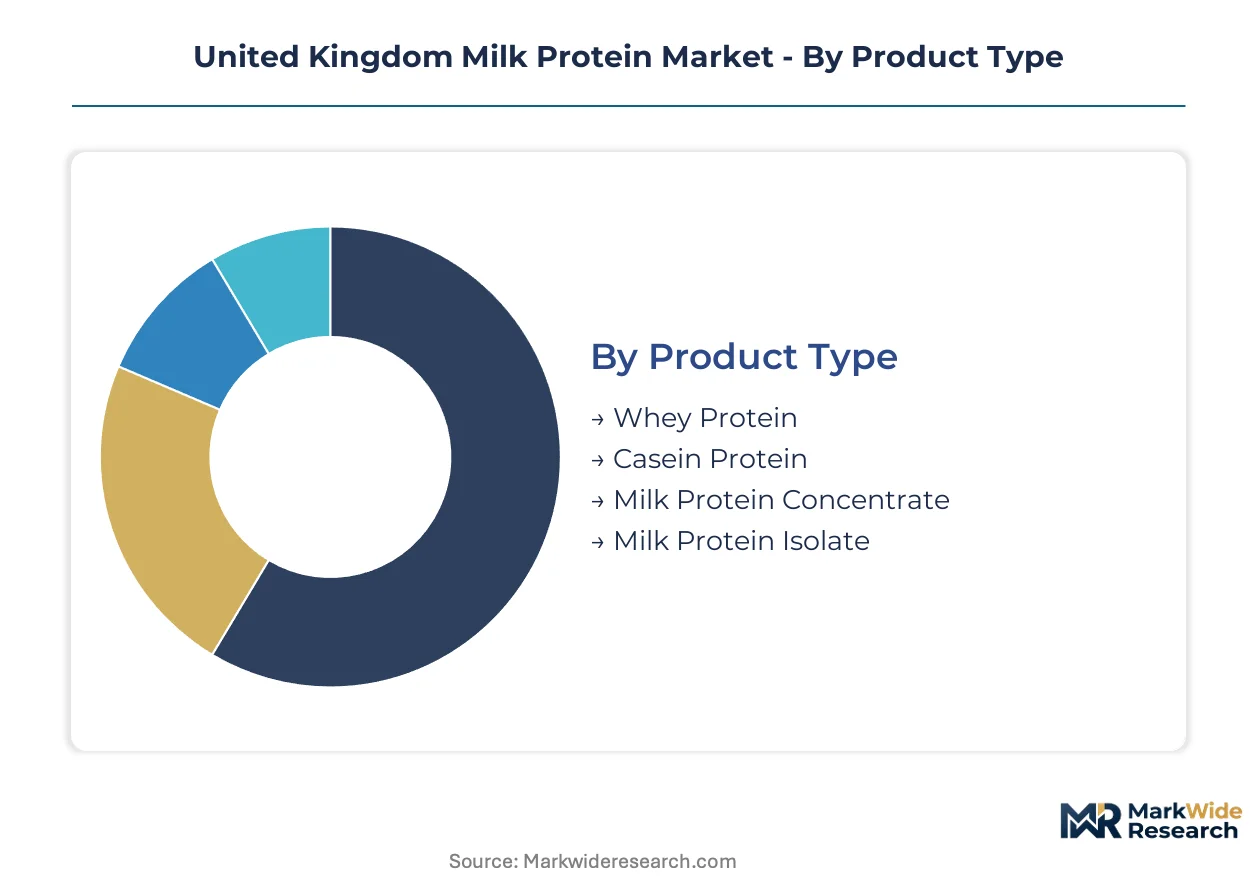
Protein fraction specifications diverge sharply across end-use applications, driving distinct procurement criteria and margin profiles. Sports nutrition brands prioritize amino acid density and rapid absorption kinetics, while infant formula producers demand documented provenance and allergen traceability.
Product Type:
Supply concentration in whey protein processing dominates England's M62 corridor, where membrane filtration infrastructure achieves economies of scale unavailable to casein specialists.
- Whey Protein:Extracted through ultrafiltration and spray drying, whey delivers 80-90% protein concentrates with superior leucine content for muscle protein synthesis. Sports nutrition formulators in Greater Manchester and West Yorkshire drive procurement volumes, prioritizing isolate grades with 90%+ purity for premium positioning.
- Casein Protein:Micellar casein fractions release amino acids over 6-8 hours, supporting overnight recovery applications. Demand concentrates in overnight protein formulations and clinical nutrition, where sustained nitrogen retention delivers measurable outcomes for athletes and medical patients.
- Milk Protein Concentrate:Blended whey-casein ratios of 40:60 to 80:20 serve cost-sensitive fortification applications in bakery and dairy alternatives.
- Milk Protein Isolate:Ultra-pure 90%+ protein fractions command specialty positioning in hypoallergenic infant formulas and medical nutrition protocols.
Today's leader: Whey Protein. Tomorrow's challenger: Milk Protein Isolate.
Application:
Cost tier stratification separates commodity fortification from premium performance positioning, with certification requirements widening the gap between mass-market and clinical-grade procurement.
- Sports Nutrition:Protein powders, ready-to-drink shakes, and recovery bars absorb the majority of whey isolate volumes. Formulators in Birmingham and Leeds negotiate direct-procurement contracts with processors, bypassing traditional dairy traders to secure volume commitments with price collars.
- Infant Nutrition:Clean-label maternal purchasing criteria are reshaping casein fraction demand toward minimally processed micellar sources with blockchain-documented batch provenance.
- Functional Foods:Bakery, dairy, and beverage fortification utilizes milk protein concentrates for emulsification and water-binding properties.
- Dietary Supplements:Capsule and tablet formats target aging populations and clinical dietary management with standardized protein dosing.
Infant Nutrition climbs fastest on clean-label premiums. Sports Nutrition retains volume dominance.
End User:
Customer type fragmentation demands parallel certification tracks, with FSA allergen protocols imposing distinct compliance burdens on pediatric versus adult-targeted production lines.
- Athletes:Competitive and recreational athletes prioritize leucine-rich whey isolates with third-party banned-substance certification. Procurement concentrates through specialty retailers and direct-to-brand subscriptions.
- Fitness Enthusiasts:Recreational gym users drive mass-market whey concentrate volumes through supermarket and online channels.
- Dietary-Sensitive Consumers:Lactose-intolerant and allergen-avoidant buyers seek hydrolyzed or ultra-filtered fractions with reduced immunoreactivity markers.
- Children:Pediatric nutrition demands exceed adult standards for heavy metal screening and microbiological purity, with FSA enforcement intensifying at manufacturing sites.
Athletes anchor premium tier pricing. Children represent the steepest regulatory escalation pathway.
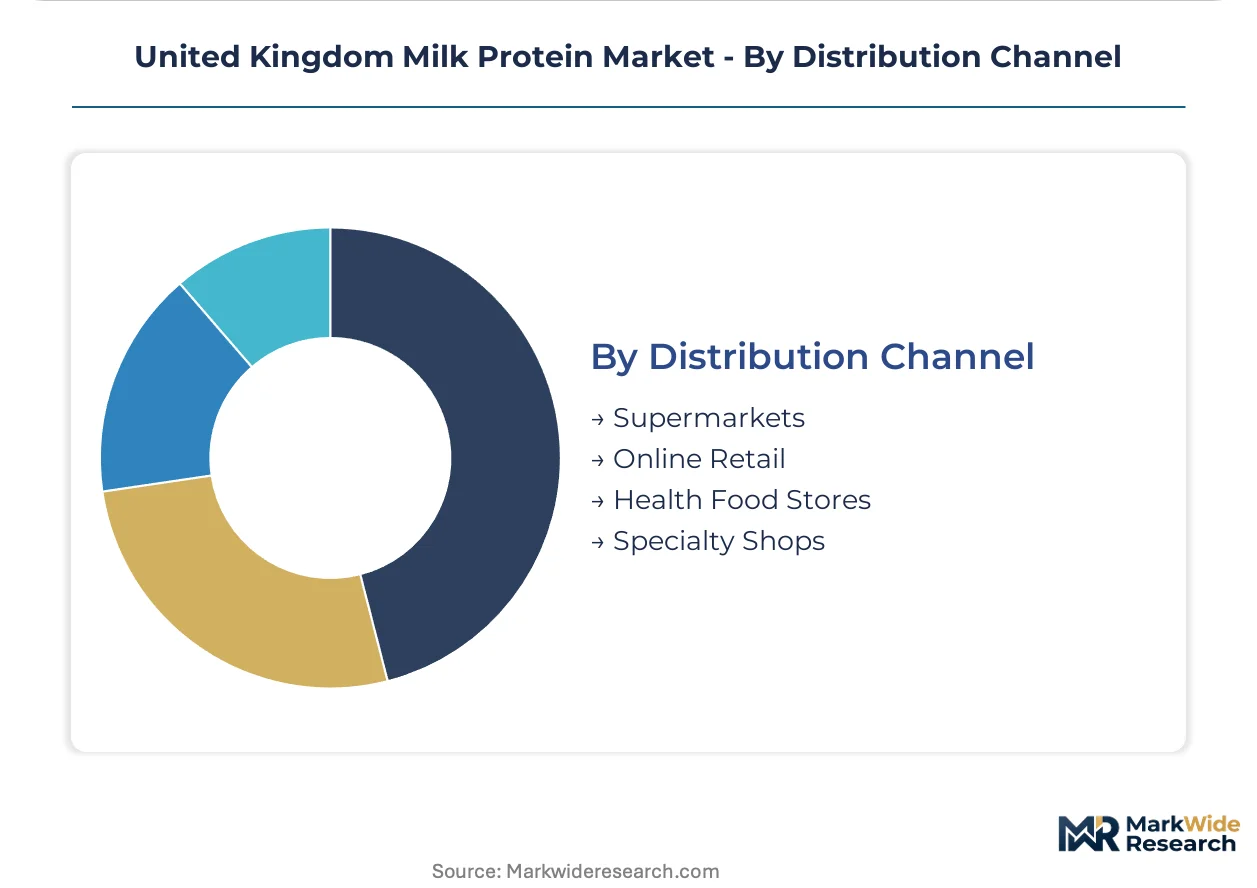
Distribution Channel:
Volume flows concentrate through supermarket and online retail, with health food stores retaining influence in early-adopter segments despite share erosion.
- Online Retail:Direct-to-consumer subscriptions and marketplace platforms capture growing share of repeat purchases, enabled by batch-traceability interfaces that satisfy FSA documentation requirements.
- Supermarkets:Tesco, Sainsbury's, and Asda shelf placement determines mass-market brand visibility, with private-label protein products expanding in Scotland and Northern England.
- Health Food Stores:Holland & Barrett and independent specialists retain influence in organic and grass-fed protein positioning.
- Specialty Shops:Gym-affiliated retail and sports performance boutiques serve immediate-convenience purchasing for training-day consumption.
Supermarkets hold current volume. Online Retail gains share fastest on subscription retention economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and dairy processing engineers cluster along England's M62 corridor, creating a talent density that anchors national protein fractionation capacity. This workforce concentration shapes where membrane filtration infrastructure scales and where FSA compliance expertise concentrates.
England's M62 Corridor
Sports nutrition formulators in Greater Manchester and West Yorkshire drive whey isolate procurement volumes. The Food Standards Agency conducts routine protein content audits at manufacturing sites across Leeds and Bradford. Co-located processing and formulation facilities enable just-in-time ingredient flows between membrane filtration plants and contract manufacturers.
Scotland
Aberdeenshire and Ayrshire offer underutilized dairy processing capacity with lower land costs than English counterparts. Dairy UK quality assurance frameworks extend enforcement to Scottish manufacturing sites with equivalent stringency. Edinburgh and Glasgow anchor distribution networks serving Highland and Island dairy producers seeking protein fractionation partnerships.
Wales
Grass-fed dairy herds in Pembrokeshire and Ceredigion supply milk with distinct fatty acid profiles valued by clean-label infant nutrition brands. Welsh Government food innovation grants support processor upgrades for FSA novel food compliance. The Cambrian Mountains dairy belt remains penetration-light for specialized isolate production despite abundant raw milk supply.
Northern Ireland
Cross-border dairy flows with the Republic of Ireland create dual-jurisdiction compliance complexity for protein processors in County Antrim and County Down. Trading Standards officers coordinate with Irish regulators on allergen labeling verification. Belfast and Londonderry serve as consolidation points for milk protein concentrates entering Great Britain distribution.
London and the Southeast
Headquarters functions for major dairy processors concentrate in the capital, with strategic procurement teams negotiating multi-year volume commitments. The Greater London Authority's food sustainability frameworks influence corporate sourcing criteria. Heathrow and Dover serve as exit nodes for protein isolate exports to continental European sports nutrition markets.
United Kingdom Milk Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base organizes around three strategic archetypes: integrated dairy cooperatives with captive milk supply, specialized protein fractionators serving performance nutrition contracts, and diversified ingredient conglomerates leveraging cross-category scale. Competitive moves concentrate on direct-procurement relationship formation and membrane filtration technology licensing rather than asset-heavy M&A.
Among Ireland-based dairy processors, Kerry Group plc and Glanbia PLC occupy positions reflecting distinct strategic emphases—one anchored in integrated ingredient systems, the other in specialized isolate capabilities. Arla Foods Group represents the farmer-owned cooperative archetype with domestic sourcing control across Northern Europe. These three exemplify how geographic origin and ownership structure shape competitive positioning under tightening FSA purity benchmarks.
| Leading Market Players |
|---|
| Kerry Group plc |
| Royal FrieslandCampina NV |
| Arla Foods Group |
| Saputo Inc. |
| Lactalis Group |
| Fonterra Co-operative Group Limited |
| Lactoprot Deutschland GmbH |
| AMCO Proteins |
| Glanbia PLC |
| Others |
Value Network & Pricing Analysis
Farmer-owned cooperative structures anchor supply discipline across England's M62 corridor, translating collective bargaining power into stable farm-gate milk pricing that buffers concentrate processors from spot-market volatility. This ownership pattern compresses margin leakage at the raw material tier while enabling long-term contract pricing that sports nutrition brands favor for procurement planning.
Pricing Analysis
Contracted bulk supply agreements versus spot-market spot purchases split the procurement landscape, with performance nutrition brands negotiating multi-year volume commitments tied to milk futures. Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade MPC levels separates FSA-certified batches from uncertified commodity flows. Pricing pressure stems from plant-protein substitution in mass-market sports nutrition, forcing whey processors to defend leucine-density premiums. Fitness enthusiasts through supermarket channels exhibit highest price sensitivity; infant formula producers accept steepest premiums for provenance documentation.
Supply Chain Analysis
Raw milk supply rests on dairy herds concentrated in England's M62 corridor, Ireland's Munster grasslands, and Scotland's Aberdeenshire belt. Membrane filtration skids, ceramic microfiltration modules, and spray-drying towers constitute the critical equipment dependencies. Single-source vulnerability concentrates in the M62 processing cluster, where co-located facilities create geographic chokepoint risk. Distribution runs through direct-procurement relationships between processors and performance nutrition contract manufacturers, displacing traditional dairy trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in medical nutrition and clean-label infant tiers, where FSA compliance investments convert into certified-supplier premiums that outpace commodity whey processing economics.
For Market Incumbents: Lock in membrane filtration technology licensing agreements before replacement cycle peaks, securing captive supply relationships with Aberdeenshire dairy cooperatives to diversify beyond M62 corridor concentration. Plant-protein substitution in mass-market sports nutrition threatens volume-based processors; respond with backward integration into specialized isolate capabilities serving clinical nutrition protocols. For New Entrants and Emerging Players: Launch via direct-procurement partnerships with Edinburgh and Glasgow distribution networks, exploiting Scotland's underutilized processing capacity and lower land costs versus English counterparts. Medical nutrition applications remain penetration-light relative to sports and infant segments; target enteral and clinical nutrition contracts with membrane filtration investments that satisfy FSA novel food guidance. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors lacking FSA-certified analytical infrastructure, where compliance capex requirements create distressed entry points. Five-to-ten-year viability hinges on membrane technology convergence and regulatory divergence management; acquisition targets should demonstrate existing Dairy UK quality framework alignment. Watch plant-protein price parity milestones as inflection indicators for whey isolate demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Ceramic microfiltration paired with inline spectroscopy enables real-time protein fraction standardization for FSA compliance. |
| Scotland Processing Capacity Expansion | Aberdeenshire and Ayrshire underutilized assets offer lower land costs with equivalent Dairy UK quality enforcement. |
| Direct-Procurement Relationship Formation | Bulk buyers negotiating multi-year volume commitments with price collars tied to milk futures displace trader intermediaries. |
| Blockchain-Enabled Batch Documentation | Infant formula producers satisfy Trading Standards audit requirements and export market documentation simultaneously. |
| Medical Nutrition Segment Penetration | Enteral and clinical nutrition applications remain underdeveloped relative to sports and infant segments. |
Research Methodology
Bottom-up sports nutrition and infant formula demand modeling reconciled against top-down membrane filtration capacity tracking forms the analytical core of this study. Primary interviews with dairy processing engineers, FSA compliance officers, sports nutrition formulators, and Trading Standards auditors combined with secondary validation from Dairy UK quality assurance reports, Food Standards Agency guidance documents, and customs trade data on protein concentrate flows. Stakeholder perspectives triangulate against production capacity databases and equipment procurement records.
Input-output matrices map raw milk supply through fractionation stages to end-use applications across the projection horizon. Segmentation dimensions include protein fraction type, application category, end-user archetype, and distribution channel, with geographic production clusters modeled separately. CAGRs derive from trend extrapolation of procurement volumes, regulatory compliance cost trajectories, and substitution elasticity parameters. Forecast inputs incorporate milk futures price volatility, membrane technology adoption curves, and FSA enforcement intensity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under plant-protein substitution acceleration or FSA novel food guidance expansion. Projections reflect documented assumptions on regulatory stability, farm-gate milk supply continuity, and membrane filtration technology diffusion rates. A small set of triggers—plant-protein price parity, M62 corridor disruption events, and analytical chemist pipeline constraints—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Global Reduced Fat Butter Market
Dairy Products
Global Cream Cheese Market
Dairy Products
A2 Milk Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
North America Casein Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Blue Cheese Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Flavored Yogurt Market