
 Meal Kit Delivery Services Market | 2026-2036
Meal Kit Delivery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Meal Kit Delivery Services Market Analytics
Logistics labor shortages across last-mile delivery networks is unwinding capacity expansion plans for several operators. HelloFresh leverages its European fulfillment backbone to sustain cross-border density advantages. Blue Apron competes through specialized dietetic programming that differentiates its health-positioned offerings.
Meal kit delivery services bundle pre-portioned ingredients with recipe instructions into temperature-controlled shipments for residential preparation. Cold-chain integrity demands continuous refrigeration between 34°F and 40°F from packing through final handoff to preserve protein and produce safety. Subscription delivery models anchor recurring revenue streams and inventory predictability for providers, while fresh ingredient offerings command premium positioning against pre-prepared alternatives that sacrifice perceived quality for convenience. Family-style meal types occupy the largest addressable segment as multi-portion economics reduce per-serving fulfillment costs.
FDA food code compliance shapes packaging material selection and allergen labeling protocols across US operations. USDA organic certification requirements influence supplier qualification and ingredient sourcing premiums for health-focused brands. Stakeholders must monitor evolving state-level plastic packaging bans and extended producer responsibility frameworks that threaten single-use insulation economics.
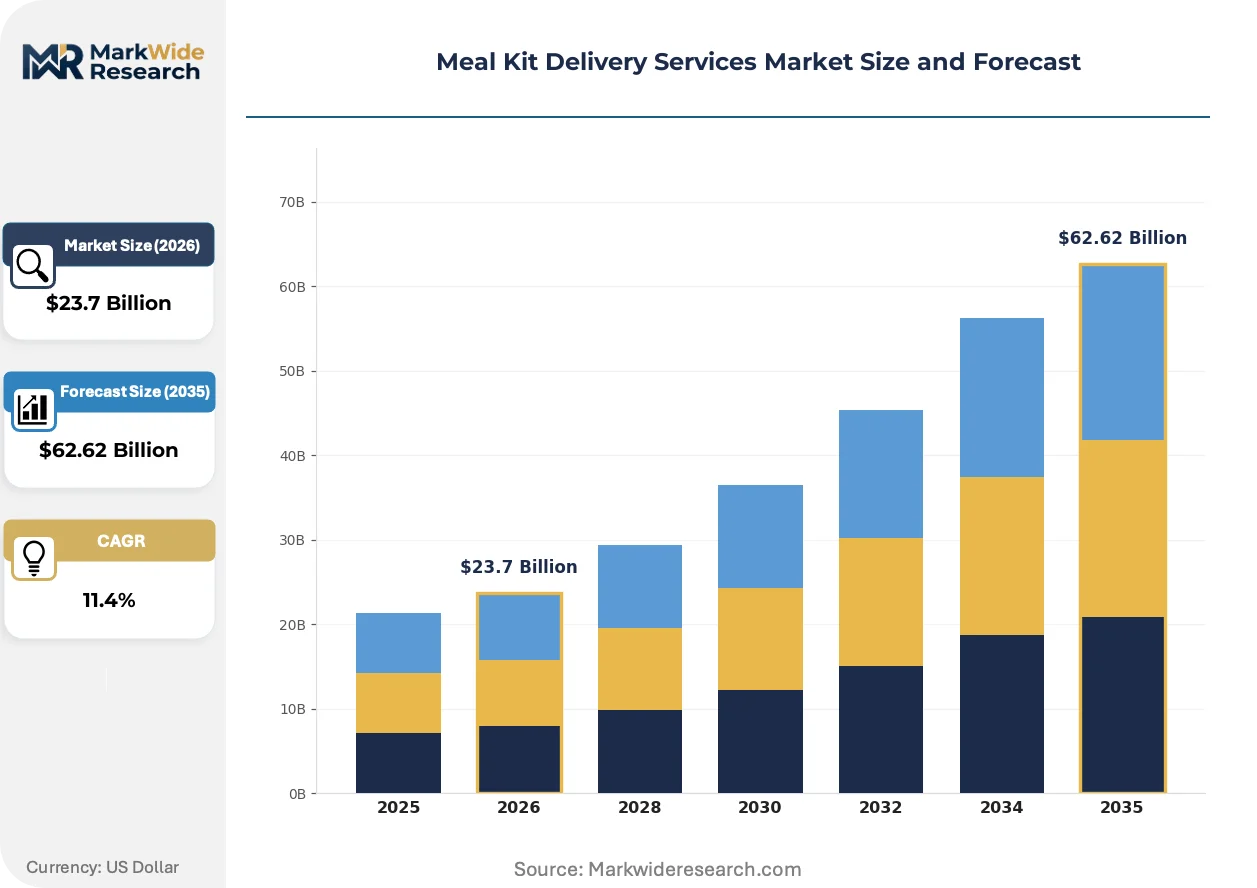
Market Dynamics
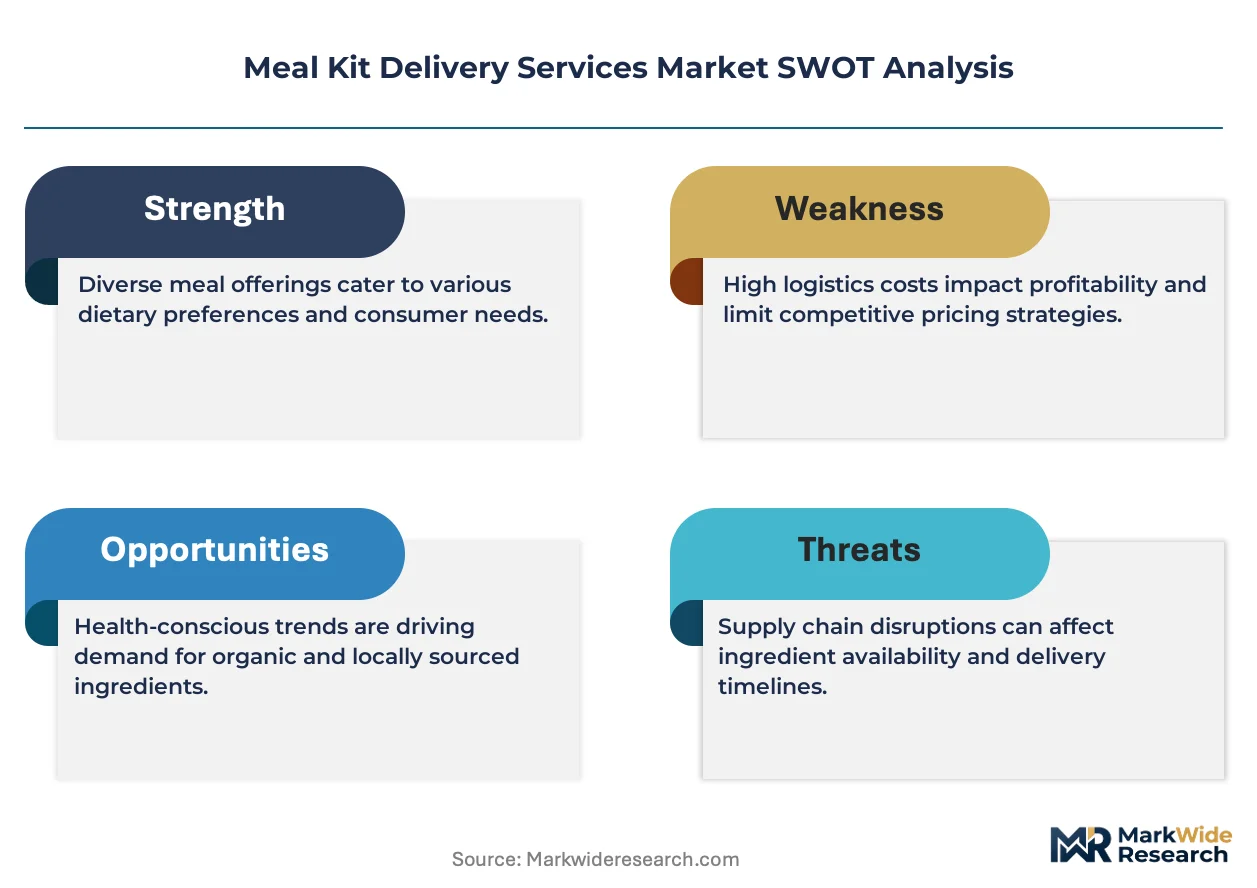
Subscription retention economics now dominate meal kit strategy as customer acquisition costs spiral and lifetime value compression forces operators toward predictive inventory systems that minimize spoilage-driven margin erosion.
Growth Catalysts
- Hybrid work normalization:Professionals with irregular home-office schedules seek flexible dinner solutions that eliminate grocery planning without sacrificing cooking engagement.
- USDA organic certification premiums:Health-conscious households pay sustained premiums for verified sourcing, expanding addressable margins for compliant suppliers.
- Active packaging innovations:Phase-change materials and cellulose-based insulation are extending safe transit windows, opening secondary markets previously unreachable within cold-chain constraints.
Market Restraints
- Protein input volatility:Beef and poultry commodity swings compress gross margins unpredictably, forcing hedging costs or menu flexibility trade-offs.
- Last-mile labor scarcity:Driver shortages in dense urban corridors constrain delivery window density and inflate wage pressure.
- Single-use packaging bans:Extended producer responsibility frameworks in multiple jurisdictions threaten insulation economics and require capital-intensive material transitions.
Strategic Opportunities
- White-space geographic expansion:Secondary US metropolitan areas with rising median incomes but limited premium grocery access represent underpenetrated demand pools.
- Healthcare channel integration:Partnerships with registered dietitians and diabetes management programs create reimbursed meal pathways.
- AI-driven personalization:Machine learning convergence with nutritional databases enables dynamic menu customization at scale previously impossible.
Industry Challenges
- Specialized cold-chain engineering talent:Scarce expertise in thermal packaging design and route optimization software implementation delays operational upgrades.
- FDA food code compliance timelines:Allergen labeling and traceability system overhauls demand 12-18 month certification cycles that stall product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meal Kit Delivery Services Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: Subscription, One-time Purchase, Gift Options, Corporate Packages Meal Type: Vegetarian, Vegan, Family-style, Low-calorie Product Offering: Fresh Ingredients, Pre-prepared Meals, Snacks, Desserts Target Audience: Busy Professionals, Families, Fitness Enthusiasts, Students |
| Companies Covered | Green Chef, Dinnerly, HelloFresh, Marley Spoon, EveryPlate, Blue Apron, Purple Carrot, Sunbasket, Home Chef, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meal Kit Delivery Services Market Evolving Landscape
Digital infrastructure and material science advances are compressing fulfillment timelines while regulatory pressure accelerates sustainable packaging transitions. Three forces are restructuring competitive requirements.
Reusable insulated container programs with deposit-return logistics are supplanting single-use expanded polystyrene across premium subscriber tiers. Urban households with storage space and environmental preferences adopt these systems at accelerating rates. This shift is compressing per-delivery material costs while creating reverse logistics complexity that rewards operators with established density.
Extended producer responsibility mandates in multiple US states are forcing packaging redesign investments ahead of federal standardization. Industrial consequences include accelerated R&D spending on compostable thermal materials and supplier qualification bottlenecks. Family-style meal providers with higher shipment volumes face disproportionate compliance pressure and are consolidating supplier relationships to manage certification burden.
Subscription flexibility models now allow pause-skip-modify cycles without penalty, displacing rigid monthly commitments. Direct-to-consumer channels are capturing share from traditional retail meal kit placements as buyers prioritize control over spontaneity. This behavioral pivot is most visible in coastal metropolitan markets where delivery density supports on-demand fulfillment promises.
Meal Kit Delivery Services Market Segmentation
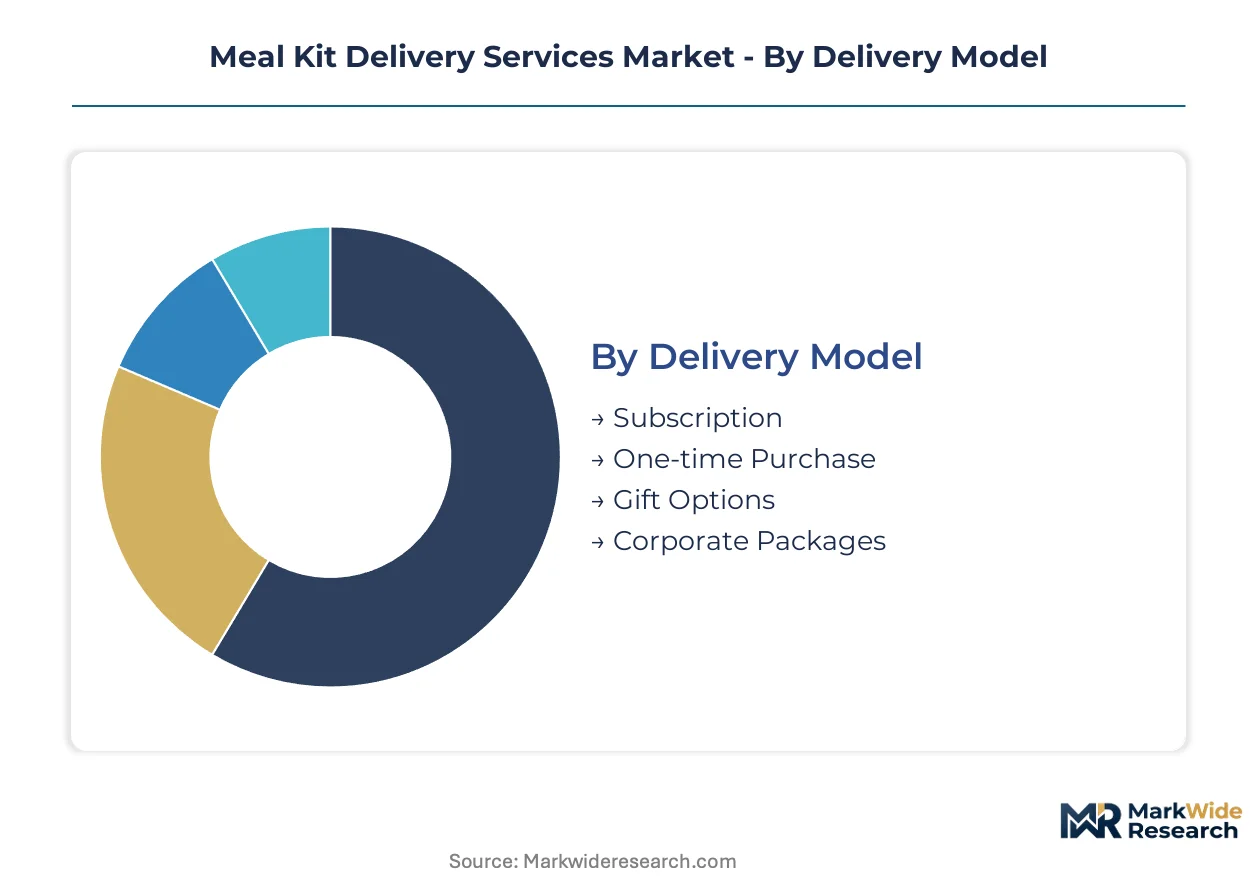
Segmentation in meal kit delivery services determines cold-chain infrastructure investment, packaging specifications, and subscription pricing architecture. Regulatory compliance requirements vary sharply across delivery models and product categories, forcing operators to engineer distinct operational workflows for each segment.
Delivery Model:
FDA food code traceability mandates and state-level extended producer responsibility laws create divergent compliance burdens across fulfillment approaches.
- Subscription:Recurring shipment schedules enable predictive inventory management and route density optimization. Households in dense US metropolitan corridors with established delivery infrastructure anchor demand, though customer acquisition cost inflation pressures lifetime value calculations.
- One-time Purchase:Flexible ordering without commitment appeals to trial-oriented consumers and gift recipients. Urban professionals with irregular travel schedules drive adoption where on-demand fulfillment networks support spontaneous purchase patterns.
- Gift Options:Pre-paid multi-week programs target seasonal demand peaks and corporate wellness budgets. Limited customization and fixed menu rotations reduce operational complexity for providers.
- Corporate Packages:Bulk enrollment programs for employer-subsidized meal benefits require specialized B2B sales infrastructure and customized invoicing systems.
Established volume favors Subscription; emerging adoption favors One-time Purchase.
Meal Type:
USDA organic certification premiums and allergen labeling protocols segment production facilities and supplier qualification requirements.
- Family-style:Multi-portion configurations reduce per-serving fulfillment costs through consolidated packaging and route density. Suburban households with children concentrate demand where storage capacity supports larger shipment volumes.
- Vegan:Plant-based protein sourcing and specialized supplier networks command ingredient premiums. Health-conscious coastal metropolitan consumers and environmental advocates sustain addressable margins despite higher procurement costs.
- Vegetarian:Dairy and egg-inclusive menus balance cost accessibility with perceived health positioning. Broad demographic appeal supports menu standardization across regional fulfillment centers.
- Low-calorie:Portion-controlled specifications and registered dietitian partnerships create reimbursed pathway potential through healthcare channel integration.
Family-style captures the largest revenue base; Vegan climbs the fastest among health-positioned alternatives.
Product Offering:
Cold-chain integrity requirements and shelf-life specifications determine thermal packaging investment and last-mile delivery window constraints.
- Fresh Ingredients:Pre-portioned raw proteins and produce demand continuous refrigeration between 34°F and 40°F from packing through final handoff. Premium positioning against processed alternatives sustains price realization where quality perception differentiates providers.
- Pre-prepared Meals:Cooked-and-chilled or flash-frozen formats extend safe transit windows and reduce preparation friction. Time-constrained professionals with minimal cooking skills drive adoption in secondary metropolitan markets with limited premium grocery access.
- Snacks:Ambient-stable or lightly refrigerated add-on items supplement core meal shipments with incremental revenue attachment.
- Desserts:Specialized temperature requirements and seasonal demand concentration create production planning complexity and margin volatility.
Fresh Ingredients commands the pricing premium; Pre-prepared Meals expands most quickly into convenience-oriented segments.
Target Audience:
Work-from-home hybrid normalization and healthcare cost containment reshape addressable demand across demographic profiles.
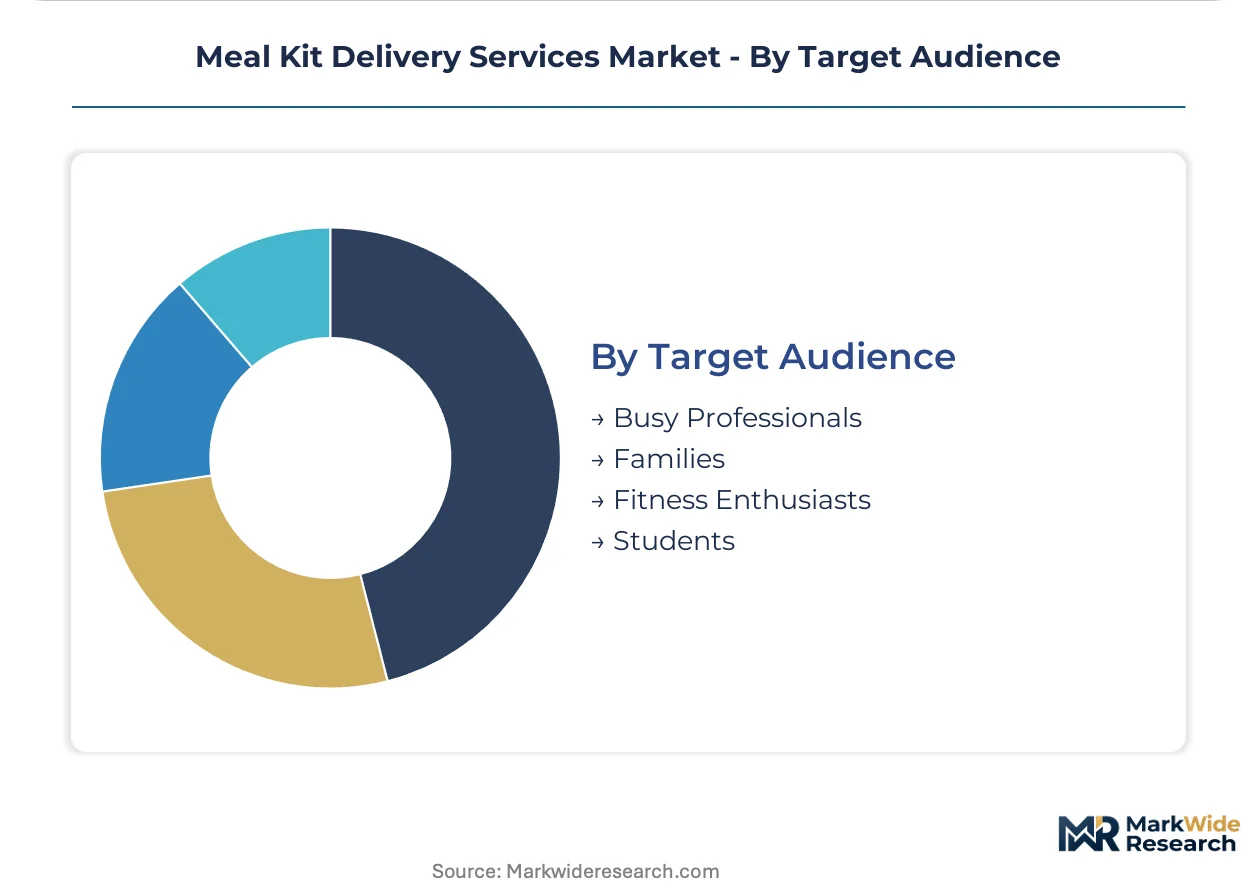
- Busy Professionals:Irregular home-office schedules eliminate predictable meal planning capacity. Urban density corridors with sub-hour delivery promise feasibility concentrate subscription conversion.
- Families:Multi-person household economics favor portion-scaled offerings and simplified weeknight execution. Suburban school-year routine alignment drives seasonal demand patterns.
- Fitness Enthusiasts:Macro-nutrient tracking integration and protein-optimized menus support premium positioning. Registered dietitian partnerships create reimbursed access pathways through employer wellness programs.
- Students:Price sensitivity and limited storage capacity constrain addressable economics; campus proximity requirements restrict scalable delivery coverage.
Busy Professionals anchor current revenue; Fitness Enthusiasts gains share fastest through healthcare channel integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US households prioritize subscription flexibility and family-style portions, while European markets emphasize organic certification premiums. Asian adoption concentrates in dense metropolitan corridors where cold-chain infrastructure supports rapid delivery windows.
United States
Hybrid work normalization and suburban family density drive subscription retention. FDA food code compliance mandates 12-18 month allergen labeling system overhauls. The New York metropolitan corridor anchors operational scale, where route density optimization sustains last-mile economics.
Germany
Organic certification premiums and environmental packaging preferences shape purchasing decisions. EFSA traceability requirements and EU Green Deal packaging mandates accelerate compostable insulation transitions. Berlin and Munich clusters concentrate fulfillment center investment as operators consolidate supplier relationships.
United Kingdom
Urban professional households with irregular schedules favor flexible pause-skip-modify subscription models. Extended producer responsibility frameworks in England and Scotland force single-use packaging redesign ahead of federal standardization. London density supports reusable insulated container deposit-return logistics at scale.
Australia
Coastal metropolitan consumers prioritize health-positioned offerings and registered dietitian partnerships. Food Standards Australia New Zealand (FSANZ) labeling protocols and state-level plastic bans reshape thermal material selection. Sydney and Melbourne corridors concentrate demand where premium grocery access remains limited in secondary suburbs.
Canada
Multi-person household economics and cold-climate delivery reliability concerns concentrate demand in Ontario and Quebec. Health Canada food safety regulations and provincial extended producer responsibility laws drive packaging compliance investments. Toronto and Vancouver clusters anchor cross-border logistics integration with US fulfillment networks.
Meal Kit Delivery Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier competitive structure. The upper tier commands cross-border density advantages and predictive inventory systems that minimize spoilage-driven margin erosion. Specialist players occupy health-positioned niches through dietetic programming and organic certification premiums. Consolidation pressure intensifies as customer acquisition costs spiral and lifetime value compression forces M&A activity and strategic partnership formations.
Within the integrated tier, HelloFresh exemplifies scale-driven operational density through European fulfillment backbone leverage. Blue Apron occupies a position among health-positioned specialists, differentiating through registered dietitian partnerships and reimbursed pathway development. Home Chef represents the mass-market accessibility archetype, competing on simplified weeknight execution for suburban families. These three anchors illustrate the strategic divergence between cross-border infrastructure investment and niche positioning through specialized programming.
| Leading Market Players |
|---|
| Green Chef |
| Dinnerly |
| HelloFresh |
| Marley Spoon |
| EveryPlate |
| Blue Apron |
| Purple Carrot |
| Sunbasket |
| Home Chef |
| Others |
Value Network & Pricing Analysis
Fulfillment center utilization rates above 85 percent in dense metropolitan corridors compress per-unit logistics costs and establish price floors that smaller operators cannot match. This scale concentration shapes competitive positioning across subscription tiers while forcing regional specialists toward niche dietetic programming to escape margin compression.
Pricing Analysis
Long-term subscription contracts dominate revenue architecture, with monthly recurring commitments anchoring predictable cash flows against spot-market ingredient volatility. Price differentiation rests on USDA organic certification tiers and family-style volume scaling, with health-positioned offerings commanding sustained premiums. Cost compression in economy-tier segments is intensifying because protein commodity swings and last-mile wage pressure erode gross margins. Students and price-sensitive single-person households exhibit highest price elasticity, while fitness enthusiasts and healthcare-integrated buyers show lowest sensitivity due to reimbursed access pathways.
Supply Chain Analysis
Inbound logistics costs from port congestion on Asia-Pacific trade lanes and refrigerated container scarcity inflate thermal packaging material expenses for US-based operators. Ingredient sourcing concentrates in the United States, Mexico, and Canada for produce and proteins, with specialty items drawing from European organic suppliers. The supply chain rests on single-source vulnerability for phase-change insulation materials and compostable thermal liners. Distribution runs through hub-and-spoke fulfillment networks with last-mile handoff to regional parcel carriers and gig-economy delivery platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Meal kit delivery services represent a high-growth disruption as AI-driven personalization converges with nutritional databases to enable dynamic menu customization at previously impossible scale. Extended producer responsibility mandates across multiple jurisdictions accelerate sustainable packaging transitions that reshape capital deployment requirements.
For Market Incumbents: Shield subscription retention economics through predictive inventory systems that minimize spoilage-driven margin erosion. Deepen cold-chain engineering capabilities in secondary metropolitan corridors where route density advantages remain defensible against emerging entrants. Consolidate supplier relationships to manage compostable insulation certification burdens as state-level packaging bans proliferate.
For New Entrants and Emerging Players: Lead with healthcare channel integration targeting reimbursed meal pathways through registered dietitian partnerships and diabetes management programs. White-space geographic expansion into secondary US metropolitan areas with rising median incomes but limited premium grocery access offers the most penetrable demand pools. Corporate wellness program bulk enrollment provides a B2B go-to-market angle with customized invoicing infrastructure.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with established AI personalization engines and reusable insulated container logistics. Long-term viability across the projection horizon hinges on cold-chain density advantages and regulatory compliance infrastructure rather than brand recognition alone. Monitor FDA food code traceability mandate implementation timelines as an inflection indicator for operational upgrade capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Personalization Engine Deployment | Machine learning convergence with nutritional databases enables dynamic menu customization at scale. |
| Reusable Insulated Container Program Launch | Deposit-return logistics in urban density corridors compress per-delivery material costs. |
| Healthcare Channel Partnership Formation | Registered dietitian collaborations create reimbursed meal pathways through employer wellness programs. |
| Compostable Thermal Material R&D Investment | Extended producer responsibility mandates accelerate sustainable packaging transitions ahead of federal standardization. |
| Secondary Metropolitan Fulfillment Center Expansion | Route density optimization in underpenetrated demand pools sustains last-mile economics. |
Research Methodology
A standing panel of fulfillment center operations directors, cold-chain logistics specialists, registered dietitians, and grocery retail category managers provided ongoing calibration throughout the study. Primary interviews with meal kit supply chain executives and subscription platform product managers combined with secondary validation from FDA food code documentation, USDA organic certification databases, and state-level extended producer responsibility filings. Customs records for refrigerated container imports and cold-storage facility permitting data anchored bottom-up capacity estimates against top-down revenue triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled delivery model segmentation, meal type categories, product offering tiers, and target audience demographics throughout the forecast period. CAGRs derived from historical subscription growth patterns, customer acquisition cost trajectories, and retention rate benchmarks. Ingredient cost indices and last-mile wage inflation assumptions informed margin compression scenarios.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain infrastructure investment and regulatory compliance timelines would require recalibration. Forecasts reflect assumptions regarding hybrid work normalization persistence, protein commodity volatility ranges, and state-level packaging ban implementation schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Kitchen Appliances Market
Food Service
United States Full Service Restaurants Market
Food Service
Food & Beverage in Asia Market
Food Service
Commercial Rice Cooker Market
Food Service
Fast Food Market
Food Service
Kamado Grill Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
Commercial Steam Table Market
Food Service
Netherlands Food Service Market
Food Service
Singapore Food Service Market
Food Service
United Kingdom Foodservice Market
Food Service
Steam Stew Pot Market
Food Service
North America Food Service Disposable Market
Food Service
Europe Airline Catering Services Market
Food Service
Rotisseries Market
Food Service
US Food Service Market