
 Fluid Milk Market | 2026-2036
Fluid Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Milk Market Intelligence
Supermarket private-label fluid milk programs are rewriting procurement relationships between retailers and dairy cooperatives. Lactalis leverages its vertically integrated European dairy network to supply store-brand milk across multiple continents. Dairy Farmers of America anchors its position through cooperative ownership of processing plants serving central US retail chains. Fonterra competes by controlling ocean freight logistics for refrigerated milk exports from New Zealand to Asian markets.
Fluid milk denotes the liquid dairy product obtained from mammalian milking, standardized to specific fat content through centrifugal separation and thermally processed via high-temperature short-time pasteurization or ultra-high-temperature treatment to achieve microbiological stability. The product serves as a nutritional staple for direct consumption, ingredient manufacturing, and food service preparation across institutional and commercial channels. Whole milk retains dominant volume share in emerging markets where caloric density drives household purchase decisions, while skimmed milk and 2% milk concentrate margin pools in North American and European health-positioned retail segments. Flavored milk represents the fastest-growing product type as dairy processors add functional ingredients targeting school nutrition programs and post-workout recovery positioning.
FDA Grade A Pasteurized Milk Ordinance governs interstate fluid milk commerce in the United States, mandating pathogen testing and temperature controls that shape processor compliance costs. EFSA dairy hygiene standards and EU Green Deal agricultural methane targets are redirecting European production investment toward lower-emission farming systems. India's FSSAI food safety codes for liquid milk establish bacterial count thresholds that determine market access for organized sector processors. Stakeholders must monitor how divergent carbon accounting methodologies across these jurisdictions will reshape competitive cost structures for fluid milk sourcing and distribution.
Market Dynamics
Extended-shelf-life processing technology is redrawing procurement geography for fluid milk, enabling dairy processors to serve distant institutional buyers without cold chain density that traditional pasteurization demands.
Growth Catalysts
- ESL Processing Adoption:Ultra-high-temperature treatment extends distribution radius for processors serving school districts and hospital networks, reducing spoilage rates in low-cold-chain-density regions.
- FSSAI Bacterial Standards:India's tightening liquid milk safety codes are accelerating cooperative investment in organized sector processing capacity, displacing informal vendors.
- Functional Ingredient Integration:Dairy processors fortify flavored milk with protein isolates and micronutrients, capturing post-workout recovery and school nutrition program demand.
Market Restraints
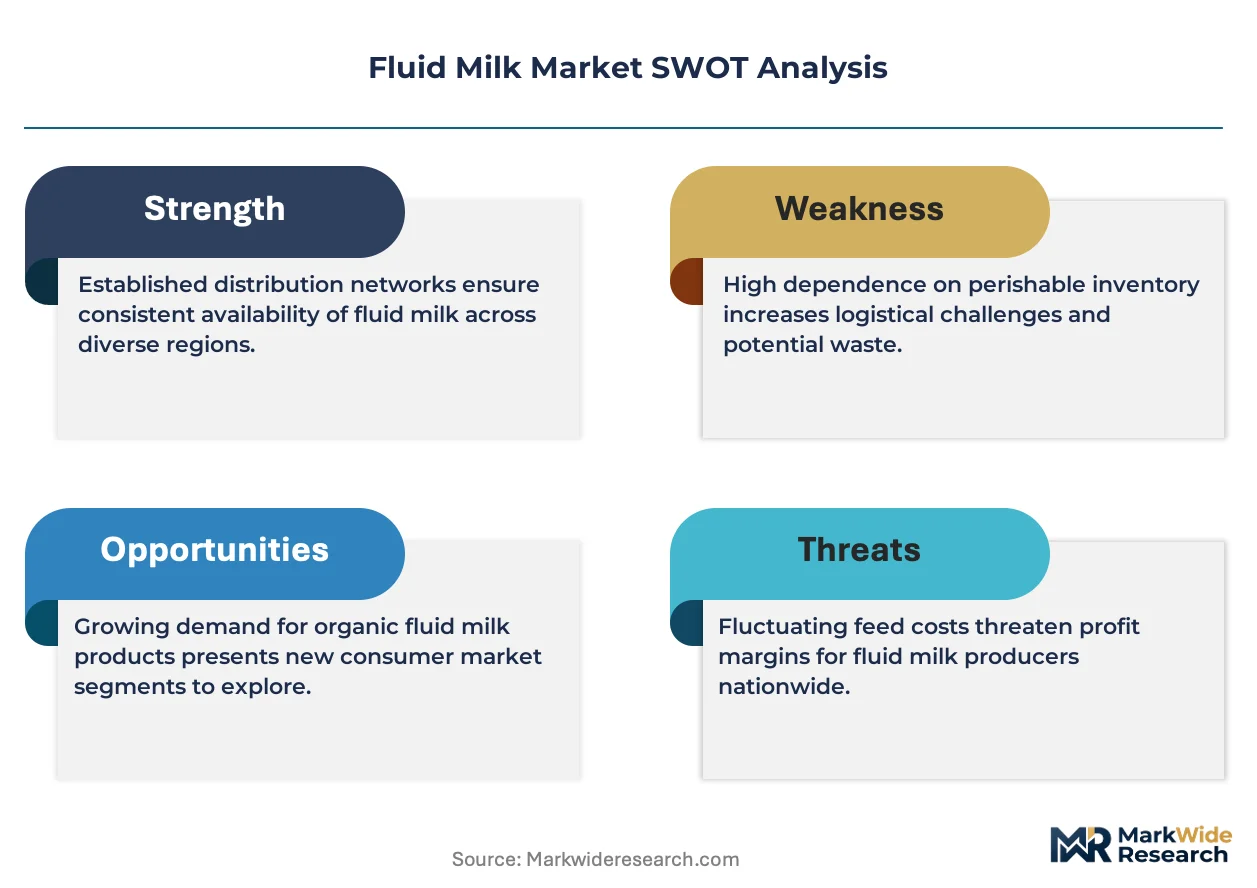
- Feed Input Volatility:Corn and soybean meal price swings transmit directly to farmgate milk production costs, compressing processor margins during commodity spikes.
- Refrigerated Distribution Concentration:Cold chain infrastructure ownership clusters with large integrated retailers, limiting independent processor market access.
- Plant-Based Substitution:Oat and almond milk alternatives capture shelf space in North American and European retail, constraining fluid milk volume expansion.
Strategic Opportunities
- Cooperative Cold Chain Modernization:India's dairy cooperatives are deploying solar-powered bulk milk chillers at village collection centers, cutting post-harvest losses.
- EU Green Deal Methane Targets:Agricultural emission reduction incentives redirect investment toward lower-carbon farming systems, creating premium positioning for compliant supply.
- Aseptic Carton Channel Expansion:Shelf-stable packaging formats penetrate convenience retail and e-commerce direct-to-consumer channels previously closed to chilled distribution.
Industry Challenges
- Pathogen Testing Compliance:FDA Grade A Pasteurized Milk Ordinance mandates impose laboratory capacity requirements that strain smaller processors.
- Carbon Accounting Divergence:Inconsistent emission measurement methodologies across US, EU, and Indian regulatory frameworks complicate cross-border sourcing decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Milk Market |
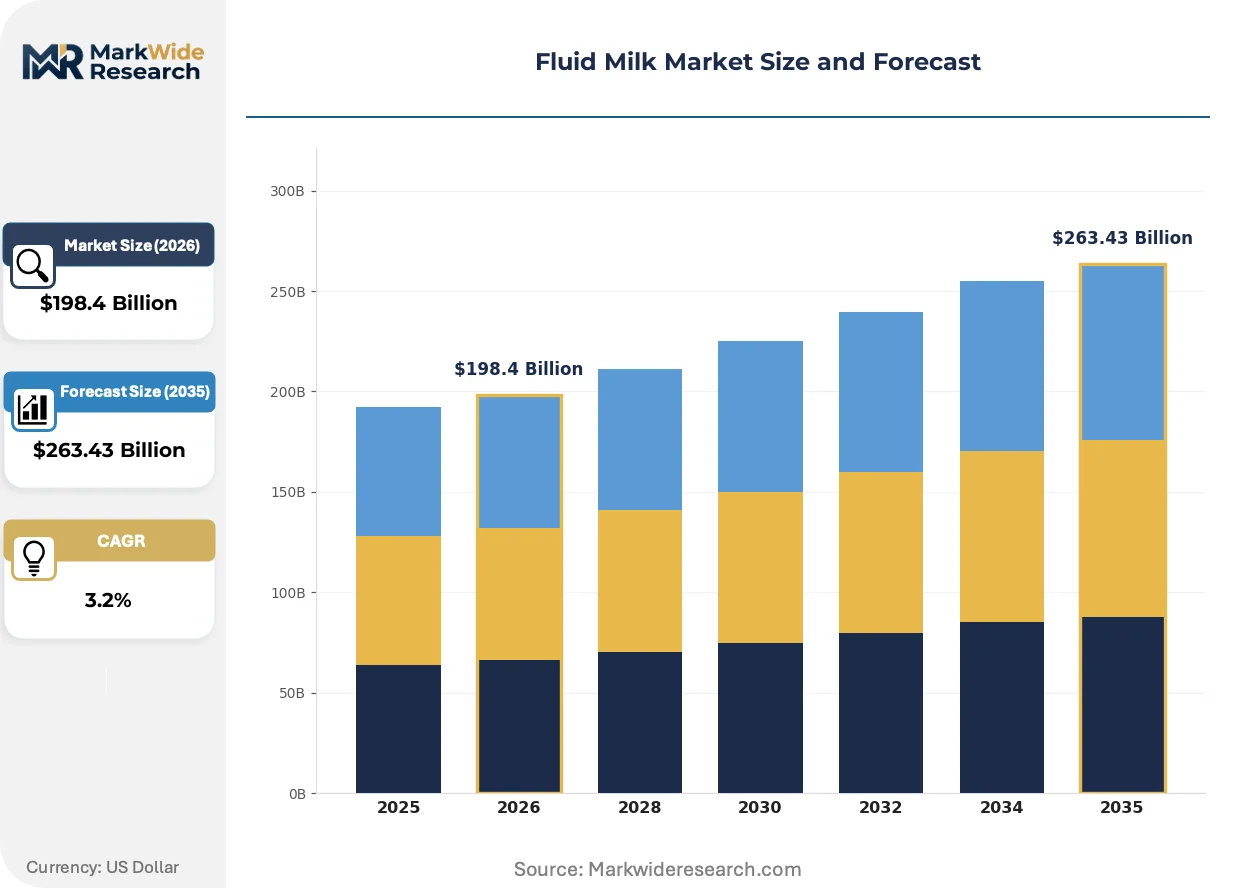
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $263.43 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skimmed Milk, 2% Milk, Flavored Milk Packaging Type: Bottles, Cartons, Pouches, Bulk Containers Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service End User: Households, Institutions, Restaurants, Cafeterias |
| Companies Covered | Nestlé, Lactalis, Dairy Farmers of America, Fonterra, Arla Foods, FrieslandCampina, Saputo, Yili Group, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Milk Market Strategic Shifts & Innovations
Digital traceability platforms and precision fermentation are converging to transform how fluid milk quality is verified and how dairy proteins are sourced, altering competitive requirements for processors and ingredient suppliers alike.
Blockchain-enabled batch tracking is virtualizing quality assurance workflows for fluid milk supply chains. Large retail chains and food service distributors now mandate farm-to-shelf digital provenance records. This technology is compressing audit timelines and reducing liability exposure for processors managing multi-source procurement.
EU Green Deal agricultural methane targets are redirecting capital toward anaerobic digesters and feed additives that suppress enteric fermentation. Dairy cooperatives in Denmark and the Netherlands face binding emission reduction pathways. Organic and grass-fed fluid milk segments absorb compliance premiums most readily.
School nutrition directors now specify protein content thresholds and reduced-sugar formulations in bulk milk contracts, shifting volume toward fortified flavored milk. This specification tightening favors processors with in-house dairy protein fractionation capabilities. The pivot is most pronounced in US K-12 institutional procurement.
Fluid Milk Market Segmentation
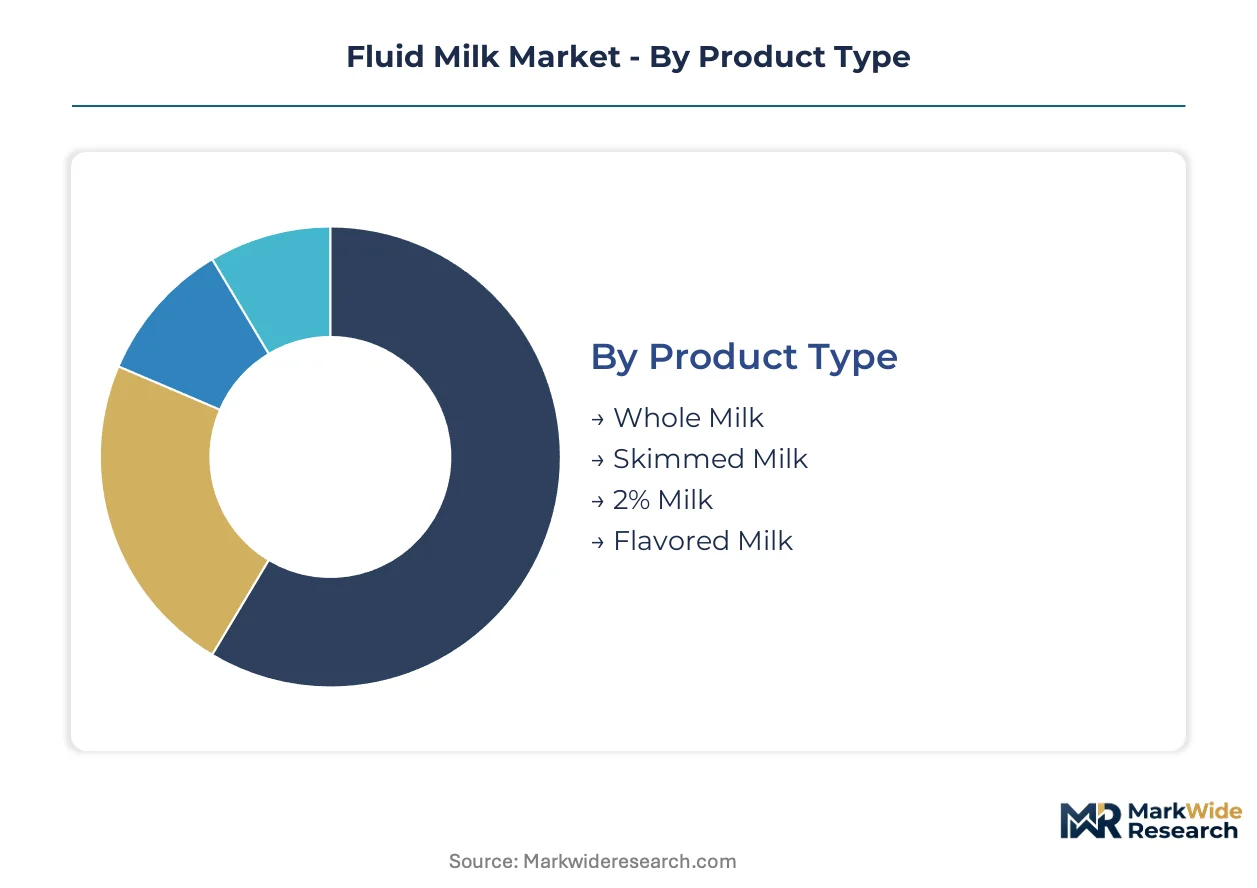
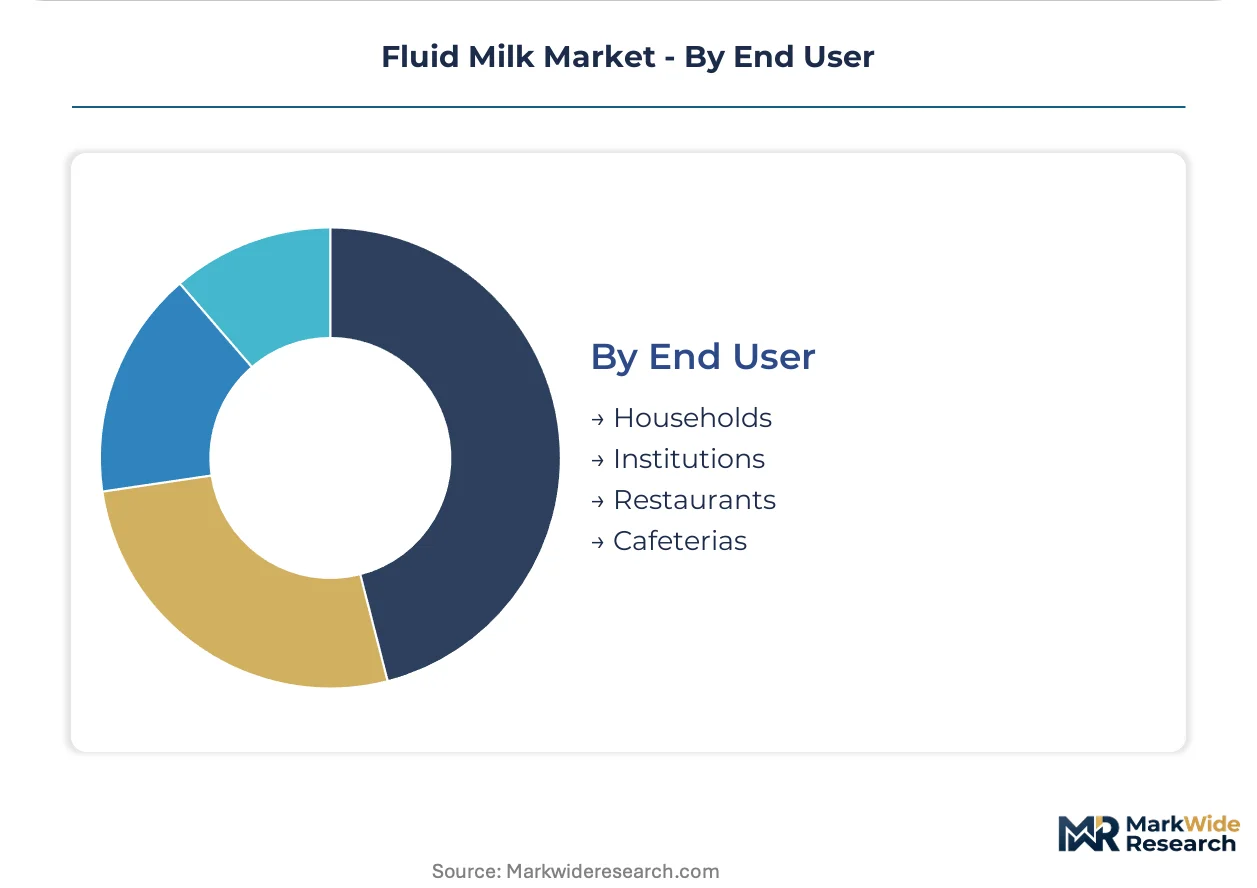
Fluid milk segmentation reveals how processing technology, packaging innovation, and channel economics partition value across distinct buyer requirements. Each dimension carries procurement implications for dairy cooperatives and retail chains navigating shelf-life demands and price positioning.
Product Type:
The use-case spectrum spans caloric-density staples in emerging markets to protein-optimized formulations in health-positioned retail segments.
- Whole Milk:Retains full butterfat content through minimal centrifugal separation, delivering caloric density that drives household purchase decisions across India and Southeast Asia. Village dairy cooperatives in Gujarat and Karnataka prioritize whole milk collection to serve price-sensitive domestic consumers.
- Flavored Milk:Dairy processors integrate protein isolates, micronutrients, and reduced-sugar formulations to capture school nutrition program contracts and post-workout recovery positioning. US K-12 procurement specifications now mandate protein thresholds that favor processors with in-house fractionation capabilities.
- Skimmed Milk:Near-zero butterfat content targets health-conscious retail segments in North American and European supermarkets.
- 2% Milk:Reduced-fat positioning balances taste preference with caloric moderation in mid-tier retail tiers.
The dominant share belongs to whole milk, while flavored milk is closing the gap fastest.
Packaging Type:
Cost tier differentiation separates premium shelf-stable formats from commodity chilled distribution infrastructure.
- Cartons:Aseptic carton technology enables ambient distribution without refrigerated logistics, penetrating convenience retail and e-commerce direct-to-consumer channels previously closed to chilled milk. Tetra Pak processing lines require capital investment that favors large cooperative processors.
- Bottles:HDPE and PET formats dominate supermarket chilled dairy cases where transparent packaging supports freshness signaling. European retailers specify recycled content thresholds that reshape procurement contracts with dairy processors.
- Pouches:Flexible packaging reduces material cost and shipping weight for price-sensitive emerging market distribution.
- Bulk Containers:Stainless steel totes and bag-in-box systems serve institutional food service and ingredient manufacturing procurement.
Cartons command premium positioning through shelf-stable technology, while pouches gain share fastest in emerging market cost optimization.
Distribution Channel:
Customer type concentration determines margin structure and cold chain investment requirements across retail formats.
- Supermarkets:Private-label fluid milk programs anchor procurement relationships between retail chains and dairy cooperatives, with Lactalis and Dairy Farmers of America competing for store-brand supply contracts. Refrigerated display ownership concentrates leverage with large integrated retailers.
- Food Service:Institutional cafeterias, hospitals, and school districts specify extended-shelf-life processing to reduce spoilage in low-cold-chain-density regions. ESL procurement is expanding distribution radius for processors serving distant institutional buyers.
- Convenience Stores:Smaller format retail prioritizes long-life packaging and single-serve portioning for immediate consumption.
- Online Retail:Direct-to-home delivery requires insulated packaging and last-mile cold chain investment that favors vertically integrated dairy networks.
Supermarkets retain volume concentration, while food service is expanding most quickly through institutional ESL adoption.
End User:
Application maturity separates established household consumption from emerging institutional specification markets.
- Households:Direct consumption remains the foundational demand driver, with whole milk dominating emerging market purchase patterns and reduced-fat variants penetrating health-positioned segments in developed economies.
- Institutions:School nutrition directors and hospital procurement officers now specify protein content, reduced-sugar formulations, and extended shelf life in bulk contracts. India's organized dairy retail sector is modernizing cold chain infrastructure to serve institutional volume.
- Restaurants:Food preparation and beverage service demand standardized fat content for recipe consistency.
- Cafeterias:Self-service institutional dining requires portion-controlled packaging and bulk dispensing systems.
Households anchor baseline demand, while institutions drive specification tightening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain terminals anchor European fluid milk redistribution to Asian and African markets. India's Dedicated Freight Corridor links Delhi to Mumbai with temperature-controlled railcars. China's Yangtze River Delta cold storage network underwrites dairy import throughput.
United States
Supermarket private-label procurement concentrates volume with cooperative processors across the Midwest. FDA Grade A Pasteurized Milk Ordinance pathogen testing mandates reshape laboratory capacity requirements. Wisconsin and California dairy clusters modernize ESL processing lines to serve distant institutional buyers.
China
Organized retail sector expansion drives demand for standardized fat content and extended shelf life. GB standards for dairy safety tighten pasteurization requirements and bacterial count thresholds. Yangtze River Delta processing hubs invest in aseptic carton technology to penetrate convenience retail channels.
India
Cooperative modernization of village collection centers accelerates organized sector displacement of informal vendors. FSSAI food safety codes establish bacterial count thresholds that determine market access for processors. Gujarat and Karnataka dairy clusters deploy solar-powered bulk milk chillers to cut post-harvest losses.
Germany
EU Green Deal agricultural methane targets redirect capital toward anaerobic digesters and feed additives. EFSA dairy hygiene standards shape cross-border sourcing compliance costs for processors. Bavarian and Lower Saxony dairy networks absorb emission reduction premiums through organic and grass-fed positioning.
Brazil
Supermarket consolidation drives procurement standardization for fluid milk fat content and packaging formats. ANVISA dairy safety regulations establish microbiological standards for interstate commerce. São Paulo and Minas Gerais processing clusters expand aseptic packaging capacity to serve Northeast retail expansion.
Fluid Milk Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The fluid milk market structures around vertically integrated dairy cooperatives, multinational consumer goods conglomerates, and regional processing specialists. Three archetypes dominate: cooperative-owned processors with captive farm supply, multinational dairy networks with cross-border logistics control, and emerging-market national champions with domestic distribution density. Competitive moves concentrate on cold chain infrastructure ownership and extended-shelf-life technology licensing.
Among European-based dairy networks, Lactalis and FrieslandCampina exemplify vertically integrated multinational archetypes with cooperative roots. Dairy Farmers of America anchors the cooperative-owned processor tier in North America. Fonterra occupies a position bridging Australasian farm supply with Asian market logistics control. These three represent distinct strategic postures: European cross-border retail private-label supply, North American domestic cooperative consolidation, and export-oriented ocean freight refrigeration mastery.
| Leading Market Players |
|---|
| Nestlé |
| Lactalis |
| Dairy Farmers of America |
| Fonterra |
| Arla Foods |
| FrieslandCampina |
| Saputo |
| Yili Group |
| Danone |
| Others |
Cost & Logistics Intelligence
Wisconsin's dairy processing corridor concentrates fluid milk capacity in a tight band of cooperative-owned plants, translating upstream consolidation into asymmetric bargaining power against retail procurement teams. This geographic clustering of pasteurization and ESL infrastructure allows large processors to enforce volume-commitment contracts that lock in shelf space while marginalizing smaller competitors on price.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with school districts and hospital networks securing sub-wholesale rates through multi-year offtake agreements while convenience retail pays spot premiums. Price differentiation hinges on certification grade — FDA Grade A compliance commands measurable premiums over state-inspected alternatives — and cold chain density, where remote delivery surcharges compound base costs. Pricing pressure stems from plant-based substitution in North American retail, compressing conventional fluid milk margins. Household direct consumption segments exhibit highest price sensitivity, while institutional buyers with nutrition-mandated protein specifications show relative inelasticity.
Supply Chain Analysis
Export-control regimes on UHT processing equipment limit technology transfer to emerging market processors, constraining capacity expansion in regions with tightening safety codes. Geographic supply concentrates in New Zealand, the United States, and the European Union's northern dairy belt. Raw material dependencies center on corn and soybean meal for dairy cow nutrition, plus aseptic packaging substrates for shelf-stable formats. Single-source vulnerability runs through ocean freight refrigeration for intercontinental trade, where container availability fluctuations disrupt New Zealand-to-Asia flows. Distribution runs through vertically integrated retail private-label networks and cooperative-owned chilled logistics pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended-shelf-life processing technology is disrupting procurement geography and margin structures, with FSSAI bacterial standards in India accelerating cooperative modernization that rewards early equipment adopters.
For Market Incumbents: Build captive cold chain infrastructure as the defensive moat, deploying solar-powered bulk milk chillers at village collection centers in Gujarat and Karnataka to lock in cooperative supply before FSSAI compliance deadlines. Deepen backward integration into aseptic carton manufacturing to capture packaging margin and reduce Tetra Pak dependency. Plant-based substitution in North American retail represents the primary margin threat requiring fortified flavored milk innovation with protein fractionation capabilities. For New Entrants and Emerging Players: India's organized dairy retail sector offers the most penetrable white space, where informal vendor displacement creates procurement vacuum for compliant processors. Target institutional food service contracts specifying ESL processing and protein thresholds, segments where incumbent cooperatives lag on formulation agility. Go-to-market leverage rests on digital traceability platforms that virtualize quality assurance for retail chains mandating farm-to-shelf provenance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with in-house ESL and fractionation capabilities over commodity pasteurization operators. Long-term viability centers on emission-compliant supply chains as EU Green Deal methane targets harden into binding reduction pathways. Acquisition archetype: regional cooperatives with latent cold chain assets and FSSAI-ready laboratory capacity. Signal to watch: ANVISA enforcement tightening in Brazil's Northeast retail expansion corridor.| Strategic Initiative | Industry Significance |
|---|---|
| ESL Processing Line Modernization | Extends distribution radius for processors serving distant institutional buyers in low-cold-chain-density regions. |
| Cooperative Cold Chain Infrastructure | Solar-powered bulk milk chillers at village collection centers cut post-harvest losses and secure FSSAI compliance. |
| Functional Ingredient Integration | Protein isolate fortification captures school nutrition program contracts with mandated protein content thresholds. |
| Aseptic Carton Channel Expansion | Shelf-stable packaging penetrates convenience retail and e-commerce direct-to-consumer channels previously closed to chilled distribution. |
| Emission-Reduction Farming Systems | Anaerobic digesters and feed additives absorb EU Green Deal compliance premiums through organic and grass-fed positioning. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA Grade A compliance filings, FSSAI food safety code amendments, EU Green Deal agricultural methane target documentation, and cooperative processing capacity disclosures. Dairy cooperative procurement managers, retail category buyers, school nutrition directors, cold chain logistics operators, and dairy protein fractionation engineers provided structured input. Secondary validation drew from customs trade data, SEC filings of listed dairy processors, and EFSA hygiene standard updates. Bottom-up capacity modeling triangulates against top-down consumption estimates across product type, packaging format, and distribution channel dimensions.
Forecast inputs encompass installed ESL processing capacity, FSSAI enforcement trajectory, EU methane reduction incentive uptake, and plant-based substitution elasticities in North American retail. Segmentation modeling spans product type, packaging technology, distribution channel, and end-user application. CAGRs derive from elasticity-adjusted volume projections and price-path assumptions across the analysis window. Industry-specific inputs include school nutrition program specification tightening and aseptic packaging substrate cost curves.
Practitioners should monitor FSSAI bacterial standard enforcement intensity, EU Green Deal agricultural methane target revision schedules, and ocean freight refrigeration container availability for early signals of forecast deviation. Material shifts in plant-based milk substitution rates or ESL equipment export-control regime liberalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Fresh Milk Market
Dairy Products
China Dairy Market
Dairy Products
Dairy Carton Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Milk Protein Crisps Market
Dairy Products
Filled Cheese Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Lactose Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Sheep Milk Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
United States Yogurt Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Goat Milk Powder Market