
 Asia-Pacific Cow Milk Minerals Market | 2026-2036
Asia-Pacific Cow Milk Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cow Milk Minerals Market Outlook
Nutraceutical companies are redrawing procurement patterns across the Asia-Pacific Cow Milk Minerals landscape, pulling volume away from traditional dairy manufacturers toward functional-ingredient specialists. Fonterra Co-operative Group Limited leverages its New Zealand grass-fed sourcing to command premium positioning in calcium concentrates. Inner Mongolia Yili Industrial Group Co., Ltd. anchors its supply through captive dairy herds across Hohhot and surrounding processing zones. Glanbia PLC specializes in micronized mineral forms for infant nutrition contracts.
Asia-Pacific cow milk minerals comprise calcium, phosphorus, magnesium, and potassium recovered from whey permeate or milk through electrodialysis, ion exchange, or spray-drying, yielding mineral contents typically exceeding twenty percent by weight for calcium-rich fractions. These concentrates serve primarily as bioavailable fortificants in foods, supplements, and clinical nutrition where solubility and particle size determine formulation compatibility. Calcium dominates product-type value pools due to its dominance in bone-health positioning across supplements and functional foods. Infant nutrition applications command structural premiums owing to stringent mineral-bioavailability requirements and long qualification cycles with brand-loyal buyers.
China's SAMR enforces GB standards on dairy-derived mineral purity and origin labeling, while Japan's MHLW administers FOSHU claims that shape functional-food positioning for milk mineral ingredients. Australia's TGA and New Zealand's MPI jointly govern cross-Tasman therapeutic claims, creating divergent compliance pathways for supplement marketers. Stakeholders must monitor evolving FOSHU claim categories and China's dual carbon goals for dairy processing energy intensity as these frameworks reshape mineral recovery economics and market access conditions.
Market Dynamics
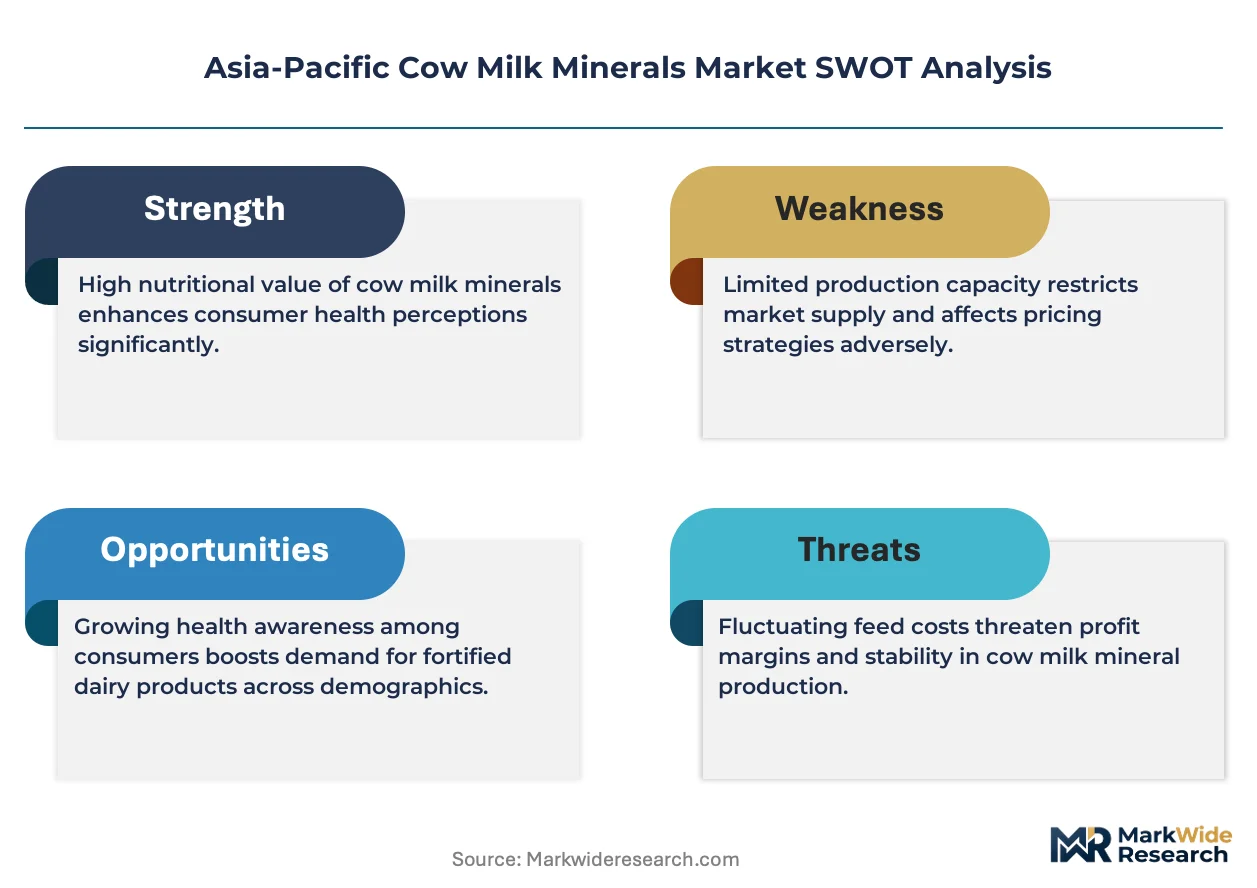
Nutraceutical formulators are redirecting procurement toward functional-ingredient specialists with captive mineral recovery capabilities, compressing traditional dairy processors' share of value-added concentrates. This buyer-side consolidation is reshaping contract structures and qualification timelines across the Asia-Pacific supply base.
Growth Catalysts
- China's dual carbon goals:Energy intensity mandates for dairy processing are accelerating capital deployment into electrodialysis and membrane filtration systems that yield higher-purity mineral fractions with lower thermal input.
- Japan's FOSHU framework expansion:New claim categories for bone-density maintenance are opening functional-food positioning for calcium concentrates in aging-population formulations.
- Infant nutrition contract demand:Micronized mineral specifications for bioavailability are pulling volume toward suppliers with spray-drying capabilities below 50-micron particle control.
Market Restraints
- Whey permeate supply concentration:China's eastern dairy corridor spanning Shandong and Hebei provinces controls over 60% of regional feedstock, creating geographic vulnerability to climate and policy shocks.
- Energy cost volatility:Thermal drying stages in mineral concentrate production expose margins to natural gas and electricity price swings across Australia and New Zealand processing assets.
- Plant-based mineral substitutes:Algae-derived calcium and lithothamnion extracts are capturing share in premium supplement positioning, particularly among flexitarian demographic segments.
Strategic Opportunities
- Southeast Asia underpenetration:Vietnam and Indonesia maintain minimal domestic mineral recovery infrastructure, creating import-dependent markets for established concentrate suppliers.
- Clinical nutrition channel expansion:Hospital and long-term care procurement of enteral formulas with specified mineral profiles represents a direct-sales bypass of retail distribution.
- Australia's TGA therapeutic claim pathway:Osteoporosis prevention positioning for calcium concentrates offers margin expansion unavailable under food-only regulatory classifications.
Industry Challenges
- Electrodialysis membrane qualification cycles:Ion-exchange resin validation for pharmaceutical-grade mineral output extends 18-24 months, freezing supplier-switching decisions.
- Cross-border GB standard harmonization:China's SAMR origin-labeling requirements for dairy-derived ingredients create documentation friction for New Zealand and Australian exporters.
- Specialized process engineering talent:Mineral recovery plant operations require hybrid dairy chemistry and membrane-technology expertise that remains scarce across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cow Milk Minerals Market |
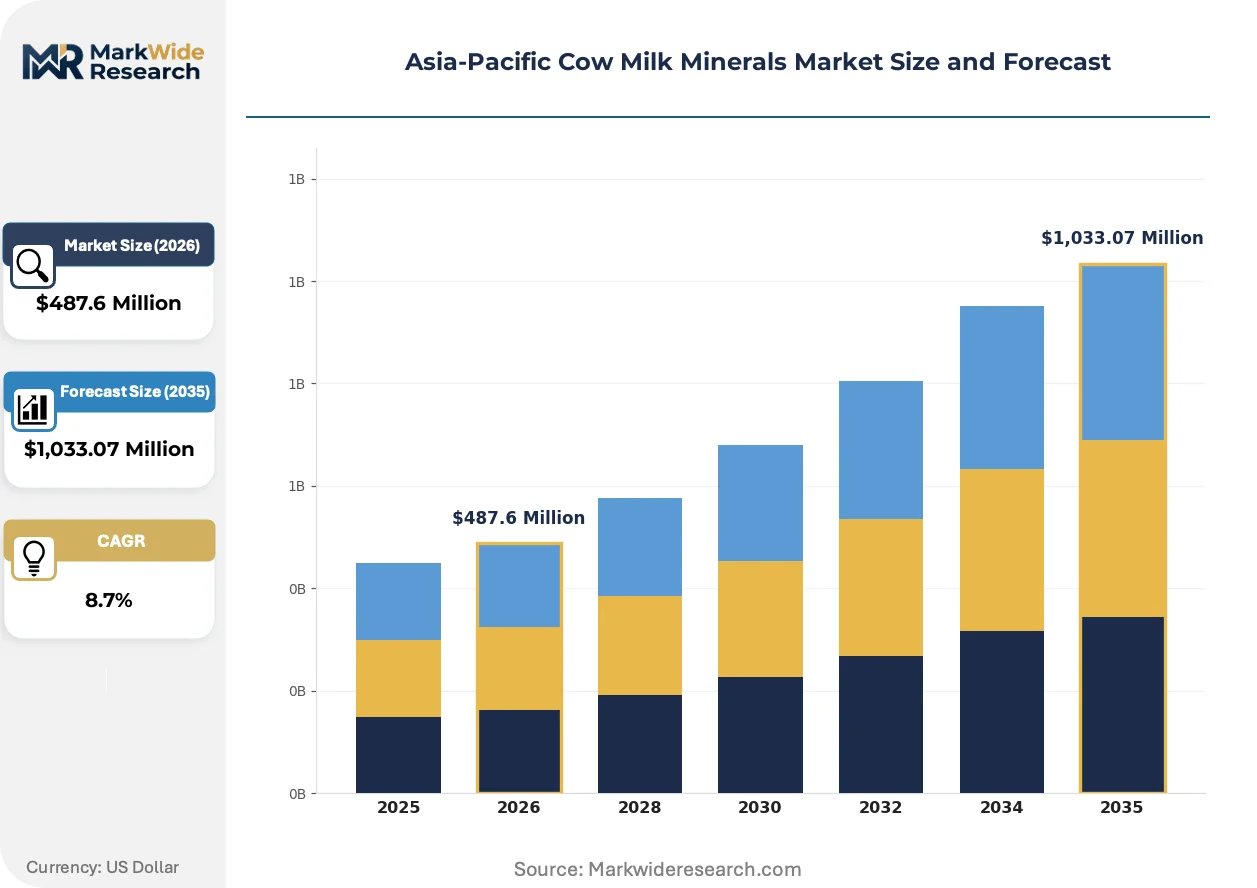
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium, Phosphorus, Magnesium, Potassium End User: Dairy Manufacturers, Food Industry, Nutraceutical Companies, Pharmaceuticals Application: Fortification, Supplements, Functional Foods, Infant Nutrition Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | China Mengniu Dairy Company Limited, Inner Mongolia Yili Industrial Group Co., Ltd., Nestlé SA, FrieslandCampina, Fonterra Co-operative Group Limited, Gujarat Cooperative Milk Marketing Federation Ltd. (Amul), Glanbia PLC, Arla Foods, Meiji Holdings Company, Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cow Milk Minerals Market Strategic Shifts
Mineral recovery technology is converging with precision nutrition formulation requirements, compressing particle size specifications and bioavailability testing protocols simultaneously. This technical escalation is filtering supplier capabilities and contract qualification barriers.
Electrodialysis coupled with nanofiltration is displacing conventional ion-exchange chromatography in calcium concentrate production for infant nutrition contracts. Japanese and Australian formulators are adopting these integrated membrane trains to achieve sub-10-micron particle distributions without secondary milling. The shift is compressing capital intensity differentials between large-scale dairy processors and specialized mineral recovery operators.
China's SAMR has tightened GB 19644 enforcement on dairy-derived ingredient origin labeling and purity thresholds for heavy metal content. The regulation is forcing exporters to install dedicated processing lines segregated from standard dairy commodity flows. Infant nutrition manufacturers are responding by consolidating supplier bases to those with certified segregated capacity.
Direct procurement relationships between nutraceutical brand owners and mineral concentrate specialists are shortening traditional dairy processor intermediation. Formulators in China's eastern provinces now negotiate specification contracts directly with New Zealand and Australian recovery operators, bypassing regional trading houses. This channel compression is most visible in bone-health supplement launches targeting China's aging coastal urban populations.
Asia-Pacific Cow Milk Minerals Market Segmentation
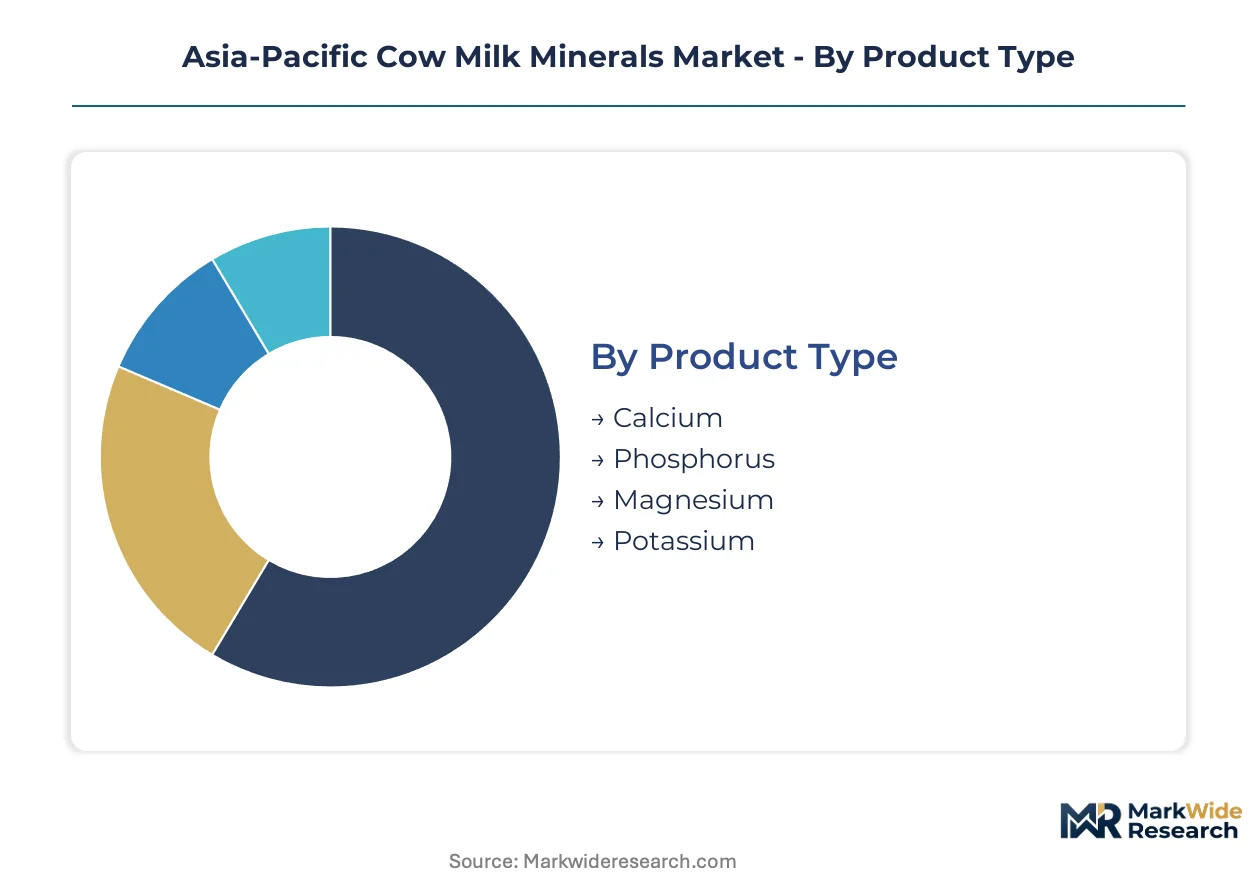
Segmentation in the Asia-Pacific Cow Milk Minerals Market reveals how regulatory frameworks and formulation requirements fragment demand across mineral types and end-use channels. Buyers prioritize bioavailability specifications and purity certifications that vary sharply by application, creating distinct procurement pools with limited supplier overlap.
Product Type:
China's SAMR enforces divergent purity thresholds across mineral categories, with calcium concentrates facing the strictest heavy metal limits under GB 19644 amendments.
- Calcium:Dominates concentrate production through electrodialysis recovery from whey permeate, yielding bioavailable fractions exceeding 20% mineral content by weight. Demand concentrates in infant nutrition contracts across China's eastern dairy corridor, where sub-10-micron particle specifications command structural premiums due to stringent bioavailability requirements and 18-24 month qualification cycles.
- Phosphorus:Recovered as calcium-phosphate complexes through ion-exchange chromatography, serving clinical nutrition formulations where mineral ratios must match physiological profiles. Japanese FOSHU bone-density claims are pulling volume toward phosphorus-enriched concentrates for aging-population functional foods, particularly in coastal urban markets with direct procurement relationships to Australian recovery operators.
- Magnesium:Micronized forms serve sports nutrition and stress-management positioning in Australian and New Zealand supplement markets.
- Potassium:Limited recovery volumes target electrolyte replacement formulations and medical foods with specified mineral balances.
Established volume favors calcium; emerging adoption favors phosphorus.
End User:
Customer-type concentration is accelerating as nutraceutical formulators bypass traditional dairy processors to contract directly with specialized mineral recovery operators.
- Nutraceutical Companies:Redrawing procurement patterns toward functional-ingredient specialists with captive electrodialysis and spray-drying capabilities below 50-micron particle control. China's eastern provinces now see direct specification contracts with New Zealand and Australian recovery operators, compressing regional trading house intermediation for bone-health supplement launches.
- Infant Nutrition Manufacturers:Consolidating supplier bases to certified segregated processing lines under tightened GB 19644 enforcement, requiring dedicated capacity separated from standard dairy commodity flows.
- Food Industry:Fortification demand in processed dairy and bakery applications maintains steady offtake through established dairy processor relationships.
- Pharmaceuticals:TGA therapeutic claim pathways in Australia offer margin expansion for osteoporosis prevention positioning unavailable under food-only classifications.
- Dairy Manufacturers:Losing share of value-added concentrates as buyers redirect toward mineral recovery specialists with hybrid dairy chemistry and membrane-technology expertise.
Direct procurement favors nutraceutical specialists; qualification inertia favors infant nutrition incumbents.
Application:
Application-level differentiation hinges on particle size specifications and bioavailability testing protocols that filter supplier capabilities unevenly.
- Infant Nutrition:Micronized mineral specifications with sub-10-micron particle distributions are climbing the fastest, driven by spray-drying capabilities and long qualification cycles with brand-loyal buyers in China and Japan.
- Supplements:Bone-health positioning dominates China's aging coastal urban populations, with direct brand-owner-to-recovery-operator contracts shortening traditional intermediation.
- Functional Foods:Japan's FOSHU framework expansion for bone-density maintenance is opening new claim categories for calcium concentrates in aging-population formulations.
- Fortification:Standard dairy and bakery applications face substitution pressure from algae-derived calcium and lithothamnion extracts in premium supplement positioning.
Technical escalation favors infant nutrition; claim differentiation favors functional foods.
Distribution Channel:
Channel configuration reflects the divergence between retail-accessible supplements and specification-driven direct sales for clinical and infant nutrition applications.
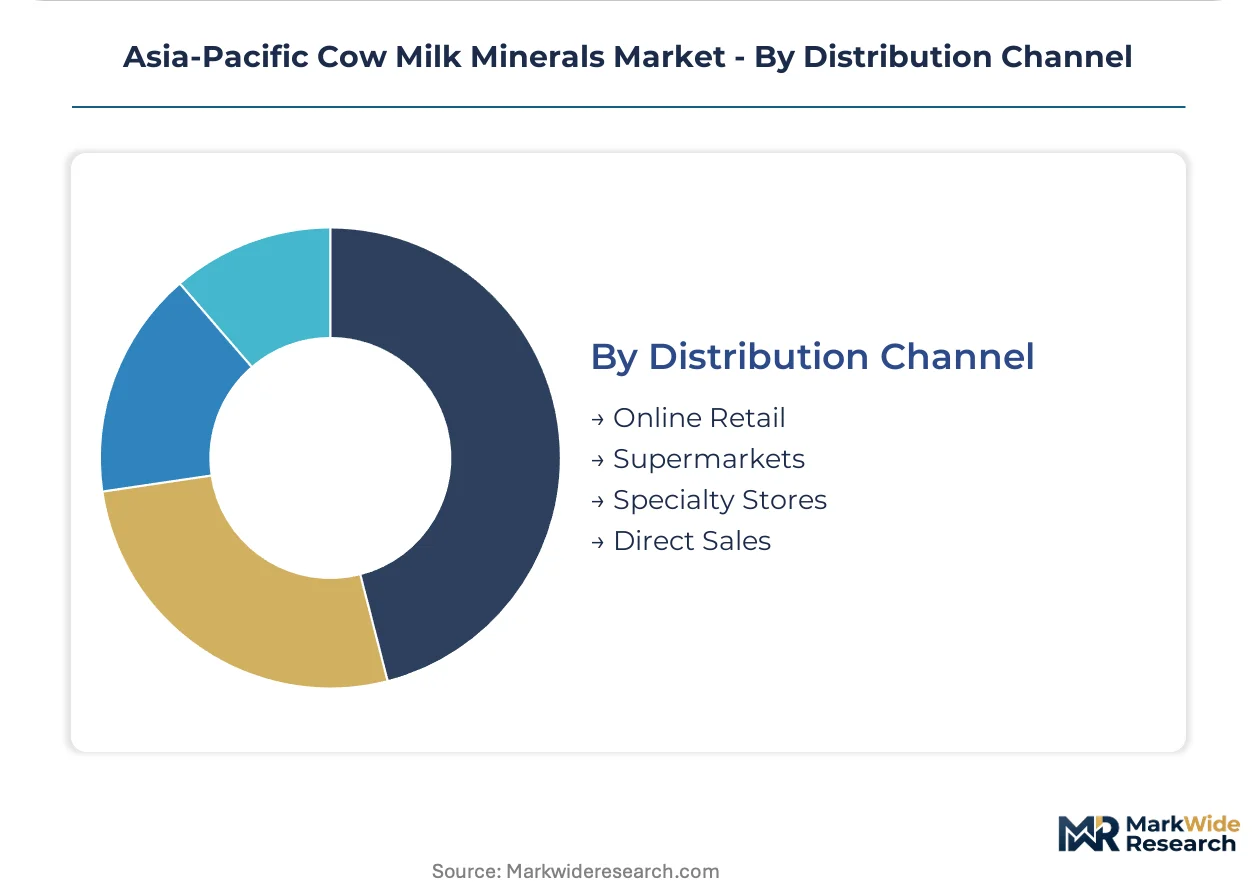
- Direct Sales:Hospital and long-term care procurement of enteral formulas with specified mineral profiles represents a bypass of retail distribution, particularly in Australia's clinical nutrition channel expansion.
- Online Retail:China's eastern provinces see compressed channel structures as nutraceutical brand owners negotiate directly with recovery operators, displacing regional trading houses.
- Specialty Stores:Premium supplement positioning in Japan and Australia serves flexitarian demographic segments seeking bone-health formulations.
- Supermarkets:Mass-market fortification products face margin pressure from energy cost volatility in thermal drying stages.
Specification contracts favor direct sales; consumer accessibility favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand mineral concentrate exports flow predominantly into China's eastern dairy processing corridor, establishing a trade-flow corridor that anchors regional supply security and pricing benchmarks across the Asia-Pacific.
China
China's SAMR enforces GB 19644 standards on dairy-derived mineral purity and origin labeling, tightening heavy metal thresholds for calcium concentrates. The eastern dairy corridor spanning Shandong and Hebei provinces controls over sixty percent of regional whey permeate feedstock, with direct procurement relationships now bypassing traditional trading houses for bone-health supplement launches.
Japan
Japan's MHLW administers FOSHU framework expansion for bone-density maintenance claims, opening functional-food positioning for calcium and phosphorus concentrates in aging-population formulations. METI coordinates with industry on claim category updates. Coastal urban markets in Kanto and Kansai regions see direct specification contracts with Australian recovery operators for micronized mineral inputs.
Australia
Australia's TGA therapeutic claim pathway offers margin expansion for osteoporosis prevention positioning unavailable under food-only classifications. Energy cost volatility in thermal drying stages exposes processing margins to natural gas price swings. Victoria and New South Wales host spray-drying assets serving clinical nutrition channel expansion into hospital and long-term care procurement.
New Zealand
New Zealand's MPI governs cross-Tasman therapeutic claims alongside Australia's TGA, creating divergent compliance pathways for supplement marketers. Fonterra Co-operative Group Limited leverages grass-fed sourcing to command premium positioning in calcium concentrates. Canterbury processing zones anchor mineral recovery infrastructure with electrodialysis and membrane filtration systems.
India
India's FSSAI regulates dairy-derived ingredient standards for domestic fortification applications, though mineral concentrate recovery infrastructure remains underdeveloped relative to fluid milk processing. Gujarat Cooperative Milk Marketing Federation Ltd. (Amul) anchors supply through cooperative dairy networks. Maharashtra and Karnataka dairy belts show emerging demand for bioavailable fortificants in processed foods.
Asia-Pacific Cow Milk Minerals Market Competitive Environment
Player mix skews toward integrated dairy cooperatives and specialized mineral recovery operators with captive electrodialysis capabilities. Market structure concentrates around three strategic archetypes: grass-fed premium-positioned exporters, domestic dairy giants with captive herd supply, and micronization specialists serving infant nutrition contracts. Competitive moves center on backward integration into whey permeate supply and qualification cycle acceleration through dedicated segregated processing lines.
Among Asia-Pacific-based dairy giants, Inner Mongolia Yili Industrial Group Co., Ltd. and China Mengniu Dairy Company Limited occupy positions anchored by captive dairy herds across Hohhot and surrounding processing zones. Fonterra Co-operative Group Limited exemplifies the grass-fed premium archetype with New Zealand-origin supply chains. Glanbia PLC sits within the micronization specialist tier, representing suppliers with spray-drying capabilities below fifty-micron particle control for infant nutrition contracts.
| Leading Market Players |
|---|
| China Mengniu Dairy Company Limited |
| Inner Mongolia Yili Industrial Group Co., Ltd. |
| Nestlé SA |
| FrieslandCampina |
| Fonterra Co-operative Group Limited |
| Gujarat Cooperative Milk Marketing Federation Ltd. (Amul) |
| Glanbia PLC |
| Arla Foods |
| Meiji Holdings Company, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Electrodialysis membrane capacity utilization above eighty percent across New Zealand's Canterbury processing zones creates scale economies that compress unit costs for calcium concentrates while establishing price floors for micronized grades. China's SAMR-mandated segregated processing lines under GB 19644 enforcement absorb capital intensity that feeds into premium tier spreads, concentrating margin leverage among operators with certified dedicated capacity.
Pricing Analysis
Prior-generation ion-exchange chromatography systems trade at thirty to forty percent discounts to integrated electrodialysis-nanofiltration trains, while next-generation sub-10-micron spray-drying assets command qualification-linked premiums from infant nutrition manufacturers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade mineral concentrates stratifies by heavy metal thresholds and particle size certification. Cost compression in standard food-grade calcium runs through energy cost volatility in thermal drying stages, particularly across Australian natural gas-exposed assets. Dairy manufacturers exhibit highest price sensitivity as procurement shifts toward functional-ingredient specialists, while infant nutrition contract buyers accept structural premiums for micronized specifications.
Supply Chain Analysis
Port congestion across Shanghai-Ningbo and Sydney container gateways elevates inbound logistics costs for ion-exchange resin and electrodialysis membrane replacements sourced from European and North American suppliers. Mineral concentrate production draws from whey permeate feedstock concentrated in New Zealand, Australia's Victoria dairy belt, and China's eastern Shandong-Hebei corridor. Single-source vulnerability concentrates in membrane filtration equipment qualified for pharmaceutical-grade output, where eighteen-to-twenty-four-month validation cycles freeze supplier switching. Distribution runs through direct specification contracts between nutraceutical brand owners and recovery operators, compressing traditional dairy processor intermediation across China's eastern provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs mineral concentrate procurement as direct brand-owner-to-recovery-operator contracts displace layered trading structures, with interoperability across FOSHU claim pathways and GB 19644 certification regimes determining ecosystem access.
For Market Incumbents: Fortify captive whey permeate supply through backward integration into cooperative dairy networks across Hohhot and Canterbury processing zones, while accelerating dedicated segregated line certification under tightened SAMR enforcement to defend against mineral recovery specialists capturing infant nutrition contract volume. For New Entrants and Emerging Players: GB 19644 fast-track certification for pharmaceutical-grade mineral output opens white-space access in China's clinical nutrition channel and Japan's FOSHU bone-density claim formulations, with Southeast Asian import-dependent markets in Vietnam and Indonesia offering lowest competitive density for established specification capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among micronization specialists with sub-50-micron particle control serving long-qualification-cycle infant nutrition contracts, suggesting five-to-ten-year viability for operators with hybrid dairy chemistry and membrane-technology talent pipelines; monitor FOSHU claim category expansion and China's dual carbon enforcement intensity as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Permeate Supply | Captive feedstock secures margin control against Shandong-Hebei supply concentration risk. |
| GB 19644 Segregated Line Certification | SAMR-compliant dedicated capacity unlocks infant nutrition contract access with structural premiums. |
| Electrodialysis-Nanofiltration Technology Upgrade | Integrated membrane trains achieve sub-10-micron particle distributions without secondary milling. |
| Direct Procurement Relationship Establishment | Bypass of regional trading houses captures margin from China's coastal nutraceutical brand owners. |
| FOSHU Claim Pathway Investment | MHLW bone-density maintenance authorization opens aging-population functional food positioning. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, FOSHU claim registration databases, and customs trade records for whey permeate and mineral concentrate flows. Interviews with mineral recovery plant managers, nutraceutical formulation scientists, infant nutrition procurement leads, and dairy cooperative supply planners combined with analysis of MPI-TGA cross-Tasman therapeutic claim guidelines and Fonterra sustainability disclosures. Bottom-up capacity utilization models triangulated against top-down demand projections from fortification and supplement consumption data.
Segmentation dimensions modeled include mineral type, particle size grade, end-use application, and regulatory certification tier across the projection horizon. CAGRs derived from growth rate reconciliation between feedstock availability constraints and formulation demand elasticity, with infant nutrition contract volumes and clinical nutrition channel expansion serving as primary forecast inputs alongside energy cost trajectory assumptions for thermal drying stages.
Underlying assumptions cover sustained GB 19644 enforcement intensity, stable FOSHU claim category expansion, and continued whey permeate supply concentration in the eastern dairy corridor, with deviation risk concentrated in membrane technology substitution rates and plant-based mineral substitute adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Non-Fat Milk Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Canada Dairy Market
Dairy Products
Butter Concentrate Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
South America Yogurt Market
Dairy Products
Blue Cheese Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
GCC Dairy Market
Dairy Products
Japan Dairy Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Smoked Cheese Market
Dairy Products
Condensed Whey Market