
 Fermented Plant Protein Market | 2026-2036
Fermented Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Plant Protein Market Analytics
Single-serve protein sachets and modular flavor pods is restructuring how home consumers and health food stores evaluate fermented plant proteins. DuPont leverages its microbial strain libraries to anchor supply security for industrial buyers. Cargill competes through backward integration into North American pea protein cultivation. Chr. Hansen specializes in fermentation culture development, positioning its portfolio toward clean-label nutritional supplements.
Fermented plant protein denotes protein isolates or concentrates derived from leguminous or cereal substrates that have undergone controlled microbial fermentation to improve amino acid bioavailability, digestibility, and sensory profile; the process typically employs Lactobacillus or Rhizopus species at temperatures between 30°C and 37°C to reduce antinutritional factors while generating bioactive peptides for human nutrition and animal feed applications. Tofu and tempeh dominate mature retail channels with established margin pools, while pea-derived fermented isolates represent the fastest-growing ingredient source as food manufacturers reformulate away from allergen-heavy soybases. Nutritional supplements command premium positioning relative to commodity animal feed applications, where price sensitivity limits value capture.
The FDA governs protein content claims and GRAS notifications for novel fermentation outputs in the United States, while the EMA and EFSA jointly influence novel food approvals and health claim substantiation across European jurisdictions. These frameworks compel manufacturers to invest in clinical validation and supply chain traceability before market entry. Stakeholders must monitor evolving strain approval pathways and carbon labeling requirements that will determine which fermentation platforms achieve commercial scale.
Market Dynamics
The FDA's updated plant protein labeling guidelines are compressing formulation timelines as manufacturers race to substantiate amino acid bioavailability claims before enforcement windows tighten.
Growth Catalysts
- Precision fermentation infrastructure:German facilities serving Central European food manufacturers are scaling Rhizopus-based production platforms, reducing antinutritional factors in soy substrates below detectable thresholds.
- Sports nutrition procurement:Athletic performance brands now specify fermented pea and soy isolates in ingredient tenders, creating dedicated demand streams separate from commodity protein markets.
- EU Green Deal alignment:Carbon labeling requirements under the EU Green Deal are favoring microbial fermentation pathways over thermal processing for protein concentrate production.
Market Restraints
- Input cost volatility:North American yellow pea prices fluctuate with drought cycles in the Canadian prairies, compressing margins for isolate producers without captive cultivation contracts.
- Regulatory friction:EFSA novel food approval pathways for new microbial strains extend commercialization timelines by 18-36 months beyond US GRAS notification windows.
- Substitution threat:Cultivated animal proteins and precision-fermented dairy isolates are capturing shelf space in premium nutrition channels where fermented plant proteins previously dominated.
Strategic Opportunities
- Underpenetrated feed applications:Brazilian aquaculture operations remain reliant on fishmeal, creating entry points for fermented soy protein concentrates with documented digestibility improvements.
- Regulatory tailwind:India's PLI scheme for food processing incentivizes domestic fermentation capacity for export-oriented plant protein manufacturing.
- Technology convergence:CRISPR-edited Lactobacillus strains combined with continuous bioreactor designs are expanding into industrial-scale peptide production for medical nutrition applications.
Industry Challenges
- Strain bank access:Proprietary microbial libraries at legacy ingredient houses restrict independent developers from optimizing fermentation protocols for novel substrates.
- Clinical validation timelines:Human bioavailability studies required for EFSA health claims consume 40% of pre-revenue R&D budgets for clean-label supplement entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Plant Protein Market |
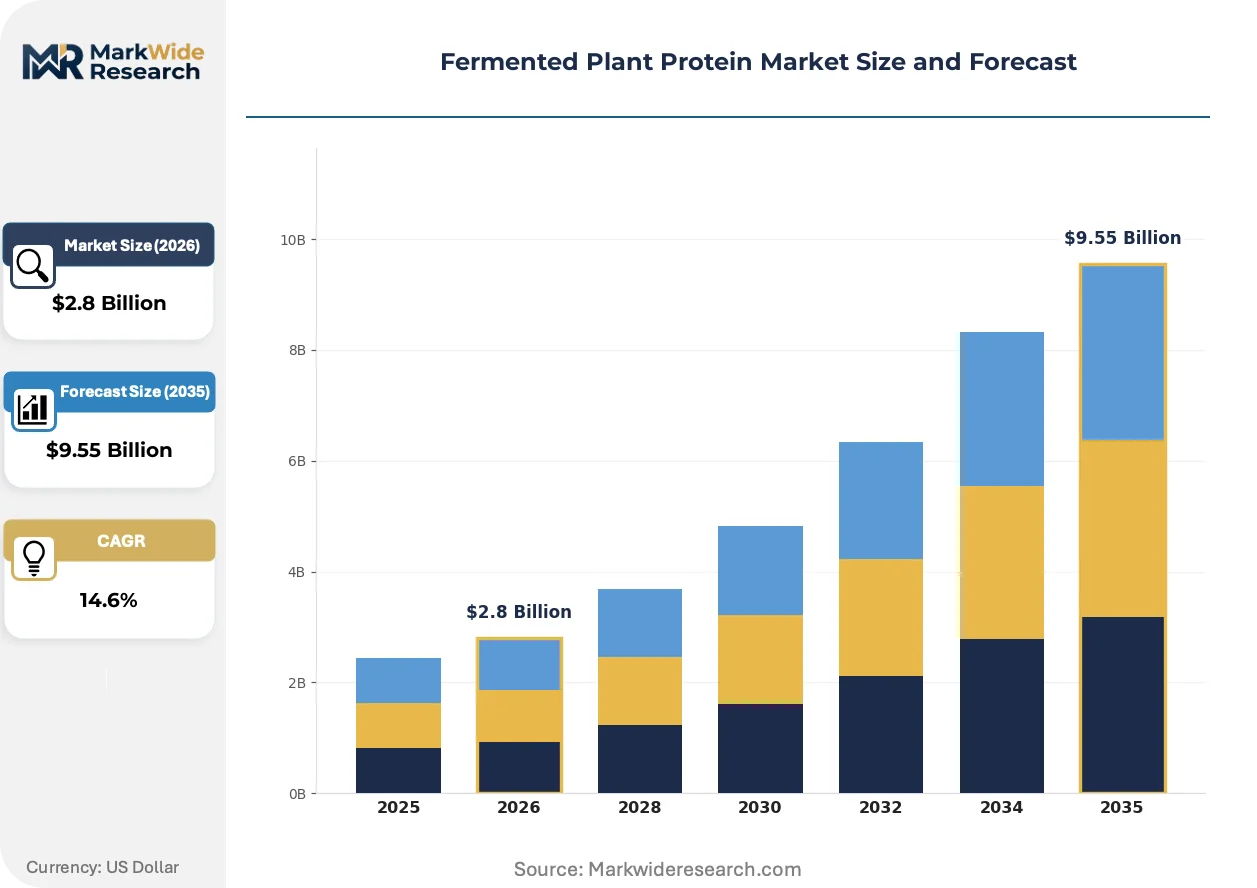
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Miso End User: Restaurants, Food Manufacturers, Health Food Stores, Home Consumers Application: Food & Beverage, Nutritional Supplements, Animal Feed, Personal Care Products Ingredient Source: Soybeans, Peas, Lentils, Chickpeas |
| Companies Covered | Ajinomoto, DuPont, Chr. Hansen, Cargill, BASF, Ingredion, Genuine Health, FIT-BioCeuticals, Sotru, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Plant Protein Market Evolving Landscape
Controlled microbial fermentation is migrating from artisan food production into industrial ingredient manufacturing, with strain engineering and bioprocess automation converging to reshape protein economics.
Precision fermentation platforms employing CRISPR-edited Rhizopus oligosporus are expanding into high-volume contract manufacturing for sports nutrition brands. These engineered strains reduce fermentation cycle times from 48 to 32 hours while elevating free amino acid content in pea protein isolates. The technology is expanding into pharmaceutical-grade peptide production, compressing the historical boundary between food and medical nutrition supply chains.
The EU's CSRD disclosure requirements now mandate Scope 3 emissions reporting for ingredient suppliers, forcing fermentation facilities to document energy inputs per kilogram of protein output. This regulatory pressure is accelerating adoption of renewable-powered bioreactors in Central European production clusters. Supplement manufacturers sourcing from these facilities are restructuring supplier scorecards to prioritize verified carbon intensity over unit pricing.
Home consumers are fragmenting bulk protein purchases into single-serve sachets paired with modular flavor pods, shifting volume concentration from institutional foodservice toward direct-to-subscription channels. Health food stores are responding by dedicating shelf space to fermented protein tasting stations where buyers customize isolate blends. This behavioral shift is most visible in German and Dutch urban markets where precision fermentation brands maintain direct retail relationships.
Fermented Plant Protein Market Segmentation
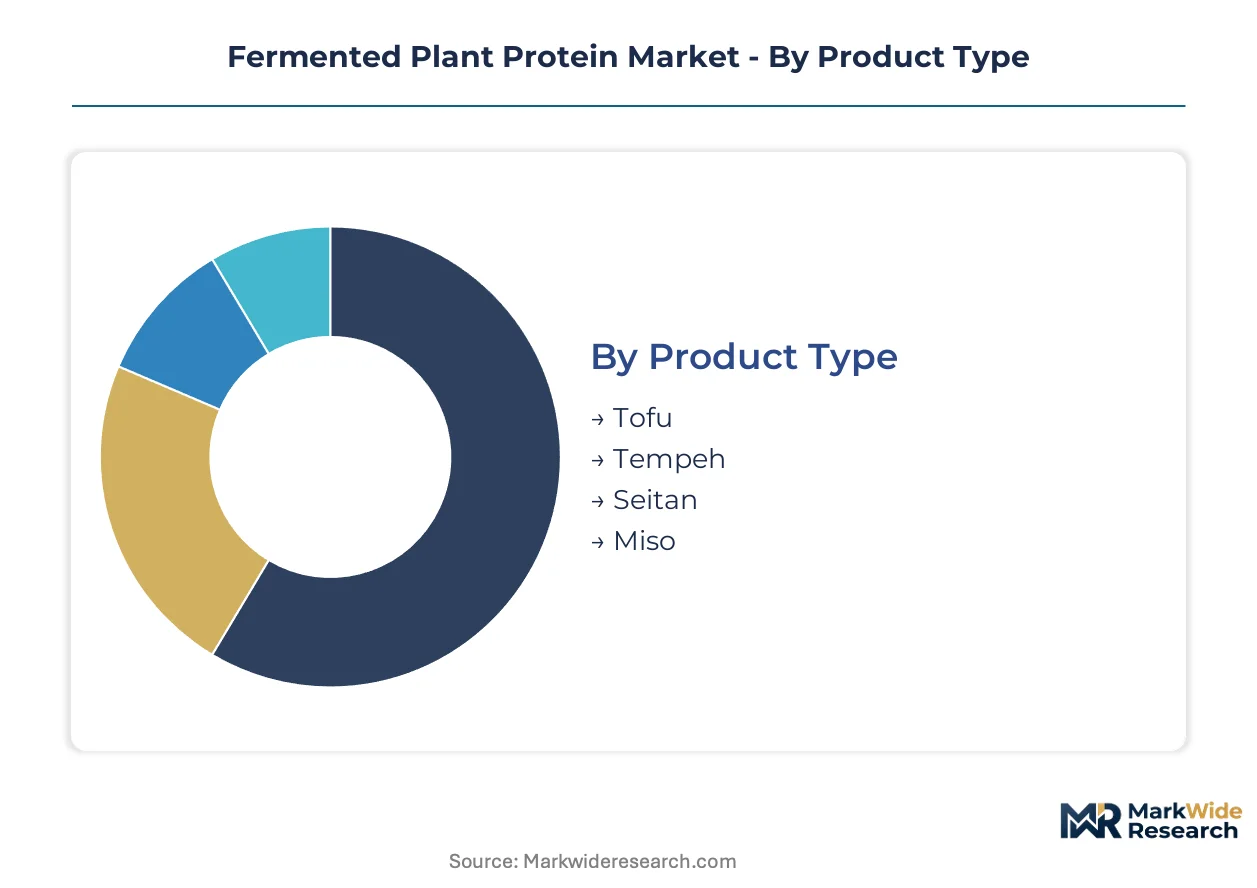
Fermented plant protein markets fragment across traditional food formats and industrial ingredient streams, with each segment carrying distinct margin profiles and regulatory requirements. Understanding these divisions reveals where formulation investments concentrate versus where commodity pressures dominate.
Product Type:
Upgrade cycles in this category track shifting consumer sophistication from whole-food formats toward isolate-based applications with enhanced bioavailability claims.
- Tofu:Coagulated soy protein with established production infrastructure across East Asian and North American manufacturing bases. Restaurant procurement in Japan and South Korea maintains steady volume, though home consumer substitution toward tempeh is compressing retail margin expansion.
- Tempeh:Whole soybean fermentation using Rhizopus oligosporus delivers superior amino acid completeness and fiber retention compared to tofu. German health food stores and Dutch direct-to-consumer channels are driving the steepest demand climb as clean-label positioning displaces conventional meat alternatives.
- Seitan:Wheat gluten isolate with minimal fermentation depth; concentrated in North American vegetarian foodservice where texture mimics poultry applications.
- Miso:Long-fermented soybean paste dominated by Japanese artisan producers; premium positioning in Western markets limits volume scale despite high unit economics.
Volume placements concentrate in tofu; the faster expansion belongs to tempeh.
End User:
Customer type determines specification intensity, with industrial buyers demanding batch consistency while retail channels prioritize storytelling and format innovation.
- Restaurants:Foodservice operators specify fermented proteins for menu differentiation, particularly in California and New York metropolitan clusters where plant-forward positioning commands price premiums.
- Food Manufacturers:Industrial buyers drive ingredient standardization, with German and Dutch facilities requiring documented antinutritional factor reduction below EFSA thresholds for novel food applications.
- Health Food Stores:Curated retail environments in German urban centers are expanding single-serve sachet assortments with modular flavor customization.
- Home Consumers:Direct subscription channels fragment bulk purchases into personalized isolate blends, with Dutch and Belgian markets showing highest trial rates for precision fermentation brands.
Procurement scale tilts toward food manufacturers; health food stores are gaining share fastest.
Application:
Application segments separate by clinical validation burden, with nutritional supplements requiring human bioavailability studies that commodity food applications bypass.
- Food & Beverage:Mature incorporation into meat alternatives and dairy replacements; FDA GRAS notifications for novel fermentation outputs compress formulation timelines as enforcement windows tighten.
- Nutritional Supplements:Premium positioning with 40% of pre-revenue R&D budgets consumed by EFSA health claim substantiation; sports nutrition brands in Germany and the United States now specify fermented isolates in dedicated ingredient tenders.
- Animal Feed:Price-sensitive commodity segment where Brazilian aquaculture operations present entry points for fermented soy concentrates with documented digestibility improvements over fishmeal.
- Personal Care Products:Niche peptide applications in cosmetic formulations; limited volume relative to nutrition channels.
Revenue concentration sits in food and beverage; nutritional supplements are climbing the fastest.
Ingredient Source:
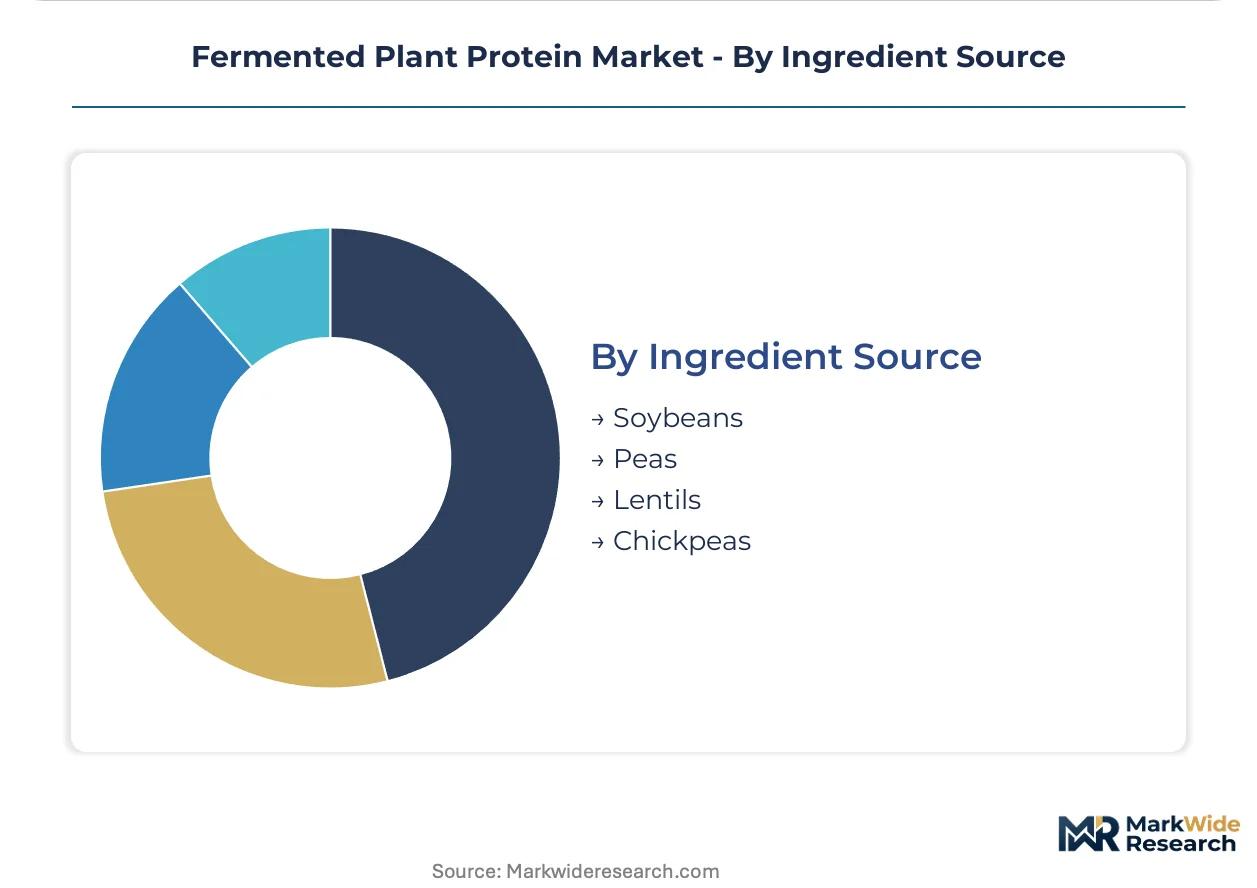
Raw material selection determines antinutritional factor profiles and supply security, with pea cultivation expanding fastest as soy allergen concerns reshape formulation strategies.
- Soybeans:Dominant substrate with established Rhizopus fermentation protocols; Canadian prairie drought cycles introduce input cost volatility for isolate producers lacking captive cultivation contracts.
- Peas:Yellow pea protein isolates represent the steepest expansion trajectory as manufacturers reformulate away from allergen-heavy soybases. North American backward integration into pea cultivation is securing supply for industrial buyers.
- Lentils:Emerging substrate with limited commercial scale; Indian PLI scheme incentives may accelerate domestic fermentation capacity for export-oriented manufacturing.
- Chickpeas:Mediterranean and Middle Eastern sourcing bases; sensory profile challenges limit adoption outside ethnic food applications.
Supply security anchors in soybeans; pea-derived isolates are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and the United States while consumption growth accelerates across Asian and Latin American markets. Supply security debates now center on which regions can scale precision fermentation infrastructure fastest. Regulatory divergence between FDA and EFSA pathways is fragmenting commercialization timelines.
United States
Sports nutrition brands in California and New York metropolitan clusters drive procurement of fermented pea and soy isolates. The FDA governs protein content claims and GRAS notifications for novel fermentation outputs, compressing formulation timelines as enforcement windows tighten. DuPont leverages its microbial strain libraries to anchor supply security for industrial buyers across the Midwest.
Germany
Precision fermentation facilities serving Central European food manufacturers are scaling Rhizopus-based production platforms. The EU Green Deal's carbon labeling requirements favor microbial fermentation pathways over thermal processing for protein concentrate production. Dutch and Belgian direct-to-consumer channels are fragmenting bulk purchases into single-serve sachets with modular flavor customization.
India
Domestic fermentation capacity for export-oriented plant protein manufacturing is accelerating under the PLI scheme for food processing. The FSSAI regulates novel food approvals with shorter windows than EFSA, attracting contract manufacturing investment. Maharashtra and Gujarat industrial corridors are integrating backward into yellow pea cultivation to secure isolate supply.
Brazil
Aquaculture operations remain reliant on fishmeal, creating entry points for fermented soy protein concentrates with documented digestibility improvements. The country's national food safety regulator evaluates novel fermentation outputs for animal feed applications. São Paulo and Paraná agricultural clusters are piloting substrate diversification into lentils for export-oriented manufacturing.
China
Industrial buyers are reformulating meat alternatives away from allergen-heavy soybases toward pea-derived isolates. The SAMR governs novel food approvals with streamlined pathways for fermentation-derived ingredients. Yangtze River Delta bioprocessing hubs are adopting continuous bioreactor designs for pharmaceutical-grade peptide production.
Fermented Plant Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. The market structure tilts toward consolidation at the ingredient supply level while fragmenting across finished product channels. Strategic archetypes include microbial library custodians, backward-integrated cultivators, and fermentation culture specialists. Dominant competitive moves center on captive supply contracts and strain licensing arrangements rather than direct product rivalry.
Within the microbial library tier, DuPont and Chr. Hansen occupy positions as anchors for industrial fermentation protocols. Cargill exemplifies the backward-integrated archetype through upstream control over North American pea protein cultivation. Among Asia-Pacific headquartered conglomerates, Ajinomoto represents diversified fermentation expertise spanning food and pharmaceutical applications.
| Leading Market Players |
|---|
| Ajinomoto |
| DuPont |
| Chr. Hansen |
| Cargill |
| BASF |
| Ingredion |
| Genuine Health |
| FIT-BioCeuticals |
| Sotru |
| Others |
Value Network & Pricing Analysis
Precision fermentation platform migration from batch to continuous bioreactor designs is compressing unit production costs while concentrating supply ownership among strain library custodians in Germany and the United States. This technological transition simultaneously elevates capital barriers for new entrants and transfers pricing power toward integrated producers with captive microbial collections.
Pricing Analysis
Margin tightening in nutritional supplement tiers reflects EFSA health claim substantiation costs consuming 40% of pre-revenue R&D budgets. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade peptide isolates from commodity food concentrates and animal feed proteins. Pricing pressure stems from Canadian prairie drought cycles introducing input cost volatility for pea protein isolate producers lacking backward integration into cultivation. Animal feed applications exhibit highest price sensitivity due to fishmeal substitution economics, while medical nutrition buyers absorb premiums for documented bioavailability.
Supply Chain Analysis
EU Green Deal carbon labeling requirements now mandate third-party verification for fermentation facilities supplying Central European food manufacturers. Production gravity centers on Germany, the United States, and India, with Maharashtra and Gujarat industrial corridors integrating backward into yellow pea cultivation. Raw material flows draw from North American prairie pea cultivation, Brazilian soy agricultural clusters, and emerging lentil substrates piloted in São Paulo. Single-source vulnerability concentrates in proprietary microbial strain libraries at legacy ingredient houses. Distribution runs through direct-to-subscription channels for precision fermentation brands and institutional offtake contracts for commodity isolates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermented plant protein supply is tightening around precision fermentation capacity bottlenecks in Germany and the United States, with strain engineering expertise propping isolate pricing premiums above commodity protein alternatives.
For Market Incumbents: Anchor supply security through exclusive strain licensing arrangements with German precision fermentation facilities and captive cultivation contracts insulating against Canadian prairie drought volatility. Defend market position by accelerating CRISPR-edited Rhizopus strain development ahead of EFSA novel food approval windows tightening for competitor submissions. Prioritize backward integration into North American pea protein cultivation to compress input cost exposure. For New Entrants and Emerging Players: CRISPR-edited Lactobacillus strains for pharmaceutical-grade peptide production offer the most penetrable technology wedge against established food-grade isolate producers. Target Brazilian aquaculture feed applications where fishmeal substitution creates white-space demand without EFSA health claim validation burdens. Pursue contract manufacturing partnerships with Indian PLI scheme beneficiaries to bypass capital-intensive fermentation infrastructure buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified ingredient conglomerates seeking microbial library depth and precision fermentation capacity. Long-term viability hinges on regulatory navigation capabilities across FDA GRAS and EFSA novel food pathways rather than unit cost optimization alone. Monitor EFSA strain approval velocity as the critical inflection signal distinguishing scalable fermentation platforms from stranded R&D investments.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Expansion | DuPont's microbial collections anchor supply security for industrial fermentation protocols across Midwest manufacturing bases. |
| Backward Integration | Cargill's upstream control over North American pea cultivation compresses input cost volatility for isolate producers. |
| Regulatory Approval Pathway | EFSA novel food submissions for CRISPR-edited Rhizopus strains extend commercialization timelines 18-36 months beyond FDA windows. |
| Carbon Certification Program | EU Green Deal Scope 3 disclosure mandates force fermentation facilities to document renewable energy inputs per kilogram output. |
| Direct-to-Consumer Launch | Single-serve sachet assortments with modular flavor pods fragment German and Dutch retail channels away from bulk institutional sales. |
Research Methodology
Independent corroboration across fermentation facility operators, sports nutrition brand procurement directors, and regulatory affairs specialists at EFSA and FDA underwrites the qualitative findings in this study. Primary interviews with strain engineering scientists, contract manufacturing executives, and health food store category buyers combined with secondary validation from FDA GRAS notifications, EFSA novel food registers, and EU Green Deal implementation guidance. Bottom-up volume triangulation across ingredient source, application, and end-user segments intersects with top-down macroeconomic calibration.
Rate-of-change decomposition across the projection horizon isolates volume drivers from pricing dynamics and mix shifts. Segmentation dimensions modeled include product type, ingredient source, application, and end-user archetype alongside fermentation technology tier. CAGRs were derived from logistic diffusion curves fitted to adoption data across German precision fermentation facilities and North American sports nutrition procurement patterns. Industry-specific inputs incorporate EFSA approval velocity assumptions and Canadian prairie precipitation indices affecting pea cultivation yields.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA strain approval pathway revisions or sustained drought cycles in North American pea cultivation regions. Model assumptions reflect documented regulatory frameworks and disclosed facility capacity expansions. A model refresh is warranted upon material change in EU carbon labeling enforcement intensity or FDA GRAS notification processing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Germany Soy Protein Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Vegan Steak Market