
 Butter Fat Fraction Market | 2026-2036
Butter Fat Fraction Market Size, Share, and Industry Trends Forecast 2026-2036
Butter Fat Fraction Market Analytics
Asset-light toll processing and third-party fractionation leasing is rewriting capital requirements for mid-sized dairy processors entering the butter fat fraction space. Fonterra Co-operative Group Limited leverages its New Zealand milk pool to sustain year-round fractionation capacity. Royal FrieslandCampina anchors European supply through integrated Dutch cooperative infrastructure. Arla Foods competes via specialized organic butter fat fraction streams for premium bakery accounts.
Butter fat fraction denotes the separation of milk fat into distinct components—typically anhydrous milk fat, butter oil, and specific melting-point fractions—via controlled crystallization or solvent-free dry fractionation to achieve precise functional properties for industrial food manufacturing. The process yields fractions with tailored melting profiles between 10°C and 40°C, enabling confectionery manufacturers to optimize mouthfeel and shelf stability without hydrogenation. Conventional butter fraction dominates volume through established bakery supply contracts, while cultured butter fractions command margin concentration in European artisanal channels. Powdered forms are accelerating fastest, driven by extended shelf-life requirements in snack food manufacturing and reduced cold-chain dependency for export markets.
FDA standards for trans-fat labeling and the EU F-Gas Regulation on industrial refrigeration emissions are tightening processing specifications and equipment upgrade timelines for butter fat fraction facilities. BIS certification requirements in India and EFSA novel food assessments for modified fat structures are fragmenting market access protocols across major dairy trade corridors. Stakeholders must monitor evolving refrigerant compliance deadlines and fractionation technology substitution economics to preserve margin structures under dual regulatory pressure.
Market Dynamics
Refrigerant phase-down mandates under the EU F-Gas Regulation are forcing butter fat fraction processors to retire conventional cooling systems and adopt solvent-free dry fractionation, compressing operating margins while reshaping capital deployment timelines across European dairy infrastructure.
Growth Catalysts
- Trans-fat labeling mandates:FDA disclosure requirements drive bakery manufacturers toward butter fat fractions as clean-label alternatives to partially hydrogenated oils in packaged goods.
- Germany:Artisanal baking traditions sustain premium fraction demand, with specialized confectioners sourcing cultured butter fractions for heritage product lines.
- Solvent-free dry fractionation:Crystallization technology advances enable precise melting-point tailoring without chemical extraction, opening clean-label positioning for export markets.
Market Restraints
- Input cost volatility:Cream and anhydrous milk fat prices fluctuate with New Zealand and EU dairy auction cycles, compressing fractionation margins unpredictably.
- Supply concentration risk:Fractionation capacity clusters in Dutch and New Zealand cooperative infrastructure, creating geographic dependency for global buyers.
- Technical limitation:Cold-chain requirements for liquid fraction transport restrict reach into tropical markets lacking refrigerated logistics networks.
Strategic Opportunities
- India:BIS certification pathways for modified milk fat structures remain underdeveloped, creating first-mover advantage for processors meeting dairy safety standards.
- Snack food manufacturing:Powdered butter fat fractions address extended shelf-life requirements in extruded and puffed product categories.
- EU Green Deal alignment:Low-emission fractionation technologies qualify for sustainable agriculture financing, offsetting equipment upgrade capital burdens.
Industry Challenges
- Refrigerant compliance timelines:F-Gas Regulation phase-down deadlines compress facility retrofit schedules, demanding simultaneous production continuity and equipment replacement.
- Fractionation expertise scarcity:Crystallization process engineering talent concentrates in legacy dairy regions, limiting expansion into emerging production geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butter Fat Fraction Market |
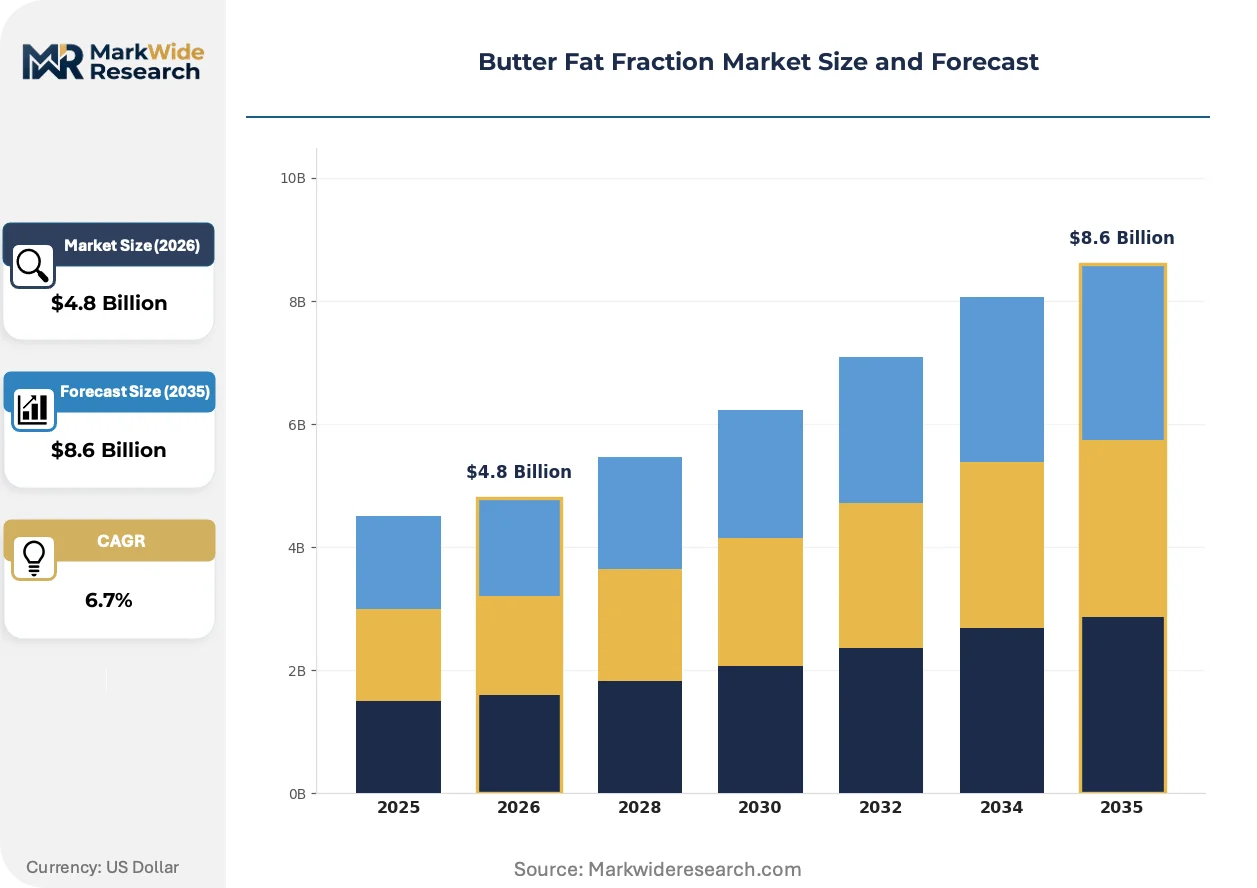
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Butter, Reduced Fat Butter, Whipped Butter, Cultured Butter End Use Industry: Dairy Products, Bakery Products, Confectionery, Snack Foods Form: Liquid, Powder, Creamy, Granulated Fat Content: Full-Fat, Low-Fat, Extra Light, Light |
| Companies Covered | Fonterra Co-operative Group Limited, Royal FrieslandCampina, Arla Foods, Lactalis Ingredients, Glanbia, Uelzena, Valio, Saputo, Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butter Fat Fraction Market Evolving Landscape
Processing technology and regulatory compliance frameworks are converging to redefine operational benchmarks, with digitization and sustainability mandates driving equipment refresh cycles and product formulation strategies simultaneously.
Membrane filtration coupled with controlled crystallization systems is digitizing temperature and agitation parameters in real-time, enabling confectionery manufacturers to specify exact melting profiles within 0.5°C tolerances. Large-scale chocolate producers in Belgium and Switzerland are piloting these systems to reduce batch-to-batch variation. The technology is digitizing quality assurance workflows, compressing laboratory testing cycles from days to hours.
The EU F-Gas Regulation mandates 79% reduction in hydrofluorocarbon refrigerant use by 2030, forcing processors to adopt ammonia or CO2-based cooling systems with higher upfront capital requirements. Dutch and German fractionation facilities face 2027 equipment upgrade deadlines, accelerating vendor consolidation for compliant refrigeration engineering. Bakery supply contracts now incorporate emissions disclosure clauses, transferring compliance verification burden upstream to fraction suppliers.
Clean-label procurement criteria have shifted buyer evaluation from price-per-kilogram to full supply-chain transparency documentation. European artisanal bakeries and North American premium snack brands now require batch-level origin tracking and carbon footprint certification. This behavioral pivot is most visible in Germany, where regional dairy cooperatives market terroir-specific fractions commanding 15-20% premiums over commodity alternatives.
Butter Fat Fraction Market Segmentation
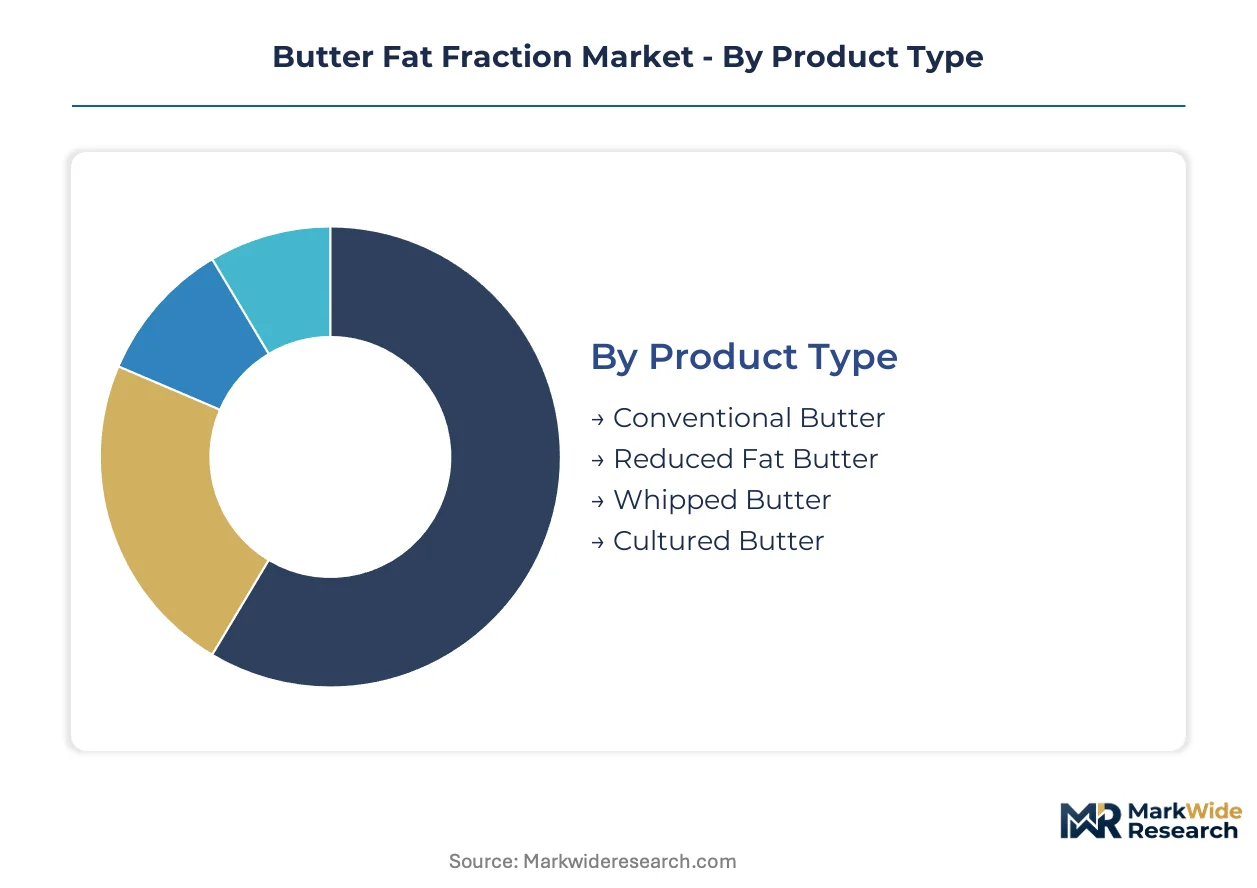
Segmentation in butter fat fraction markets reveals how crystallization technology and formulation requirements fragment demand across distinct functional specifications. Each dimension—product chemistry, downstream application, physical state, and fat concentration—creates separate procurement channels with unique margin structures and regulatory exposure.
Product Type:
Mature conventional formats anchor volume throughput while emerging specialty variants capture margin expansion through clean-label positioning and artisanal supply contracts.
- Conventional Butter:Standard anhydrous milk fat fractions with melting profiles between 32°C and 37°C serve industrial bakery and confectionery manufacturers requiring consistent plasticity for laminated doughs and chocolate coatings. German artisanal bakeries source conventional fractions for heritage product lines where traditional mouthfeel specifications override premium positioning.
- Cultured Butter:Fermented cream fractions with elevated diacetyl content deliver distinctive aromatic profiles for European premium channels and North American specialty food retailers. Belgian chocolate producers specify cultured fractions for ganache applications where subtle acidity balances sweetness.
- Reduced Fat Butter:Water-in-oil emulsions with 60-80% fat content address calorie-conscious formulation in North American snack food manufacturing.
- Whipped Butter:Nitrogen-aerated fractions with increased spreadability target foodservice dispensing systems and retail convenience segments.
Conventional Butter handles the majority of throughput; Cultured Butter is the fastest mover on share.
End Use Industry:
Application-driven procurement splits between commodity-scale food manufacturing and precision-formulation specialty channels with divergent technical service requirements.
- Bakery Products:Laminated doughs, puff pastries, and croissants demand fractions with precise plasticity ranges and oxidative stability for extended sheeting operations. Dutch industrial bakeries specify low-melting-point fractions for frozen dough applications where cold-chain distribution stresses fat crystal structures.
- Confectionery:Chocolate tempering and praline filling applications require sharp-melting fractions with complete solidification above 20°C to prevent fat bloom and ensure clean flavor release. Swiss manufacturers pilot membrane-filtered fractions with 0.5°C melting tolerance specifications.
- Dairy Products:Ice cream and recombined milk applications utilize medium-melting fractions for texture stabilization and overrun control.
- Snack Foods:Extruded and puffed categories drive powdered fraction adoption for extended shelf-life without refrigerated distribution.
Bakery Products commands the largest procurement volumes; Snack Foods is expanding most quickly as powdered formulations displace liquid alternatives.
Form:
Physical state selection trades cold-chain dependency against reconstitution flexibility, with powder formats gaining ground in export-oriented supply chains.
- Liquid:Bulk anhydrous milk fat in heated tanker configurations serves regional dairy processors and industrial bakeries with continuous production lines and refrigerated storage infrastructure.
- Powder:Spray-dried or encapsulated fractions with 12-24 month ambient stability enable Southeast Asian and Middle Eastern market entry without refrigerated logistics networks.
- Creamy:Semi-solid fractions in pail or drum packaging target small-batch foodservice and artisanal manufacturing with intermediate scale requirements.
- Granulated:Free-flowing particulate fractions facilitate precise metering in automated snack food seasoning systems.
Liquid handles the majority of throughput; Powder is climbing the fastest on share as tropical market penetration accelerates.
Fat Content:
Concentration tiers align with regulatory labeling thresholds and functional performance requirements across reformulation and premium positioning strategies.
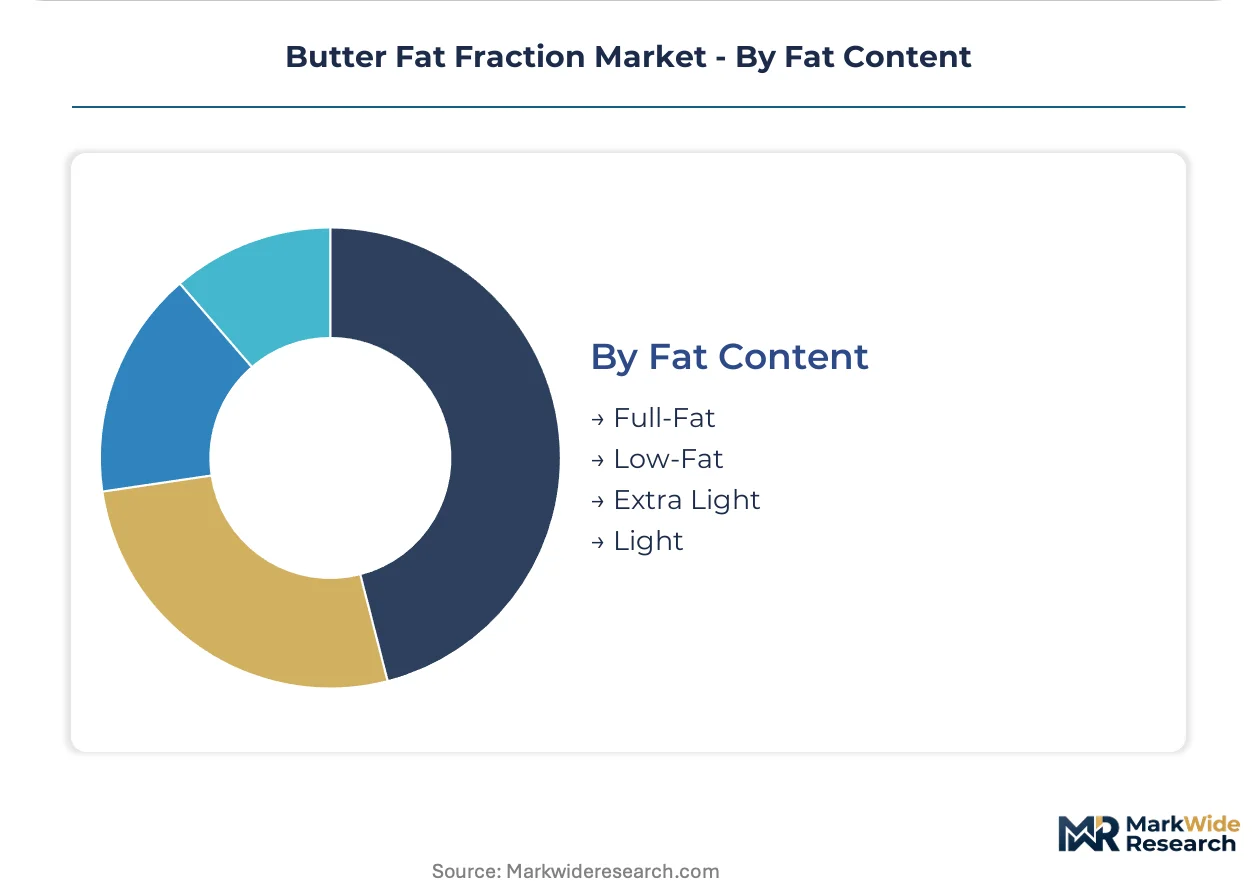
- Full-Fat:Standardized anhydrous milk fat at 99.8% minimum fat content provides maximum flavor carrying capacity and crystallization control for chocolate and premium pastry applications.
- Low-Fat:60-80% fat emulsions support FDA trans-fat labeling compliance and calorie-reduction claims in North American packaged bakery goods.
- Light:40-60% fat spreads target retail table use with spreadability optimization.
- Extra Light:Below 40% fat formulations serve specialized dietetic and institutional feeding applications with stringent fat restriction protocols.
Full-Fat dominates industrial procurement volumes; Low-Fat is gaining share fastest as trans-fat replacement mandates drive reformulation activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisanal bakery procurement clusters in Germany, industrial confectionery demand concentrates in Belgium and Switzerland, while export-oriented fractionation capacity anchors in New Zealand and the Netherlands.
Germany
Heritage baking traditions sustain premium cultured butter fraction consumption, with regional cooperatives supplying heritage product lines. The EU F-Gas Regulation mandates refrigerant phase-down compliance by 2027, compressing facility retrofit timelines. Bavarian dairy processors in the Munich-Stuttgart corridor specialize in terroir-specific fractions commanding 15-20% premiums over commodity alternatives.
Belgium
Large-scale chocolate manufacturers pilot membrane-filtered fractions with 0.5°C melting tolerance specifications for tempering applications. EFSA novel food assessments govern modified fat structure approvals, fragmenting market access protocols. Antwerp-Ghent industrial zones host precision fractionation facilities serving praline and ganache producers with sharp-melting fat requirements.
Switzerland
Swiss confectioners specify cultured butter fractions where subtle acidity balances sweetness in premium ganache formulations. REACH compliance frameworks regulate chemical processing inputs, though solvent-free dry fractionation avoids extraction-related obligations. The Zurich-Basel corridor concentrates high-margin specialty fraction production for luxury chocolate brands.
New Zealand
Year-round milk pool availability sustains continuous fractionation capacity for export markets across Asia-Pacific. The country's dairy regulator enforces strict compositional standards for anhydrous milk fat exports. Canterbury-based cooperatives leverage southern hemisphere production cycles to supply northern hemisphere bakery manufacturers during seasonal supply gaps.
Netherlands
Integrated cooperative infrastructure anchors European butter fat fraction supply through Rotterdam-Antwerp logistics corridors. EU Green Deal sustainable agriculture financing offsets equipment upgrade capital burdens for low-emission fractionation adoption. Dutch facilities face 2027 F-Gas Regulation deadlines, accelerating vendor consolidation for ammonia and CO2-based cooling systems.
Butter Fat Fraction Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships, with cooperative structures dominating upstream milk sourcing and independent processors carving niches in organic and specialty fractions. The vendor base clusters around dairy cooperative networks in New Zealand and the Netherlands, supplemented by European private-label specialists and North American dairy marketing cooperatives. Three archetypes prevail: vertically integrated cooperatives with captive milk supply, toll-processing specialists offering asset-light fractionation services, and organic-certified niche players serving premium bakery accounts. Dominant competitive moves include backward integration into milk pooling to secure feedstock, and technology licensing agreements for solvent-free dry fractionation equipment.
Within the cooperative archetype, Fonterra Co-operative Group Limited and Royal FrieslandCampina occupy anchor positions exemplifying contrasting geographic strategies. Fonterra represents southern hemisphere export-oriented production, while FrieslandCampina exemplifies European integrated infrastructure. Arla Foods sits within the specialty-tier vector, representing organic and clean-label positioning for premium channel penetration. These three entities collectively illustrate how milk pool control, processing scale, and certification differentiation segment competitive positioning across global supply corridors.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Royal FrieslandCampina |
| Arla Foods |
| Lactalis Ingredients |
| Glanbia |
| Uelzena |
| Valio |
| Saputo |
| Dairy Farmers of America |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation refrigerant phase-down deadlines compress both pricing tier spreads and supply chain configuration choices for butter fat fraction processors. Dutch and German facilities face simultaneous equipment replacement mandates and production continuity requirements, forcing capital allocation decisions that widen the gap between ammonia-cooled premium fractions and legacy-standard alternatives.
Pricing Analysis
Cost-plus contracts indexed to Global Dairy Trade auction prices dominate butter fat fraction procurement, with Fonterra's monthly auction serving as the primary reference point. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from cold-chain logistics cost escalation for liquid fractions. Industrial bakery manufacturers exhibit highest price sensitivity, while European artisanal channels absorb premiums for terroir-specific cultured variants.
Supply Chain Analysis
Tariff exposure between New Zealand and China dominates supply chain risk calculus for Asia-Pacific fraction exports. Production concentrates in the Netherlands, New Zealand, and Germany, with raw material sourcing drawing from cooperative milk pools in Canterbury and Friesland. Single-source vulnerability exists for membrane filtration equipment suppliers serving Belgian chocolate manufacturers. Distribution runs through Rotterdam-Antwerp logistics corridors for European supply and Auckland-Singapore shipping lanes for Asia-Pacific delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated industrial bakery groups negotiating multi-year fraction supply agreements. This consolidation fragments margin capture for mid-sized processors lacking captive milk supply.
For Market Incumbents: Build regulatory compliance moats through early ammonia cooling system adoption ahead of Dutch and German 2027 F-Gas deadlines. Secure backward integration into organic milk pooling to defend against Arla Foods' clean-label positioning. Invest in membrane filtration R&D to meet Swiss chocolate manufacturers' 0.5°C melting tolerance specifications. For New Entrants and Emerging Players: Build out toll-processing capabilities in India to capture first-mover advantage before BIS certification pathways mature for modified milk fat structures. Target Southeast Asian snack food manufacturers with powdered fraction formulations eliminating cold-chain dependency. Pursue asset-light leasing models for solvent-free dry fractionation equipment to bypass capital-intensive infrastructure requirements. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors processors with compliant refrigeration infrastructure and established EU Green Deal financing relationships. Long-term viability hinges on controlling fractionation expertise concentrated in legacy dairy regions. Watch for F-Gas compliance deadline acceleration as the inflection signal triggering distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Dry Fractionation Adoption | Enables EU F-Gas Regulation compliance without chemical extraction obligations under REACH frameworks. |
| Organic Milk Pool Integration | Secures feedstock for Arla Foods-competing clean-label fraction streams targeting premium bakery accounts. |
| Membrane Filtration Scale-Up | Meets Belgian and Swiss chocolate manufacturers' precision melting-profile specifications. |
| Powdered Fraction Capacity Addition | Addresses Southeast Asian and Middle Eastern market entry without refrigerated logistics networks. |
| Toll-Processing Partnership Expansion | Reduces capital barriers for mid-sized dairy processors entering butter fat fraction production. |
Research Methodology
Initial hypotheses were tested against primary input from dairy cooperative procurement directors, fractionation plant engineers, bakery manufacturing R&D leads, and confectionery supply chain managers and refined through secondary validation. Sources included Global Dairy Trade auction data, EU F-Gas Regulation compliance filings, EFSA novel food assessment records, and BIS dairy safety standard documentation. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Demand-supply balance dynamics across the analysis window shaped the forecast framework, with segmentation by product type, end-use industry, physical form, and fat concentration tier informing growth allocation. CAGRs were derived from trend extrapolation calibrated against historical dairy auction cycles and regulatory implementation timelines. Input variables included refrigerant phase-down compliance costs and powdered fraction adoption rates in tropical markets.
Practitioners should monitor EU F-Gas deadline acceleration, New Zealand drought-induced milk pool contraction, and Indian BIS certification finalization for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Skimmed Milk Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Goat Milk Powder Market
Dairy Products
Gruyere Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Evaporated Milk Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Hydrolyzed Casein Market