
 Portable Keg System Market | 2026-2036
Portable Keg System Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Keg System Market Analytics
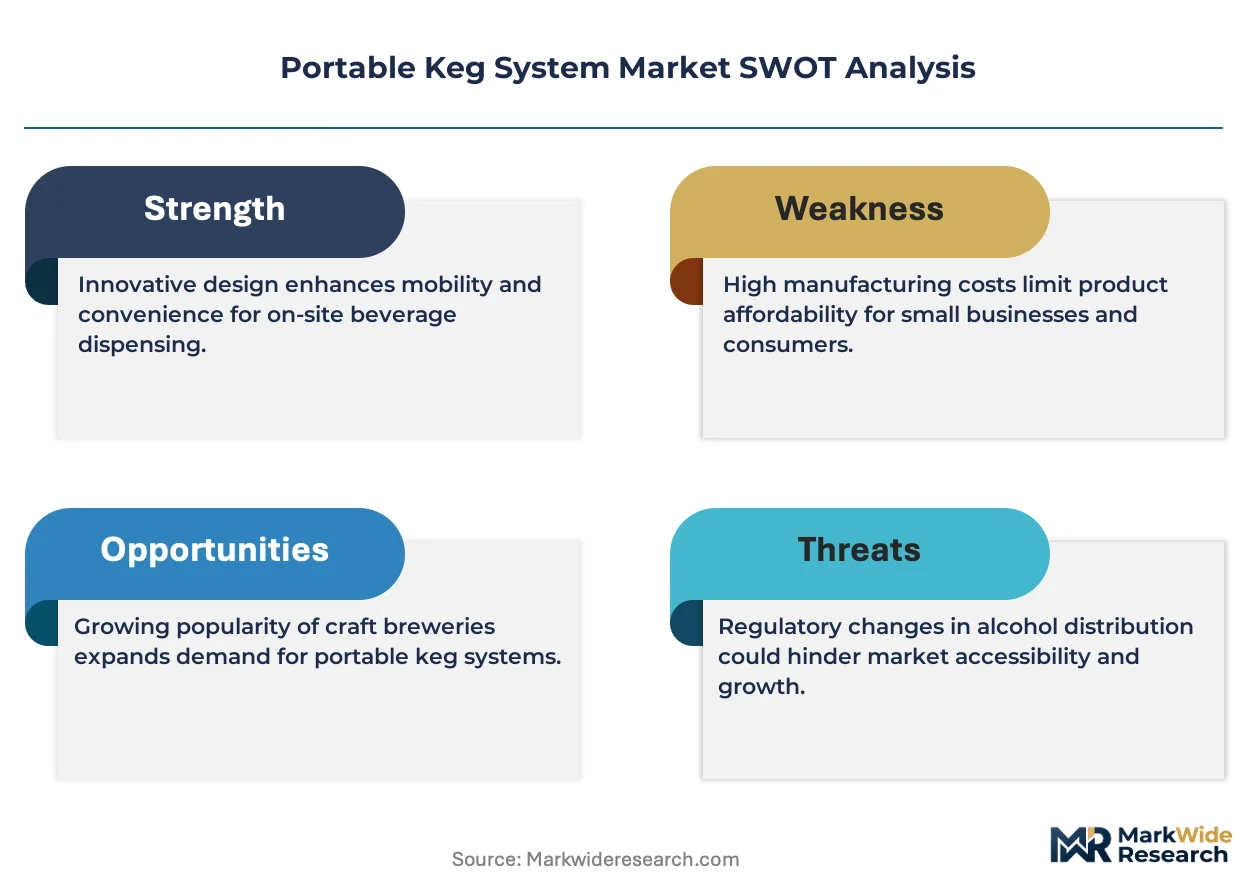
The capital-intensity divergence between stainless steel fabricators and plastic-mold specialists is reorganizing competitive tiers in portable keg supply. Heineken N.V. leverages its captive brewery network to secure high-volume keg placements across European hospitality chains. Micro Matic anchors North American market presence through specialized dispensing equipment integration with keg hardware.
A portable keg system comprises pressurized vessels—typically constructed from 304-grade stainless steel or food-grade aluminum with CO2 regulator assemblies—designed to store, transport, and dispense carbonated beverages while preserving sensory integrity. Stainless steel variants sustain premium positioning in commercial bars where durability cycles exceed ten years, while plastic and hybrid formats capture accelerating adoption among home users seeking lighter, lower-cost alternatives. Cornelius kegs dominate craft brewing workflows owing to standardized ball-lock interfaces and reconditioning economies.
US FDA food-contact material standards and EU REACH chemical safety frameworks govern material composition and surface treatment protocols, directly constraining supplier qualification and cross-border shipment eligibility. Germany's KBA and France's ANSM enforce transport-pressure vessel certifications that add compliance layers to mobile keg designs. Stakeholders must monitor evolving refrigerant regulations and material substitution trajectories to anticipate where certification burdens will shift next.
Market Dynamics
EU F-Gas Regulation compliance costs are redrawing competitive boundaries between stainless steel fabricators and plastic-mold specialists, forcing refrigerant-dependent cooling system suppliers to redesign thermal management architectures or exit European hospitality channels entirely.
Growth Catalysts
- Ball-Lock Standardization:Cornelius keg interface uniformity across craft brewing workflows reduces reconditioning costs and accelerates equipment interoperability throughout North American microbrewery networks.
- REACH Material Certification:EU chemical safety frameworks create qualification barriers that favor established 304-grade stainless steel suppliers with existing compliance documentation and testing infrastructure.
- Bavaria Consumption Density:Germany's sustained keg utilization rates in on-premise channels generate predictable replacement demand for pressurized vessel assemblies and regulator components.
Market Restraints
- Nickel Price Volatility:304-grade stainless steel input costs fluctuate with London Metal Exchange nickel futures, compressing margin stability for premium commercial-grade fabricators.
- Transport Vessel Certification:Germany's KBA and France's ANSM pressure-testing requirements add 8-14 week approval timelines to mobile keg launches, delaying revenue recognition.
- Single-Use Packaging Substitution:Aluminum canning lines achieve sub-15-cent per-unit costs at scale, diverting craft brewery capex away from reusable keg infrastructure.
Strategic Opportunities
- Home Dispensing Convergence:Lighter hybrid-format kegs paired with compact CO2 regulators penetrate residential channels previously blocked by stainless steel weight barriers.
- US IRA Clean Energy Credits:Domestic manufacturing incentives for energy-efficient cooling components offset refrigerant system redesign costs for suppliers with US fabrication assets.
- Cold-Chain Beverage Extension:Nitrogen-compatible pressurized vessels enable craft coffee and kombucha producers to adopt keg distribution without dedicated equipment lines.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section IX pressure vessel welder qualifications require 18-24 month apprenticeship pipelines, constraining stainless steel fabricator capacity expansion.
- Legacy Dispensing Integration:Micro Matic and Perlick tap hardware proprietary threading standards force keg suppliers to maintain multiple valve configurations, inflating SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Keg System Market |
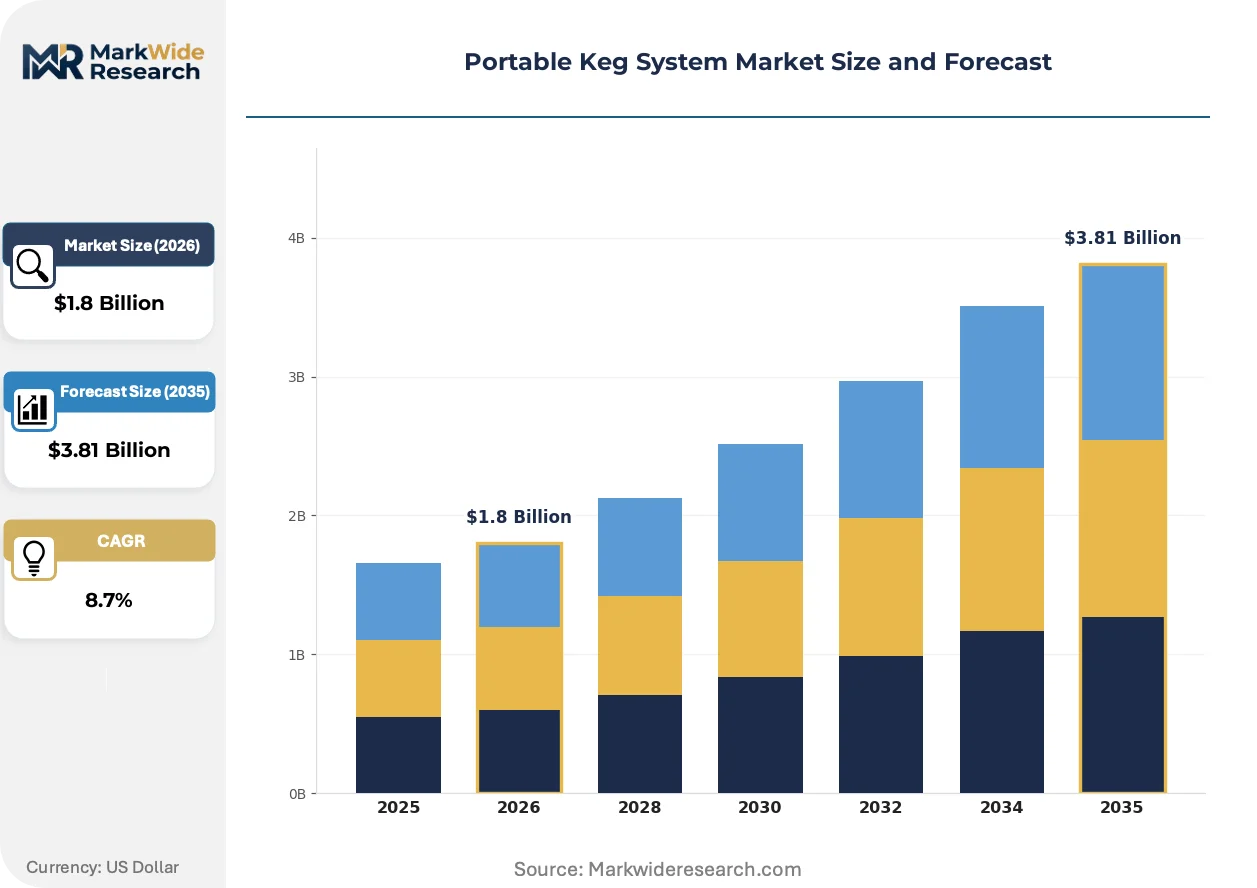
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Keg, Cornelius Keg, Mini Keg, Party Keg End User: Bars, Restaurants, Catering Services, Home Users Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales Material: Stainless Steel, Aluminum, Plastic, Hybrid |
| Companies Covered | Heineken N.V., Anheuser-Busch InBev, Carlsberg Group, Kegco, Cornelius Kegs Ltd., Perlick Corporation, Micro Matic, UBC Keg Systems, Diageo plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Keg System Market Evolving Landscape
Material science advances and regulatory chemistry constraints are bifurcating product architectures, with thermal management systems facing forced redesign while vessel construction explores aluminum-polymer hybrids.
Hybrid aluminum-polymer keg construction is fragmenting the traditional stainless steel monopoly in commercial hospitality. Mid-tier restaurant chains in Germany and the Netherlands adopt these vessels for seasonal outdoor service where weight reduction outweighs 10-year durability requirements. The technology is fragmenting supplier tiers by enabling plastic-mold specialists to capture keg shell production without metallurgical fabrication capabilities.
EU F-Gas Regulation phasedown schedules are compressing hydrofluorocarbon refrigerant availability for integrated cooling systems. Keg dispensing equipment manufacturers face reformulation costs or supplier switches to hydrocarbon or CO2-based alternatives. German hospitality chains with centralized procurement are accelerating specification updates to lock in compliant thermal architectures before 2027 supply constraints.
Direct-to-brewery equipment leasing displaces traditional distributor-owned keg pools in North American craft brewing. Smaller microbreweries in Oregon and Colorado prefer operational expenditure models that bundle vessel maintenance, regulator replacement, and line cleaning services. This procurement evolution concentrates vendor relationships with integrated service providers rather than pure hardware suppliers.
Portable Keg System Market Segmentation
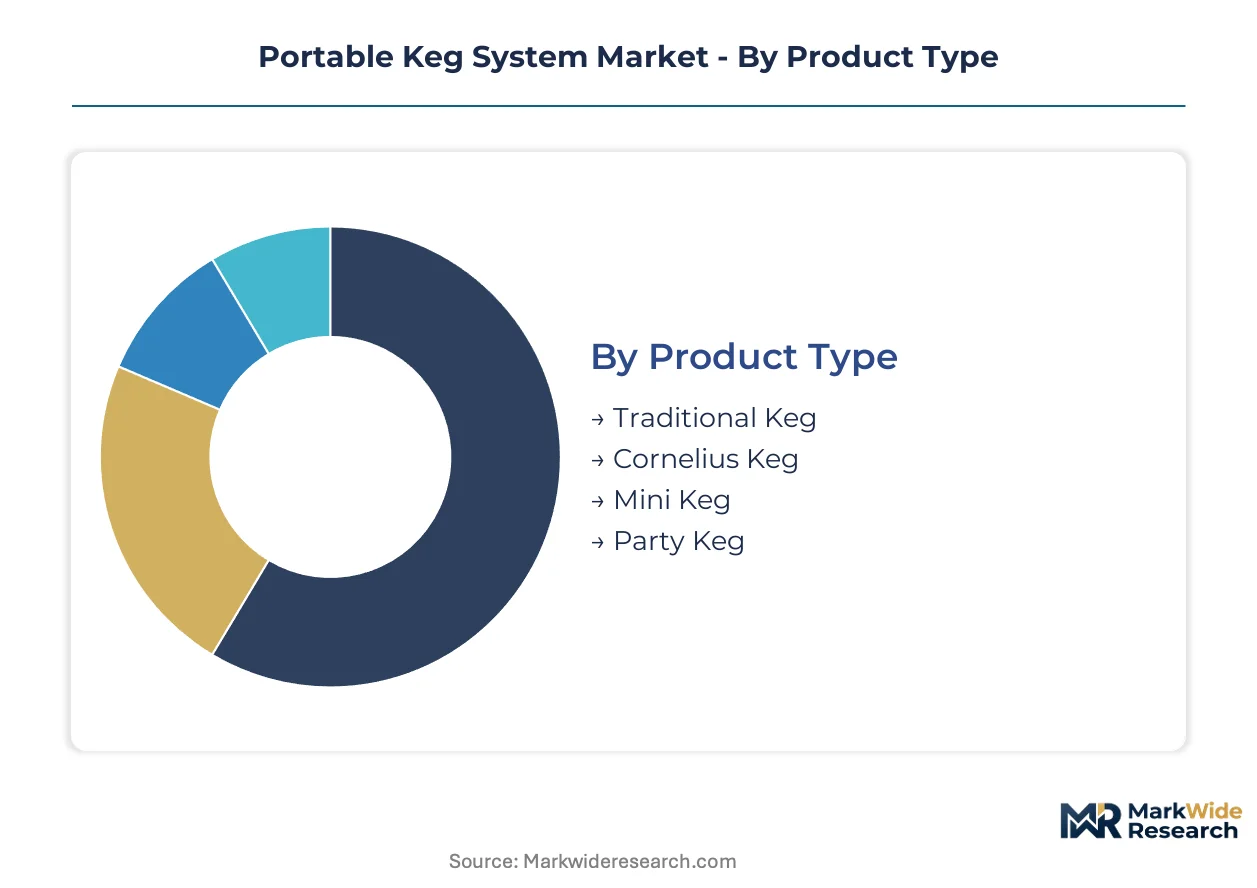
Portable keg system segmentation reveals divergent supply chain configurations across product architectures and procurement channels. Material composition and end-use application dictate certification requirements, geographic sourcing patterns, and margin structures throughout the value chain.
Product Type:
Cornelius kegs dominate North American craft brewing workflows through standardized ball-lock interfaces, while traditional stainless steel variants anchor European commercial hospitality procurement.
- Traditional Keg:Pressurized vessels constructed from 304-grade stainless steel with welded seam construction and reinforced chime rings. German brewers specify these units for multi-decade service cycles in Bavarian on-premise channels, where KBA transport certification and REACH material documentation filter supplier pools to established fabricators.
- Cornelius Keg:Ball-lock interface standardization enables rapid reconditioning and cross-brewery equipment interoperability. Oregon and Colorado microbreweries drive replacement demand through direct-to-brewery leasing models that bundle vessel maintenance with regulator service.
- Mini Keg:Compact 5-liter disposable and reusable formats target residential dispensing with reduced CO2 system complexity.
- Party Keg:Single-event plastic vessels with integrated tap mechanisms serve outdoor catering and temporary hospitality installations.
Traditional kegs command the established base. The steepest expansion runs through Cornelius keg formats.
End User:
Procurement scale and equipment integration requirements separate commercial hospitality buyers from residential adopters, with diverging price sensitivities and service expectations.
- Bars:High-volume dispensing environments prioritize 304-grade stainless steel durability and Micro Matic tap compatibility. French ANSM pressure vessel certification adds compliance timelines to equipment procurement cycles.
- Restaurants:Mid-tier chains in the Netherlands and Germany adopt hybrid aluminum-polymer vessels for seasonal outdoor service where weight reduction outweighs extended durability requirements.
- Catering Services:Mobile event operators favor lightweight disposable formats with simplified logistics and reduced cleaning infrastructure.
- Home Users:Residential channels accelerate adoption of plastic and hybrid formats paired with compact CO2 regulators, displacing stainless steel weight barriers that previously blocked consumer penetration.
Bars anchor commercial procurement volume. Home users are gaining share fastest.
Distribution Channel:
Channel selection correlates with buyer scale and technical service requirements, with integrated leasing providers displacing pure hardware distributors in craft brewing segments.
- Online Retailers:E-commerce platforms capture residential and small commercial buyers seeking standardized SKUs with transparent pricing. Home dispensing convergence drives platform specialization in compact regulator bundles and consumable replenishment.
- Specialty Stores:Physical retail with technical consultation serves craft brewers requiring equipment interoperability validation and ball-lock interface matching.
- Wholesale Distributors:Traditional keg pool operators face displacement as direct-to-brewery leasing concentrates vendor relationships with integrated service providers.
- Direct Sales:Manufacturer-direct procurement dominates large hospitality chains with centralized specification authority and volume contracting leverage.
Direct sales lock in chain hospitality accounts. Online retailers climb the fastest.
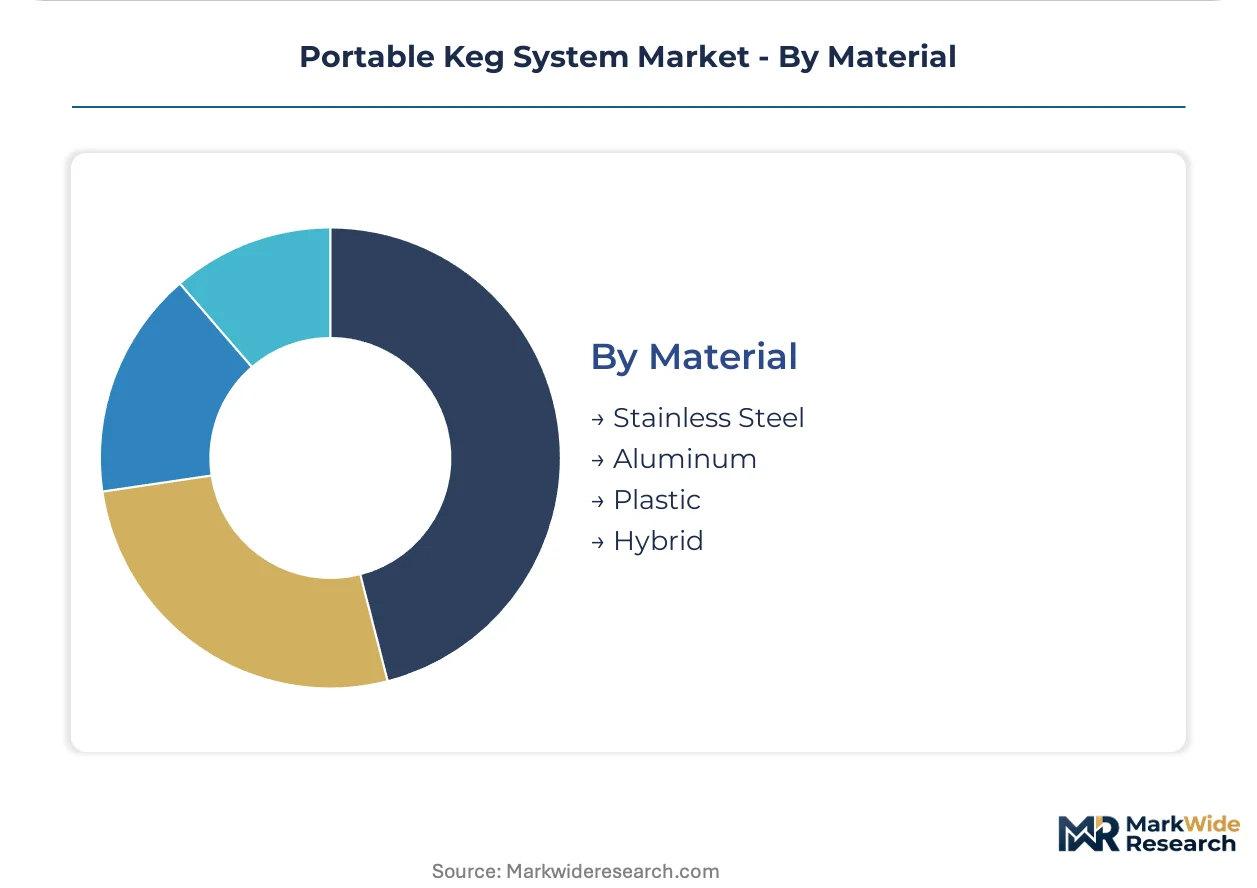
Material:
Input cost volatility and regulatory chemistry constraints are fragmenting supplier tiers, with plastic-mold specialists capturing shell production without metallurgical fabrication capabilities.
- Stainless Steel:304-grade construction sustains premium positioning in commercial bars where durability cycles exceed ten years. Nickel price volatility on London Metal Exchange futures compresses margin stability for premium fabricators.
- Aluminum:Lighter weight alternatives reduce transport costs and enable hybrid construction with polymer components. EU REACH chemical safety frameworks govern surface treatment protocols and constrain cross-border shipment eligibility.
- Plastic:Food-grade polymer formats capture accelerating residential adoption through weight reduction and cost minimization. US FDA food-contact material standards directly constrain supplier qualification.
- Hybrid:Aluminum-polymer construction fragments the traditional stainless steel monopoly in mid-tier commercial hospitality. Plastic-mold specialists capture keg shell production without ASME Section IX welding certification requirements.
Stainless steel holds the premium commercial base. Hybrid formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command premium pricing for KBA-certified transport vessels while US craft brewers in Oregon and Colorado drive volume through operational lease models. This pricing-power asymmetry reflects divergent certification burdens and procurement evolution across Atlantic markets.
United States
Oregon and Colorado microbreweries accelerate direct-to-brewery equipment leasing that bundles vessel maintenance with regulator service. FDA food-contact material standards constrain plastic-format supplier qualification for residential channels. Portland's craft brewing cluster anchors replacement demand for Cornelius keg ball-lock interfaces.
Germany
Bavarian on-premise channels sustain multi-decade service cycles for 304-grade stainless steel vessels with predictable replacement demand. KBA transport-pressure vessel certifications add 8-14 week approval timelines to mobile keg launches. Munich's brewing equipment fabricators concentrate premium commercial-grade production.
Netherlands
Mid-tier restaurant chains adopt hybrid aluminum-polymer vessels for seasonal outdoor service where weight reduction outweighs durability requirements. EU F-Gas Regulation compliance costs pressure refrigerant-dependent cooling system redesigns. Amsterdam's hospitality procurement networks accelerate specification updates ahead of 2027 supply constraints.
France
ANSM pressure vessel certification creates compliance barriers that filter supplier pools to established fabricators with existing documentation infrastructure. REACH chemical safety frameworks govern surface treatment protocols for aluminum alternatives. Parisian bar operators prioritize Micro Matic tap compatibility in high-volume dispensing environments.
United Kingdom
Specialty retail channels with technical consultation serve craft brewers requiring equipment interoperability validation. CE marking requirements align with EU regulatory trajectories for cross-border shipment eligibility. London's brewing equipment distributors face displacement as integrated leasing providers concentrate vendor relationships.
Portable Keg System Market Competitive Landscape
Concentration sits with stainless steel fabricators holding ASME Section IX welding certifications and established REACH documentation infrastructure. The vendor base spans three strategic tiers: captive brewery networks leveraging high-volume keg placements, specialized dispensing equipment integrators, and plastic-mold specialists capturing hybrid-format shell production. Dominant competitive moves include direct-to-brewery leasing model expansion and refrigerant system architecture redesign for EU F-Gas compliance.
Among Dutch-based beverage conglomerates, Heineken N.V. exemplifies captive network leverage across European hospitality chains. Danish brewer Carlsberg Group occupies a comparable position within integrated supply structures. On the equipment-specialist vector, Micro Matic represents the dispensing integration archetype that bundles hardware with tap system compatibility.
| Leading Market Players |
|---|
| Heineken N.V. |
| Anheuser-Busch InBev |
| Carlsberg Group |
| Kegco |
| Cornelius Kegs Ltd. |
| Perlick Corporation |
| Micro Matic |
| UBC Keg Systems |
| Diageo plc |
| Others |
Value Network & Pricing Analysis
Eight-to-fourteen-week KBA certification timelines for German transport-pressure vessels concentrate pricing power with Munich-area fabricators holding pre-qualified documentation infrastructure, while plastic-mold specialists in Asia capture hybrid-format shell production without metallurgical apprenticeship pipelines. This lead-time asymmetry stratifies procurement costs across commercial hospitality tiers.
Pricing Analysis
Configured-to-order pricing for KBA-certified stainless steel vessels commands substantial premiums over standard Cornelius keg formats. Three-tier pricing structure across premium certified, standard commercial, and economy disposable levels reflects divergence in material grade and regulatory documentation burden. Cost compression in standard-grade tiers intensifies because aluminum-polymer hybrid alternatives displace 304-grade demand among mid-tier restaurant chains. Home users exhibit highest price sensitivity, while Bavarian brewers prioritize decade-scale durability over unit economics.
Supply Chain Analysis
Germany and China anchor global vessel fabrication, with Munich fabricators concentrating premium stainless steel production and Guangdong mold specialists capturing hybrid shell manufacturing. Raw material flows draw from Indonesian nickel ore, Chinese 304-grade steel rolling capacity, and German polymer compounding. Single-source vulnerability concentrates in ASME Section IX certified welder pools, where eighteen-to-twenty-four-month apprenticeship timelines constrain capacity expansion. Distribution runs through direct sales for large hospitality chains, integrated leasing providers for craft breweries, and e-commerce platforms for residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Craft brewery capital expenditure cycles are recovering from aluminum canning line diversion, restoring replacement demand for reusable keg infrastructure. This cyclical rebound favors suppliers with bundled service capabilities.
For Market Incumbents: Shield market position by deepening backward integration into CO2 regulator assembly and securing exclusive Micro Matic tap compatibility agreements. Invest in hydrocarbon refrigerant system redesign ahead of EU F-Gas phasedown deadlines to preempt specification lockout from centralized hospitality procurement. For New Entrants and Emerging Players: Lead with lightweight hybrid-format vessels targeting Netherlands and German mid-tier restaurant chains for seasonal outdoor deployment. Exploit plastic-mold production capabilities without ASME welding certification requirements. Pursue direct-to-brewery leasing models bundling maintenance and line cleaning services to displace traditional keg pool operators. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification barriers and welding apprenticeship bottlenecks constrain new capacity entry. Target integrated service providers with established brewery leasing relationships and existing REACH documentation infrastructure. Monitor nickel futures volatility on London Metal Exchange as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant System Redesign | EU F-Gas compliance secures access to German and Dutch hospitality procurement channels ahead of supply constraints. |
| Direct-to-Brewery Leasing Expansion | Operational expenditure models concentrate vendor relationships with integrated service providers in Oregon and Colorado. |
| Hybrid Format Manufacturing Scale-Up | Aluminum-polymer construction enables plastic-mold specialists to capture keg shell production without metallurgical capabilities. |
| ASME Welder Apprenticeship Investment | Eighteen-to-twenty-four-month certification pipelines constrain competitor capacity expansion in premium stainless steel tiers. |
| Ball-Lock Interface Standardization | Cornelius keg interoperability reduces reconditioning costs and accelerates equipment adoption across North American microbreweries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact material filings, KBA transport-pressure vessel registrations, EU REACH substance databases, and London Metal Exchange nickel futures data. Brewery operations directors, hospitality procurement managers, stainless steel fabrication plant engineers, and refrigerant system design engineers provided operational perspective. Customs records and SEC 10-K filings from disclosed equipment suppliers furnished shipment and revenue triangulation against bottom-up volume estimates.
Segmentation dimensions modeled include material composition tier, end-use application, distribution channel structure, and geographic regulatory cluster across the analysis window. CAGRs derive from regression against historical replacement cycles, craft brewery formation rates, and hospitality capital expenditure surveys. Forecast inputs incorporate EU F-Gas phasedown schedules and nickel price volatility assumptions.
The analysis sits within stated boundaries; outcomes outside sustained Bavarian on-premise consumption density or accelerated aluminum canning substitution would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and refrigerant technology transition rates. Recalibration cycles align with material shifts in EU chemical safety enforcement and London Metal Exchange nickel futures volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Beer Line Cleaning Kit Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Wine Cellar Market