
 Dry Buttermilk Market | 2026-2036
Dry Buttermilk Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Buttermilk Market Foresight
The split between premium and commodity tiers is hardening as food manufacturers demand spray-dried buttermilk with sub-five percent moisture and defined protein profiles, while commodity buyers prioritize cost over functional consistency. Lactalis Ingredients leverages its European dairy network to supply standardized buttermilk solids to industrial bakeries. Fonterra Co-operative Group Limited anchors Oceania supply through its NZMP brand, controlling export volumes to Asian food manufacturers. Arla Foods amba differentiates via cooperative-owned sourcing and sustainability certifications that resonate with Northern European dairy processors.
Dry buttermilk is the dehydrated form of liquid buttermilk, typically produced through spray-drying or roller-drying to yield a free-flowing powder containing approximately thirty percent protein, seven percent fat, and four to six percent moisture depending on processing intensity. The material functions primarily as an acidulant, emulsifier, and flavor carrier in baked goods, dry mixes, and processed dairy applications. Powdered buttermilk leads volume due to its shelf stability and ease of incorporation into industrial formulations, while buttermilk concentrate commands premium positioning in artisan bakery and specialty sauce segments where flavor intensity outweighs unit cost. Buttermilk flakes occupy a narrow niche in gourmet confectionery, though growth remains constrained by limited production capacity and higher moisture sensitivity during storage.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that govern pathogen limits and drying facility sanitation for dairy ingredients sold into interstate commerce, while the USDA monitors organic certification claims for buttermilk powders labeled under its National Organic Program. EFSA sets maximum residue thresholds for veterinary drugs and contaminants in dairy-derived ingredients entering European food manufacturing channels, directly influencing import acceptance criteria for non-EU suppliers. Stakeholders must monitor evolving allergen labeling requirements and carbon footprint disclosure rules that are tightening across both North American and European procurement specifications.
Market Dynamics
Clean-label mandates from the FDA and EFSA are compressing residual moisture tolerances and tightening microbiological specifications, forcing dairy processors to retool spray-drying infrastructure for sub-five percent moisture consistency.
Growth Catalysts
- Grade A Pasteurized Milk Ordinance enforcement:FDA pathogen limits are standardizing drying facility sanitation across interstate suppliers, creating procurement preference for certified processors.
- Bakery chain consolidation:Industrial food manufacturers demand powdered buttermilk with defined protein profiles for formulation repeatability at scale.
- Spray-drying intensity upgrades:Sub-five percent moisture capability is differentiating premium tier supply from commodity powders.
Market Restraints
- Buttermilk flake moisture sensitivity:Gourmet confectionery applications face storage degradation constraints that limit production capacity expansion.
- Veterinary drug residue thresholds:EFSA maximum limits for contaminants create import friction for non-EU dairy suppliers entering European channels.
- Skim milk powder substitution:Cost-conscious commodity buyers pivot to lower-cost acidulants where functional consistency is not specified.
Strategic Opportunities
- Carbon footprint disclosure rules:Northern European dairy processors prioritize cooperative-owned sourcing with sustainability certifications.
- Artisan bakery concentrate demand:Buttermilk concentrate commands premium positioning where flavor intensity outweighs unit cost.
- Asian food manufacturing expansion:Oceania export infrastructure anchors supply to underpenetrated processed dairy markets.
Industry Challenges
- Allergen labeling compliance timelines:Evolving declaration requirements across North American and European procurement specifications strain formulation documentation systems.
- Legacy drying equipment retrofit costs:Capex intensity for moisture control upgrades compresses margins for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Buttermilk Market |
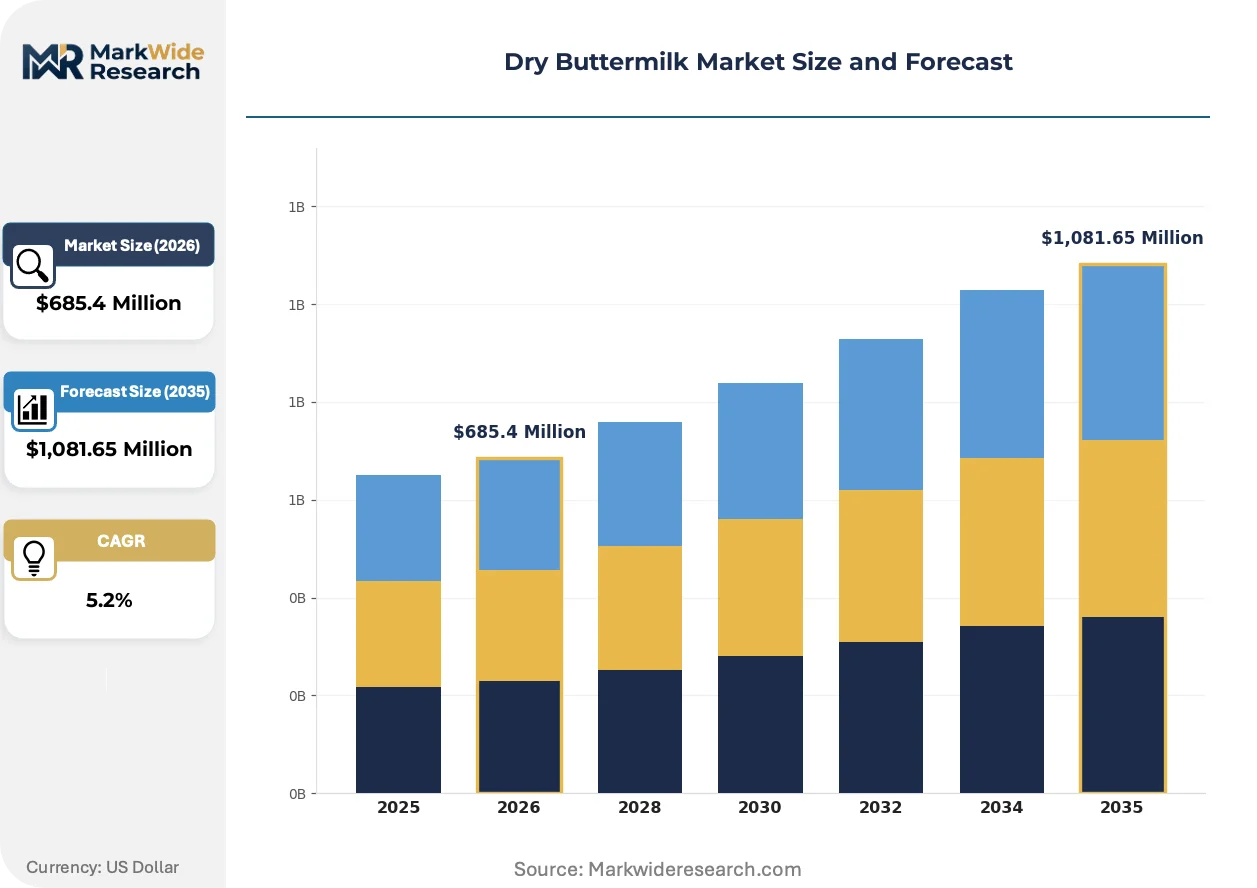
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Buttermilk, Buttermilk Solids, Buttermilk Flakes, Buttermilk Concentrate Application: Baking, Dairy Products, Confectionery, Sauces End User: Food Manufacturers, Bakeries, Restaurants, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | All American Foods, Inc., Lactalis Ingredients, Fonterra Co-operative Group Limited, Arla Foods amba, Dairy Farmers of America, Inc., Agropur, Uelzena Ingredients, Hoogwegt Group, NZMP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Buttermilk Market Shifts & Advancements
Processing technology and procurement specifications are converging to reward precision over volume, with automation and regulatory alignment determining competitive position.
Membrane filtration pre-concentration is automating solids standardization before spray-drying, reducing energy intensity per kilogram of finished powder. Large-scale dairy processors in the United States are adopting these systems to meet FDA Grade A sanitation mandates while compressing batch-to-batch variation. The technology is automating quality control checkpoints that previously required manual intervention.
EFSA's tightening maximum residue thresholds for veterinary drugs and contaminants are restructuring import acceptance criteria for dairy-derived ingredients. Non-EU suppliers face elevated testing burdens to access European food manufacturing channels. Organic certification claims under the USDA National Organic Program are experiencing parallel scrutiny as buyers demand documentation depth.
Specification-driven procurement is consolidating supplier relationships around processors capable of certificate-of-analysis consistency. Bakery chains and industrial food manufacturers are reducing vendor counts in favor of integrated dairy networks that control upstream sourcing. This concentration is most visible in the United States, where large-scale processing infrastructure supports downstream ingredient specialization.
Dry Buttermilk Market Segmentation
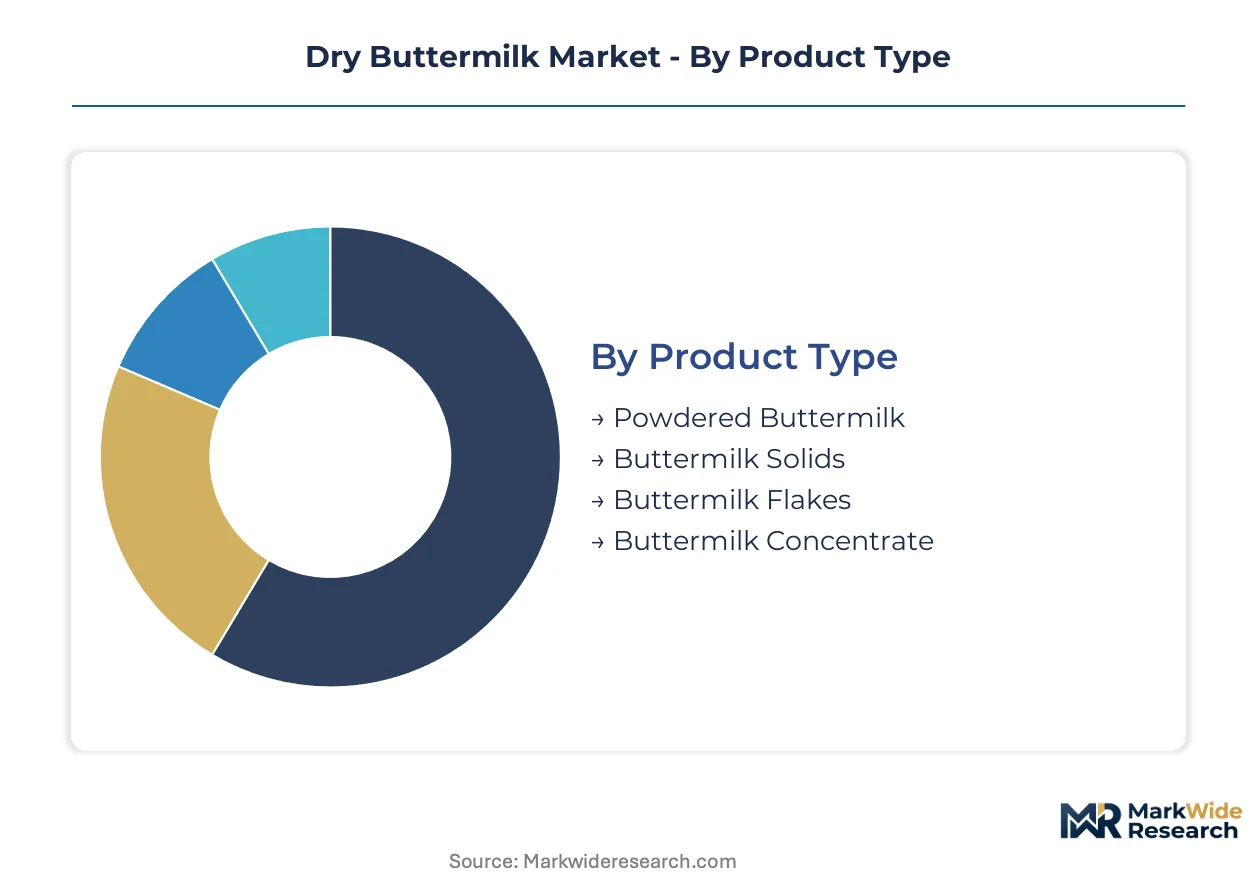
Dry buttermilk procurement decisions hinge on moisture tolerance, protein standardization, and shelf stability requirements. Food manufacturers segment supply by functional performance tier, while distribution channels stratify around volume scale and technical service intensity.
Product Type:
Buyers prioritize moisture specification and protein profile consistency when selecting between spray-dried and concentrated formats.
- Powdered Buttermilk:Spray-dried to four-to-six percent moisture with approximately thirty percent protein content, this free-flowing format dominates industrial bakery and dry mix applications where batch-to-batch uniformity is mandatory. Demand concentrates in the United States, where large-scale dairy processing infrastructure supports downstream ingredient specialization and FDA Grade A sanitation mandates favor certified processors.
- Buttermilk Concentrate:Higher solids content delivers intensified flavor and acidulant potency for artisan bakery and specialty sauce segments where functional performance outweighs unit cost. European procurement channels under EFSA veterinary residue thresholds favor concentrate imports from cooperative-owned sourcing networks with sustainability certifications.
- Buttermilk Solids:Standardized protein and fat fractions serve industrial food manufacturers requiring defined formulation inputs.
- Buttermilk Flakes:Limited production capacity and moisture sensitivity constrain expansion in gourmet confectionery niches.
Powdered buttermilk leads on scale; buttermilk concentrate leads on momentum.
Application:
End-use differentiation tracks formulation complexity and regulatory exposure across processed food categories.
- Baking:Industrial bakeries and bakery chains drive volume through standardized acidulant and emulsifier requirements for consistent crumb structure and browning. EFSA microbiological specifications and FDA pathogen limits are compressing residual moisture tolerances, forcing spray-drying infrastructure upgrades.
- Dairy Products:Processed dairy applications demand defined protein profiles for texture modification and flavor carrier functions in cultured products and frozen desserts.
- Confectionery:Gourmet segments seek buttermilk flakes for visual and textural differentiation, though storage degradation limits capacity expansion.
- Sauces:Specialty sauce manufacturers favor concentrate for flavor intensity in premium positioning.
Baking commands the largest volume position; dairy products are climbing the fastest as processed dairy markets expand.
End User:
Procurement scale and technical specification intensity separate institutional buyers from fragmented foodservice operators.
- Food Manufacturers:Industrial scale buyers demand certificate-of-analysis consistency and integrated dairy network control over upstream sourcing, consolidating vendor relationships around processors capable of sub-five percent moisture delivery.
- Bakeries:Artisan and industrial bakery segments split between commodity powder and premium concentrate based on flavor intensity requirements versus cost constraints.
- Restaurants:Limited penetration due to reconstitution complexity and refrigerated liquid buttermilk preference in scratch cooking.
- Catering Services:Volume procurement favors shelf-stable powder formats for operational simplicity.
Food manufacturers anchor volume throughput; bakeries show the steepest expansion trajectory for premium tier concentrates.
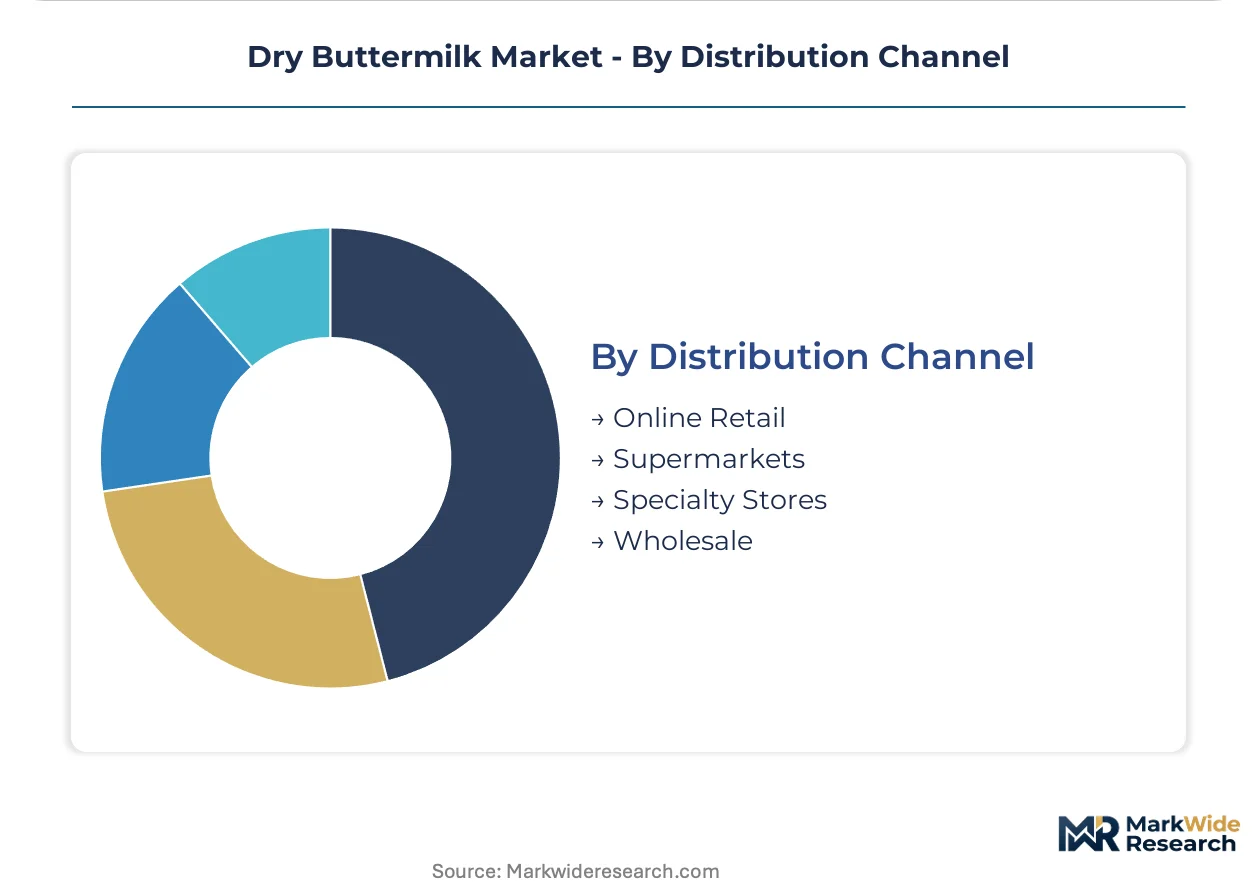
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic coverage needs.
- Wholesale:Industrial food manufacturers and bakery chains procure through dairy ingredient distributors offering integrated logistics and certificate-of-analysis documentation depth.
- Online Retail:Specialty and artisan bakery segments access smaller pack sizes with technical specifications for formulation experimentation.
- Supermarkets:Consumer-packaged goods and small commercial buyers drive limited volume in standard moisture grades.
- Specialty Stores:Gourmet and organic-certified buttermilk products serve niche confectionery and artisan dairy applications.
Wholesale channels dominate value flow; online retail is gaining share fastest among specialty and artisan segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled dairy processing technicians concentrate in Wisconsin and California, anchoring North American spray-drying capacity. European cooperative networks in Denmark and France sustain specialized buttermilk fractionation. Oceania's pastoral workforce supports seasonal milk solids harvesting for Asian export channels.
United States
Industrial bakeries and bakery chains drive procurement of sub-five percent moisture powders for formulation repeatability. FDA Grade A Pasteurized Milk Ordinance enforcement standardizes pathogen limits across interstate suppliers. Wisconsin's Fox Valley dairy cluster hosts large-scale spray-drying infrastructure serving downstream ingredient specialization.
France
Artisan bakery segments demand buttermilk concentrate for intensified flavor in premium positioning. EFSA veterinary drug residue thresholds restructure import acceptance criteria for non-EU dairy suppliers. Brittany's cooperative-owned processing networks leverage sustainability certifications for Northern European procurement preference.
Denmark
Organic-certified buttermilk powders gain traction under USDA National Organic Program parallel scrutiny. EFSA microbiological specifications compress residual moisture tolerances for European food manufacturing channels. Arla Foods amba's cooperative structure anchors supply chain control from pasture to powder.
New Zealand
Asian food manufacturers expand processed dairy procurement through Oceania export infrastructure. Fonterra Co-operative Group Limited's NZMP brand controls volume allocation to underpenetrated markets. Canterbury Plains dairy processing clusters specialize in standardized protein profiles for industrial formulation.
Germany
Industrial food manufacturers consolidate vendor relationships around certificate-of-analysis consistency. EFSA maximum residue limits for contaminants elevate testing burdens for dairy-derived ingredients. Bavaria's dairy technology corridor automates membrane filtration pre-concentration for energy-efficient spray-drying.
Dry Buttermilk Market Competitive Landscape
Capital-heavy dairy cooperatives compete with asset-light ingredient traders across the value chain. The supplier base organizes around three strategic tiers: integrated dairy networks controlling upstream sourcing, regional processors specializing in moisture-standardized powders, and trading houses aggregating spot volumes for cost-sensitive buyers. Dominant competitive moves include backward integration into milk supply contracts and automation of quality control checkpoints previously requiring manual intervention.
Within the integrated dairy network tier, Lactalis Ingredients, Fonterra Co-operative Group Limited, and Arla Foods amba exemplify contrasting geographic anchoring strategies. Lactalis Ingredients represents European cooperative sourcing depth. Fonterra Co-operative Group Limited occupies a position linking Oceania pasture supply to Asian manufacturing demand. Arla Foods amba exemplifies Northern European sustainability certification differentiation.
| Leading Market Players |
|---|
| All American Foods, Inc. |
| Lactalis Ingredients |
| Fonterra Co-operative Group Limited |
| Arla Foods amba |
| Dairy Farmers of America, Inc. |
| Agropur |
| Uelzena Ingredients |
| Hoogwegt Group |
| NZMP |
| Others |
Supply & Pricing Matrix
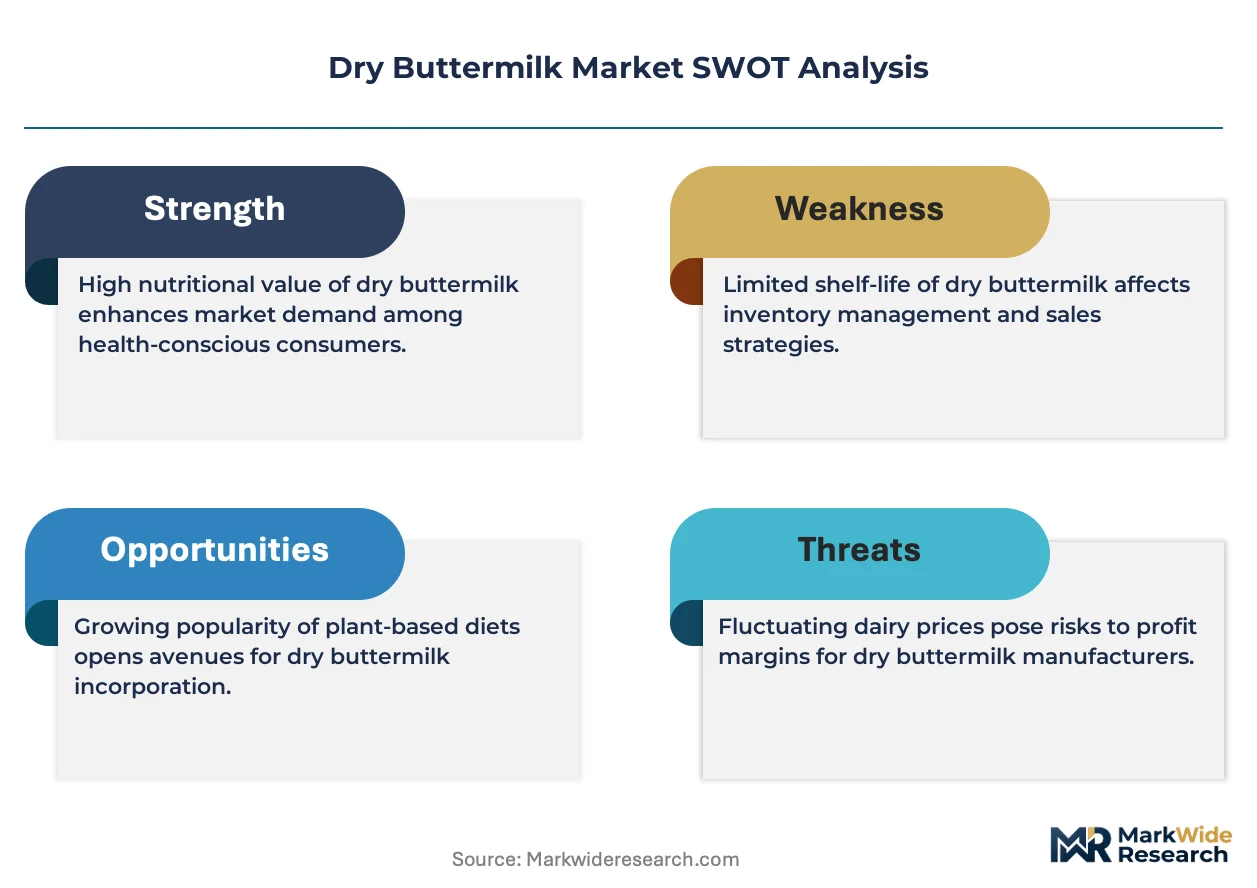
Bakery chains and industrial food manufacturers concentrate procurement volume, anchoring a contract-based long-term offtake model where specification-grade powders command premium positioning over commodity tiers.
Pricing Analysis
Unbundled certificate-of-analysis documentation and technical service support separate premium-tier supply from commodity spot transactions. Three-tier pricing structure across premium, standard, and economy levels tracks moisture specification, protein profile consistency, and FDA Grade A certification status. Cost compression in the economy tier intensifies because skim milk powder substitution erodes functional-buttermilk volumes. Food manufacturers with formulation repeatability requirements show least price sensitivity; spot buyers in fragmented foodservice channels show most.
Supply Chain Analysis
Skilled dairy processing technicians concentrate in Wisconsin and California, anchoring North American spray-drying capacity against seasonal constraints. Raw material flows draw from Grade A fluid milk supply pools, membrane filtration equipment, and natural gas for thermal processing. Single-source vulnerability sits with concentrated whey and lactose co-product offtake agreements that balance plant economics. Distribution runs through dairy ingredient distributors offering integrated logistics and documentation depth to industrial bakery and processed food channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry buttermilk procurement functions as a geographic-arbitrage play: EFSA veterinary residue thresholds elevate European testing burdens while FDA Grade A infrastructure in the United States offers standardized pathogen compliance at lower certification cost.
For Market Incumbents: Hedge against skim milk powder substitution by deepening backward integration into fluid milk supply contracts in Wisconsin and California dairy clusters. Invest in membrane filtration automation to compress batch-to-batch variation below competitor capability. Defensive positioning requires locking bakery chain procurement through multi-year specification-grade supply agreements before commodity buyers consolidate vendor relationships. For New Entrants and Emerging Players: Enter via artisan bakery concentrate segments in France and Denmark where flavor intensity requirements outweigh unit cost sensitivity and cooperative-owned sourcing networks leave technical-service gaps. White-space targets include carbon footprint disclosure-compliant supply for Northern European processors and organic-certified powders under USDA National Organic Program scrutiny. Go-to-market leverage rests on sustainability certification depth rather than volume scale. For Investors and Strategic Acquirers: Dairy cooperatives with captive milk supply and spray-drying infrastructure are the most active acquirer in this space, consolidating regional processors to control upstream sourcing. Long-term viability over a 5-10 year window hinges on FDA and EFSA regulatory alignment capability rather than commodity volume positioning. Watch for inflection in carbon footprint disclosure rule adoption across North American and European procurement specifications as signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluid Milk Supply | Captive Grade A milk pools in Wisconsin secure FDA-compliant pathogen baseline for interstate commerce. |
| Membrane Filtration Automation | Pre-concentration systems in Bavaria and California reduce energy intensity per kilogram of finished powder. |
| Sustainability Certification Investment | Arla Foods amba's cooperative-owned sourcing resonates with Northern European carbon disclosure mandates. |
| Multi-Year Specification-Grade Contracts | Bakery chain consolidation favors processors delivering sub-five percent moisture with certificate-of-analysis consistency. |
| Asian Export Infrastructure Expansion | Fonterra's NZMP brand controls volume allocation to underpenetrated processed dairy markets through Oceania pastoral networks. |
Research Methodology
Coverage spans North America, Europe, and Oceania, with primary inputs from each region combining structured interviews with dairy processing plant managers, procurement leads at industrial bakeries, distribution channel partners, and technical R&D directors at ingredient manufacturers. Secondary validation draws from FDA Grade A Pasteurized Milk Ordinance filings, USDA National Organic Program certification databases, EFSA maximum residue threshold documentation, and customs trade data on dairy ingredient flows. Bottom-up volume modeling triangulates against top-down value estimates across product type, application, and end-user segmentation.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include moisture specification tier, protein profile standardization level, end-use application complexity, and regional regulatory cluster. CAGRs derive from historical trajectory analysis adjusted for spray-drying capacity expansion timelines and bakery chain procurement consolidation patterns. Forecast inputs incorporate EFSA veterinary residue threshold evolution and FDA sanitation mandate enforcement intensity.
Inputs from dairy cooperative financial disclosures and regulatory filing databases were available through the study window; gaps in real-time spot pricing for commodity-grade powders introduce uncertainty bands around economy-tier volume projections. Forecasts reflect assumptions on clean-label mandate adoption velocity and carbon footprint disclosure rule implementation timelines. Material deviation in FDA Grade A enforcement intensity or EFSA import acceptance criteria revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
UHT Milk Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Green Tea Butter Market
Dairy Products
North America Milk Powder Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Sheep Milk Market
Dairy Products
Cheese Packaging Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
China Dairy Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Europe Yogurt Market
Dairy Products
Ricotta Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Butter Fat Fraction Market