
 X-Ray Machine Manufacturing Market | 2026-2036
X-Ray Machine Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Machine Manufacturing Market Intelligence
German component suppliers is decoupling from legacy analog sourcing as Asian manufacturers scale flat-panel detector output. Siemens AG leverages captive semiconductor fabrication to secure sensor supply chains. General Electric Company anchors its North American installed base through predictive service contracts. Canon Inc. competes on CMOS detector miniaturization for portable units.
X-ray machine manufacturing encompasses the design, assembly, and calibration of ionizing radiation systems generating electromagnetic waves between 0.01 and 10 nanometers for medical imaging and industrial inspection. These systems require tungsten-rhenium target anodes, high-voltage generators exceeding 150 kV, and precision collimators to modulate beam geometry for tissue-specific diagnostic clarity. Digital and Direct Radiography segments command premium positioning as healthcare networks retire film-based workflows, while Computed Radiography persists in cost-sensitive clinics. Portable systems attract the fastest upgrade cycles among ambulatory surgical centers seeking point-of-care flexibility.
FDA 510(k) premarket notifications, EU MDR conformity assessments, and IEC 60601-1-3 dose safety standards collectively elevate engineering costs for new market entrants while accelerating replacement demand at accredited facilities. Japan's PMDA enforces supplemental quality audits on imported tubes, tightening access for non-domestic suppliers. Stakeholders must monitor evolving cybersecurity guidance for networked imaging architectures as hospital IT integration deepens.
Market Dynamics
Flat-panel detector miniaturization is compressing hardware footprints while expanding point-of-care deployment options, forcing manufacturers to recalibrate assembly lines toward portable architectures and away from fixed-room systems.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's updated premarket notification pathways for digital radiography systems accelerate clearance timelines for iterative hardware upgrades, reducing regulatory friction for established manufacturers.
- Oncology Screening Volumes:Hospital networks across Germany, Japan, and the United States are expanding early-detection programs, redirecting capital expenditure toward high-throughput diagnostic platforms with integrated AI-assisted image analysis.
- Tungsten-Rhenium Supply Localization:Captive semiconductor fabrication investments by dominant European and North American OEMs are securing anode material supply chains against Asian sourcing volatility.
Market Restraints
- High-Voltage Generator Concentration:Precision generator manufacturing concentrates among German and Japanese component specialists, creating single-source vulnerability for systems exceeding 150 kV output specifications.
- EU MDR Conformity Costs:Extended assessment timelines and supplemental clinical evidence requirements for Class IIa imaging devices elevate engineering budgets and delay product launches by 12-18 months.
- Computed Tomography Substitution:Cross-sectional imaging modalities are capturing diagnostic cases previously routed to projection radiography, particularly in trauma and emergency settings.
Strategic Opportunities
- Ambulatory Surgical Center Penetration:United States outpatient facilities represent underdeployed demand for battery-powered portable units with wireless DICOM transmission capabilities.
- IEC 60601-1-3 Harmonization:Converging international dose safety standards create regulatory economies of scale for manufacturers designing single-platform architectures serving multiple approval jurisdictions.
- CMOS-Scintillator Convergence:Direct deposition of cesium iodide onto CMOS active pixel sensors is enabling detector form factors previously unattainable with amorphous silicon backplanes.
Industry Challenges
- Embedded Cybersecurity Engineering:Networked imaging architectures require dedicated firmware security teams capable of implementing IEC 80001-1 risk management protocols across heterogeneous hospital IT environments.
- Legacy PACS Integration:New digital radiography deployments must maintain bidirectional compatibility with decade-old picture archiving systems, complicating software architecture decisions and extending validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Machine Manufacturing Market |
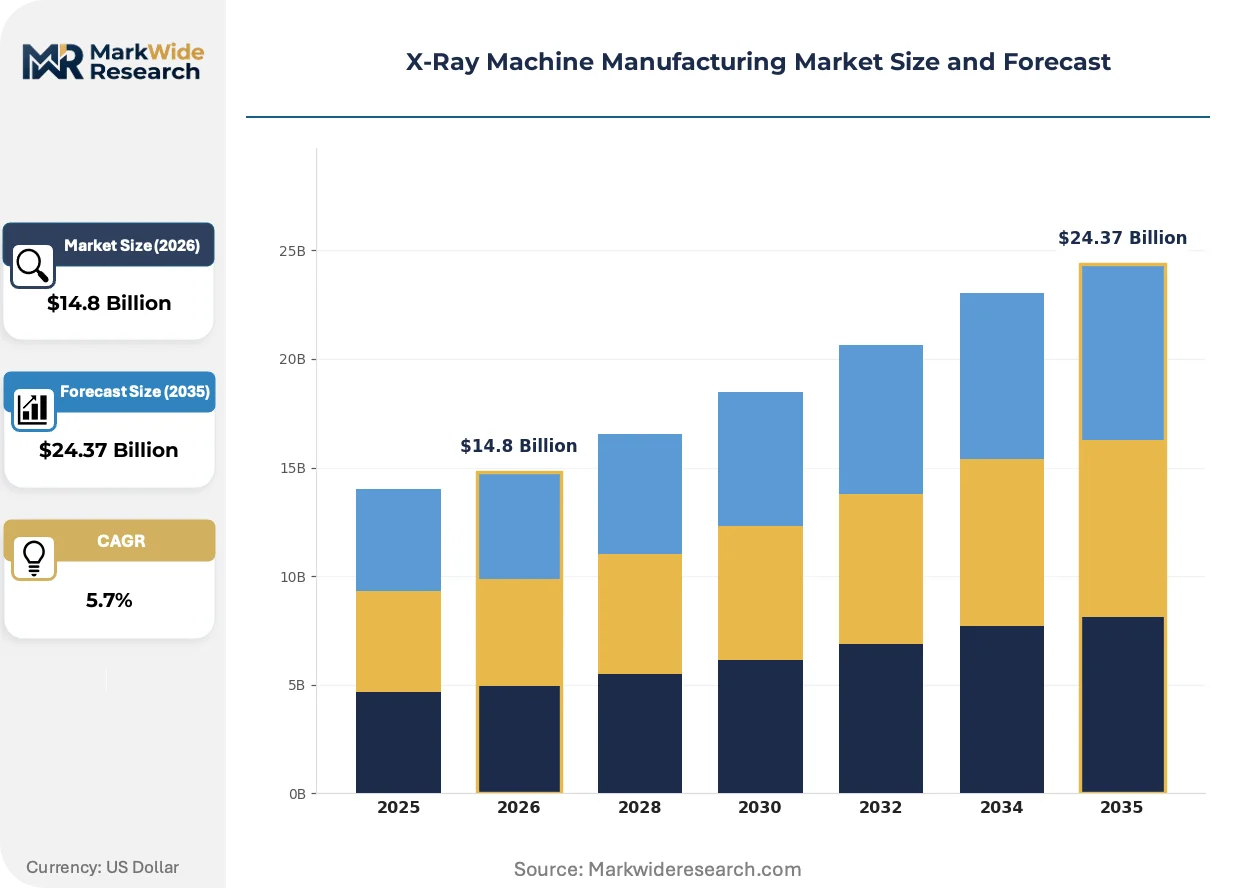
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Mobile, Handheld Technology: Analog, Digital, Computed Radiography, Direct Radiography End User: Hospitals, Clinics, Diagnostic Centers, Research Institutes Application: Cardiology, Orthopedics, Oncology, Dentistry |
| Companies Covered | Siemens AG, General Electric Company, Canon Inc., Fujifilm Holdings Corporation, Koninklijke Philips N.V., Carestream Health, Shimadzu Corporation, Hitachi Ltd., Varex Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Machine Manufacturing Market Strategic Shifts & Innovations
Detector technology convergence and regulatory harmonization are compressing product lifecycles while expanding addressable clinical settings beyond traditional radiology departments.
CMOS active pixel sensor technology is modularizing portable X-ray system architectures by enabling direct digital readout without intermediate conversion layers. Emergency departments and intensive care units are adopting these compact units for bedside imaging within 24-48 hour decision windows. The shift is modularizing supply chains, allowing manufacturers to source standardized sensor substrates from semiconductor foundries rather than specialized radiography component vendors.
The EU Medical Device Regulation's enhanced post-market surveillance requirements are mandating systematic clinical follow-up data collection for imaging systems. Manufacturers must now maintain active registries tracking device performance across installed bases, elevating quality management system costs. Digital radiography platforms with embedded remote diagnostic capabilities are capturing preference share as they reduce field service burdens and accelerate adverse event reporting.
Hospital procurement departments are consolidating vendor relationships through multi-year equipment leasing arrangements that bundle hardware, software, and predictive maintenance. Independent service organizations are losing access to proprietary diagnostic tools as OEMs restrict technical documentation. This concentration is most pronounced in United States health systems exceeding 500 beds, where standardization across facilities overrides point-of-care flexibility preferences.
X-Ray Machine Manufacturing Market Segmentation
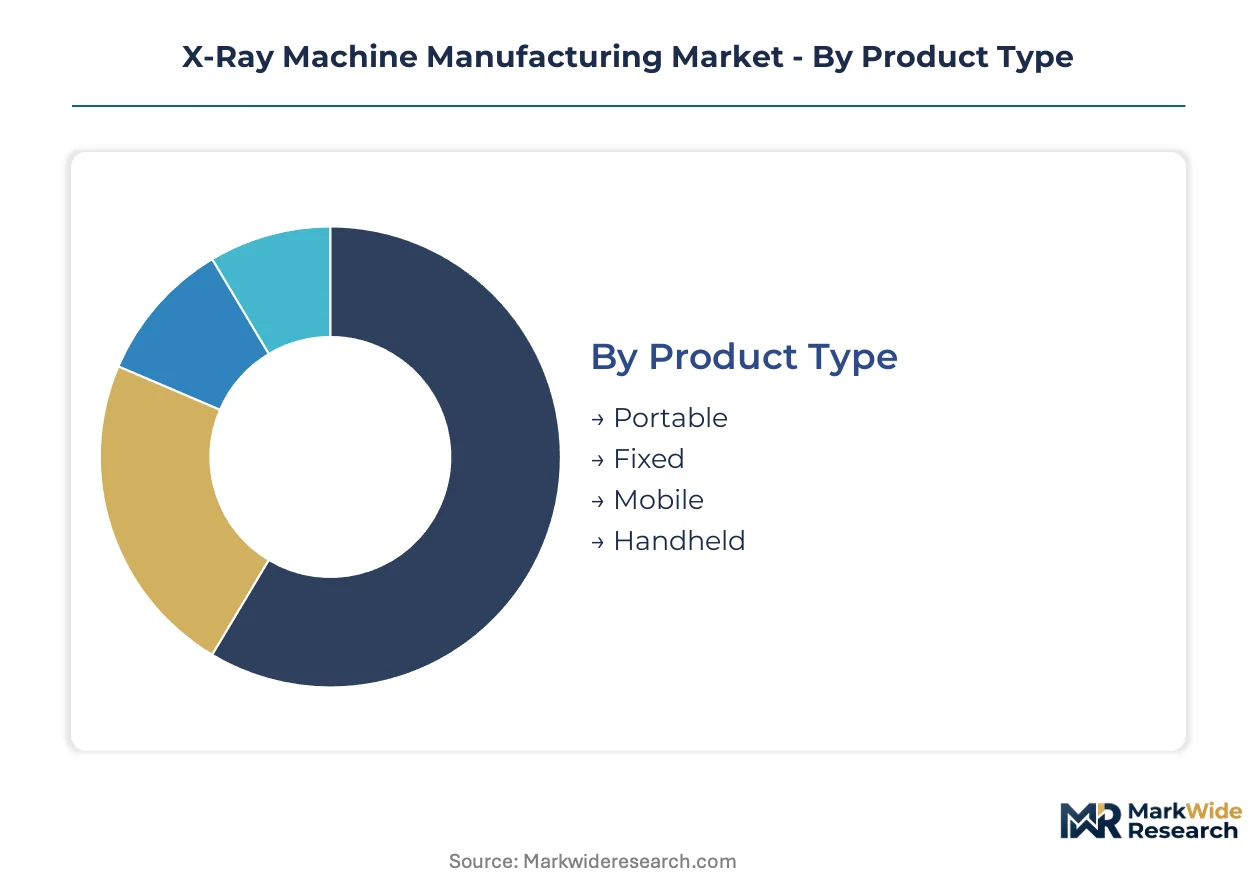
Procurement patterns diverge sharply across X-ray machine categories as hospital networks consolidate vendor relationships while ambulatory settings prioritize mobility. Buyers weigh detector resolution specifications against total cost of ownership, with regulatory clearance timelines and cybersecurity architecture now influencing selection criteria alongside traditional performance metrics.
Product Type:
Facility infrastructure constraints and point-of-care workflow requirements dictate hardware form factor selection across clinical environments.
- Portable:Battery-powered units with wireless DICOM transmission enable bedside imaging in intensive care units and emergency departments. United States ambulatory surgical centers are deploying these systems for intraoperative verification, driven by reimbursement incentives for same-day discharge protocols.
- Fixed:Ceiling-mounted or floor-mounted installations with integrated high-voltage generators exceeding 150 kV serve high-throughput radiology departments. Germany's hospital networks favor these configurations for oncology screening programs requiring sub-millimeter spatial resolution.
- Mobile:Motorized units with on-board power systems bridge the gap between fixed-room performance and portable flexibility. These systems concentrate in Japan's aging acute care facilities where elevator shaft dimensions limit fixed-room construction.
- Handheld:Compact devices weighing under 5 kilograms target extremity imaging and dental applications. Veterinary clinics and sports medicine practices represent emerging demand clusters for these ultra-portable architectures.
Volume sits with Fixed installations; growth tilts toward Portable configurations.
Technology:
Image acquisition methodology determines detector cost structure, workflow integration complexity, and regulatory classification pathways.
- Analog:Film-screen systems with chemical processing requirements persist in cost-sensitive settings and regulatory environments with delayed digital infrastructure investment. Rural clinics in developing economies maintain these installations where electricity reliability constrains electronic detector operation.
- Digital:Broad category encompassing both computed and direct radiography architectures with electronic image capture. Hospital procurement departments are standardizing on digital platforms to enable PACS integration and AI-assisted diagnostic overlays.
- Computed Radiography:Photostimulable phosphor plates with separate laser scanning readout stations offer intermediate digitization for facilities transitioning from film. These systems retain preference in low-volume imaging environments where capital constraints delay full detector replacement.
- Direct Radiography:Flat-panel detectors with immediate digital readout eliminate intermediate processing steps. CMOS active pixel sensor variants are compressing form factors for portable deployment while amorphous silicon backplanes dominate fixed-room installations.
Direct Radiography commands the steepest expansion trajectory as healthcare networks retire film-based workflows.
End User:
Capital expenditure authority and patient volume scale shape equipment specification requirements across institutional categories.
- Hospitals:Multi-modality imaging departments with 24-hour operational requirements demand redundant generator capacity and predictive maintenance contracts. United States health systems exceeding 500 beds are consolidating vendor relationships through multi-year leasing arrangements.
- Clinics:Outpatient facilities prioritize compact footprints and simplified operator interfaces for general radiography. These settings drive demand for portable units with automated exposure control to compensate for limited radiologic technologist staffing.
- Diagnostic Centers:Specialized imaging facilities with high patient throughput require rapid image acquisition and automated quality assurance protocols. Germany's independent radiology groups are deploying these systems for statutory health insurance contract fulfillment.
- Research Institutes:Preclinical and clinical trial applications demand customized beam geometry and dose calibration traceable to national standards laboratories. These installations require extensive validation documentation for regulatory submission support.
Procurement volume concentrates in Hospitals; Clinics are gaining share fastest among outpatient facility expansion.
Application:
Anatomical imaging requirements determine collimator design, detector size specifications, and specialized software algorithm needs.
- Cardiology:High-frame-rate acquisition systems with ECG-gated triggering capture coronary artery and cardiac chamber visualization. These installations require dedicated catheterization laboratory infrastructure with hemodynamic monitoring integration.
- Orthopedics:Long-length imaging capabilities and weight-bearing positioning systems support musculoskeletal diagnosis and surgical planning. Sports medicine clinics and trauma centers prioritize these configurations for fracture assessment and implant verification.
- Oncology:Low-dose protocols with iterative reconstruction algorithms enable screening program participation. Japan's prefectural health authorities are expanding these programs for lung and gastric cancer early detection.
- Dentistry:Intraoral and panoramic systems with specialized sensor geometries address maxillofacial imaging requirements. Cone-beam computed tomography variants are displacing conventional panoramic units in orthodontic and implantology practices.
Oncology applications anchor current installed base value; Orthopedics is expanding most quickly through ambulatory surgical center penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten-rhenium anode sourcing concentrates in German and Japanese component corridors, anchoring procurement decisions for high-voltage tube assemblies across diagnostic imaging networks.
United States
Ambulatory surgical centers are expanding same-day discharge protocols, redirecting capital toward battery-powered portable units with wireless DICOM transmission. FDA 510(k) streamlining accelerates clearance timelines for iterative hardware upgrades. The Southeast corridor from Florida to Georgia hosts concentrated procurement activity for point-of-care flexibility.
Germany
Hospital networks prioritize high-throughput oncology screening platforms with sub-millimeter spatial resolution for statutory health insurance contract fulfillment. EU MDR conformity assessments elevate engineering budgets for Class IIa imaging devices. Bavaria's medical technology cluster anchors Siemens AG's captive semiconductor fabrication for sensor supply chains.
Japan
Prefectural health authorities are expanding lung and gastric cancer early-detection programs, driving demand for low-dose protocols with iterative reconstruction. PMDA enforces supplemental quality audits on imported tubes, tightening access for non-domestic suppliers. Kanto region acute care facilities favor mobile units where elevator shaft dimensions limit fixed-room construction.
China
Domestic hospital networks are retiring film-based workflows at accelerating rates, compressing upgrade cycles for direct radiography platforms. NMPA registration pathways for digital radiography systems are converging toward international dose safety benchmarks. Yangtze River Delta manufacturing corridors are scaling flat-panel detector output for regional supply security.
India
Diagnostic center chains in metropolitan corridors are deploying compact digital systems to serve outpatient imaging demand with limited radiologic technologist staffing. CDSCO medical device registration requirements are tightening for imported high-voltage generators. Maharashtra and Karnataka host concentrated procurement activity for cost-sensitive clinics transitioning from computed radiography.
X-Ray Machine Manufacturing Market Key Industry Players
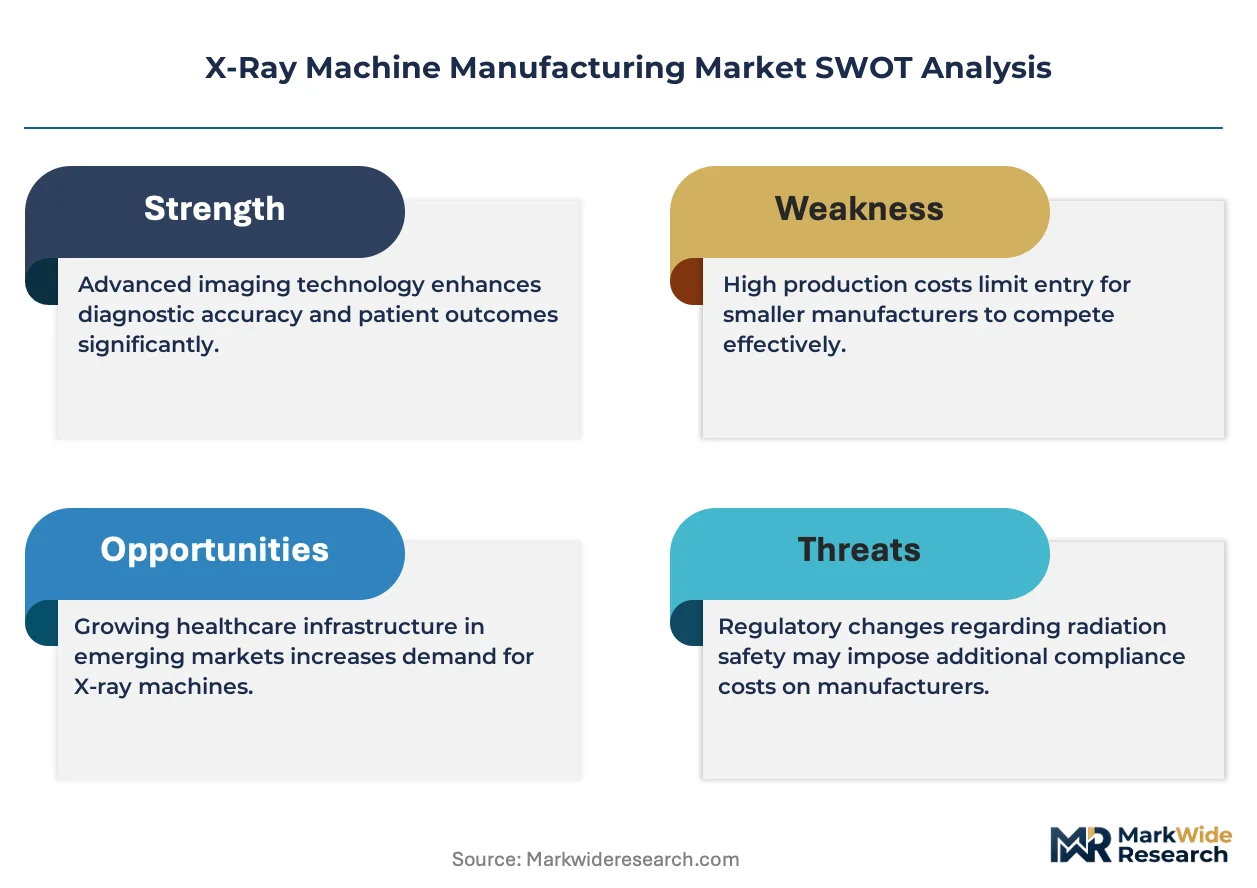
Global majors compete with regional champions across detector technology specialization and regulatory clearance velocity. Market structure tilts toward consolidated tiers where captive component fabrication separates premium-positioned OEMs from assembly-dependent competitors. Three archetypes dominate: vertically integrated conglomerates with semiconductor foundry control, specialized detector technology houses, and regional system integrators sourcing standardized sensor substrates. Dominant competitive moves include strategic partnerships for tungsten-rhenium supply security and portfolio diversification into predictive maintenance contracts.
Within the vertically integrated tier, Siemens AG and General Electric Company exemplify archetypes combining captive fabrication with predictive service ecosystems. Canon Inc. occupies a position representing CMOS detector miniaturization specialization for portable architectures. These three anchors illustrate how technology control points and service contract bundling are concentrating procurement relationships in United States health systems exceeding 500 beds.
| Leading Market Players |
|---|
| Siemens AG |
| General Electric Company |
| Canon Inc. |
| Fujifilm Holdings Corporation |
| Koninklijke Philips N.V. |
| Carestream Health |
| Shimadzu Corporation |
| Hitachi Ltd. |
| Varex Imaging |
| Others |
Cost & Logistics Intelligence
Captive semiconductor fabrication investments by Siemens AG and General Electric Company anchor both supply security and pricing power, allowing these vertically integrated OEMs to bundle predictive maintenance contracts at premium rates while assembly-dependent competitors face margin compression from tungsten-rhenium sourcing volatility.
Pricing Analysis
Service-bundling differentiation separates OEMs offering multi-year predictive maintenance contracts from vendors selling bare hardware with limited warranty coverage. Three-tier pricing structure across premium, standard, and economy levels tracks detector resolution specifications and cybersecurity certification tiers. Cost compression in economy-tier portable units is intensifying because Asian manufacturers are scaling flat-panel detector output. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while United States health systems exceeding 500 beds prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Reverse-logistics networks for flat-panel detector refurbishment and high-voltage generator remanufacturing are extending component lifecycles while creating secondary revenue streams for OEMs with field service infrastructure. Tungsten-rhenium anode sourcing concentrates in Germany and Japan, with CMOS active pixel sensor substrates drawing from Taiwan and South Korea. Single-source vulnerability persists for precision generators exceeding 150 kV output specifications. Distribution runs through hospital procurement departments consolidating vendor relationships and independent service organizations losing access to proprietary diagnostic tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The X-Ray Machine Manufacturing Market functions as a cost-of-compliance arena where EU MDR conformity assessments for Class IIa imaging devices create 12-18 month launch delays that protect incumbent positions against undercapitalized entrants lacking quality management system infrastructure.
For Market Incumbents: Lock in tungsten-rhenium supply security through backward integration or long-term offtake agreements with German and Japanese component specialists. Expand predictive maintenance contract penetration in United States health systems exceeding 500 beds to defend against independent service organizations gaining detector refurbishment capabilities. Prioritize IEC 80001-1 cybersecurity certification investment as hospital IT integration deepens.
For New Entrants and Emerging Players: Launch via portable unit specialization targeting United States ambulatory surgical centers with battery-powered architectures and wireless DICOM transmission capabilities. Exploit underpenetrated demand for handheld extremity imaging systems in veterinary clinics and sports medicine practices. Pursue CMOS-scintillator convergence partnerships with semiconductor foundries to bypass specialized radiography component vendor dependencies.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated conglomerates seeking detector technology specialization or regional system integrators requiring captive semiconductor fabrication capabilities. Long-term viability favors OEMs with predictive service ecosystems and hospital procurement department relationships. Monitor FDA 510(k) clearance velocity differentials between established manufacturers and emerging entrants as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication Investment | Siemens AG secures sensor supply chains against Asian sourcing volatility through in-house production. |
| Predictive Maintenance Contract Expansion | General Electric Company anchors North American installed base through multi-year service bundling arrangements. |
| CMOS Detector Miniaturization R&D | Canon Inc. enables portable form factors previously unattainable with amorphous silicon backplane architectures. |
| FDA 510(k) Streamlining Utilization | Established manufacturers accelerate iterative hardware upgrade clearance timelines against regulatory friction. |
| Ambulatory Surgical Center Partnership | Battery-powered portable unit deployments capture reimbursement incentives for same-day discharge protocols. |
Research Approach
Independent corroboration across FDA 510(k) premarket notification databases, EU MDR conformity assessment records, and hospital procurement contract registries underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and aftermarket service heads combined with secondary validation from IEC standards documentation, PMDA quality audit reports, and CMS Medicare imaging utilization data. Bottom-up installation base modeling and top-down healthcare capital expenditure triangulation anchor volume estimates.
Comparable-period anchoring to historical replacement cycle data and regulatory transition timelines structures the projection methodology across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user institution category, and application-specific detector configuration. CAGRs derive from installed base growth rates, retirement timing of analog and computed radiography systems, and penetration assumptions for AI-assisted diagnostic overlays. Forecast inputs incorporate tungsten-rhenium supply constraints and EU MDR assessment timeline distributions.
The model assumes a particular technology adoption path; alternative pathways for CMOS-scintillator convergence or direct radiography platform substitution would alter the outlook. Forecasts reflect assumptions regarding oncology screening program expansion rates and cybersecurity compliance enforcement intensity. Practitioners should monitor FDA cybersecurity guidance evolution and PMDA import audit stringency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Medical Physics Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Tissue Culture Incubator Market