
 Asia-Pacific Medical Device Reprocessing Market | 2026-2036
Asia-Pacific Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Device Reprocessing Market Outlook
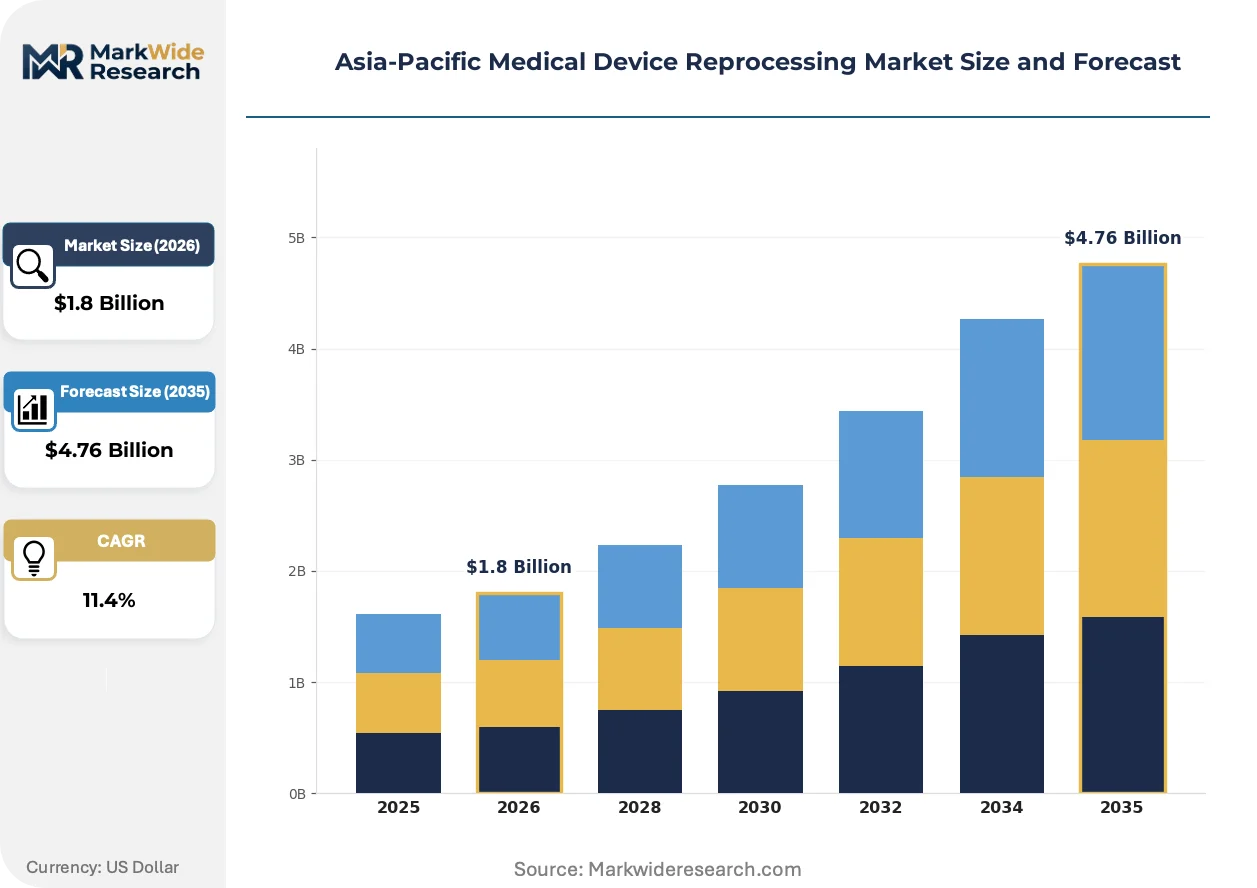
Ambulatory surgery centers are reorganizing procurement priorities across the Asia-Pacific Medical Device Reprocessing Market, shifting volume away from traditional hospital supply chains toward specialized third-party sterilization contracts. Stryker Corporation sustains technology leadership in validated reprocessing protocols for complex electrosurgical devices. Johnson & Johnson leverages its broad infection prevention portfolio to anchor multi-year service agreements with large hospital networks. Cardinal Health competes on geographic density, operating regional sterilization hubs that reduce logistics costs for clinic chains.
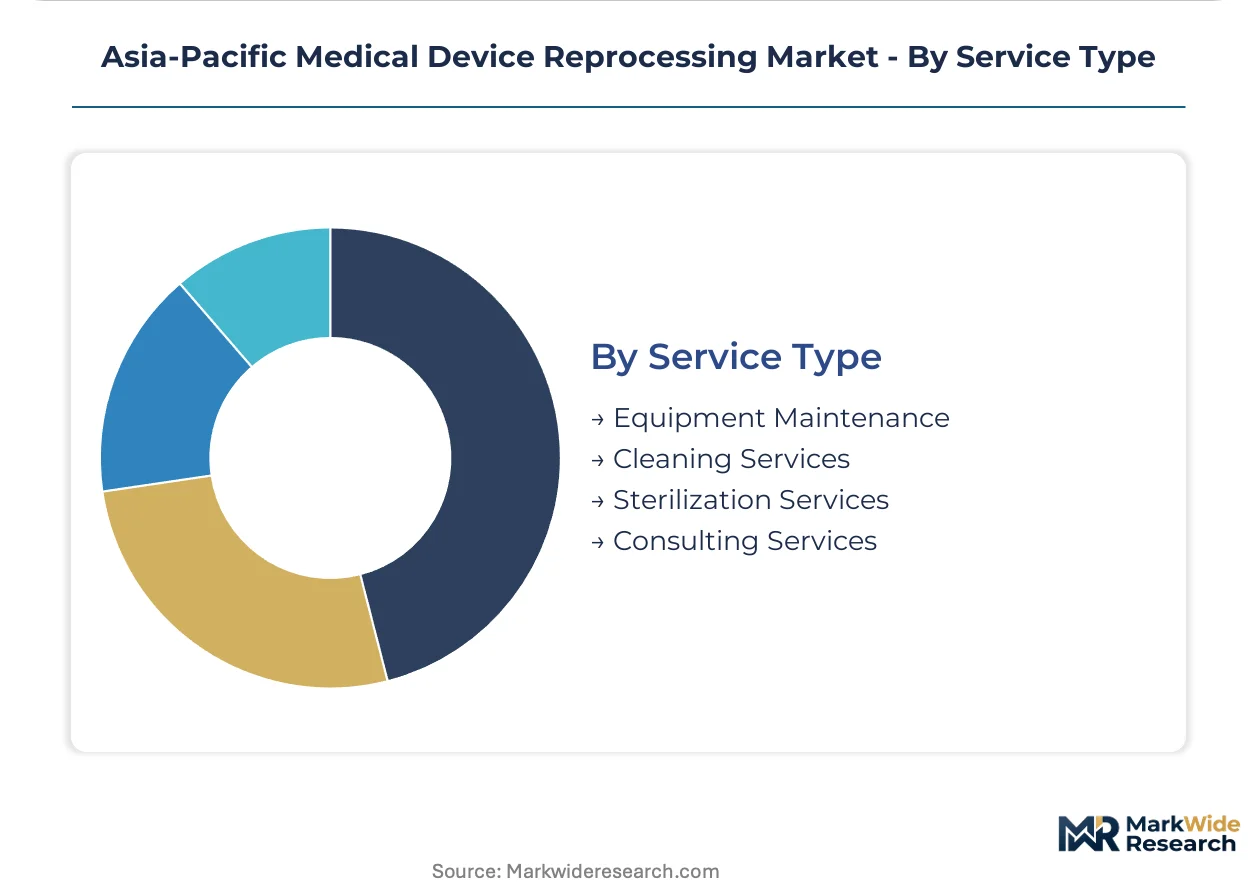
Medical device reprocessing encompasses the cleaning, functional testing, repackaging, and sterilization of pre-owned medical devices to restore them to safe reusable condition, governed by strict bioburden reduction parameters and material compatibility thresholds. Its primary commercial purpose is to extend device life cycles while maintaining clinical performance equivalent to original manufacture. Surgical instruments and endoscopes command the largest current revenue pools, though catheters represent the fastest-expanding product category as polymer validation protocols mature. Among service types, sterilization services capture disproportionate margins due to capital-intensive barrier requirements, while consulting services remain nascent but gain traction where regulators mandate quality system overhauls.
Japan's PMDA, India's CDSCO, and China's NMPA each enforce distinct sterility assurance levels and traceability standards that determine which reprocessors qualify for national procurement tenders. The EU MDR's extraterritorial influence on Asia-Pacific exporters additionally pressures manufacturers to align reprocessing documentation with European notified body expectations. Stakeholders must monitor divergent national validation timelines and pre-position compliance infrastructure ahead of anticipated regulatory convergence.
Market Dynamics
Centralized hospital procurement networks across China, India, and Japan are consolidating reprocessing contracts, displacing fragmented vendor relationships and forcing sterilization providers to scale compliance infrastructure ahead of regulatory tightening.
Growth Catalysts
- CDSCO sterility mandates:India's tightened bioburden reduction requirements are accelerating investments in validated reprocessing protocols among domestic sterilization facilities.
- Ambulatory surgery expansion:Outpatient procedure volumes across Thailand, Malaysia, and Vietnam are creating dedicated demand for third-party reprocessing services outside traditional hospital supply chains.
- Polymer validation maturation:Advanced compatibility testing for catheter materials is expanding the addressable device pool beyond metals and rigid endoscopes.
Market Restraints
- Ethylene oxide supply concentration:Sterilant gas production clusters in select Chinese chemical hubs create input cost volatility for regional sterilization operators.
- PMDA traceability requirements:Japan's device-level tracking mandates impose documentation burdens that smaller reprocessors struggle to satisfy.
- Single-use device substitution:Original manufacturers are engineering lower-cost disposable alternatives to defend against reprocessing economics.
Strategic Opportunities
- Indonesia's hospital network expansion:Government-funded healthcare infrastructure buildout is creating first-mover advantages for sterilization providers establishing regional hubs.
- EU MDR alignment services:Asia-Pacific exporters require reprocessing documentation retrofitting to satisfy European notified body expectations.
- Automated cleaning systems:Robotics integration with existing washer-disinfector infrastructure is reducing labor dependency and cycle time variability.
Industry Challenges
- Biomedical engineering talent scarcity:Qualified validation specialists capable of polymer-specific sterility assurance testing remain concentrated in Japan and Australia.
- Legacy equipment integration:Hospital sterilization departments face workflow disruption when connecting automated tracking systems to existing steam sterilizers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Device Reprocessing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Endoscopes, Electrosurgical Devices, Catheters Application: Hospitals, Clinics, Ambulatory Surgery Centers, Laboratories Technology: Steam Sterilization, Ethylene Oxide, Hydrogen Peroxide, Ozone Sterilization Service Type: Equipment Maintenance, Cleaning Services, Sterilization Services, Consulting Services |
| Companies Covered | Medline Industries, Stryker Corporation, Johnson & Johnson, NEScientific, ReNu Medical, Sterilmed, Hygia Health Services, SureTek Medical, Cardinal Health, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Device Reprocessing Market Strategic Shifts
Reprocessing technology is converging with digital traceability and automated quality systems, compressing cycle times while expanding the categories of devices deemed suitable for safe reuse.
Low-temperature hydrogen peroxide plasma sterilization is miniaturizing from centralized hospital installations to compact units deployable in ambulatory settings. ASC chains in South Korea and Taiwan are adopting these systems to process electrosurgical instruments on-site. The technology is miniaturizing capital requirements and enabling point-of-care reprocessing that bypasses third-party logistics entirely.
PMDA's revised sterility assurance guidelines now mandate real-time environmental monitoring data submission for reprocessing facility licensure. Japanese hospital networks are retrofitting existing sterilization departments with continuous particle counting and biological indicator automation. Electrosurgical device reprocessors face the steepest compliance burden, as these instruments require documented material integrity verification beyond standard bioburden testing.
Hospital procurement departments are consolidating reprocessing contracts under multi-year service agreements that bundle sterilization, logistics, and regulatory documentation. Specialized third-party providers are displacing fragmented local vendors in China's provincial hospital networks. This concentration is most visible in Jiangsu and Zhejiang provinces, where centralized tendering platforms now pre-qualify only reprocessors with national-scale sterility validation capabilities.
Asia-Pacific Medical Device Reprocessing Market Segmentation
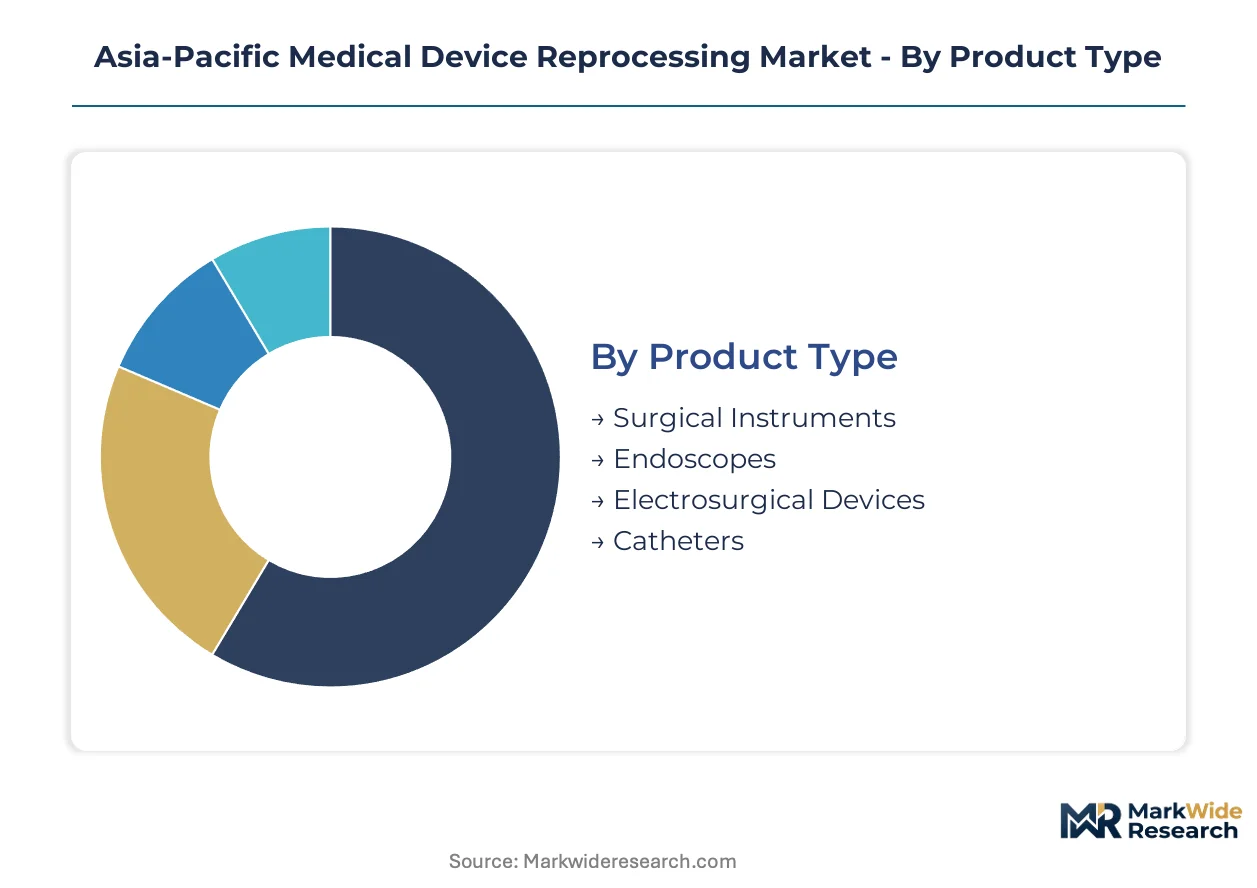
Segmentation in the Asia-Pacific Medical Device Reprocessing Market reveals where substitute threats from single-use alternatives concentrate versus where durable device economics retain structural advantage. Understanding these pressure gradients guides capital allocation across sterilization infrastructure and validation capabilities.
Product Type:
Substitution pressure from original equipment manufacturers varies sharply across device categories, with polymer-based instruments facing the most aggressive disposable competition.
- Surgical Instruments:Stainless steel and tungsten carbide instruments dominate current reprocessing volumes across China's provincial hospital networks. Metal durability supports hundreds of reuse cycles, insulating this segment from single-use substitution despite OEM price-cutting on basic forceps and clamps.
- Catheters:Polyurethane and silicone catheter reprocessing is expanding most quickly as compatibility testing protocols mature for balloon and diagnostic variants. Thailand's cardiac catheterization labs are adopting validated reprocessing for electrophysiology devices, though peripheral vascular catheters remain vulnerable to lower-cost disposable alternatives from domestic Chinese manufacturers.
- Endoscopes:Flexible gastrointestinal and bronchoscopy devices require complex channel cleaning and leak testing that preserves reprocessing economics against disposable competition.
- Electrosurgical Devices:Handpiece and electrode reprocessing concentrates in Japan and South Korea where PMDA validation requirements create barriers to entry for substitute products.
Surgical instruments retain volume leadership; catheters hold the steepest expansion curve.
Application:
Procurement centralization across customer types is redistributing contract scale and margin concentration toward institutional buyers with national tendering authority.
- Hospitals:China's provincial centralized procurement platforms and India's government hospital networks aggregate sterilization demand into multi-year service agreements. CDSCO's sterility assurance mandates are forcing hospital biomedical departments to outsource complex device validation to specialized third-party providers.
- Ambulatory Surgery Centers:Outpatient procedure growth across Malaysia, Vietnam, and Indonesia is fragmenting demand geographically while creating volume for regional sterilization hubs. ASC chains in South Korea are deploying compact hydrogen peroxide plasma units for on-site electrosurgical instrument processing.
- Clinics:Dialysis and dental clinics in the Philippines and Indonesia rely on third-party logistics networks for device collection and return.
- Laboratories:Research and diagnostic facilities in Australia and Singapore generate specialized demand for high-containment sterilization of biosafety level equipment.
Hospitals retain volume leadership; ambulatory surgery centers hold the steepest expansion curve.
Technology:
Capital intensity and sterilant supply security differentiate technology tiers, with gas-based methods facing input concentration risks that steam alternatives avoid.
- Steam Sterilization:Saturated steam under pressure remains the dominant technology for metal surgical instruments across India's CDSCO-regulated facilities. The method's lower capital requirements and absence of chemical residuals suit high-throughput hospital central sterile supply departments.
- Ethylene Oxide:Heat-sensitive polymer devices require this low-temperature gas sterilization, though production concentration in select Chinese chemical hubs creates supply volatility for regional operators. Japanese PMDA facilities maintain redundant sterilant inventories to mitigate this concentration risk.
- Hydrogen Peroxide:Plasma and vapor-phase systems are miniaturizing for ambulatory deployment in Taiwan and South Korea.
- Ozone Sterilization:Emerging applications in water-sensitive electronics and certain endoscope categories remain limited by cycle time constraints.
Steam sterilization retains volume leadership; hydrogen peroxide holds the steepest expansion curve.
Service Type:
Margin capture across the service stack correlates with regulatory documentation burden and capital barrier height.
- Sterilization Services:Validated terminal sterilization commands premium pricing due to bioburden validation requirements and continuous environmental monitoring mandates. Japan's PMDA real-time data submission rules for facility licensure have elevated compliance costs that only national-scale providers can amortize.
- Consulting Services:Quality system overhauls and EU MDR documentation alignment for Asia-Pacific exporters represent the fastest-climbing service category. Indian sterilization facilities preparing for CDSCO inspections and European notified body audits drive demand for validation protocol design.
- Cleaning Services:Pre-sterilization decontamination and functional testing precede terminal sterilization in most reprocessing workflows.
- Equipment Maintenance:Washer-disinfector and sterilizer calibration contracts anchor long-term vendor relationships.
Sterilization services retain volume leadership; consulting services hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports sterilization equipment and reprocessed device components to Southeast Asian hospital networks, establishing the dominant trade corridor in the Asia-Pacific medical device reprocessing ecosystem.
China
Provincial centralized procurement platforms in Jiangsu and Zhejiang aggregate hospital demand into multi-year sterilization contracts. NMPA traceability mandates for high-risk devices force domestic reprocessors to upgrade documentation systems. Shanghai-based sterilization hubs serve as collection points for catheter reprocessing bound for regional hospital networks.
India
Government hospital networks and private hospital chains drive sterilization outsourcing as procedure volumes climb. CDSCO sterility assurance requirements accelerate compliance investments among domestic reprocessing facilities. Gujarat's medical device manufacturing clusters host specialized sterilization subcontractors serving export-oriented instrument makers.
Japan
PMDA's real-time environmental monitoring rules elevate facility licensure costs that only national-scale providers absorb. Electrosurgical device reprocessing concentrates in Kansai region facilities with validated material integrity protocols. Osaka-based sterilization operators maintain redundant ethylene oxide inventories to mitigate supply concentration risks.
South Korea
Ambulatory surgery center chains deploy compact hydrogen peroxide plasma systems for on-site electrosurgical instrument processing. MFDS validation requirements for polymer device compatibility testing create barriers to entry for substitute products. Seoul Capital Area sterilization hubs serve ASC networks expanding into secondary cities.
Australia
TGA-regulated facilities generate specialized demand for high-containment sterilization of biosafety level laboratory equipment. Research and diagnostic institutions in New South Wales and Victoria outsource complex device validation to third-party providers. Sydney-based sterilization operators anchor service agreements with academic medical centers.
Asia-Pacific Medical Device Reprocessing Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and compliance infrastructure dimensions, producing a tiered structure where scale advantages concentrate in sterilization services while consulting and equipment maintenance segments host fragmented regional players. Three strategic archetypes dominate: multinational healthcare conglomerates with integrated infection prevention portfolios, specialized third-party sterilization providers with regional hub networks, and domestic reprocessors serving single-country procurement systems. Competitive moves center on multi-year service agreement consolidation and automated tracking system deployment to satisfy real-time regulatory data submission requirements.
Among multinational healthcare conglomerates, Stryker Corporation and Johnson & Johnson occupy positions as archetype anchors for validated reprocessing protocol development. Cardinal Health exemplifies the regional hub specialist model with sterilization infrastructure designed for geographic density and logistics cost reduction. These three companies represent the scale-driven tier where compliance infrastructure investments amortize across national hospital network contracts.
| Leading Market Players |
|---|
| Medline Industries |
| Stryker Corporation |
| Johnson & Johnson |
| NEScientific |
| ReNu Medical |
| Sterilmed |
| Hygia Health Services |
| SureTek Medical |
| Cardinal Health |
| Others |
Value Chain & Pricing Dynamics
Multi-year service agreements with centralized procurement platforms lock in sterilization capacity for hospital networks across Jiangsu and Zhejiang provinces while capping annual price escalations. These contracts bundle terminal sterilization, logistics, and regulatory documentation into predictable cost structures that insulate buyers from ethylene oxide supply volatility.
Pricing Analysis
Next-generation hydrogen peroxide plasma systems command premiums over steam sterilization baselines, though prior-generation ethylene oxide contracts face cost compression from sterilant supply concentration in Chinese chemical hubs. Pricing stratifies across PMDA-validated, CDSCO-compliant, and non-certified facility tiers, with Japan's real-time monitoring mandates elevating compliance premiums. Margins are tightening for smaller reprocessors unable to amortize environmental monitoring infrastructure across national-scale contracts. Ambulatory surgery centers exhibit highest price sensitivity due to fragmented volumes, while integrated hospital networks accept premium pricing for bundled compliance assurance.
Supply Chain Analysis
China and India anchor regional sterilization equipment manufacturing, with Shanghai and Gujarat hosting specialized washer-disinfector and sterilizer production clusters. Ethylene oxide feedstock draws from concentrated petrochemical complexes in Shandong and Jiangsu provinces, creating single-source vulnerability for regional operators. Japanese facilities mitigate this risk through redundant sterilant inventories and diversified gas supplier relationships. Distribution runs through provincial hospital procurement platforms in China and third-party logistics networks for ASC chains across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific medical device reprocessing market sits at an early-cycle expansion phase propelled by ambulatory surgery center proliferation outside traditional hospital supply chains. Penetration remains shallow in Indonesia's government-funded hospital buildout and Vietnam's outpatient clinic networks.
For Market Incumbents: Consolidate multi-year service agreements with China's provincial centralized procurement platforms before CDSCO and PMDA compliance requirements escalate facility licensure costs. Acquire automated environmental monitoring capabilities to satisfy real-time data submission mandates. Backward integration into ethylene oxide storage infrastructure defends margin position against sterilant supply volatility from Chinese chemical hub concentration. For New Entrants and Emerging Players: Anchor in Indonesia's hospital network expansion, where government-funded infrastructure buildout creates first-mover advantages for regional sterilization hubs lacking established vendor relationships. Target consulting services for EU MDR documentation alignment, the fastest-climbing segment where validation protocol design expertise commands premium pricing. Pursue partnerships with domestic catheter manufacturers in Thailand seeking polymer compatibility testing capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors national-scale sterilization providers with amortized compliance infrastructure over fragmented regional operators. Long-term viability hinges on exposure to centralized procurement contract flows rather than spot-market ASC volumes. Monitor CDSCO inspection timelines and PMDA facility licensure approvals as inflection indicators for competitive position shifts.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Facility Licensure Investment | Real-time environmental monitoring compliance unlocks access to Japan's electrosurgical device reprocessing tenders. |
| CDSCO Validation Protocol Development | Pre-positioning for India's tightened bioburden reduction requirements accelerates hospital outsourcing decisions. |
| Regional Hub Expansion in Indonesia | Government-funded hospital networks create captive demand for sterilization services in underserved provinces. |
| EU MDR Documentation Alignment Services | Asia-Pacific exporters require retrofitting reprocessing records to satisfy European notified body expectations. |
| Automated Cleaning System Integration | Robotics deployment with existing washer-disinfector infrastructure reduces labor dependency for high-throughput facilities. |
Study Parameters
The analysis maps sterilization services, consulting services, cleaning services, and equipment maintenance segments, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and third-party sterilization facility operators. Primary interviews with these stakeholders combined secondary sources including CDSCO regulatory filings, PMDA facility licensure databases, hospital procurement platform records, and customs trade data for sterilization equipment imports. Bottom-up facility capacity estimates triangulated against top-down provincial healthcare expenditure allocations.
Consistency checks validated volume and value outputs against external benchmarks including national healthcare infrastructure investment disclosures and ASC chain expansion announcements. The projection horizon spans product type, application, technology, and service type dimensions, with CAGRs derived from regression analysis of historical sterilization outsourcing penetration rates and forward assumptions for regulatory compliance cost trajectories. Ethylene oxide supply concentration indices and polymer validation protocol maturation timelines informed technology-specific growth differentials.
Decision-makers should treat outputs as directional under assumptions of continued regulatory tightening and ambulatory surgery volume expansion; material deviation in sterilant supply security or single-use device substitution rates would warrant model refresh. Recalibration cycles align with material shifts in CDSCO enforcement intensity and PMDA guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Medical Physics Market
Medical Equipment
Water Bath Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Medical Tubing Market