
 Global Medical Power Supply Market | 2026-2036
Global Medical Power Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Power Supply Market Foresight
The gap between premium and commodity tiers is broadening as hospitals demand IEC 60601-1 certified isolated power supplies while cost-sensitive clinics accept basic AC-DC units. XP Power leverages its programmable platform to capture high-reliability diagnostic imaging contracts. Delta Electronics anchors its position through captive magnetics manufacturing in Asia. TDK-Lambda differentiates via medical-grade modular systems that reduce field failure rates.
Medical power supply denotes purpose-built electrical conversion equipment engineered to deliver stable, low-noise output with patient-safety isolation, typically achieving leakage current below 300 microamperes and dielectric strength per IEC 60601-1. Switch-mode technology dominates volume due to compact footprint and efficiency above 85 percent, yet linear power supplies retain share in precision laboratory instruments where electromagnetic interference must approach zero. Patient monitoring applications pull the fastest growth as ambulatory surgical centers and home care settings multiply device counts per bed. Diagnostic imaging sustains the largest revenue pool because CT and MRI systems require multi-kilowatt programmable supplies with active power factor correction.
FDA 510(k) clearance timelines and the EU Medical Device Regulation reshape product development cycles, forcing suppliers to front-load clinical validation documentation. IEC 60601-1 third edition leakage limits and emerging EU AI Act requirements for software-integrated power management will filter vendor participation. Stakeholders must track whether emerging economies adopt harmonized standards or erect country-specific testing barriers that fragment certification budgets.
Market Dynamics
Switch-mode power conversion is compressing product lifecycles as hospitals demand higher efficiency from smaller footprints, forcing suppliers to requalify designs against IEC 60601-1 third edition leakage limits within compressed FDA 510(k) windows.
Growth Catalysts
- Home Healthcare Expansion:Ambulatory surgical centers and remote patient monitoring platforms in the United States and Germany are multiplying device counts per care setting, pulling compact isolated supplies into distributed care networks.
- EU Medical Device Regulation:MDR harmonization across European member states is consolidating procurement toward pre-certified suppliers, filtering out uncertified competitors and concentrating contract awards.
- Diagnostic Imaging Upgrades:CT and MRI system replacements in Japan are requiring multi-kilowatt programmable supplies with active power factor correction, sustaining premium-tier demand.
Market Restraints
- Magnetics Supply Concentration:Ferrite core and transformer winding capacity concentrates in East Asian contract manufacturers, exposing lead-time volatility for isolated designs.
- IEC 60601-1 Third Edition Compliance Burden:Dielectric testing and leakage current validation protocols extend development cycles by four to six months for new product introductions.
- Linear Supply Residual Share:Electromagnetic interference-sensitive laboratory instruments retain demand for legacy linear architectures, fragmenting R&D allocation across competing topologies.
Strategic Opportunities
- Brazil Diagnostic Infrastructure:ANVISA regulatory alignment with IEC standards is opening procurement pathways for pre-certified suppliers in Latin America's largest healthcare market.
- EU AI Act Integration:Software-integrated power management systems with predictive maintenance capabilities qualify for preferential positioning in European hospital tenders.
- Direct Hospital Contracting:Bypassing traditional distribution layers through group purchasing organization partnerships is capturing margin in the United States acute care segment.
Industry Challenges
- EMC Engineering Talent Scarcity:Electromagnetic compatibility design expertise for medical-grade isolation is concentrating at a handful of specialist firms, inflating recruitment costs.
- Legacy System Integration:New switch-mode supplies must interface with fifteen-to-twenty-year-old diagnostic platforms without triggering ground fault interruptions, complicating field retrofit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Power Supply Market |
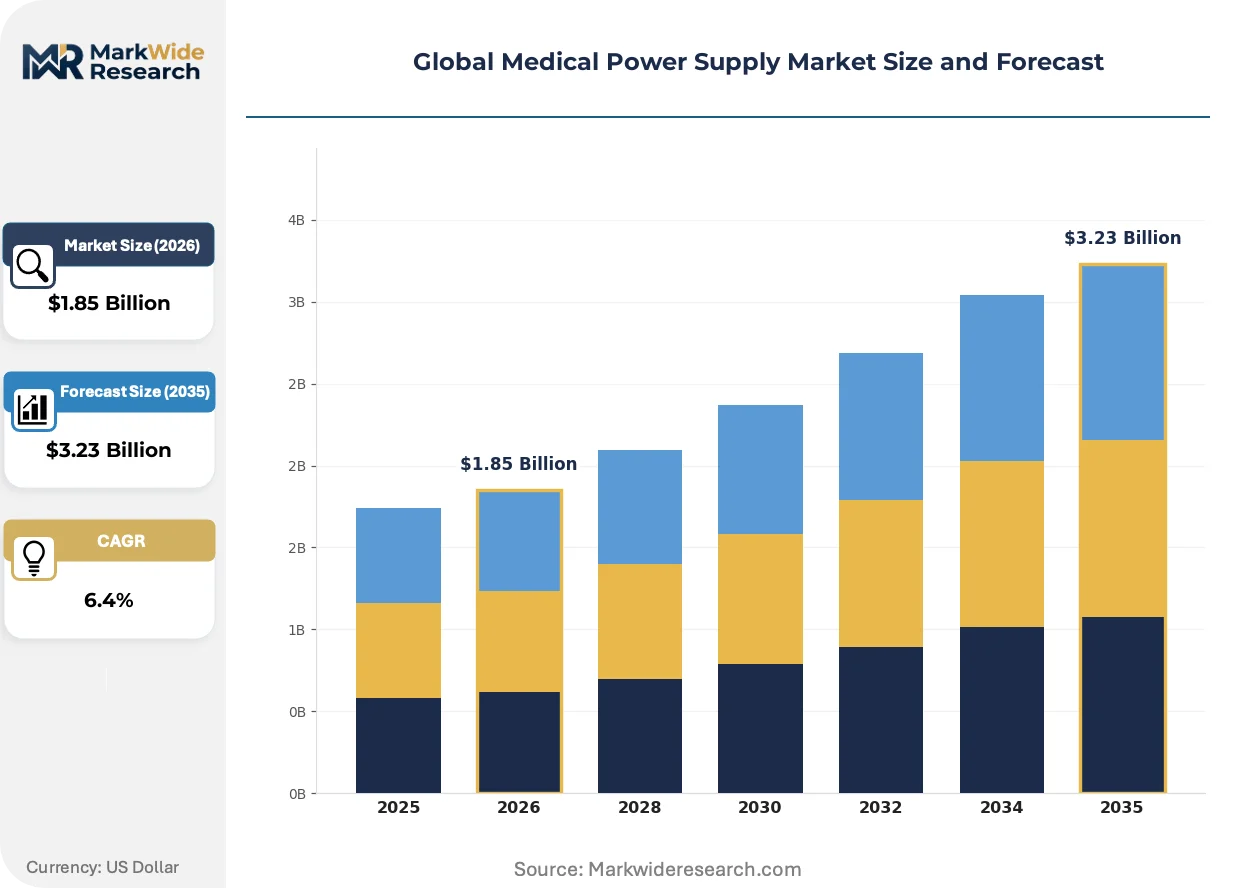
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC-DC Power Supply, DC-DC Converters, Battery Backup Systems, Uninterruptible Power Supplies, Charging Stations Application: Diagnostic Imaging, Patient Monitoring, Surgical Equipment, Laboratory Instruments, Therapeutic Devices Technology: Switch Mode, Linear Power Supplies, Modular Systems, Programmable Power Supplies, Isolated Power Supplies End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Laboratories, Healthcare Clinics |
| Companies Covered | Advanced Energy Industries Inc., XP Power, Delta Electronics Inc., TDK-Lambda Corporation, SL Power Electronics Corp, Spellman High Voltage Electronics Corporation, Astrodyne TDI, MEAN WELL Enterprises Co. Ltd., COSEL Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Power Supply Market Shifts & Advancements
Digital control architectures and wide-bandgap semiconductors are redefining efficiency benchmarks while regulatory software mandates are embedding compliance deeper into hardware design cycles.
GaN-based switching topologies are consolidating 100-watt to 500-watt medical adapter segments by enabling 94-percent efficiency at half the volume of silicon MOSFET equivalents. Ambulatory device manufacturers in Germany and the United States are qualifying these designs for portable ultrasound and infusion pump applications. The technology is consolidating mid-power supply tiers into unified platforms that span multiple diagnostic categories.
The EU AI Act's risk classification framework is mandating algorithmic transparency for power management software in Class IIb and Class III devices. Suppliers must document decision logic for adaptive voltage scaling and fault-response protocols. Diagnostic imaging OEMs serving European markets are front-loading software validation to preempt notified body scrutiny.
Hospital procurement departments are unbundling after-sales service contracts from hardware acquisition, negotiating separate multi-year maintenance agreements with third-party clinical engineering firms. This disintermediation is compressing upfront equipment margins while extending revenue visibility for suppliers with certified field service networks. The pattern is most pronounced in United States academic medical centers and Japanese university hospitals.
Global Medical Power Supply Market Segmentation
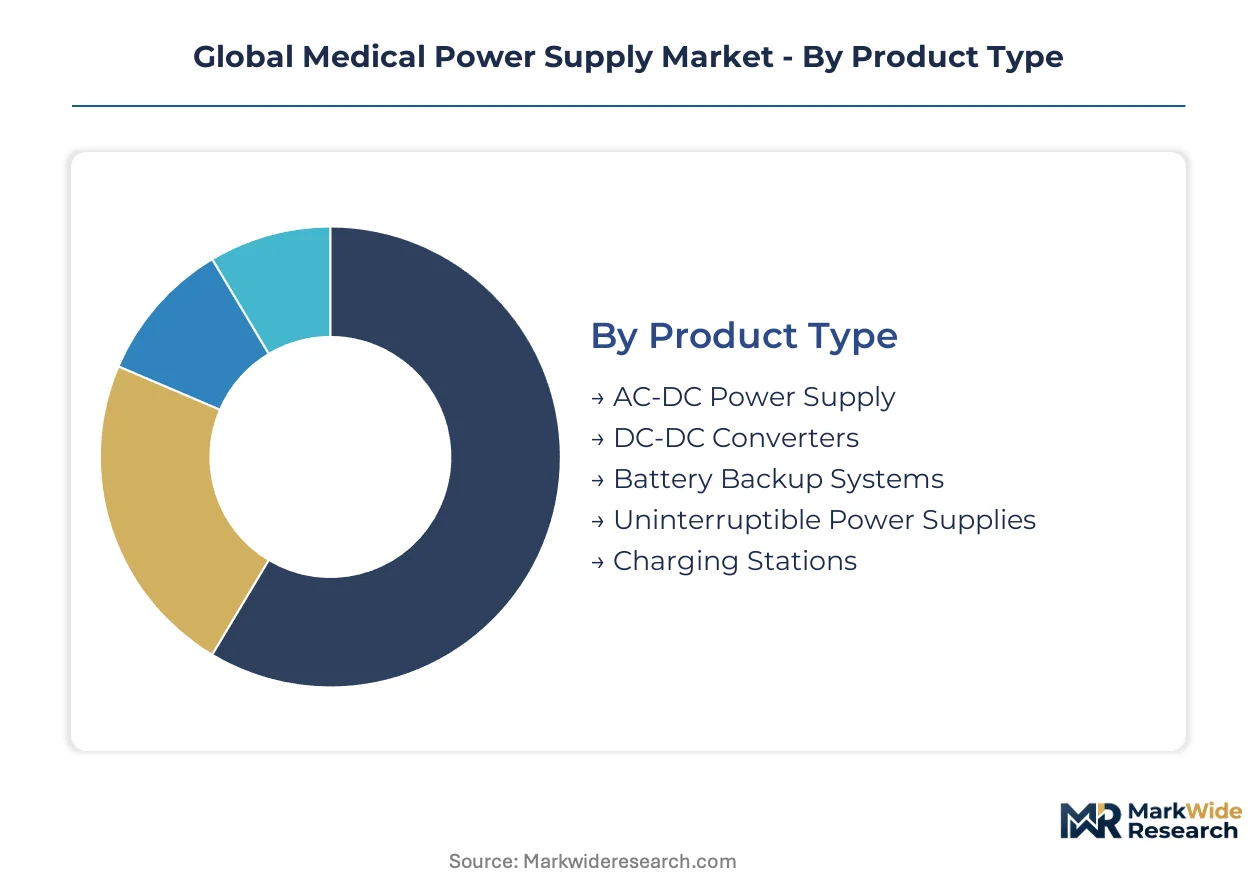
Medical power supply segmentation reveals how regulatory requirements, clinical workflows, and infrastructure constraints fragment procurement patterns across healthcare delivery settings. Understanding these divides helps suppliers align certification investments with addressable revenue pools.
Product Type:
Electrical conversion architectures determine isolation performance, efficiency ceilings, and form-factor constraints across clinical environments.
- AC-DC Power Supply:Wall-plug and rack-mounted units convert mains voltage to isolated low-voltage DC with active power factor correction. Demand concentrates in United States hospitals replacing aging linear supplies in patient monitoring bays, driven by IEC 60601-1 third edition leakage current mandates.
- DC-DC Converters:Point-of-load modules step voltage between internal system rails while maintaining patient isolation barriers. German diagnostic imaging OEMs specify these for distributed power architectures in CT gantries, where space constraints and thermal management dominate design tradeoffs.
- Battery Backup Systems:Lithium-ion and lead-acid storage units bridge utility interruptions for life-support equipment.
- Uninterruptible Power Supplies:Online double-conversion systems deliver zero-transfer-time backup for surgical suites and critical care units.
- Charging Stations:Docking infrastructure for mobile medical carts and portable diagnostic devices.
Mature deployment sits with AC-DC Power Supply. Newer deployment is concentrated in DC-DC Converters.
Application:
Clinical use cases impose divergent electrical noise, reliability, and regulatory burdens on power subsystem selection.
- Diagnostic Imaging:CT, MRI, and PET systems demand multi-kilowatt programmable supplies with active power factor correction and <0.5% output ripple. Japanese university hospitals are upgrading aging Toshiba and Hitachi installations, sustaining premium-tier procurement for 80-150kW combined system loads.
- Patient Monitoring:Bedside and wearable devices require compact isolated supplies below 50W with sub-100-microampere leakage currents. Ambulatory surgical centers in Germany and the United States are multiplying device counts per bed, expanding the fastest-growing application segment.
- Surgical Equipment:Electrosurgical generators and laser systems need high-peak-current capability with fast transient response.
- Laboratory Instruments:Precision analytical equipment retains demand for linear architectures where electromagnetic interference must approach zero.
- Therapeutic Devices:Infusion pumps, ventilators, and dialysis machines specify medically isolated supplies with redundant fault detection.
Diagnostic Imaging commands the largest revenue pool. Patient Monitoring exhibits the steepest expansion trajectory.
Technology:
Power conversion topologies trade efficiency, electromagnetic compatibility, and design flexibility against certification complexity.
- Switch Mode:High-frequency MOSFET and GaN-based designs achieve 85-94% efficiency in compact footprints. United States and German ambulatory device manufacturers are qualifying GaN topologies for portable ultrasound and infusion pump applications, consolidating mid-power tiers.
- Isolated Power Supplies:Transformer-coupled architectures with reinforced insulation provide patient safety barriers per IEC 60601-1. FDA 510(k) clearance pathways and EU MDR harmonization are filtering procurement toward pre-certified isolated designs, concentrating contract awards among compliant suppliers.
- Linear Power Supplies:Legacy transformer-rectifier designs with minimal switching noise retain niche demand.
- Modular Systems:Hot-swappable N+1 redundant configurations enable field-repairable infrastructure.
- Programmable Power Supplies:Software-configurable output parameters support multi-protocol diagnostic platforms.
Switch Mode dominates volume shipments. Isolated Power Supplies are capturing margin expansion from regulatory tightening.
End User:
Procurement authority and technical sophistication vary sharply across healthcare delivery settings, shaping supplier engagement models.
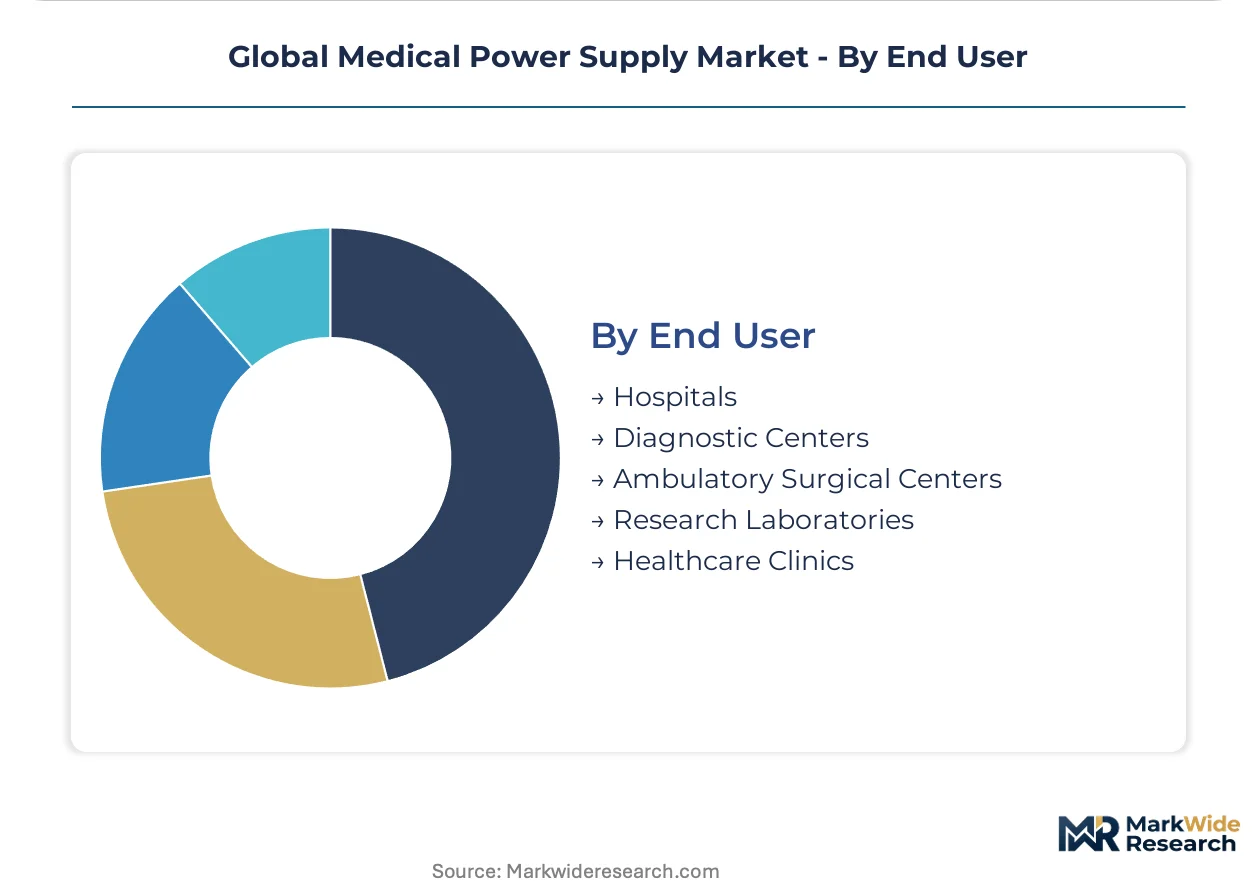
- Hospitals:Acute care facilities with centralized clinical engineering departments specify enterprise-grade power infrastructure with 10-15 year service life expectations. United States academic medical centers are unbundling after-sales contracts from hardware acquisition, negotiating separate multi-year maintenance agreements.
- Diagnostic Centers:Outpatient imaging chains prioritize throughput uptime and rapid service response over capital cost minimization.
- Ambulatory Surgical Centers:Cost-constrained settings with limited technical staff favor compact integrated power subsystems.
- Research Laboratories:University and pharmaceutical R&D facilities demand precision power with extensive documentation.
- Healthcare Clinics:Primary care settings accept basic AC-DC units without advanced monitoring capabilities.
Hospitals anchor premium-tier procurement. Ambulatory Surgical Centers are expanding device counts fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American medical device manufacturing, concentrating FDA-cleared power supply procurement for diagnostic imaging and patient monitoring systems.
United States
Academic medical centers in Boston and Houston are unbundling after-sales service contracts from hardware acquisition, negotiating separate multi-year maintenance agreements with third-party clinical engineering firms. FDA 510(k) clearance timelines compress development cycles for switch-mode designs. The Minneapolis-Saint Paul corridor hosts concentrated procurement from Medtronic and Boston Scientific suppliers.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia are multiplying device counts per bed, pulling compact isolated supplies into distributed care networks. EU Medical Device Regulation harmonization consolidates procurement toward pre-certified suppliers. The Munich-Regensburg medical technology cluster drives specification of IEC 60601-1 third edition compliant DC-DC converters for CT gantries.
Japan
University hospitals in Tokyo and Osaka are replacing aging Toshiba and Hitachi diagnostic imaging installations, sustaining premium-tier demand for multi-kilowatt programmable supplies. METI efficiency standards accelerate GaN-based switching adoption. The Nagoya medical device manufacturing belt concentrates sourcing for precision diagnostic expansion.
China
Domestic diagnostic equipment manufacturers in Shenzhen and Suzhou are qualifying locally produced isolated power supplies for CT and MRI systems. NMPA regulatory alignment with IEC standards tightens leakage current validation protocols. The Yangtze River Delta medical electronics corridor attracts magnetics manufacturing investment from Taiwanese suppliers.
Brazil
Diagnostic infrastructure expansion in São Paulo and Rio de Janeiro is opening procurement pathways for pre-certified suppliers. ANVISA regulatory alignment with IEC standards filters vendor participation toward compliant international manufacturers. The Campinas medical technology cluster drives demand for mid-power AC-DC units in outpatient imaging chains.
Global Medical Power Supply Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and thermal performance, with IEC 60601-1 third edition clearance separating contract awards. The vendor base concentrates among programmable platform specialists, captive magnetics manufacturers, and modular system integrators. Three archetypes dominate: diagnostic imaging OEM partners, distributed power architecture suppliers, and field-service-network operators. Competitive moves center on FDA 510(k) pre-certification investments and group purchasing organization partnership structures.
Within the programmable platform tier, XP Power and Delta Electronics exemplify divergent geographic positioning strategies. XP Power represents European-based high-reliability diagnostic imaging contract capture. Delta Electronics anchors Asia-Pacific manufacturing scale through captive magnetics production. TDK-Lambda occupies a position bridging modular medical-grade systems with reduced field failure rate positioning.
| Leading Market Players |
|---|
| Advanced Energy Industries Inc. |
| XP Power |
| Delta Electronics Inc. |
| TDK-Lambda Corporation |
| SL Power Electronics Corp |
| Spellman High Voltage Electronics Corporation |
| Astrodyne TDI |
| MEAN WELL Enterprises Co. Ltd. |
| COSEL Co. Ltd. |
| Others |
Supply & Pricing Matrix
Ferrite core and transformer winding costs flow from East Asian contract manufacturers through three distinct pricing tiers, with IEC 60601-1 third edition certification separating premium isolated designs from commodity AC-DC units procured by cost-sensitive clinics.
Pricing Analysis
Throughput-based pricing anchors diagnostic imaging contracts, where multi-kilowatt programmable supplies command premium positioning against per-unit transactional models dominating patient monitoring segments. Certification grade and after-sales service bundling drive price differentiation, with FDA 510(k) pre-cleared suppliers capturing margin expansion. Cost compression in the mid-power tier intensifies as GaN topologies consolidate adapter segments. Ambulatory surgical centers exhibit highest price sensitivity; Japanese university hospitals show lowest sensitivity due to uptime requirements.
Supply Chain Analysis
Dual-sourcing requirements from United States and German hospital procurement departments mandate qualified backup suppliers for magnetics components, mitigating single-source vulnerability. Ferrite cores, copper windings, and semiconductor substrates draw from China, Taiwan, and Japan. Tariff exposure on Chinese-sourced magnetics concentrates risk for isolated designs. Distribution runs through group purchasing organizations and specialized medical device distributors serving acute care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetics manufacturing capacity constraints prop pricing power for certified suppliers, with qualified winding capacity acting as the binding bottleneck across the forecast window.
For Market Incumbents: To counter GaN-based topology disruption from power semiconductor specialists, lock in multi-year magnetics supply agreements with Taiwanese and Japanese winding houses. Accelerate FDA 510(k) pre-certification investments to filter contract awards toward compliant incumbents. For New Entrants and Emerging Players: Capture white-space in Brazil's diagnostic infrastructure expansion by qualifying ANVISA-aligned designs before regulatory harmonization completes. Target ambulatory surgical centers in Germany with compact isolated supplies. Lead with direct hospital contracting models bypassing traditional distribution layers. For Investors and Strategic Acquirers: EU AI Act enforcement on software-integrated power management is the leading indicator that predictive maintenance capabilities will separate acquisition targets from stranded assets. Five-to-ten year viability favors programmable platform specialists with captive field service networks. Watch for notified body backlogs clearing as the signal for MDR-compliant supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Certification Investment | Compresses clearance timelines for switch-mode designs against IEC 60601-1 third edition leakage limits. |
| Captive Magnetics Manufacturing | Secures ferrite core and transformer winding capacity against East Asian lead-time volatility. |
| EU MDR Harmonization Alignment | Consolidates European procurement toward pre-certified suppliers filtering uncertified competitors. |
| Hospital GPO Partnership Structure | Bypasses distribution layers to capture margin in United States acute care segments. |
| Software-Integrated Power Management | Qualifies for preferential positioning under EU AI Act risk classification frameworks. |
Research Methodology
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads underwrites the qualitative findings. Primary interviews with clinical engineering directors and power supply design engineers combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital procurement contracts, and customs trade data. Bottom-up shipment analysis and top-down healthcare capital expenditure triangulation anchor volume estimates.
Comparable-period anchoring to historical diagnostic equipment replacement cycles and home healthcare expansion trajectories structures the projection horizon. Segmentation dimensions span product type, application, technology, and end-user procurement authority, with regional regulatory cluster effects modeled throughout the forecast period. CAGR derivation rests on equipment replacement velocity, ambulatory device proliferation, and certification barrier intensity. GaN adoption curves and MDR transition timelines feed industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA regulatory alignment pace and emerging economy standard harmonization. Deviation in magnetics manufacturing capacity expansion or IEC 60601-1 fourth edition drafting would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Medical Tubing Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Dial Thermometers Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Medical Linear Accelerators (MLA) Market