
 US ECG Equipment Market | 2026-2036
US ECG Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US ECG Equipment Market Insights
Aftermarket service revenue is narrowing as manufacturers bundle remote monitoring subscriptions with hardware sales. GE Healthcare leverages its installed base of hospital ECG systems to sustain recurring software revenue. Philips Healthcare anchors its position through integrated cardiology informatics platforms that span acute and ambulatory settings. iRhythm Technologies differentiates via proprietary wearable patch algorithms that occupy the long-term monitoring niche.
US ECG equipment comprises electrocardiograph machines that detect, amplify, and record electrical impulses generated by myocardial depolarization, typically sampling at 500 Hz with 12-lead configurations for diagnostic fidelity. The primary commercial purpose is non-invasive cardiac rhythm assessment to guide clinical intervention and triage. Holter monitors and portable ECG devices lead volume shipments as outpatient migration accelerates, while ECG management systems capture disproportionate margin pools through enterprise software licensing. Wireless ECG technology is displacing analog installations in hospital retrofit cycles, though digital ECG remains the revenue backbone due to replacement demand from aging installed bases.
FDA premarket notification requirements under 21 CFR 870.2340 govern diagnostic ECG device clearance, while HIPAA security rules constrain cloud-based ECG data transmission architectures. The Centers for Medicare & Medicaid Services determines reimbursement codes that directly shape provider procurement timing for capital equipment. Stakeholders must monitor FDA guidance on AI/ML-enabled ECG algorithms as predicate device pathways evolve for machine-learning-based diagnostic tools.
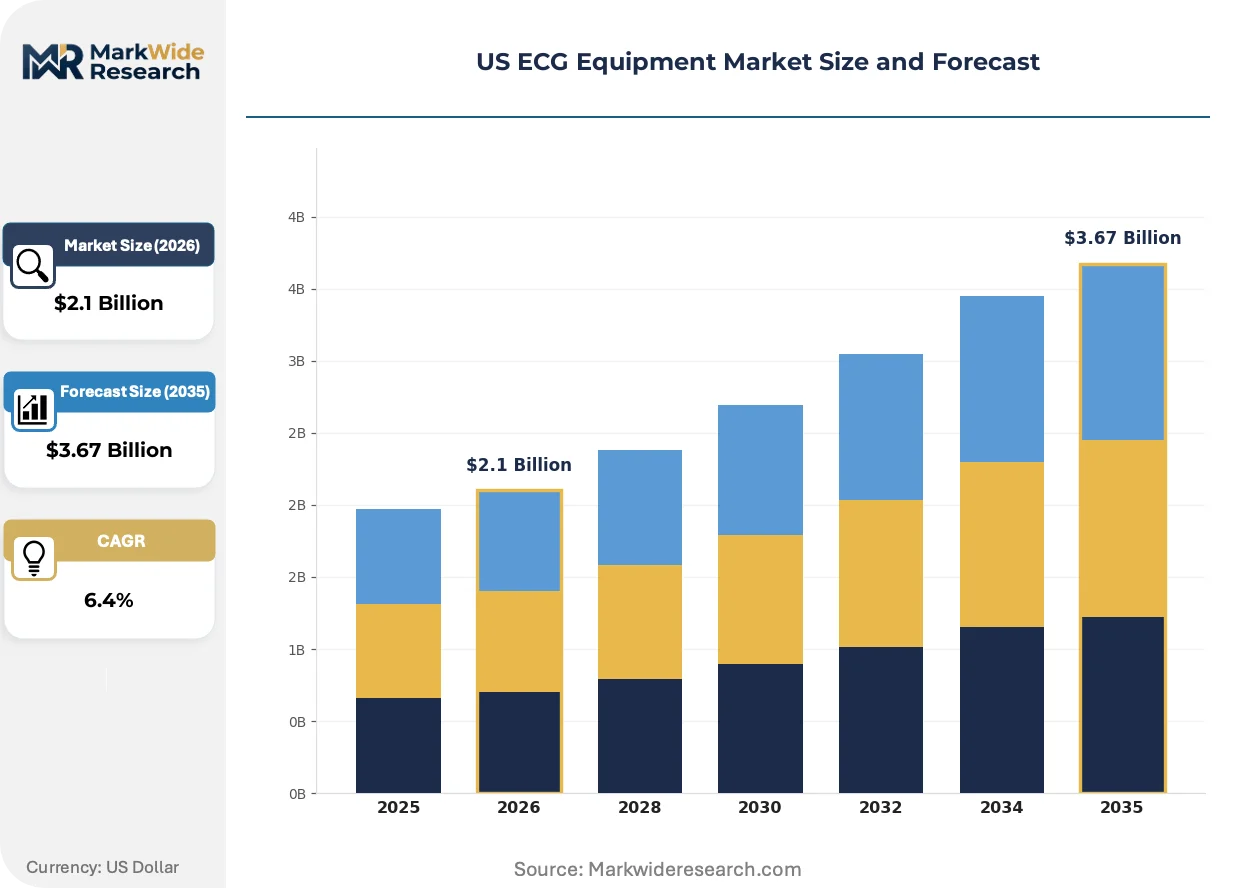
Market Dynamics
AI-enabled diagnostic algorithms are compressing FDA clearance timelines and forcing incumbent manufacturers to restructure R&D roadmaps around predicate device pathways rather than traditional 510(k) submissions.
Growth Catalysts
- CMS reimbursement alignment:Medicare coverage determinations for remote cardiac monitoring accelerate outpatient clinic procurement cycles for ambulatory ECG systems.
- Wireless telemetry integration:Bluetooth-enabled patch monitors eliminate lead-wire maintenance burdens and reduce nursing labor in telemetry wards.
- California-Texas-Florida corridor:Concentrated cardiology center density in these three states generates disproportionate hardware demand and service contract volume.
Market Restraints
- Semiconductor supply concentration:Analog front-end chips for high-fidelity ECG acquisition depend on Taiwan-based foundry capacity subject to geopolitical disruption.
- FDA AI/ML guidance uncertainty:Evolving predicate device requirements for machine-learning algorithms extend premarket notification review timelines unpredictably.
- Disposable electrode cost volatility:Silver-silver chloride electrode prices fluctuate with precious metals markets, squeezing consumable margins for Holter monitoring services.
Strategic Opportunities
- Rural health clinic penetration:Federally Qualified Health Centers in underserved states lack on-site cardiology diagnostics and present untapped hardware placement potential.
- Atrial fibrillation screening mandates:State-level requirements for post-stroke cardiac monitoring create reimbursement tailwinds for long-term patch-based systems.
- Cloud-native ECG platforms:Convergence of edge computing with HIPAA-compliant architectures enables real-time diagnostic streaming without on-premise server infrastructure.
Industry Challenges
- Clinical informatics integration:ECG management systems must interface with fragmented electronic health record architectures from Epic, Cerner, and Meditech, requiring costly custom HL7 mapping.
- Biomedical engineering talent scarcity:Hospitals face acute shortages of technicians trained to maintain legacy analog ECG systems while supporting wireless retrofit deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US ECG Equipment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Stress Test Systems, Resting ECG Machines, ECG Management Systems Technology: Wireless ECG, Digital ECG, Analog ECG, Portable ECG End User: Hospitals, Outpatient Clinics, Home Care, Cardiology Centers Application: Disease Diagnosis, Patient Monitoring, Clinical Research, Telemedicine |
| Companies Covered | GE Healthcare, Philips Healthcare, Nihon Kohden Corporation, Hill-Rom Holdings, Schiller AG, BioTelemetry, Mindray Medical, iRhythm Technologies, AliveCor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US ECG Equipment Market Trends and Innovations
Deep learning inference at the point of care is collapsing the latency between signal acquisition and diagnostic output, restructuring competitive advantage around algorithmic accuracy rather than hardware specifications alone.
12-lead ECG acquisition hardware with embedded GPU chipsets is digitizing diagnostic workflows by enabling real-time arrhythmia detection without cloud round-trips. Large health systems in the Northeast and Midwest are piloting these systems to reduce emergency department triage times. The shift is digitizing the traditional model of centralized cardiology over-read, compressing specialist labor requirements into automated preliminary interpretations.
FDA draft guidance on predetermined change control plans for AI/ML-enabled devices is reshaping how manufacturers structure software-as-medical-device submissions. The framework permits iterative algorithm updates without repeated 510(k) filings if validation protocols are pre-specified. Cardiology AI developers are restructuring quality management systems around this pathway to accelerate post-market improvement cycles.
Subscription-based remote monitoring is displacing capital purchase models for ambulatory ECG services, with health systems preferring per-patient-per-month fees that align costs with utilization. Independent diagnostic testing facilities are consolidating purchasing authority, reducing vendor count and demanding outcome guarantees on arrhythmia detection sensitivity. Texas and Florida outpatient networks are leading this contractual evolution, pressuring manufacturers to assume clinical performance risk.
US ECG Equipment Market Segmentation
ECG equipment segmentation reveals divergent margin structures across hardware, software, and service layers. Product type and technology dimensions command the highest strategic attention due to replacement cycles and AI integration timelines reshaping procurement patterns.
Product Type:
Mature diagnostic hardware segments face margin compression while software platforms capture expanding recurring revenue pools.
- Holter Monitors:Ambulatory patch-based systems sample cardiac electrical activity over 24-hour to 14-day wear periods. Outpatient clinics in Texas and Florida are standardizing on disposable patch formats to eliminate lead-wire maintenance labor and reduce nursing overhead.
- ECG Management Systems:Enterprise software platforms aggregate multi-site ECG data with HL7 interoperability for Epic and Cerner integration. Health systems in California prioritize cloud-native architectures that collapse on-premise server infrastructure while maintaining HIPAA-compliant data transmission protocols.
- Stress Test Systems:Treadmill-integrated ECG workstations with automated ST-segment analysis.
- Resting ECG Machines:12-lead acquisition devices for static diagnostic interpretation in acute settings.
ECG Management Systems handle the majority of throughput; Holter Monitors are expanding most quickly on share as ambulatory migration accelerates.
Technology:
Wireless and portable modalities are displacing legacy analog infrastructure in hospital retrofit cycles, though digital ECG remains the installed base backbone.
- Wireless ECG:Bluetooth-enabled patch monitors and telemetry systems eliminate lead-wire artifacts and enable real-time streaming to centralized monitoring stations. Northeast health systems pilot GPU-embedded acquisition hardware for point-of-care deep learning inference without cloud latency.
- Portable ECG:Handheld and smartphone-connected devices enable point-of-care screening in Federally Qualified Health Centers lacking on-site cardiology diagnostics. Rural clinic penetration in underserved states drives hardware placement potential outside traditional hospital procurement channels.
- Digital ECG:Conventional PC-based acquisition systems with software-defined signal processing.
- Analog ECG:Legacy thermal paper output devices subject to replacement demand from aging installed bases.
Digital ECG maintains the largest installed footprint; Wireless ECG is gaining share fastest through telemetry ward retrofits.
End User:
Procurement authority is fragmenting across integrated delivery networks, independent diagnostic testing facilities, and direct-to-consumer channels.
- Outpatient Clinics:Ambulatory surgery centers and cardiology group practices drive volume demand for compact Holter systems. Medicare reimbursement alignment for remote cardiac monitoring accelerates capital equipment procurement timing in this channel.
- Hospitals:Acute care facilities concentrate demand for 12-lead resting ECG machines and stress test systems with enterprise software integration requirements.
- Cardiology Centers:Specialty diagnostic facilities with concentrated procedure volume.
- Home Care:Direct-to-patient monitoring services with subscription-based revenue models.
Hospitals handle the majority of throughput; Outpatient Clinics are climbing the fastest as care migration continues.
Application:
Clinical utility is expanding beyond traditional diagnostic interpretation into screening mandates and decentralized research protocols.
- Disease Diagnosis:Arrhythmia detection and myocardial ischemia assessment through 12-lead acquisition and algorithmic interpretation. State-level post-stroke cardiac monitoring mandates in select jurisdictions create reimbursement tailwinds for long-term patch-based deployment.
- Telemedicine:Real-time ECG streaming to remote cardiologists for urgent over-read and triage decisions. Cloud-native platforms with edge computing architectures enable diagnostic streaming without on-premise infrastructure in rural health clinic deployments.
- Patient Monitoring:Continuous telemetry for inpatient surveillance and ambulatory post-discharge tracking.
- Clinical Research:Centralized ECG core lab services for pharmaceutical trial endpoints.
Disease Diagnosis handles the majority of throughput; Telemedicine is expanding most quickly on share as reimbursement codes mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECG equipment procurement concentrates in three state corridors where cardiology center density and Medicare reimbursement alignment create favorable demand conditions. California, Texas, and Florida collectively generate disproportionate hardware volume and service contract revenue. The analysis examines demand patterns across five sub-regional markets.
California
Health systems in the San Francisco Bay Area and Los Angeles Basin prioritize cloud-native ECG management architectures that eliminate on-premise server infrastructure. FDA 510(k) clearance pathways for AI-enabled diagnostic algorithms accelerate procurement cycles among integrated delivery networks. Stanford and Cedars-Sinai anchor enterprise software deployment for multi-site cardiology informatics.
Texas
Independent diagnostic testing facilities in the Dallas-Fort Worth and Houston metros consolidate purchasing authority and demand outcome guarantees on arrhythmia detection sensitivity. CMS reimbursement codes for remote cardiac monitoring drive capital equipment timing in outpatient networks. The Texas Medical Center complex sustains concentrated demand for 12-lead resting ECG machines.
Florida
Ambulatory surgery centers and cardiology group practices in the Miami and Tampa corridors standardize on disposable patch-based Holter systems to reduce nursing overhead. State-level post-stroke cardiac monitoring mandates create reimbursement tailwinds for long-term monitoring deployment. The Southeast Florida medical corridor leads volume shipments for portable ECG devices.
Northeast Corridor
Health systems in Massachusetts and New York pilot GPU-embedded acquisition hardware for point-of-care deep learning inference without cloud latency. HIPAA security rules constrain cloud-based data transmission architectures and shape vendor selection criteria. The Boston-Philadelphia corridor concentrates demand for wireless telemetry integration in academic medical centers.
Midwest
Federally Qualified Health Centers in Illinois, Ohio, and Michigan present untapped hardware placement potential for portable ECG screening devices. Rural clinic penetration lags national averages due to cardiology specialist scarcity. The Cleveland Clinic and Mayo Clinic anchor enterprise ECG management system deployments across multi-state networks.
US ECG Equipment Market Competitive Landscape
Diversified medical technology conglomerates and specialized cardiac monitoring firms split the market into distinct competitive tiers. Incumbent manufacturers leverage installed base relationships to sustain recurring software revenue streams against insurgent wearable patch specialists. Three archetypes dominate: integrated health technology platforms, dedicated cardiology informatics vendors, and disposable patch algorithm developers. Competitive dynamics center on predicate device pathway navigation for AI-enabled algorithms and subscription-based remote monitoring contract structures.
Within the diversified health technology tier, GE Healthcare and Philips Healthcare exemplify platform consolidation strategies that span acute and ambulatory settings. iRhythm Technologies occupies a distinct position among wearable patch specialists focused on long-term monitoring niches. These three companies anchor the competitive structure through divergent approaches to hardware-software integration and service model innovation.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Nihon Kohden Corporation |
| Hill-Rom Holdings |
| Schiller AG |
| BioTelemetry |
| Mindray Medical |
| iRhythm Technologies |
| AliveCor |
| Others |
Pricing and Supply Chain Analysis
Taiwan-based foundry capacity for analog front-end chips concentrates upstream margin capture among semiconductor suppliers, while downstream pricing power fragments across ECG hardware manufacturers competing for hospital procurement contracts. Silver-silver chloride electrode volatility feeds directly into consumable margin compression for Holter monitoring services, forcing service providers to absorb cost swings or renegotiate subscription terms.
Pricing Analysis
CMS reimbursement codes dictate the pricing tier structure for ambulatory ECG systems, with Medicare coverage determinations creating three-tier pricing stratification across premium AI-enabled platforms, standard digital ECG machines, and economy analog replacements. Price differentiation hinges on FDA clearance tier and after-sales service bundling, with 510(k) predicate device pathways commanding premiums over de novo submissions. Pricing pressure stems from independent diagnostic testing facilities consolidating purchasing authority and demanding outcome guarantees. Federally Qualified Health Centers exhibit highest price sensitivity, while integrated delivery networks in California prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries and supply-chain finance facilities anchored in Singapore sustain working capital for analog front-end chip procurement. Taiwan, South Korea, and Japan concentrate semiconductor manufacturing for high-fidelity ECG acquisition components. Raw material dependencies span silver-silver chloride for electrodes, copper for lead wires, and rare earth elements for GPU chipsets. Tariff exposure on Chinese-sourced printed circuit boards creates supply chain risk. Distribution runs through group purchasing organizations and direct hospital contracts, with regional service depots maintaining spare parts inventory for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumer-grade wearable ECG substitutes threaten to commoditize basic arrhythmia detection, forcing incumbent manufacturers to defend clinical-grade positioning through regulatory moats and hospital integration depth.
For Market Incumbents: Harden software lock-in through HL7 interoperability investments that increase switching costs for hospital ECG management systems. Deepen backward integration into AI algorithm development to capture recurring diagnostic revenue streams rather than ceding margin to third-party analytics vendors. Defend against patch-based monitoring entrants by embedding predictive algorithms directly into 12-lead acquisition hardware. For New Entrants and Emerging Players: Rural health clinics in Illinois, Ohio, and Michigan present underpenetrated white-space for portable ECG screening devices, with cardiology specialist scarcity creating demand for point-of-care diagnostics. Target Federally Qualified Health Centers with smartphone-connected hardware that bypasses capital-intensive enterprise sales cycles. Pursue state-level atrial fibrillation screening mandates as regulatory tailwinds for long-term monitoring deployment. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native ECG platform developers with HIPAA-compliant architectures and established Epic or Cerner integration pathways. Long-term viability hinges on software-as-medical-device revenue models that decouple growth from hardware replacement cycles. Monitor FDA draft guidance finalization on predetermined change control plans as the signal for algorithm update velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) clearance for AI-enabled algorithms accelerates hospital procurement cycles and predicates software revenue streams. |
| Hospital System Partnership | Enterprise ECG management deployments with Stanford or Cedars-Sinai anchor multi-site informatics standardization. |
| Software Companion Development | Cloud-native platforms with edge computing architectures eliminate on-premise infrastructure for rural clinic penetration. |
| Reimbursement Strategy | CMS remote cardiac monitoring codes determine capital equipment timing for Texas and Florida outpatient networks. |
| Acquisition of Specialist Firm | Wearable patch algorithm developers with proprietary arrhythmia detection IP command premium valuations from platform consolidators. |
Research Methodology
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and cardiology informatics directors anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and medical device trade association reports. Bottom-up triangulation of unit shipment estimates with top-down revenue aggregation ensures consistency across the analysis window.
Calibration against historical replacement cycles for analog ECG installed bases and wireless telemetry adoption curves shapes the analytical framework. Segmentation dimensions span product type, technology modality, end-user channel, and application across the projection horizon. CAGRs derive from weighted average of equipment replacement demand, ambulatory migration velocity, and AI algorithm penetration assumptions. Forecast inputs incorporate semiconductor supply constraints and evolving FDA AI/ML guidance timelines.
Practitioners should monitor reimbursement code revisions, foundry capacity announcements, and predicate device pathway clarifications for early signals of forecast deviation. The analysis reflects assumptions regarding outpatient clinic migration velocity and Medicare coverage stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Water Bath Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Autopsy Equipment Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Healthcare Simulators Market