
 Europe Medical Carts Market | 2026-2036
Europe Medical Carts Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Carts Market Analytics
Ambulatory surgery centers is broadening the end-use base for medical carts across Europe, pulling manufacturers beyond traditional hospital contracting. Ergotron, Inc. leverages its long-standing presence in ergonomic mounting systems to dominate premium adjustable cart segments. GCX Corporation anchors its position through specialized mounting solutions for diagnostic and monitoring equipment in catheterization labs.
Europe medical carts are wheeled or fixed infrastructure platforms designed to transport medications, emergency supplies, diagnostic devices, and computing equipment within clinical environments, typically constructed from antimicrobial-coated metals or polymer composites with integrated cable management and power distribution systems. Their primary purpose is to enable safe, efficient point-of-care delivery while supporting infection control protocols and clinician ergonomics. Medication carts command stable replacement demand from hospital pharmacies seeking barcode verification integration, while emergency carts carry premium pricing due to crash-cart standardization requirements and rapid-access drawer configurations. Mobile carts lead volume shipments as facilities prioritize flexibility in room utilization, though wall-mounted units gain traction in space-constrained Nordic clinics.
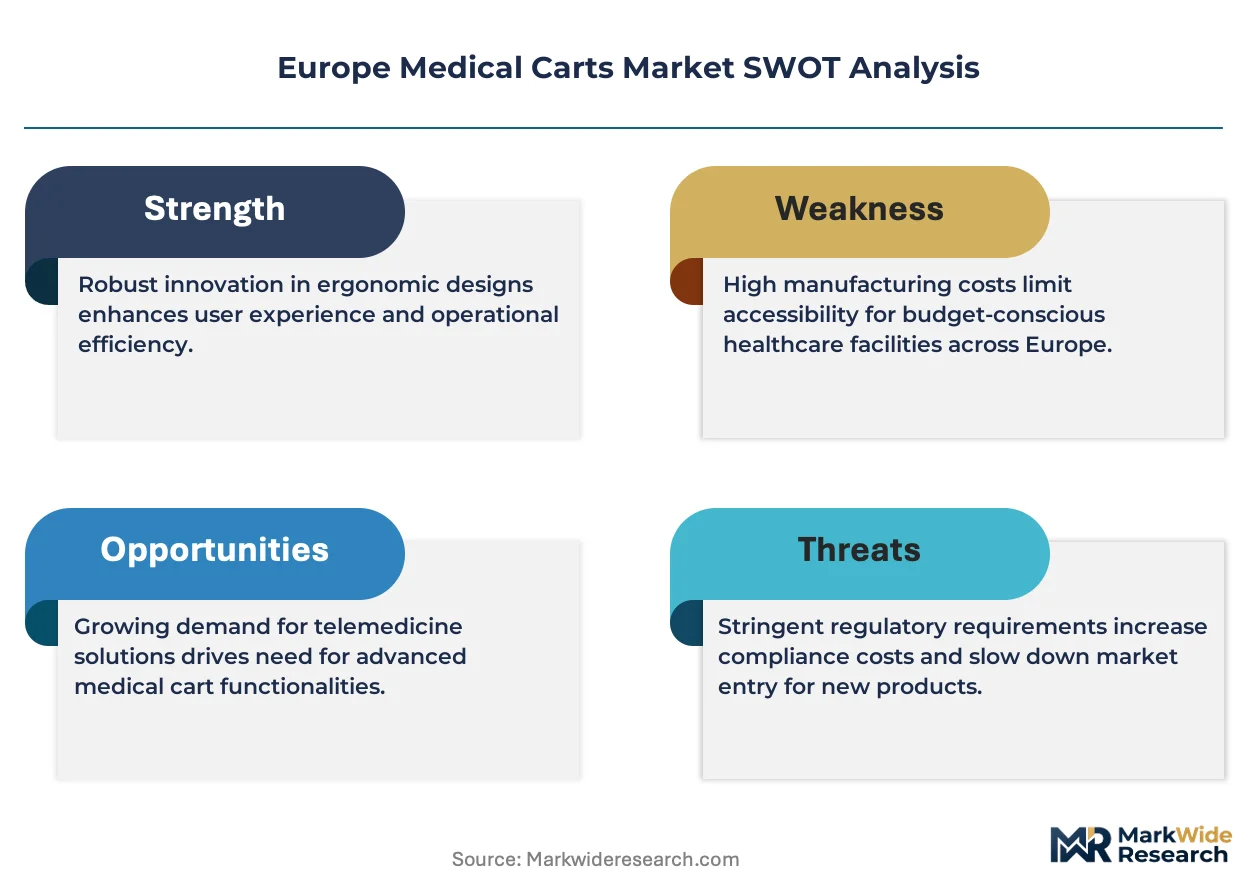
The EU Medical Device Regulation and CE marking framework govern electrical safety, electromagnetic compatibility, and material biocompatibility for cart-integrated systems, compelling manufacturers to maintain updated technical documentation and notified body certifications. ECHA REACH restrictions on certain plastics and surface coatings shape material selection, particularly for components in prolonged patient contact. Germany's KBA-equivalent medical device oversight and France's ANSM registration requirements add national-layer compliance complexity. Stakeholders must track evolving MDR implementation timelines and assess whether backward integration into aluminum or stainless steel fabrication offers insulation from supply chain certification bottlenecks.
Market Dynamics
Hospital digitization mandates across Germany, France, and the Netherlands are compressing replacement cycles for clinical infrastructure, forcing procurement departments to evaluate carts as integrated computing platforms rather than passive transport equipment. This shift elevates electrical safety certification and software interoperability to primary selection criteria.
Growth Catalysts
- EU Medical Device Regulation (MDR):The tightened electrical safety and biocompatibility requirements for cart-mounted equipment are compelling hospitals to replace legacy fleets, generating sustained replacement demand through 2035.
- Ambulatory surgery centers:These facilities are broadening the end-use base beyond traditional hospital contracting, pulling manufacturers into specialized outpatient procurement channels.
- Antimicrobial-coated aluminum:Material substitution toward infection-resistant metals is opening premium positioning for fabricators with in-house surface treatment capabilities.
Market Restraints
- ECHA REACH restrictions:Limits on certain plastics and surface coatings are constraining material selection for components in prolonged patient contact, forcing reformulation of polymer composites.
- Aluminum supply concentration:European smelter capacity constraints and energy cost volatility are creating input price instability for cart frame fabrication.
- CE marking timeline compression:Extended notified body backlogs under MDR implementation are stretching certification lead times to 12-18 months for new cart-integrated systems.
Strategic Opportunities
- Nordic space-constrained clinics:Wall-mounted cart configurations are gaining traction in Denmark, Sweden, and Finland where room utilization flexibility commands premium pricing.
- Barcode verification integration:Medication carts with embedded scanning infrastructure represent an underpenetrated upgrade pathway for hospital pharmacies seeking closed-loop medication management.
- EU Green Deal procurement incentives:Public hospital tenders with embedded sustainability scoring are favoring manufacturers with verified recycled aluminum content and circular take-back programs.
Industry Challenges
- Electromagnetic compatibility engineering:Integrating wireless telemetry, RFID, and computing equipment without interference requires scarce RF engineering talent, particularly for catheterization lab configurations.
- Legacy fleet interoperability:Hospitals with mixed-vendor cart populations face integration complexity when upgrading to MDR-compliant power distribution and cable management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Carts Market |
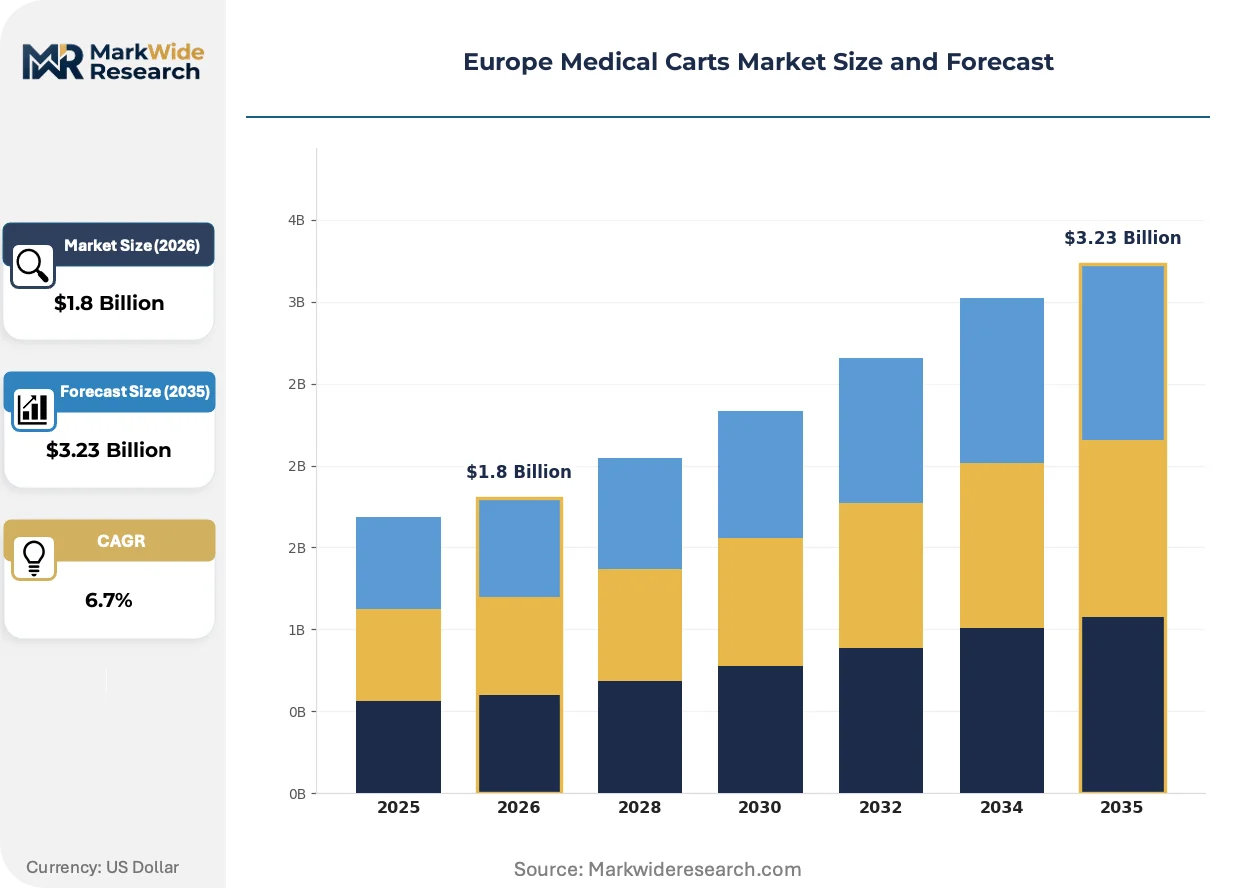
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Carts, Medication Carts, Transport Carts, Procedure Carts End User: Hospitals, Clinics, Nursing Homes, Ambulatory Surgery Centers Material: Stainless Steel, Aluminum, Plastic, Wood Design Type: Mobile Carts, Wall-Mounted Units, Integrated Solutions, Customized Designs |
| Companies Covered | Ergotron, Inc., GCX Corporation, Advantech Co., Ltd, Enovate Medical, JACO, Inc., Capsa Healthcare, Medline Industries Inc., Harloff Company, ITD GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Carts Market Evolving Landscape
Three distinct vectors are reshaping cart design priorities: embedded computing density, material compliance depth, and procurement flexibility. Each trend reflects the sector's evolution from mechanical transport toward integrated clinical workstations.
Modular power distribution systems with hot-swappable battery architectures are absorbing the computational load of point-of-care diagnostics, ultrasound, and telemedicine endpoints. German acute care hospitals are deploying these configurations at scale to eliminate wall-tethered workflows. The technology is absorbing margin pressure from commodity cart frames by shifting value capture toward electrical infrastructure and software integration layers.
France's ANSM registration requirements are layering national compliance complexity atop the EU MDR framework, creating dual-track certification obligations for cart-integrated diagnostic equipment. Manufacturers must maintain parallel technical documentation streams, elevating regulatory affairs headcount as a fixed cost center. Catheterization lab configurations face the steepest compliance burden due to combined electrical safety and patient contact material rules.
Hospital procurement departments are unbundling after-sales service contracts from hardware acquisition, treating preventive maintenance and firmware updates as separately negotiated spend categories. This behavioral shift is compressing vendor margins on initial equipment sales while elevating the strategic importance of remote diagnostics and predictive maintenance platforms. The Netherlands and Belgium are leading this unbundling pattern through centralized hospital group purchasing organizations.
Europe Medical Carts Market Segmentation
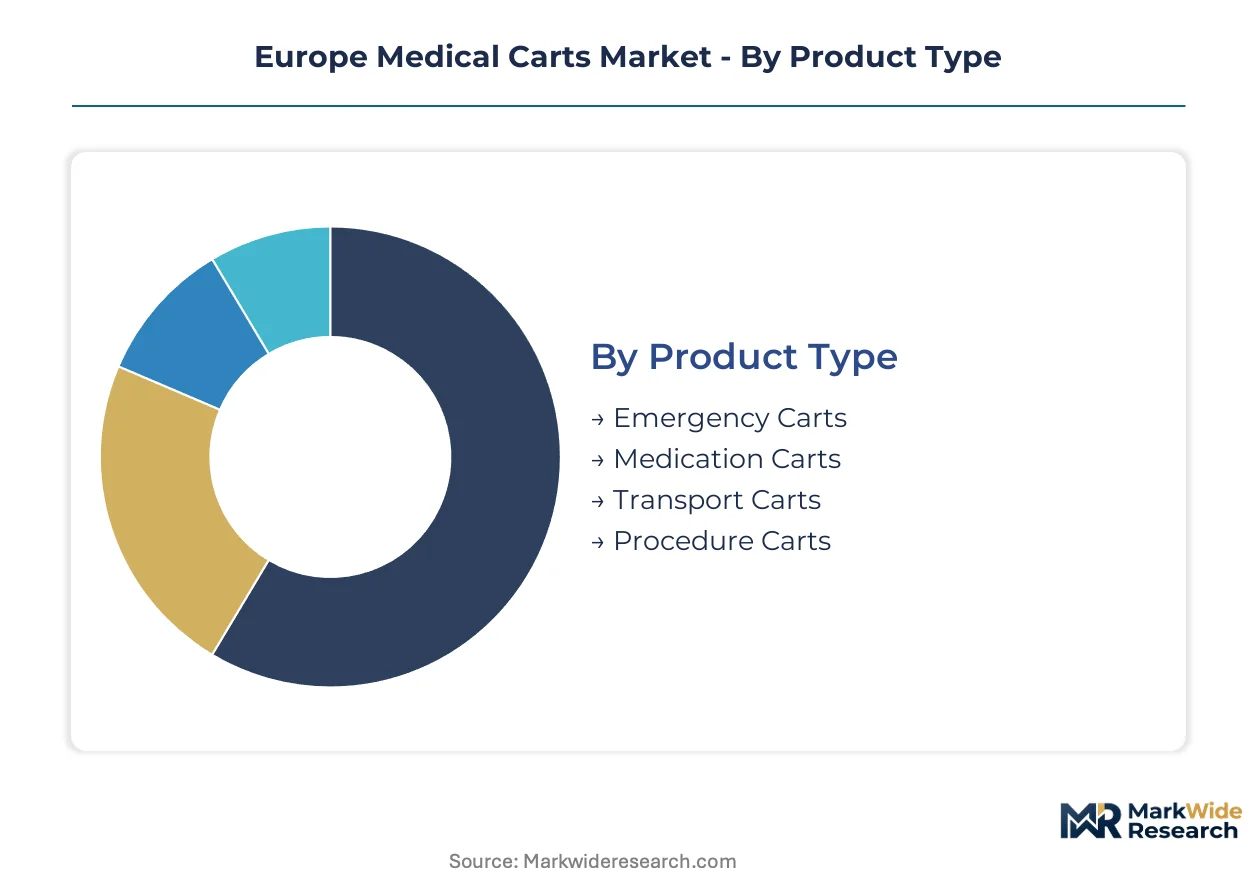
Medical cart procurement in Europe diverges sharply between high-acuity settings demanding crash-ready configurations and long-term care facilities prioritizing cost containment. Segmentation reveals how MDR compliance costs and digitization mandates are reshaping manufacturer priorities across product tiers.
Product Type:
Emergency carts command premium pricing while medication carts drive replacement volume through pharmacy automation mandates.
- Emergency Carts:These units feature rapid-access drawer configurations, defibrillator mounting brackets, and standardized crash-cart layouts compliant with resuscitation protocols. German acute care hospitals and French trauma centers are deepening investment following MDR electrical safety deadlines for life-support equipment integration.
- Medication Carts:Barcode verification infrastructure and controlled-substance locking mechanisms define current specifications. Hospital pharmacies across the Netherlands and Belgium are replacing legacy fleets to enable closed-loop medication management systems.
- Transport Carts:Basic mobility platforms for linen, supplies, and equipment relocation with minimal electrical integration.
- Procedure Carts:Specialized configurations for catheterization labs and interventional suites requiring integrated power and cable management.
Mature deployment sits with medication carts in established hospital networks. Newer deployment is concentrated in emergency carts as facilities accelerate MDR-driven fleet replacement.
End User:
Hospital procurement dominates absolute spend while ambulatory surgery centers are expanding the addressable market beyond traditional contracting channels.
- Hospitals:Acute care facilities in Germany, France, and the Netherlands are compressing replacement cycles for clinical infrastructure under digitization mandates. These buyers evaluate carts as integrated computing platforms rather than passive transport equipment.
- Ambulatory Surgery Centers:Outpatient facilities across Denmark and Sweden are pulling manufacturers into specialized procurement channels with distinct space constraints and procedure-specific requirements.
- Clinics:Primary care and diagnostic centers with moderate equipment density and intermittent cart utilization patterns.
- Nursing Homes:Long-term care facilities prioritizing durable, low-maintenance configurations with minimal electrical complexity.
Volume leadership remains with hospital systems. Steepest expansion trajectory is occurring in ambulatory surgery centers as outpatient procedural volume migrates from inpatient settings.
Material:
Aluminum and stainless steel are displacing legacy polymers as REACH restrictions and infection control protocols tighten material specifications.
- Aluminum:Antimicrobial-coated aluminum frames with in-house surface treatment capabilities are commanding premium positioning. Fabricators with captive anodizing operations are insulating procurement departments from ECHA REACH compliance bottlenecks affecting polymer composites.
- Stainless Steel:304 and 316-grade constructions dominate catheterization lab and surgical suite applications where sterilization compatibility and structural durability outweigh weight considerations.
- Plastic:Polymer composites facing reformulation pressure under ECHA REACH restrictions on certain plastics and surface coatings for components in prolonged patient contact.
- Wood:Limited to aesthetic-focused administrative and reception applications with minimal clinical functionality.
Established procurement favors stainless steel in high-acuity settings. Material substitution is accelerating fastest in aluminum as infection-resistant metals gain preference across German and Nordic facilities.
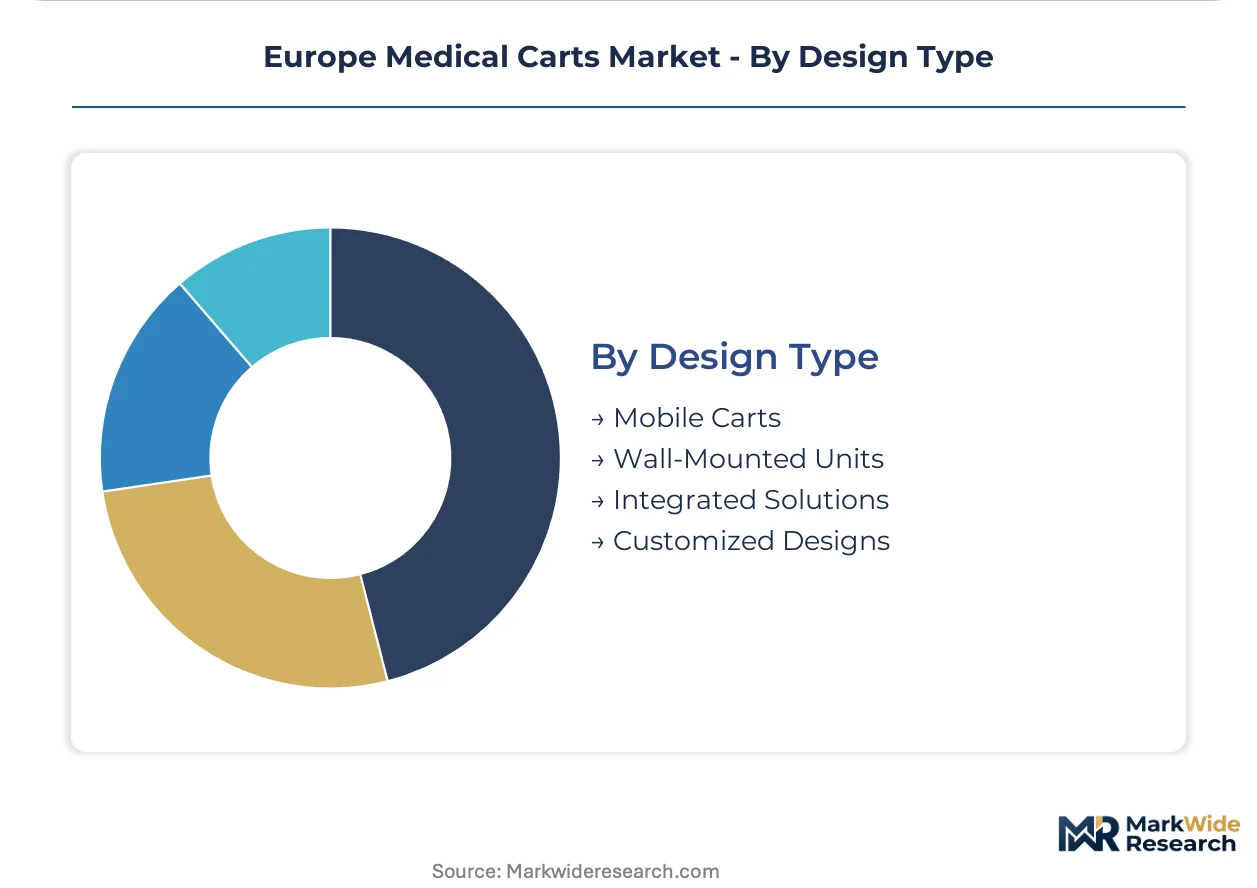
Design Type:
Mobile configurations lead shipment volume while wall-mounted units capture premium pricing in space-constrained Nordic markets.
- Mobile Carts:Wheeled platforms with hot-swappable battery architectures are absorbing computational loads from point-of-care diagnostics and telemedicine endpoints. German hospitals are deploying these at scale to eliminate wall-tethered workflows.
- Wall-Mounted Units:Fixed installations gaining traction in Denmark, Sweden, and Finland where room utilization flexibility commands premium pricing and floor space is severely constrained.
- Integrated Solutions:Custom-engineered configurations combining storage, computing, and diagnostic mounting for specific departmental requirements.
- Customized Designs:Bespoke fabrications for specialized procedural environments with non-standard equipment footprints.
Volume concentration sits with mobile carts across continental Europe. Premium expansion is concentrated in wall-mounted units as Nordic clinic construction prioritizes space efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital digitization programs and French trauma center investments are concentrating procurement in Western European industrial corridors. Benelux purchasing organizations and Nordic outpatient construction are expanding the addressable market beyond traditional acute care contracting.
Germany
Hospital digitization mandates and aging clinical infrastructure replacement cycles are accelerating procurement across Bavaria and North Rhine-Westphalia. The KBA-equivalent medical device oversight enforces strict electrical safety certification timelines for cart-integrated systems. Berlin-Brandenburg medical technology clusters host fabricators specializing in antimicrobial-coated aluminum frames with captive anodizing operations.
France
Trauma centers in Île-de-France and Auvergne-Rhône-Alpes are deepening investment in crash-cart configurations following MDR electrical safety deadlines. ANSM registration requirements layer national compliance complexity atop EU MDR framework for catheterization lab equipment. Lyon-based manufacturers maintain parallel technical documentation streams to satisfy dual-track certification obligations.
Netherlands
Centralized hospital group purchasing organizations in the Randstad region are unbundling after-sales service contracts from hardware acquisition. CE marking timeline compression under MDR implementation stretches certification lead times to 12-18 months. Eindhoven-area fabricators supply wall-mounted configurations to space-constrained clinics across Benelux markets.
Sweden
Outpatient procedural volume migration from inpatient settings is expanding ambulatory surgery center demand in Stockholm and Gothenburg corridors. ECHA REACH restrictions on polymer composites favor material substitution toward infection-resistant metals. Malmö-based specialists configure mobile platforms with hot-swappable battery architectures for telemedicine endpoints.
Denmark
Nordic clinic construction prioritizes space efficiency, driving premium pricing for wall-mounted units in Copenhagen and Aarhus medical districts. EU Green Deal procurement incentives with embedded sustainability scoring favor verified recycled aluminum content. Odense-area fabricators operate circular take-back programs qualifying for public hospital tender preferences.
Europe Medical Carts Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium adjustable cart configurations commanding distinct procurement channels from commodity transport platforms. Market structure tilts toward consolidation in MDR-compliant electrical infrastructure tiers while remaining fragmented in basic mobility segments. Three archetypes dominate: ergonomic mounting specialists with long-standing hospital relationships, diagnostic equipment integrators serving catheterization labs, and diversified healthcare fabricators leveraging scale across multiple clinical infrastructure categories. Competitive moves concentrate on backward integration into aluminum fabrication and predictive maintenance platform development.
Among US-based ergonomic specialists, Ergotron, Inc. and GCX Corporation exemplify divergent positioning strategies within the premium tier. Ergotron anchors the adjustable mounting segment through decades of clinician workflow optimization, while GCX occupies a specialized position in diagnostic equipment integration for interventional suites. California-based Enovate Medical and Illinois-rooted Capsa Healthcare represent the diversified healthcare fabricator archetype, leveraging cross-product scale to absorb regulatory compliance costs. These three entities collectively illustrate how geographic origin and naming conventions signal strategic focus areas without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Ergotron, Inc. |
| GCX Corporation |
| Advantech Co., Ltd |
| Enovate Medical |
| JACO, Inc. |
| Capsa Healthcare |
| Medline Industries Inc. |
| Harloff Company |
| ITD GmbH |
| Others |
Value Network & Pricing Analysis
Centralized hospital group purchasing organizations in the Netherlands and Belgium concentrate procurement volume, forcing manufacturers toward contract-based long-term offtake structures with embedded service unbundling. This buyer concentration elevates price transparency while compressing margins on initial hardware sales across German and French acute care networks.
Pricing Analysis
Short lead-time configurations command substantial premiums as CE marking timeline compression under MDR implementation stretches certification lead times to 12-18 months for new cart-integrated systems. Pricing stratifies across MDR-premium, transitional-standard, and legacy-economy tiers based on certification status and electrical safety integration depth. Cost compression in the economy tier intensifies because aluminum supply concentration and energy cost volatility create input price instability for basic frame fabrication. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while German trauma centers demonstrate lowest sensitivity given digitization mandate deadlines and crash-cart standardization requirements.
Supply Chain Analysis
Freight cost volatility from Asian component sourcing is reshaping European fabricator location decisions, with Berlin-Brandenburg and Lyon medical technology clusters absorbing expanded production roles. Aluminum smelting capacity in Germany, France, and Norway anchors frame fabrication, while battery cell production draws from South Korean and Japanese suppliers for hot-swappable power architectures. Single-source vulnerability sits with specialized RF engineering talent for electromagnetic compatibility integration in catheterization lab configurations. Distribution runs through hospital group purchasing organizations in Benelux and direct contracting with German KBA-equivalent certified fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around MDR-compliant electrical infrastructure capabilities, with extended notified body backlogs and certification complexity forcing sub-scale polymer composite fabricators toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into captive anodizing operations for antimicrobial-coated aluminum, insulating procurement departments from ECHA REACH compliance bottlenecks. Deepen predictive maintenance platform development to capture unbundled after-sales service contracts that Dutch and Belgian hospital group purchasing organizations now negotiate separately. Threat substitution from diagnostic equipment integrators with embedded cart solutions demands defensive software interoperability investment.
For New Entrants and Emerging Players: Embedded barcode verification infrastructure for medication carts offers a technology-first wedge into closed-loop medication management upgrades across Netherlands and Belgium hospital pharmacies. Target Nordic wall-mounted configurations in Denmark and Sweden where space-constrained clinic construction commands premium pricing and established players lack specialized regional presence. Go-to-market angle should leverage EU Green Deal procurement incentives with verified recycled aluminum content and circular take-back programs.
For Investors and Strategic Acquirers: The window for entry favors mid-cap fabricators with captive surface treatment capabilities and existing notified body relationships. Long-term viability hinges on MDR certification asset durability as regulatory complexity compounds. Acquisition target archetype: German or French specialists with parallel ANSM and CE marking technical documentation streams. Signal to watch: hospital procurement department unbundling penetration rates in Netherlands and Belgium as leading indicator of service revenue capture potential.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Notified body backlog navigation compresses 12-18 month timelines for cart-integrated systems. |
| Backward Integration into Aluminum Fabrication | Captive anodizing operations insulate against ECHA REACH polymer composite restrictions. |
| Hospital System Partnership | Direct contracting with German digitization programs secures replacement cycle volume. |
| Software Companion Development | Predictive maintenance platforms capture unbundled after-sales service spend in Benelux. |
| EU Green Deal Certification Program | Verified recycled aluminum content qualifies for public hospital tender sustainability scoring. |
Research Methodology
EU MDR implementation guidance documents, ECHA REACH restriction updates, and hospital procurement database records formed the secondary backbone for market sizing and regulatory timeline validation. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and cart fabricator regulatory affairs leads combined with secondary validation through bottom-up shipment analysis and top-down healthcare infrastructure spend reconciliation. Cross-referencing German KBA-equivalent certification timelines with French ANSM registration requirements enabled dual-track compliance cost modeling.
Historical trendline analysis of replacement cycle compression across German, French, and Dutch acute care facilities informed demand trajectory assumptions over the projection horizon. The analytical framework modeled segmentation across product type, end user, material substitution patterns, and design configuration, with CAGRs derived from infrastructure investment correlation with digitization mandate implementation schedules. Aluminum price volatility coefficients and notified body capacity constraints served as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including potential MDR implementation timeline extensions, abrupt aluminum smelter capacity closures from energy price spikes, and unforeseen ECHA restriction expansions to additional polymer categories. Forecasts reflect assumptions about sustained hospital digitization program funding and stable EU Green Deal procurement incentive structures. Stakeholders should weight assumptions against their own operating context and regulatory compliance cost absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Medical Automation Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Global Blood Purification Equipment Market