
 PCR Plate Sealer Market | 2026-2036
PCR Plate Sealer Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Plate Sealer Market Analytics
Direct distribution to large pharmaceutical accounts is reshaping how PCR plate sealer vendors allocate field service and technical support resources. Thermo Fisher Scientific leverages its installed base of thermal cyclers to bundle sealing equipment with consumables contracts. Eppendorf anchors its position in European research markets through precision engineering and localized application support. QIAGEN differentiates by integrating plate sealers into automated nucleic acid extraction workflows, reducing customer integration burden.
A PCR plate sealer applies uniform pressure and thermal energy to bond adhesive or heat-activated films across multi-well microplates, typically achieving seal integrity against evaporation rates below 0.5% per hour at 90 degrees Celsius. The device serves primarily to prevent cross-contamination and sample loss during thermal cycling, storage, and transport in quantitative PCR and sequencing workflows. Automated sealers command the strongest margin pools as pharmaceutical companies prioritize walk-away automation in high-throughput screening facilities. Manual sealers retain substantial volume in academic institutions where capital constraints favor lower-cost entry points. Heat sealing technology leads in molecular biology applications due to its compatibility with polypropylene plates across temperature extremes from minus 80 to 110 degrees Celsius.
FDA 21 CFR Part 11 compliance requirements shape electronic records and signature capabilities in systems sold to United States pharmaceutical end users, while the EU In Vitro Diagnostic Regulation imposes stricter performance documentation on diagnostic applications in European markets. ISO 13485 quality management certification increasingly functions as a market access threshold for vendors supplying clinical laboratories rather than research-only facilities. Stakeholders must monitor how evolving harmonization between FDA and EMA quality system expectations affects validation documentation burdens and time-to-market for new automated sealing platforms.
Market Dynamics
Automated sample preparation workflows in clinical diagnostics laboratories are compressing equipment replacement cycles and forcing vendors to bundle validation documentation with hardware sales.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in United States pharmaceutical facilities drive replacement of legacy manual sealers with compliant automated platforms.
- Heat sealing technology:Polypropylene plate compatibility from minus 80 to 110 degrees Celsius expands addressable applications in biobanking and cold-chain logistics.
- Centralized reference laboratories:Germany's diagnostic consolidation creates standardized procurement specifications that favor validated automated systems.
Market Restraints
- Capital intensity:Automated sealing platforms require substantial upfront investment that constrains adoption in academic institutions with fixed equipment budgets.
- Adhesive film supply concentration:Specialized sealing films depend on petrochemical feedstock pricing and limited qualified film converters.
- EU In Vitro Diagnostic Regulation:Stricter performance documentation requirements extend time-to-market for diagnostic-targeted equipment in European markets.
Strategic Opportunities
- Point-of-care expansion:Miniaturized sealing formats for decentralized diagnostic testing in India and Southeast Asia remain underpenetrated.
- ISO 13485 certification:Quality management certification functions as a market access threshold for clinical laboratory suppliers, creating differentiation value.
- Cloud-connected validation:Integration of remote monitoring and predictive maintenance with automated sealers opens recurring revenue streams.
Industry Challenges
- Application engineering talent:Shortage of specialists who bridge molecular biology protocols with automation engineering slows customer onboarding.
- Legacy system integration:Automated sealers must interface with diverse thermal cycler and liquid handler brands without custom programming.
- Validation timeline compression:Pharmaceutical customers demand compressed installation qualification and operational qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Plate Sealer Market |
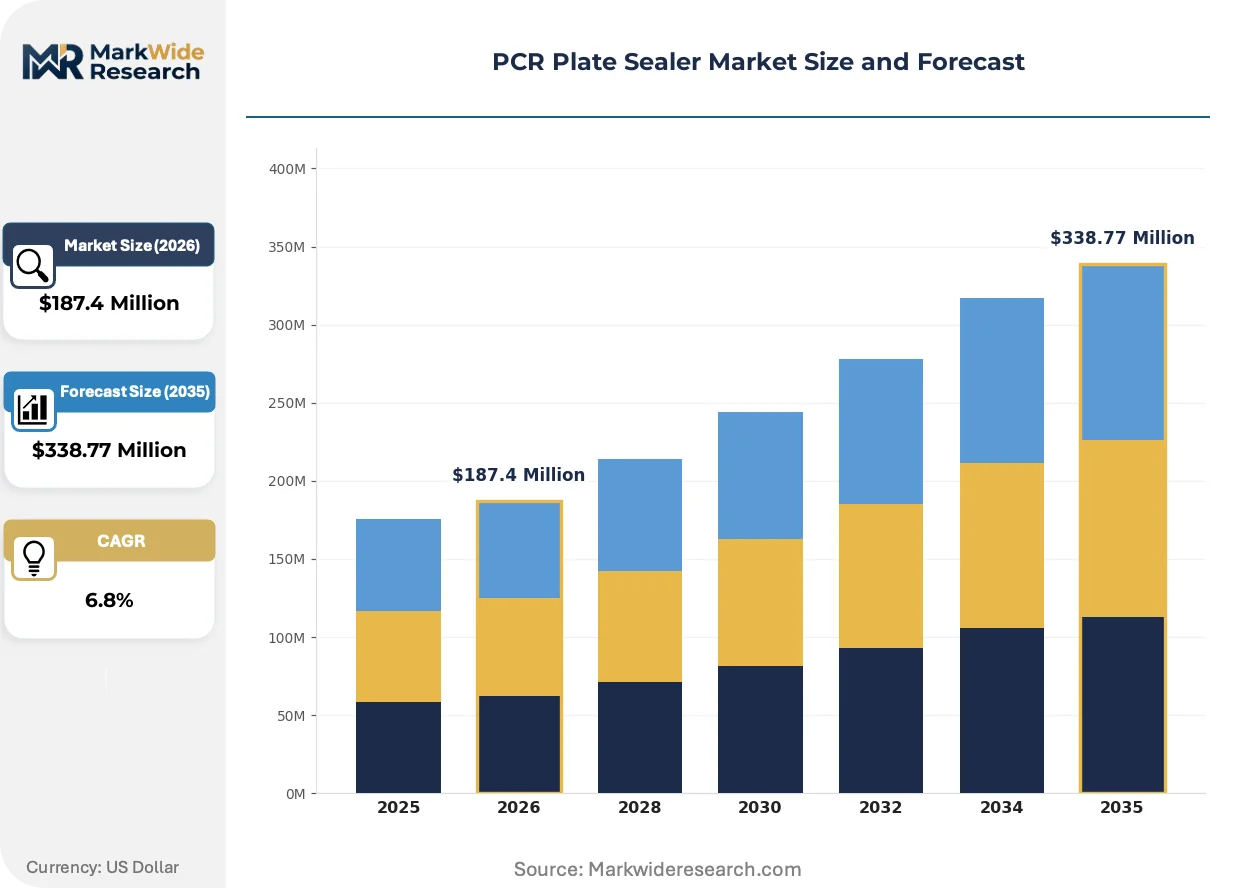
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Sealers, Automated Sealers, Thermal Sealers, UV Sealers End User: Research Laboratories, Pharmaceutical Companies, Academic Institutions, Clinical Research Organizations Technology: Heat Sealing, Adhesive Sealing, Vacuum Sealing, Robotic Sealing Application: Molecular Biology, Genetic Testing, Diagnostics, Drug Development |
| Companies Covered | Eppendorf, QIAGEN, Thermo Fisher Scientific, Danaher Corporation, F. Hoffmann-La Roche, Agilent Technologies, Corning, Azenta Life Sciences, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Plate Sealer Market Evolving Landscape
Digital validation architectures and remote service models are displacing on-site technical support as the primary vendor-customer interface in automated sealing equipment.
Cloud-based equipment monitoring software is virtualizing the traditional field service relationship between PCR plate sealer vendors and pharmaceutical quality assurance departments. Large contract research organizations in the United States now expect predictive maintenance alerts and remote diagnostic access as standard features. This virtualization compresses response times from days to hours while reducing vendor travel costs.
The EU In Vitro Diagnostic Regulation's performance documentation requirements are forcing equipment manufacturers to redesign quality management systems for traceability. Diagnostic application sales now require extensive clinical evidence packages that extend product development timelines. German and French reference laboratories are prioritizing suppliers with pre-validated regulatory dossiers.
Consolidated procurement through group purchasing organizations is displacing direct laboratory purchasing authority in North American hospital systems. Integrated delivery networks now negotiate enterprise contracts covering multiple diagnostic equipment categories. This concentration is most visible in United States metropolitan markets where health system mergers have reduced independent laboratory counts.
PCR Plate Sealer Market Segmentation
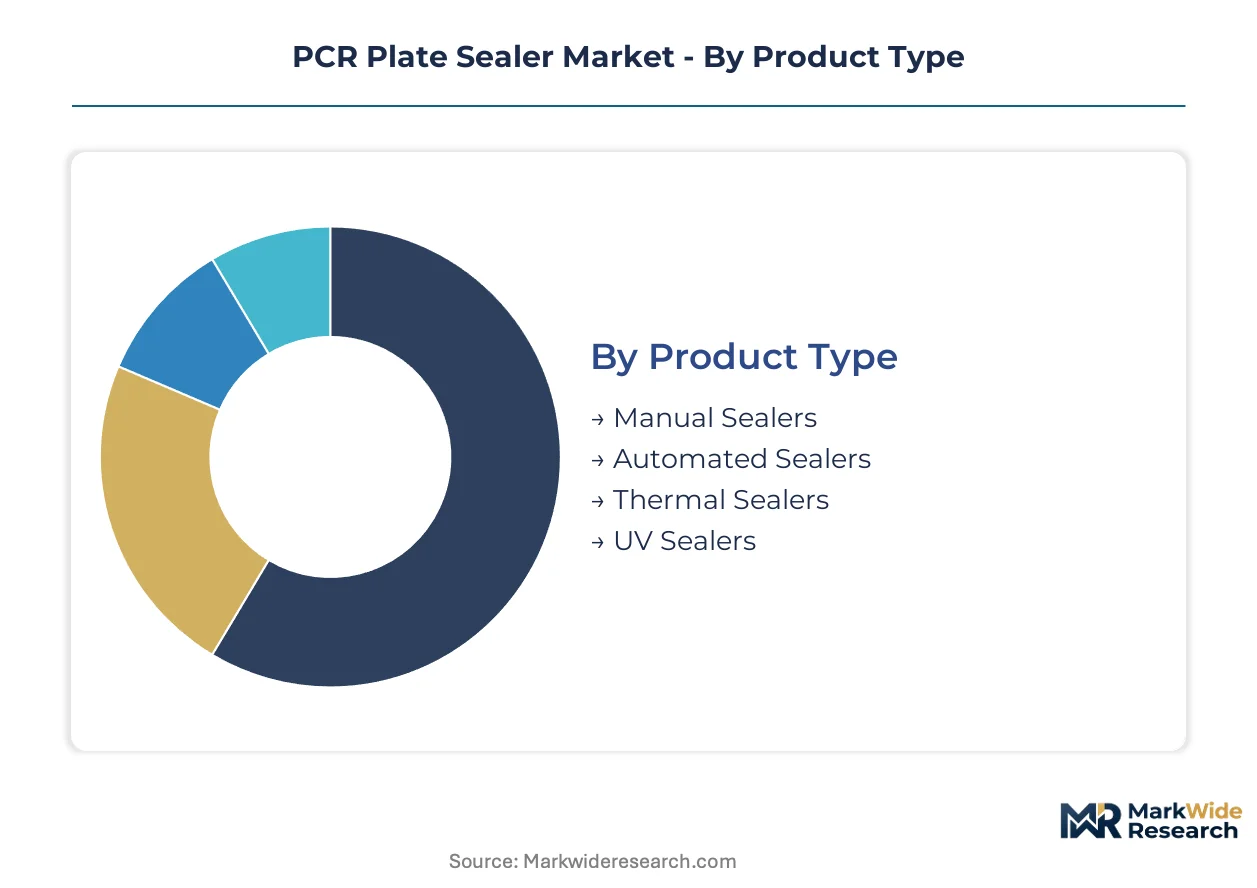
PCR plate sealer segmentation reveals divergent equipment requirements across research, clinical, and industrial workflows. Technology maturity and automation intensity create distinct margin profiles that reshape vendor resource allocation and product development priorities.
Product Type:
Maturity spans from legacy manual platforms to emerging robotic systems, with automation intensity determining price positioning and service attachment rates.
- Automated Sealers:Programmable pressure and temperature control enables walk-away operation in high-throughput pharmaceutical screening facilities. Pharmaceutical companies in Germany and the United States prioritize these systems for compliance with FDA 21 CFR Part 11 electronic records mandates.
- Manual Sealers:Hand-operated lever mechanisms apply uniform pressure for low-volume research applications. Academic institutions in France and Spain retain substantial procurement volume due to capital budget constraints and intermittent usage patterns.
- Thermal Sealers:Direct heat application bonds polypropylene-compatible films across temperature extremes from minus 80 to 110 degrees Celsius.
- UV Sealers:Photochemical curing systems eliminate thermal stress for temperature-sensitive reagent plates.
Manual sealers retain volume leadership; automated sealers hold the steepest expansion curve.
End User:
Customer type determines validation burden, with regulated pharmaceutical environments demanding extensive documentation that research laboratories circumvent.
- Pharmaceutical Companies:Integrated drug discovery pipelines require validated sealing workflows compatible with automated liquid handlers and thermal cyclers. FDA enforcement of Good Laboratory Practice standards in United States facilities drives replacement cycles and bundled service contracts.
- Research Laboratories:Flexible protocol requirements favor modular equipment configurations adaptable across nucleic acid extraction, sequencing, and storage applications. Contract research organizations in Switzerland and the Netherlands concentrate demand for multi-format compatibility.
- Academic Institutions:Grant-funded capital constraints favor entry-level manual systems with minimal maintenance requirements.
- Clinical Research Organizations:Multi-site trial logistics demand portable sealing solutions with standardized performance documentation.
Academic institutions anchor procurement volume; pharmaceutical companies generate the highest margin concentration.
Technology:
Application temperature range and film compatibility create distinct technical performance tiers that segment addressable markets.
- Heat Sealing:Thermal bonding of adhesive films achieves sub-0.5% evaporation rates at 90 degrees Celsius, supporting long-term biobanking and thermal cycling applications. German reference laboratories standardize on heat-sealed polypropylene plates for centralized diagnostic workflows.
- Adhesive Sealing:Pressure-activated films enable room-temperature sealing without energy input, suited to field-deployable diagnostic platforms. Point-of-care expansion in India favors adhesive formats for battery-independent operation.
- Vacuum Sealing:Negative pressure-assisted film application ensures uniform adhesion across irregular plate surfaces.
- Robotic Sealing:Vision-guided placement systems integrate with automated sample preparation lines for unattended operation.
Heat sealing dominates installed base; adhesive sealing gains share fastest in decentralized testing environments.
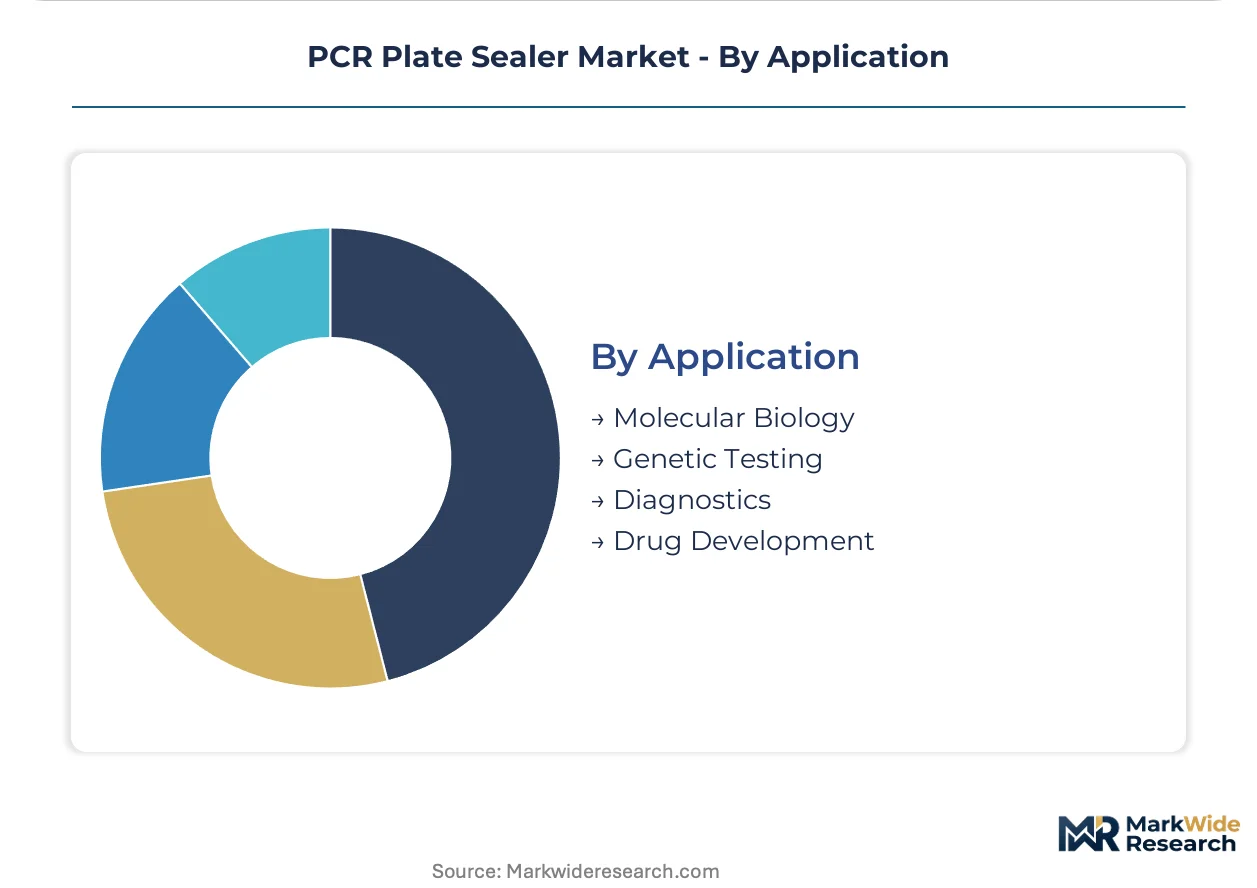
Application:
Regulatory classification intensity varies sharply, with diagnostic applications triggering EU In Vitro Diagnostic Regulation compliance that research workflows escape.
- Diagnostics:Clinical laboratory applications require ISO 13485 quality management certification and extensive performance documentation for EU regulatory submission. French and Italian hospital laboratories prioritize pre-validated systems to compress procurement timelines.
- Drug Development:High-throughput screening demands seal integrity across extended compound storage and thermal cycling protocols. United States contract research organizations specify automated sealers with remote monitoring capabilities.
- Molecular Biology:Research-grade nucleic acid workflows prioritize film compatibility with qPCR and sequencing chemistries.
- Genetic Testing:Direct-to-consumer and clinical genetics applications require traceable sample handling with chain-of-custody documentation.
Molecular biology retains the broadest installed base; diagnostics commands the steepest regulatory-driven replacement cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites the Netherlands' role in European biobanking distribution, while direct rail links from Frankfurt to Basel accelerate diagnostic equipment transit across the Rhine corridor.
United States
FDA 21 CFR Part 11 enforcement drives pharmaceutical facility upgrades in Massachusetts and North Carolina. The agency's Good Laboratory Practice inspections compress replacement cycles for non-compliant legacy sealers. Boston's Kendall Square biotech cluster demands walk-away automation compatible with 24-hour screening operations.
Germany
Centralized reference laboratories in Berlin and Munich standardize procurement specifications across automated sample preparation platforms. The EU In Vitro Diagnostic Regulation imposes performance documentation burdens that favor pre-validated system suppliers. The Rhine-Main biotech corridor concentrates demand for heat-sealing workflows in diagnostic manufacturing.
China
NMPA medical device registration reforms accelerate domestic diagnostic equipment approvals in Shanghai and Suzhou. The Yangtze River Delta's contract research expansion creates demand for multi-format sealing compatibility. Shenzhen's precision manufacturing base supplies component modules to international OEMs.
India
CDSCO streamlined licensing for in-vitro diagnostics opens point-of-care expansion in Maharashtra and Karnataka. Government biotech parks in Hyderabad and Bengaluru incubate local sealing equipment assembly. The Delhi-Mumbai Industrial Corridor logistics network reduces film consumable distribution costs to decentralized testing sites.
Switzerland
Swissmedic quality system expectations align with ISO 13485 certification requirements for clinical laboratory suppliers. Basel's pharmaceutical headquarters concentrate high-throughput screening demand. The country's precision engineering tradition supports specialized application engineering services for nucleic acid workflow integration.
PCR Plate Sealer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in film chemistry and precision mechanics. The vendor base separates into three tiers: multinational life science conglomerates with thermal cycler installed bases; mid-cap automation specialists with regional application support; and consumables-focused suppliers bundling films with entry-level hardware. Consolidation pressures intensify as pharmaceutical procurement concentrates through integrated delivery networks. Two dominant competitive moves are emerging: backward integration into specialized film manufacturing to secure supply continuity, and cloud service attachment to hardware contracts for recurring revenue conversion.
Among German precision engineering specialists, Eppendorf exemplifies the mid-cap archetype anchored in European research markets. Thermo Fisher Scientific occupies a position as a platform integrator leveraging thermal cycler installed bases for sealing equipment bundling. QIAGEN sits within the workflow integration tier, representing suppliers that reduce customer burden through pre-validated nucleic acid extraction system compatibility.
| Leading Market Players |
|---|
| Eppendorf |
| QIAGEN |
| Thermo Fisher Scientific |
| Danaher Corporation |
| F. Hoffmann-La Roche |
| Agilent Technologies |
| Corning |
| Azenta Life Sciences |
| Bio-Rad Laboratories |
| Others |
Value Network & Pricing Analysis
Shenzhen's precision manufacturing cluster anchors global component supply for PCR plate sealing equipment, with capacity utilization swings in Guangdong Province transmitting directly to OEM pricing power in European and North American markets. The concentration of stepper motor and heating element production within this hub creates asymmetric leverage for contract manufacturers negotiating with mid-tier automation vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11-validated automated systems from entry-level manual units and research-grade thermal sealers. Price differentiation centers on ISO 13485 certification status and bundled service contract depth, with pharmaceutical buyers in Germany and the United States showing lowest sensitivity due to compliance-driven procurement mandates. Cost compression in the economy tier is intensifying because academic budget constraints in France and Spain favor lowest-capital entry points. Research laboratories exhibit highest price sensitivity, while clinical diagnostic facilities prioritize total cost of ownership over upfront hardware expenditure.
Supply Chain Analysis
Export-control restrictions on precision motion control systems limit component flows from certain jurisdictions to Chinese diagnostic equipment assemblers. Supply concentrates in Germany for precision-engineered sealing mechanics, Japan for thermal control modules, and China for commodity electronic subassemblies. Raw material dependencies encompass polypropylene resin for plate compatibility validation, specialized adhesive films requiring petrochemical feedstocks, and rare-earth elements in heating element construction. Single-source vulnerability around qualified film converters represents the dominant structural risk. Distribution runs through life science distributors in North America, direct OEM relationships in Germany, and government procurement channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected validation services and predictive maintenance contracts are expanding faster than hardware unit sales, transforming PCR plate sealer economics from capital equipment transactions toward recurring revenue architectures.
For Market Incumbents: Entrench platform dominance by backward integration into specialized film manufacturing to secure supply continuity against petrochemical volatility, and deepen regulatory dossier libraries to compress customer validation timelines. Threat substitution from adhesive sealing technologies in point-of-care markets demands defensive patent positioning. Certification investment in ISO 13485 quality systems serves as the priority lever for clinical laboratory market access retention. For New Entrants and Emerging Players: Build out portable sealing formats for decentralized diagnostic testing in Maharashtra and Karnataka, where CDSCO streamlined licensing has opened procurement channels underserved by incumbent automation-heavy portfolios. The most penetrable segment lies in battery-independent adhesive sealing for field-deployable platforms. A service-led go-to-market angle emphasizing rapid installation qualification support differentiates against established vendors with slower response architectures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors workflow integration specialists with pre-validated nucleic acid extraction compatibility over standalone hardware manufacturers. Long-term viability across the five-to-ten year horizon rests on recurring revenue conversion capability rather than unit shipment volume. The acquisition target archetype encompasses mid-cap automation vendors with installed bases in European reference laboratories but underdeveloped service attachment rates. The signal to watch is consolidation velocity among German centralized diagnostic networks, which would accelerate standardization around preferred supplier platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Validation Platform Launch | Remote monitoring capabilities satisfy FDA 21 CFR Part 11 electronic records mandates for pharmaceutical customers. |
| Backward Integration into Film Manufacturing | In-house production of specialized sealing films mitigates petrochemical feedstock pricing volatility exposure. |
| ISO 13485 Quality System Certification | Certification functions as market access threshold for clinical laboratory suppliers under EU In Vitro Diagnostic Regulation. |
| Point-of-Care Miniaturization Development | Battery-independent adhesive formats address underpenetrated decentralized testing expansion in India and Southeast Asia. |
| Strategic Partnership with Thermal Cycler OEMs | Integration with automated liquid handler and thermal cycler brands reduces customer programming burden. |
Research Methodology
Desk research of SEC filings from life science conglomerates, FDA 510(k) and EU MDR submission databases, and trade flow records from German and Chinese customs authorities preceded structured interviews with diagnostic laboratory directors, pharmaceutical automation engineers, GPO contracts managers, and aftermarket service heads at major OEMs. Bottom-up equipment shipment estimates triangulated against top-down market sizing derived from thermal cycler installed base analysis and consumables attach-rate modeling.
Assumptions regarding regulatory harmonization between FDA and EMA quality system expectations, petrochemical feedstock pricing stability, and consolidation velocity among North American integrated delivery networks were held fixed across baseline scenarios while sensitivity testing varied automation adoption rates in academic versus clinical settings. The analytical framework segmented volume and value outputs across product type, end user, technology, and application dimensions, with CAGRs derived from regression analysis against thermal cycler replacement cycles and nucleic acid testing volume growth. Forecast inputs encompassed pharmaceutical R&D expenditure trends and diagnostic laboratory accreditation expansion rates.
Stress conditions across EU In Vitro Diagnostic Regulation implementation timelines, NMPA medical device registration reform velocity in China, and CDSCO licensing streamlining effectiveness in India were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained enforcement of Good Laboratory Practice standards and continued centralization of German reference laboratory networks. Material shifts in FDA 21 CFR Part 11 interpretation or accelerated adhesive sealing technology substitution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Medical Equipment Rental Market