
 Medical Gas Cylinders Market | 2026-2036
Medical Gas Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Gas Cylinders Market Outlook
Homecare settings is reorganizing demand within the Medical Gas Cylinders Market as chronic respiratory patients shift from hospital-based oxygen therapy to portable home systems. Linde Plc anchors its position through extensive gas distribution infrastructure spanning North America and Europe. Luxfer Holdings Plc specializes in lightweight aluminum and composite cylinder designs that reduce patient transport burden. Everest Kanto Cylinder Ltd. dominates manufacturing scale across Asian markets with high-volume steel and aluminum production lines.
Medical gas cylinders are sealed pressure vessels constructed from aluminum, steel, or composite materials, designed to store and dispense medical-grade gases at pressures typically ranging from 2,000 to 3,000 psi for therapeutic and emergency applications. Oxygen cylinders lead product type demand due to chronic disease prevalence and emergency preparedness requirements, while composite and carbon fiber materials represent the fastest-growing material segment as weight reduction becomes critical for ambulatory and homecare portability. Aluminum occupies the mature volume position in hospital infrastructure, where fixed installations prioritize cost efficiency over portability.
FDA enforces strict material biocompatibility and pressure vessel certification under 21 CFR requirements, while ISO 7866 and ISO 9809 govern international design and testing protocols that manufacturers must satisfy for cross-border market access. The EU MDR and CE marking framework impose additional conformity assessment burdens on cylinder suppliers seeking European distribution channels. Stakeholders must monitor evolving composite material qualification timelines and regional hospital privatization trends that will determine whether lightweight premium cylinders or standardized steel units capture the next wave of institutional procurement.
Market Dynamics
Homecare oxygen delivery is compressing hospital infrastructure demand while composite cylinder technology redraws material specifications across therapeutic and emergency applications.
Growth Catalysts
- India PLI Scheme:Domestic production incentives accelerate local manufacturing scale for steel and aluminum cylinders serving government hospital procurement.
- ISO 13485 Certification:Traceability mandates drive quality investment among suppliers seeking cross-border medical device market access.
- Carbon Fiber Composites:Ambulatory patient transport requirements pull lightweight material substitution in portable oxygen systems.
Market Restraints
- Aluminum Input Volatility:Raw material price swings compress margin buffers for high-volume cylinder producers dependent on metal supply chains.
- EU MDR Compliance Burden:Conformity assessment timelines extend product launch windows for European distribution channels.
- Fixed Hospital Infrastructure:Institutional procurement cycles favor standardized steel units over premium lightweight alternatives in cost-constrained budgets.
Strategic Opportunities
- Rural India Penetration:District hospital expansion under national health missions creates procurement volume for basic oxygen cylinder configurations.
- Wearable Oxygen Integration:Convergence of pulse-dose delivery systems with ultra-lightweight composite vessels enables continuous ambulatory therapy.
- Direct-to-Patient Channels:Home medical equipment distributors bypass traditional institutional procurement for chronic respiratory patient segments.
Industry Challenges
- Composite Qualification Timelines:Pressure vessel certification for carbon fiber designs requires extended testing protocols under ISO 9809.
- Specialized Welding Labor:High-purity gas cylinder production faces technician scarcity for precision seam welding operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Gas Cylinders Market |
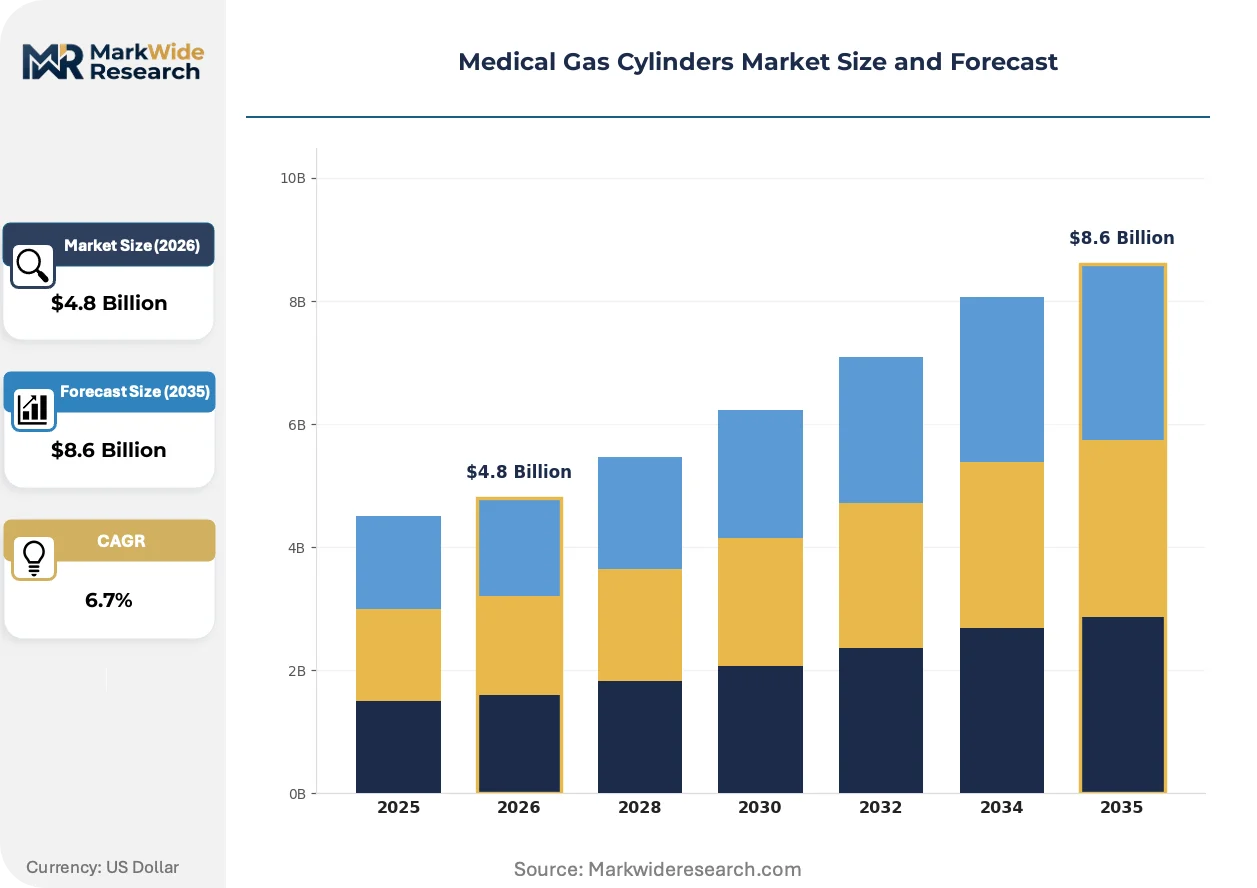
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Cylinders, Nitrous Oxide Cylinders, Acetylene Cylinders, Carbon Dioxide Cylinders End User: Hospitals, Homecare Settings, Ambulance Services, Clinics Material: Aluminum, Steel, Composite, Carbon Fiber Application: Anesthesia, Medical Treatment, Emergency Services, Laboratory Use |
| Companies Covered | Air Liquide SA, Linde Plc, Atlas Copco AB, Worthington Industries Inc., Luxfer Holdings Plc, Faber Industrie SPA, Everest Kanto Cylinder Ltd., CIMC ENRIC Holdings Ltd., B.N.O.S. Meditech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Gas Cylinders Market Strategic Shifts
Material science advances and regulatory harmonization efforts are compressing traditional cylinder specifications while expanding portable therapeutic possibilities.
Carbon fiber-wrapped aluminum liners are miniaturizing cylinder footprints without sacrificing gas capacity. Homecare oxygen providers accelerate adoption of sub-five-pound configurations for chronic obstructive pulmonary disease patients. This technology is miniaturizing patient mobility constraints that previously tethered users to stationary concentrators.
EU MDR technical documentation requirements tighten biocompatibility verification for cylinder interior coatings and valve assemblies. Manufacturers serving European markets extend quality management system investments to satisfy notified body scrutiny. Composite material suppliers face the steepest compliance ramps as novel substances lack grandfathered regulatory recognition.
Hospital group purchasing organizations consolidate supplier rosters around multi-year oxygen service contracts bundling cylinders, refills, and maintenance. Independent durable medical equipment dealers lose share to integrated gas distributors offering total cost guarantees. This consolidation is most visible in United States metropolitan markets where health system mergers concentrate buying power.
Medical Gas Cylinders Market Segmentation
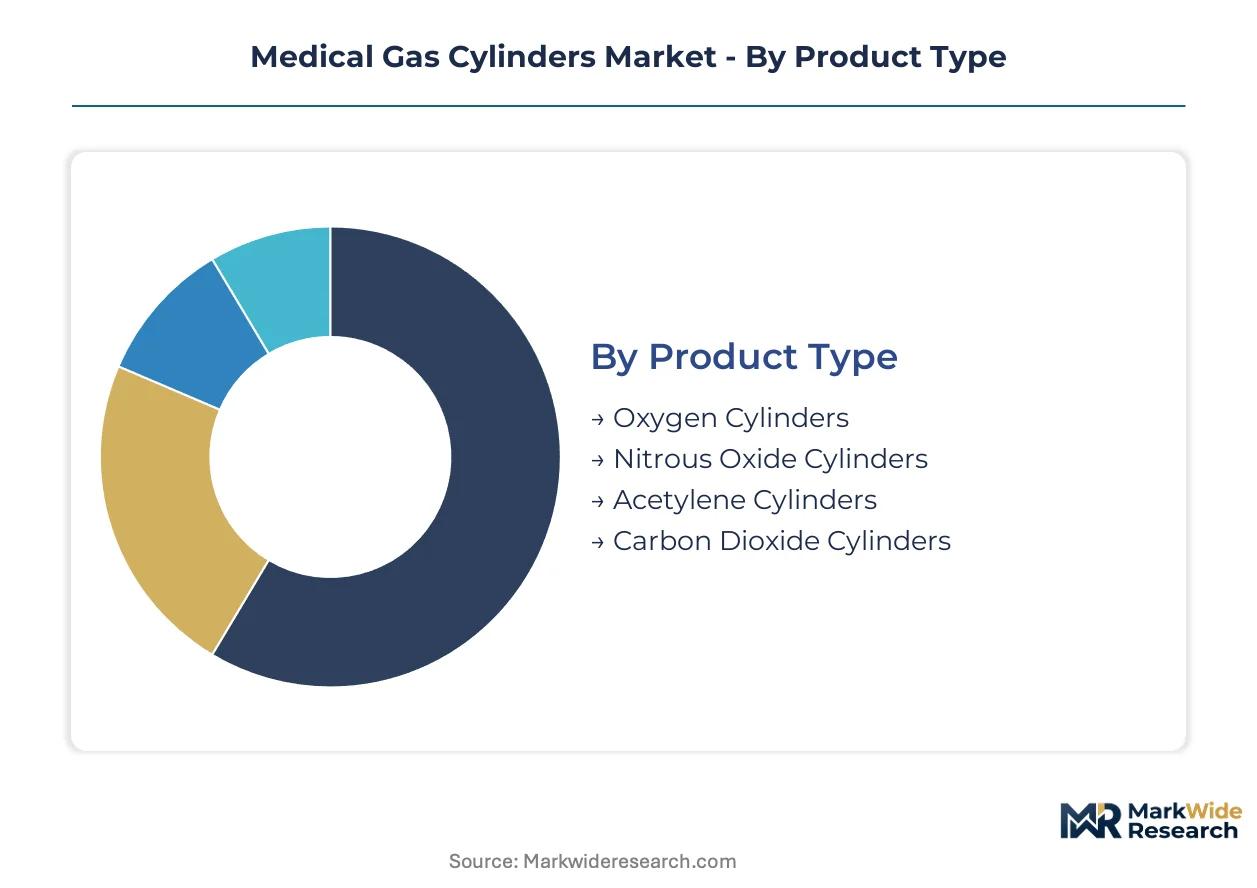
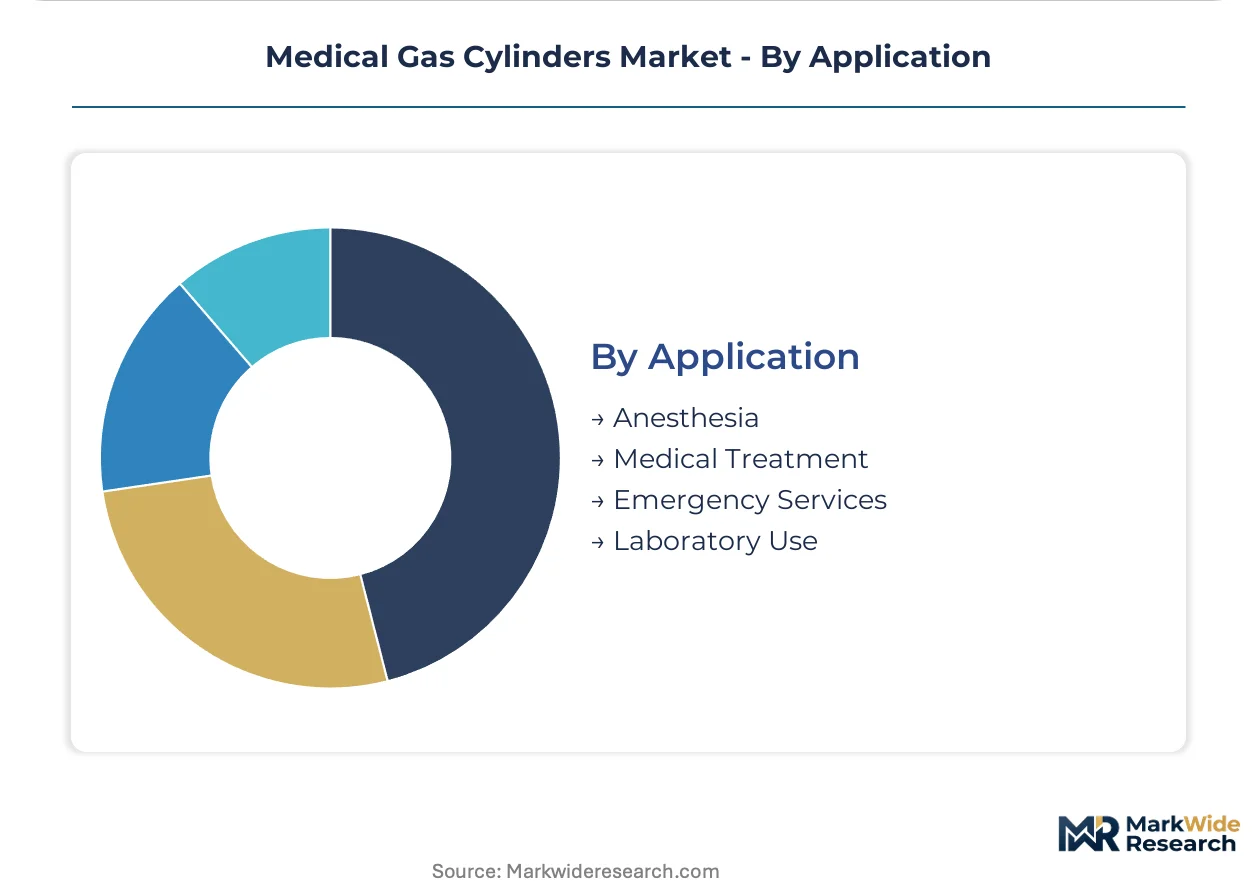
Segmentation in medical gas cylinders reveals how material substitution and care setting migration reshape procurement priorities across therapeutic applications. Cylinder manufacturers must calibrate product portfolios to diverging technical specifications between institutional infrastructure and portable homecare systems.
Product Type:
Oxygen cylinders face the strongest substitution pressure from concentrator technology, while specialty gas configurations defend their position through irreplaceable clinical applications.
- Oxygen Cylinders:These vessels store medical-grade oxygen at pressures up to 3,000 psi for respiratory therapy and emergency resuscitation. Demand concentrates in Indian district hospitals expanding under national health missions, constrained by concentrator reliability concerns in power-unstable regions.
- Nitrous Oxide Cylinders:Designed for anesthetic delivery in surgical suites, these cylinders maintain precise pressure regulation for controlled gas flow. Dental clinics and ambulatory surgery centers in the United States drive procurement volume amid outpatient procedure growth.
- Acetylene Cylinders:Specialized vessels for surgical cauterization equipment with acetone-dissolved gas storage. Hospital procurement departments bundle these with oxygen contracts under group purchasing organization frameworks.
- Carbon Dioxide Cylinders:Compressed CO2 systems for insufflation in laparoscopic procedures and laboratory cell culture incubation. Research institutions and tertiary surgical centers represent the concentrated demand base.
Oxygen cylinders retain volume leadership; carbon dioxide configurations hold the steepest expansion curve amid minimally invasive surgery adoption.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from price-sensitive homecare channels requiring lightweight portability.
- Hospitals:Fixed installations in intensive care units and emergency departments prioritize cylinder reliability over weight reduction. Steel and aluminum units dominate procurement through multi-year gas service agreements.
- Homecare Settings:Portable oxygen systems for chronic obstructive pulmonary disease patients demand sub-five-pound composite configurations. Medicare reimbursement policies in the United States shape patient acquisition economics for durable medical equipment dealers.
- Ambulance Services:Mobile emergency vehicles require rapid-exchange cylinder systems with standardized valve connections. Fire department and municipal EMS fleets concentrate procurement in North American metropolitan markets.
- Clinics:Outpatient facilities balance cost constraints against space limitations in multi-specialty practice settings. Group purchasing organization contracts extend hospital pricing tiers to affiliated clinic networks.
Hospitals command procurement volume; homecare settings are climbing the fastest as chronic disease management shifts beyond institutional walls.
Material:
Application-specific requirements segment material selection between stationary cost efficiency and ambulatory weight minimization.
- Aluminum:Seamless aluminum alloy cylinders offer corrosion resistance and moderate weight reduction for hospital infrastructure. Indian PLI scheme incentives accelerate domestic production scale for government hospital procurement programs.
- Steel:High-strength carbon steel vessels deliver lowest unit cost for high-volume oxygen storage in fixed installations. Margin compression from aluminum input volatility constrains producer profitability in this mature segment.
- Composite:Polymer-matrix wrapped liners achieve significant weight reduction for patient transport applications. FDA 21 CFR biocompatibility requirements extend qualification timelines for novel resin formulations.
- Carbon Fiber:Filament-wound carbon fiber overwrap delivers maximum strength-to-weight ratio for wearable oxygen systems. ISO 9809 pressure vessel certification protocols impose extended testing burdens on manufacturers pursuing this premium tier.
Steel retains institutional volume leadership; carbon fiber configurations gain share fastest in ambulatory and homecare portability segments.
Application:
Customer type differentiation separates regulated therapeutic uses from research laboratory procurement with divergent compliance burdens.
- Anesthesia:Precision-blended gas delivery systems for operating room inhalational anesthesia. Nitrous oxide and oxygen mixtures in this application face limited substitution from intravenous anesthetic alternatives.
- Medical Treatment:Long-term oxygen therapy and acute respiratory support in clinical and home settings. Chronic disease prevalence in aging populations sustains baseline demand for therapeutic oxygen delivery.
- Emergency Services:Rapid-deployment cylinders for cardiac arrest, trauma, and respiratory failure intervention. Ambulance fleet standardization around DIN valve connections streamlines equipment interoperability.
- Laboratory Use:Ultra-high-purity gas containment for cell culture, chromatography, and analytical instrumentation. Research universities and pharmaceutical quality control labs concentrate demand for specialized cylinder interior coatings.
Medical treatment applications anchor volume; emergency services are expanding most quickly amid pre-hospital care system investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in India and China, where government production incentives and expanding hospital infrastructure compress unit costs for steel and aluminum cylinders. European and North American markets pull premium composite configurations for ambulatory homecare segments. Regulatory divergence across FDA, EU MDR, and CDSCO frameworks fragments certification timelines for cross-border suppliers.
United States
Medicare reimbursement policies for durable medical equipment shape patient acquisition economics for portable oxygen systems. FDA enforces 21 CFR biocompatibility requirements for cylinder interior coatings and valve assemblies. Metropolitan health system mergers in markets like Houston and Phoenix concentrate procurement through group purchasing organizations bundling gas service contracts.
Germany
Industrial gas distribution networks anchor cylinder demand from university hospitals and research institutions requiring ultra-high-purity containment. EU MDR technical documentation mandates extend conformity assessment timelines for notified body scrutiny. The Rhine-Ruhr industrial corridor hosts precision welding specialists serving medical pressure vessel fabrication.
India
PLI scheme incentives for medical device manufacturing accelerate domestic production scale for government hospital procurement programs. CDSCO tightens traceability mandates for cylinder materials under revised medical device rules. Manufacturing clusters in Gujarat and Maharashtra concentrate high-volume steel and aluminum cylinder output for district hospital expansion.
China
NMPA pressure vessel certification protocols govern carbon fiber composite qualification for wearable oxygen applications. Yangtze River Delta fabrication hubs supply standardized steel cylinders for institutional procurement across domestic hospital networks. Local producers leverage GB standards alignment to compress export compliance costs for Southeast Asian markets.
Japan
Aging population demographics sustain chronic respiratory therapy demand for lightweight homecare configurations. METI industrial policy supports carbon fiber material R&D for next-generation pressure vessel applications. Osaka-Kobe manufacturing corridors specialize in precision aluminum cylinder production for domestic and regional export.
Medical Gas Cylinders Market Competitive Environment
Concentration sits with diversified industrial gas distributors and specialized cylinder fabricators competing across diverging cost and performance tiers. The vendor base spans multinational gas majors with integrated distribution infrastructure, mid-scale metal forming specialists, and emerging composite material innovators. Three archetypes dominate: gas-integrated distributors bundling cylinder and refill services, standalone cylinder manufacturers selling through third-party channels, and composite technology specialists targeting premium ambulatory segments. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure raw material supply and regional distribution access.
Among gas-integrated distributors, Air Liquide SA and Linde Plc exemplify the archetype of infrastructure-heavy players leveraging captive distribution networks. Luxfer Holdings Plc occupies a position within the specialty materials tier, representing composite-focused engineering capabilities. Everest Kanto Cylinder Ltd. anchors the high-volume manufacturing segment, exemplifying scale-driven production for emerging market procurement.
| Leading Market Players |
|---|
| Air Liquide SA |
| Linde Plc |
| Atlas Copco AB |
| Worthington Industries Inc. |
| Luxfer Holdings Plc |
| Faber Industrie SPA |
| Everest Kanto Cylinder Ltd. |
| CIMC ENRIC Holdings Ltd. |
| B.N.O.S. Meditech Ltd. |
| Others |
Value Chain & Pricing Dynamics
Indian PLI scheme capacity utilization above 80 percent compresses unit economics for steel and aluminum cylinders, concentrating supply power among high-volume fabricators and establishing price floors that marginal producers cannot match. This scale concentration enables tiered pricing separation across certification grades, with ISO 9809-tested vessels commanding premiums over basic DOT specifications.
Pricing Analysis
Volume-discount tiering structures separate hospital group purchasing organization contracts from spot procurement by independent durable medical equipment dealers. Price differentiation hinges on FDA 21 CFR biocompatibility certification and after-sales gas refill bundling. Cost compression in standard steel configurations is intensifying because aluminum input volatility erodes margin buffers. Homecare patients through Medicare reimbursement channels exhibit highest price sensitivity; tertiary surgical centers with captive maintenance staff show lowest.
Supply Chain Analysis
Inventory lead times for carbon fiber composite liners extend 16-20 weeks due to filament-winding capacity constraints at specialized tier-two suppliers. Manufacturing concentrates in India, China, and Germany for finished cylinder assembly, drawing from aluminum billet, high-strength steel coil, and epoxy-impregnated carbon fiber tow. Single-source vulnerability sits with Japanese Toray-equivalent carbon fiber precursors. Distribution runs through industrial gas majors' captive logistics networks rather than independent channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical gas cylinder markets present a service-attach opportunity as gas refill and preventive maintenance contracts expand faster than hardware unit sales, with recurring revenue multiples exceeding equipment margins.
For Market Incumbents: Compound defensive positioning through backward integration into aluminum billet casting and carbon fiber precursor supply. Oxygen concentrator substitution threatens portable cylinder demand; counter by deepening ISO 13485-certified refurbishment service layers that concentrator manufacturers cannot replicate. Add filament-winding capacity in Gujarat manufacturing clusters to capture Indian government hospital procurement volume. For New Entrants and Emerging Players: CDSCO fast-track approval pathways for district hospital tenders offer lower regulatory barriers than FDA or EU MDR routes. Target rural India penetration under national health mission expansion, where basic steel oxygen configurations face supply gaps. Go-to-market through state medical services corporation direct contracts bypassing established gas distributor intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors composite material specialists with qualified ISO 9809 carbon fiber designs over legacy metal forming assets. Long-term viability rests on wearable oxygen convergence enabling continuous ambulatory therapy. Watch FDA 510(k) clearance velocity for sub-five-pound composite configurations as inflection indicator for homecare substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Traceability mandates from FDA and CDSCO lock out uncertified competitors from cross-border procurement. |
| Carbon Fiber Composite Scale-Up | Filament-winding capacity additions in India capture PLI incentives and district hospital lightweight cylinder demand. |
| Hospital System Partnership | Multi-year gas service contracts with GPOs bundle cylinders, refills, and maintenance into exclusive supplier relationships. |
| Backward Integration into Aluminum | In-house billet casting insulates margin from LME price volatility affecting high-volume steel-alternative production. |
| Reimbursement Strategy Development | Medicare DME contractor alignment shapes patient acquisition economics for homecare portable oxygen configurations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CDSCO medical device registration databases, Indian government hospital procurement records, and ISO certification registries. Interviews with biomedical engineers, GPO contracts managers, cylinder fabrication plant managers, and homecare DME dealers combined with trade data from DGFT and customs records. Bottom-up unit economics triangulate against top-down gas distributor revenue segment disclosures.
Segmentation dimensions modeled include material type, product gas specification, end-use setting, and geographic regulatory cluster across the projection horizon. CAGRs derive from installed base replacement cycles, hospital bed expansion forecasts, and homecare patient population projections. Industry-specific inputs incorporate oxygen concentrator reliability data for power-unstable regions and composite pressure vessel qualification timelines under ISO 9809.
Underlying assumptions cover aluminum price band stability, PLI scheme continuity, and EU MDR notified body capacity, with deviation risk concentrated in carbon fiber supply concentration and district hospital budget execution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Cath Lab Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Brazil Massage Equipment Market