
 Dialyzer Reprocessing Machines and Concentrates Market | 2026-2036
Dialyzer Reprocessing Machines and Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Dialyzer Reprocessing Machines and Concentrates Market Outlook
Multi-source procurement for reprocessing chemicals is realigning how dialysis chains manage supply risk. Fresenius Medical Care leverages captive manufacturing to secure concentrate supply across its clinic network. Baxter International anchors its position through integrated distribution into hospital purchasing cooperatives. B. Braun Melsungen AG differentiates via heat disinfection technology leadership in European regulatory environments.
Dialyzer reprocessing machines and concentrates encompass automated and manual systems that clean, disinfect, and restore hollow-fiber dialyzers for repeated patient use, typically achieving 10-20 reuse cycles per unit depending on membrane material and disinfection modality. These systems employ peracetic acid, formaldehyde, or heat-based protocols to maintain biocompatibility and solute clearance performance across successive treatments. Automated reprocessors dominate installed base value given labor reduction and standardization benefits, while concentrate solutions command recurring revenue streams tied to treatment volume. Membrane filtration technology leads technology segmentation due to its compatibility with high-flux dialyzers, and hemodialysis application share reflects the modality's prevalence over peritoneal alternatives in most developed markets.
FDA 510(k) clearance requirements govern reprocessor safety and efficacy claims in the United States, while EMA's Medical Device Regulation imposes clinical evidence standards across European markets and Japan's PMDA enforces post-market surveillance for disinfectant residue limits. These frameworks elevate barriers for new entrants and compel incumbents to maintain dedicated regulatory affairs functions. Stakeholders must monitor evolving sterility assurance level expectations and chemical safety thresholds as reuse protocols face renewed scrutiny from infection control bodies.
Market Dynamics
Cost-containment mandates from Medicare and private payers are forcing dialysis chains to extend dialyzer reuse cycles beyond historical norms, compressing capital recovery timelines for reprocessing equipment and intensifying concentrate procurement negotiations.
Growth Catalysts
- EMA MDR clinical evidence requirements:Stringent post-market surveillance for reusable dialyzer systems elevates validation standards that favor established automated reprocessor suppliers with dedicated regulatory affairs infrastructure.
- Heat disinfection protocols:European clinic networks are migrating from chemical sterilants toward thermal-based reprocessing to eliminate disinfectant residue monitoring burdens and reduce per-treatment supply costs.
- United States ESRD prevalence concentration:Medicare reimbursement structures sustain clinic infrastructure investment across Florida, Texas, and California dialysis corridors, anchoring installed base expansion for automated systems.
Market Restraints
- Peracetic acid supply concentration:Three chemical manufacturers control bulk concentrate production for North American dialysis chains, exposing procurement functions to input cost volatility and force majeure disruption risk.
- FDA 510(k) clearance timelines:Novel reprocessor submissions face extended review cycles for sterility assurance level claims, delaying commercialization of membrane filtration innovations by 18-24 months versus historical baselines.
- Single-use dialyzer substitution:Polyethersulfone membrane manufacturing scale economies are narrowing the cost gap between reprocessed and disposable units in Japanese reimbursement environments.
Strategic Opportunities
- German outpatient dialysis expansion:Privatized nephrology clinic chains in Bavaria and North Rhine-Westphalia are consolidating purchasing cooperatives, creating volume aggregation points for integrated reprocessor-concentrate contracts.
- Remote monitoring convergence:IoT-enabled reprocessor diagnostics combined with predictive maintenance algorithms offer service revenue streams independent of per-treatment concentrate sales.
- Japan PMDA disinfectant residue guidance revision:Anticipated relaxation of formaldehyde detection thresholds would validate extended reuse protocols for high-flux dialyzers in Tokyo and Osaka metropolitan treatment centers.
Industry Challenges
- Biomedical technician certification gaps:Automated reprocessor maintenance requires specialized training in heat exchanger calibration and chemical dosing pump verification that community college programs rarely cover.
- Legacy system integration friction:Clinic networks operating mixed fleets of 1990s-era manual reprocessors face workflow disruption when introducing automated units with incompatible concentrate connector standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dialyzer Reprocessing Machines and Concentrates Market |
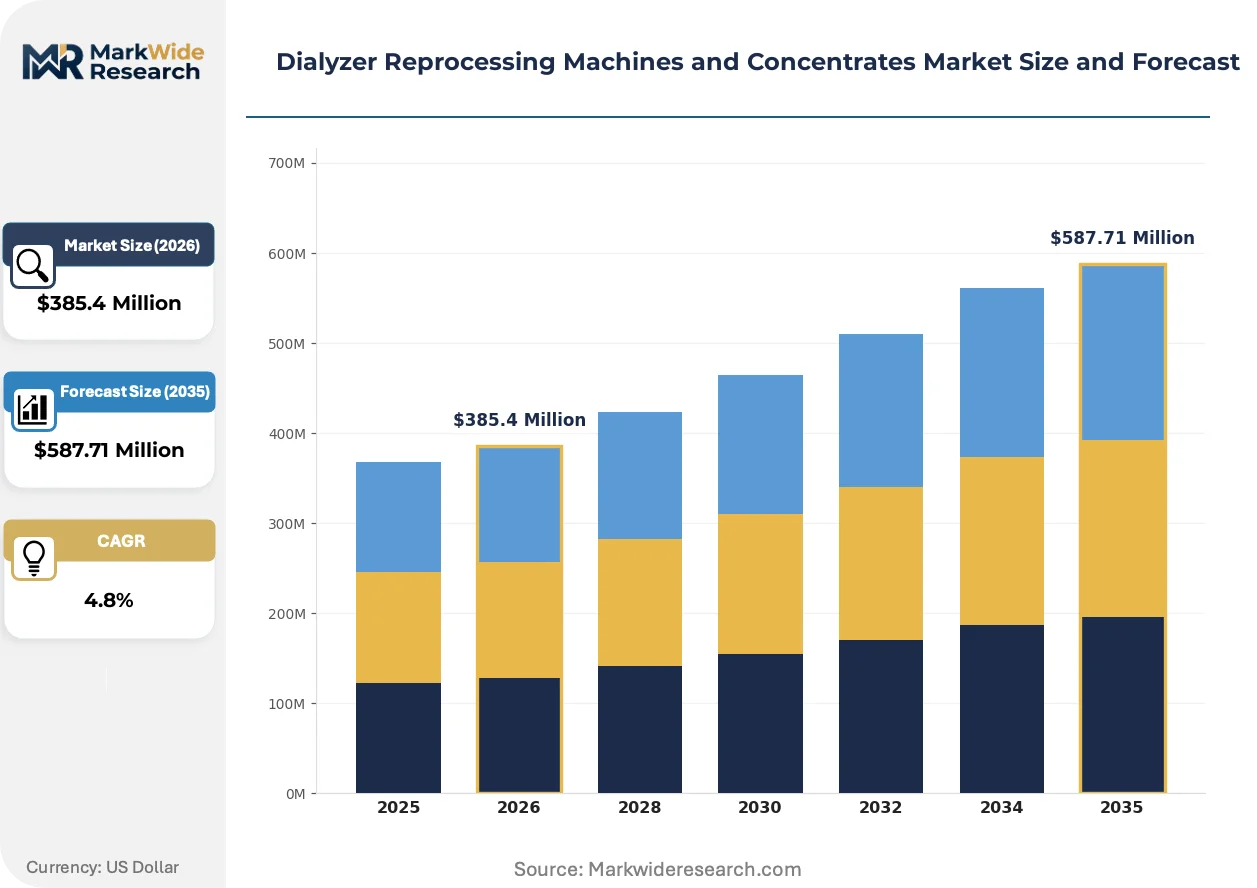
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Reprocessors, Manual Reprocessors, Concentrate Solutions, Dialysate Concentrates End User: Hospitals, Dialysis Centers, Home Care, Specialty Clinics Technology: Membrane Filtration, Chemical Reprocessing, UV Treatment, Heat Disinfection Application: Hemodialysis, Peritoneal Dialysis, Water Treatment, Equipment Sterilization |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun Melsungen AG, Medivators, Nipro Corporation, CURA Healthcare, Asahi Kasei Medical, Rockwell Medical, Anjue Medical Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dialyzer Reprocessing Machines and Concentrates Market Strategic Shifts
Reprocessing technology is converging around closed-loop automation that eliminates operator variability, while regulatory scrutiny of chemical sterilants accelerates protocol diversification across major dialysis markets.
Membrane filtration reprocessors equipped with real-time fiber bundle integrity testing are unifying quality assurance and disinfection functions within single automated workflows. Large dialysis organizations in the United States are deploying these systems at replacement cycles compressed to 5-7 years versus historical 10-year baselines. This unifying architecture is compressing the addressable market for standalone dialyzer testing equipment and redirecting capital toward integrated platform vendors.
REACH chemical authorization procedures for peracetic acid intermediates are tightening supply chain documentation requirements for European concentrate formulators. Manufacturers must now submit extended safety dossiers for biocidal product regulation compliance, elevating formulation costs and disadvantaging smaller regional blenders. German and French dialysis providers are responding by consolidating procurement around suppliers with dedicated regulatory toxicology functions.
Hospital purchasing cooperatives are capturing dialysis concentrate sourcing decisions that independent clinics previously controlled through distributor relationships. Integrated delivery networks in California and Texas are mandating sole-source contracts for reprocessing chemicals to secure volume rebates, displacing the multi-vendor strategies that dominated procurement through 2020. This concentration is most visible in academic medical center affiliations where supply chain standardization protocols override individual clinic preferences.
Dialyzer Reprocessing Machines and Concentrates Market Segmentation
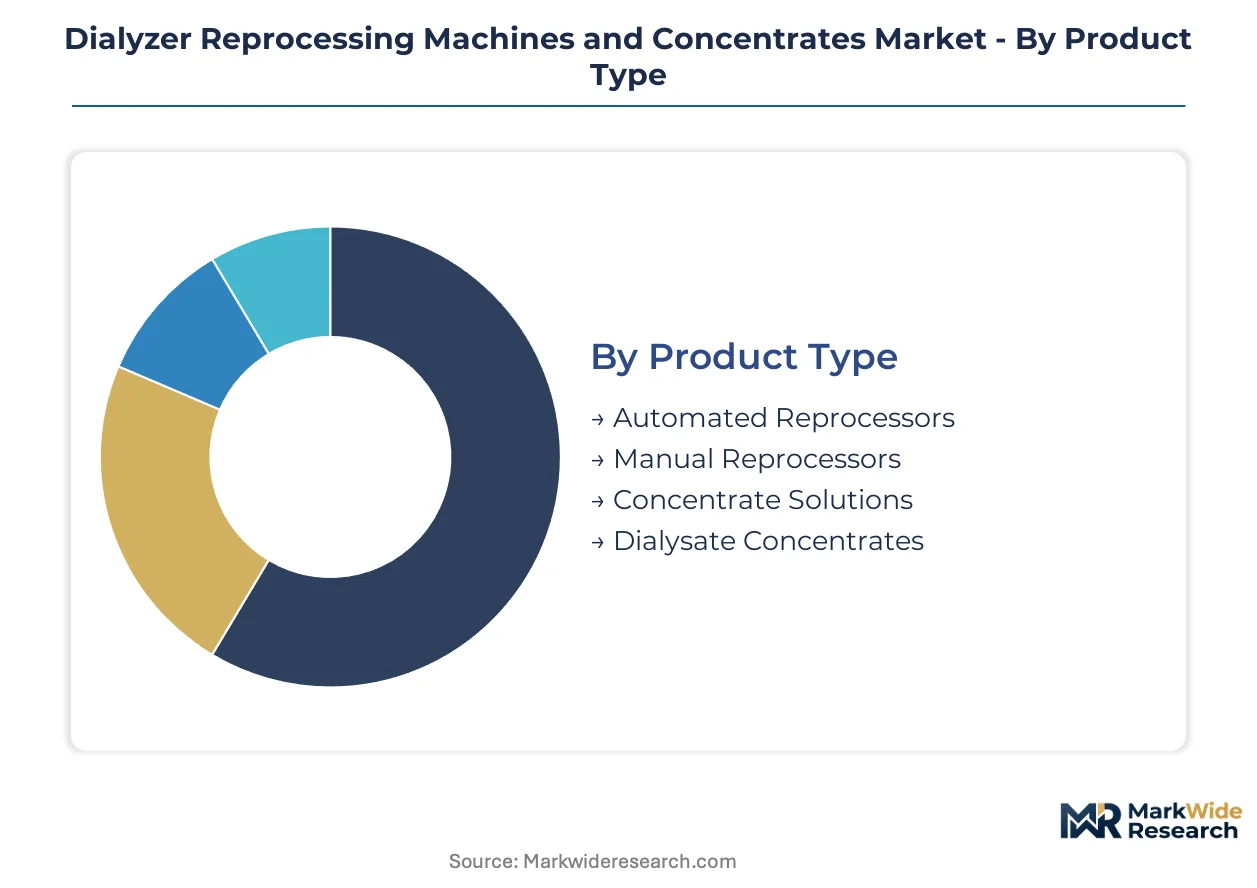
Segmentation in dialyzer reprocessing reveals how capital equipment, consumable chemistry, and disinfection protocols fragment across clinical settings. Each axis—product type, end user, technology, and application—carries distinct procurement rhythms and regulatory exposure that shape vendor strategy.
Product Type:
Equipment sophistication and recurring revenue chemistry define the product architecture.
- Automated Reprocessors:Closed-loop systems integrate cleaning, disinfection, and fiber bundle integrity testing within single workflows. Demand concentrates in United States large dialysis organizations where labor standardization and Medicare audit documentation requirements drive replacement cycles.
- Concentrate Solutions:Peracetic acid and formaldehyde formulations command recurring revenue streams tied to treatment volume. Procurement in German clinic networks is consolidating around suppliers with dedicated REACH compliance functions as ECHA documentation burdens intensify.
- Manual Reprocessors:Operator-dependent cleaning stations persist in budget-constrained settings.
- Dialysate Concentrates:Acid and bicarbonate solutions for fluid preparation represent separate chemistry supply chains from disinfectant concentrates.
Mature deployment sits with Automated Reprocessors. Newer deployment is concentrated in Concentrate Solutions as heat disinfection protocols reduce per-treatment chemical intensity.
End User:
Site of care determines capital intensity and regulatory scrutiny exposure.
- Dialysis Centers:Freestanding clinics dominate installed base value. United States Medicare reimbursement structures sustain infrastructure investment across Florida, Texas, and California treatment corridors where chain consolidation accelerates automated system deployment.
- Hospitals:Integrated delivery networks in academic medical centers mandate sole-source concentrate contracts to secure volume rebates.
- Home Care:Patient-operated reprocessing remains minimal given FDA training and infection control requirements.
- Specialty Clinics:Nephrology-focused outpatient facilities in Bavaria and North Rhine-Westphalia are consolidating purchasing cooperatives.
Volume concentration sits with Dialysis Centers. Margin expansion is concentrated in Hospitals where supply chain standardization protocols override individual clinic preferences.
Technology:
Disinfection modality selection drives chemistry procurement and residue monitoring burdens.
- Membrane Filtration:Hollow-fiber integrity testing combined with automated cleaning dominates high-flux dialyzer compatibility. Japanese PMDA post-market surveillance for disinfectant residue limits sustains validation investment in Tokyo and Osaka metropolitan centers.
- Heat Disinfection:Thermal protocols eliminate chemical sterilant documentation requirements. European clinic networks are migrating from peracetic acid toward heat-based systems to reduce REACH authorization burdens and per-treatment supply costs.
- Chemical Reprocessing:Peracetic acid and formaldehyde protocols retain installed base in legacy systems.
- UV Treatment:Ultraviolet adjunct disinfection supplements primary protocols in water treatment applications.
Regulatory tailwinds favor Heat Disinfection. Technical performance leadership remains with Membrane Filtration.
Application:
Clinical modality determines reuse cycle economics and membrane compatibility requirements.
- Hemodialysis:Blood filtration through hollow-fiber dialyzers represents the dominant reuse application. End-stage renal disease prevalence in the United States, Germany, and Japan anchors installed base expansion for automated reprocessing systems.
- Peritoneal Dialysis:Continuous ambulatory and automated peritoneal modalities use single-use dialysate bags without dialyzer reuse, excluding this segment from reprocessing equipment demand.
- Water Treatment:Reverse osmosis system disinfection employs similar chemistry but separate equipment from dialyzer reprocessors.
- Equipment Sterilization:Ancillary device disinfection represents peripheral demand.
Revenue concentration sits with Hemodialysis. Peritoneal Dialysis remains outside reprocessing scope by clinical protocol design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peracetic acid manufacturing clusters in Germany and the United States anchor supply chain geography for dialyzer reprocessing chemistry. These localities concentrate regulatory validation infrastructure and automated equipment assembly capacity. Dialysis center density follows end-stage renal disease prevalence corridors in Florida, Texas, Bavaria, and Tokyo.
United States
Medicare reimbursement structures sustain clinic infrastructure investment across Florida, Texas, and California dialysis corridors. FDA 510(k) clearance requirements govern reprocessor safety claims and elevate barriers for new equipment entrants. Large dialysis organizations in the Southeast and Southwest deploy automated systems at compressed replacement cycles.
Germany
Privatized nephrology clinic chains in Bavaria and North Rhine-Westphalia consolidate purchasing cooperatives for integrated reprocessor-concentrate contracts. EMA Medical Device Regulation imposes clinical evidence standards across European markets. REACH chemical authorization procedures for peracetic acid intermediates tighten supply chain documentation for concentrate formulators.
Japan
Post-market surveillance from PMDA enforces disinfectant residue limits in Tokyo and Osaka metropolitan treatment centers. End-stage renal disease prevalence drives clinic infrastructure investment in Kanto and Kansai regions. Anticipated relaxation of formaldehyde detection thresholds would validate extended reuse protocols for high-flux dialyzers.
France
ANSM oversight of medical device sterilization protocols shapes reprocessing equipment procurement in Île-de-France clinic networks. Heat disinfection migration reduces per-treatment chemical intensity in Paris-region dialysis centers. ECHA documentation burdens disadvantage smaller regional concentrate blenders.
United Kingdom
NHS cost-containment mandates accelerate dialyzer reuse program expansion across London and Midlands treatment facilities. MHRA conformity assessment procedures align with EMA MDR clinical evidence requirements. Hospital purchasing cooperatives capture concentrate sourcing decisions previously controlled through distributor relationships.
Dialyzer Reprocessing Machines and Concentrates Market Competitive Environment
Capacity expansion dominates the current landscape as established suppliers scale automated reprocessor manufacturing to capture replacement cycles compressed to 5-7 years. The vendor base concentrates around integrated medical technology conglomerates with dedicated regulatory affairs infrastructure. Three strategic archetypes prevail: diversified dialysis equipment suppliers with captive concentrate production, standalone reprocessor specialists with heat disinfection technology leadership, and chemical formulators with REACH compliance capabilities. M&A activity and strategic partnerships represent the dominant competitive moves as scale advantages intensify in procurement negotiations.
Among diversified medical technology conglomerates, Fresenius Medical Care and Baxter International exemplify archetypes with integrated distribution into hospital purchasing cooperatives. B. Braun Melsungen AG occupies a position representing European-focused specialists with regulatory toxicology functions. These three entities anchor competitive positioning across automated equipment and recurring concentrate revenue streams.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun Melsungen AG |
| Medivators |
| Nipro Corporation |
| CURA Healthcare |
| Asahi Kasei Medical |
| Rockwell Medical |
| Anjue Medical Equipment |
| Others |
Value Chain & Pricing Dynamics
Automated reprocessor premium tiers diverge sharply from manual system commodity segments, with FDA-validated heat disinfection platforms commanding bundled service contracts while chemical-dependent stations compete on per-cycle operating cost. This bifurcation concentrates procurement leverage among large dialysis organizations in the United States that negotiate sole-source agreements, while fragmented clinic networks in Europe face elevated per-unit chemistry costs due to REACH documentation burdens.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium automated reprocessor vendors from unbundled manual equipment suppliers in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, heat disinfection capability, and fiber bundle integrity testing integration. Pricing pressure stems from Medicare reimbursement compression forcing dialysis chains toward extended reuse cycles and lower per-treatment cost ceilings. Hospital purchasing cooperatives exhibit lowest price sensitivity given integrated delivery network standardization mandates, while independent specialty clinics in Germany demonstrate highest sensitivity to concentrate volume rebates.
Supply Chain Analysis
Dual-sourcing requirements for peracetic acid concentrates compel dialysis chains to qualify multiple chemical formulators despite manufacturing concentration in Germany and the United States. Bulk sterilant production draws from acetic acid and hydrogen peroxide feedstocks, with formulation blending capacity concentrated in Bavaria and Texas chemical corridors. Single-source vulnerability pervades heat disinfection equipment componentry sourced from Japanese precision heating element manufacturers. Distribution runs through hospital purchasing cooperatives and GPO contracts that have displaced independent distributor relationships across California and Texas clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive concentrate production and automated platform control represent the decisive upstream levers. Players securing regulatory validation infrastructure and heat disinfection intellectual property position for procurement consolidation.
For Market Incumbents: To counter single-use dialyzer substitution threats in Japanese reimbursement environments, deepen backward integration into peracetic acid intermediate production and accelerate heat disinfection platform deployment across European clinic networks. Prioritize REACH compliance certification to disqualify regional concentrate blenders from German purchasing cooperatives. For New Entrants and Emerging Players: Remote monitoring diagnostics with IoT-enabled predictive maintenance algorithms offer technology-first entry points against established equipment vendors. Target underpenetrated specialty clinic segments in Bavaria and North Rhine-Westphalia with modular heat disinfection systems. Pursue hospital purchasing cooperative qualification pathways rather than independent distributor channels. For Investors and Strategic Acquirers: Re-rating potential sits with automated reprocessor specialists possessing dedicated FDA regulatory affairs infrastructure given EMA MDR clinical evidence requirement intensification. Long-term viability hinges on recurring concentrate revenue attachment rates exceeding equipment replacement cycle compression. Watch PMDA formaldehyde guidance revision timing as inflection signal for extended reuse protocol validation in Tokyo and Osaka metropolitan centers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Chemistry | Captive peracetic acid production secures supply continuity against REACH authorization bottlenecks in Germany. |
| Heat Disinfection Platform Expansion | Thermal protocol migration eliminates chemical sterilant residue monitoring burdens across European clinic networks. |
| FDA 510(k) Regulatory Infrastructure Investment | Dedicated validation capabilities compress clearance timelines for membrane filtration innovations in United States markets. |
| Hospital Purchasing Cooperative Partnership | Sole-source contract capture displaces multi-vendor procurement strategies in California and Texas integrated delivery networks. |
| Remote Monitoring Service Layer Development | IoT-enabled diagnostics generate recurring revenue streams independent of per-treatment concentrate sales volume. |
Study Parameters
Multi-period observation of dialyzer reuse cycle extension patterns and concentrate procurement contract structures anchored the trend analysis, supplemented by interviews with dialysis chain procurement directors, biomedical engineering managers, GPO contracts specialists, and regulatory affairs leads at concentrate formulators. Secondary validation drew from FDA 510(k) clearance databases, EMA MDR submission records, CMS Medicare reimbursement filings, and hospital purchasing cooperative contract disclosures. Bottom-up equipment installed base modeling triangulated against top-down chemistry consumption estimates across the analysis window.
Segment-weighting approaches applied differential growth assumptions across automated reprocessor, manual system, and concentrate solution product categories, further disaggregated by heat disinfection versus chemical protocol technology splits and hemodialysis versus water treatment application boundaries. CAGRs derived from treatment volume projections tied to ESRD prevalence corridors in Florida, Texas, Bavaria, and Tokyo. Modeling incorporated replacement cycle compression effects from membrane filtration integrity testing integration and REACH compliance cost pass-through assumptions for European concentrate formulators.
Several conditions sit outside the modeled scope, including abrupt single-use dialyzer cost parity achievement in Japanese markets, force majeure disruption of acetic acid feedstock supply, and radical PMDA disinfectant residue threshold tightening. Forecasts reflect documented assumptions regarding Medicare reimbursement stability and EMA MDR enforcement consistency. Deviation in heat disinfection technology adoption velocity or peracetic acid authorization timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Medical Automation Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Single-Coated Medical Tape Market