
 Silastic Implant Market | 2026-2036
Silastic Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Silastic Implant Market Analytics
Cross-linked silicone elastomer formulation is narrowing the performance gap between aesthetic and reconstructive applications, forcing manufacturers to unify quality systems across both pathways. Dow Inc leverages backward integration into siloxane monomer production to control raw material purity. Momentive Performance Materials sustains R&D intensity through dedicated medical-grade compounding facilities. Wacker Chemie AG anchors European supply with ISO 13485-certified manufacturing sites in Germany.
Silastic implants are medical devices constructed from cross-linked polydimethylsiloxane elastomer, typically vulcanized via platinum-catalyzed addition cure to achieve Shore A hardness between 20 and 70 for tissue-mimicking compliance; their primary purpose is permanent soft-tissue augmentation or replacement in reconstructive and cosmetic procedures. Breast implants occupy the largest revenue pool due to established reimbursement pathways for post-mastectomy reconstruction, while penile implants represent the fastest-growing segment driven by rising diabetes-related erectile dysfunction referrals. Manufacturing type splits reveal injection molding dominates high-volume production for standardized shapes, whereas 3D printing emerges for patient-specific craniofacial reconstructions where custom geometry commands premium pricing.
The US FDA enforces rigorous premarket approval pathways for silicone-based devices under 21 CFR 878, while the EU Medical Device Regulation mandates notified body involvement for all implantable silicone products; China's NMPA implements national standards GB/T 16886 for biocompatibility testing that governs market access. These frameworks elevate barriers for uncertified suppliers while rewarding manufacturers with established regulatory dossiers. Stakeholders must monitor evolving biocompatibility testing protocols and reimbursement policy shifts to align portfolio development with compliance requirements.
Market Dynamics
The US FDA's updated silicone device guidance under 21 CFR 878 is compressing product development timelines while elevating biocompatibility testing burdens, forcing manufacturers to consolidate quality systems across aesthetic and reconstructive pathways.
Growth Catalysts
- Post-mastectomy reconstruction reimbursement:Established insurance pathways in the United States and Brazil drive hospital procurement of silicone breast implants at scale.
- Platinum-catalyzed addition cure chemistry:Advances in cross-linking density control enable Shore A hardness tuning between 20 and 70, expanding tissue-mimicking applications.
- Diabetes-related erectile dysfunction referrals:Rising urology clinic volumes in South Korea and Germany accelerate penile implant adoption among aging male populations.
Market Restraints
- Siloxane monomer supply concentration:Dow Inc and Momentive Performance Materials control upstream polydimethylsiloxane feedstock, creating input cost volatility for compounders.
- EU MDR notified body bottleneck:Extended certification timelines for implantable silicone products delay European market entry by 12-18 months relative to historical CE marking.
- Saline implant substitution:Non-silicone alternatives retain share in cost-sensitive cosmetic procedures where reimbursement is absent.
Strategic Opportunities
- Patient-specific craniofacial reconstructions:3D printing of custom silicone geometries commands premium pricing in maxillofacial surgery centers.
- China's NMPA GB/T 16886 harmonization:Biocompatibility testing alignment with ISO standards reduces duplicate study costs for multinational manufacturers.
- Telemedicine-enabled pre-surgical consultation:Remote patient assessment expands access to reconstructive surgery departments in secondary Brazilian cities.
Industry Challenges
- ISO 13485-certified polymer compounding talent:Medical-grade silicone formulation expertise concentrates in Germany and the United States, constraining facility expansion.
- Premarket approval dossier complexity:FDA 21 CFR 878 PMA submissions require 5-7 year clinical follow-up, freezing R&D capital in regulatory limbo.
- Legacy injection molding asset utilization:Standardized-shape production lines face underutilization as customization demand rises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silastic Implant Market |
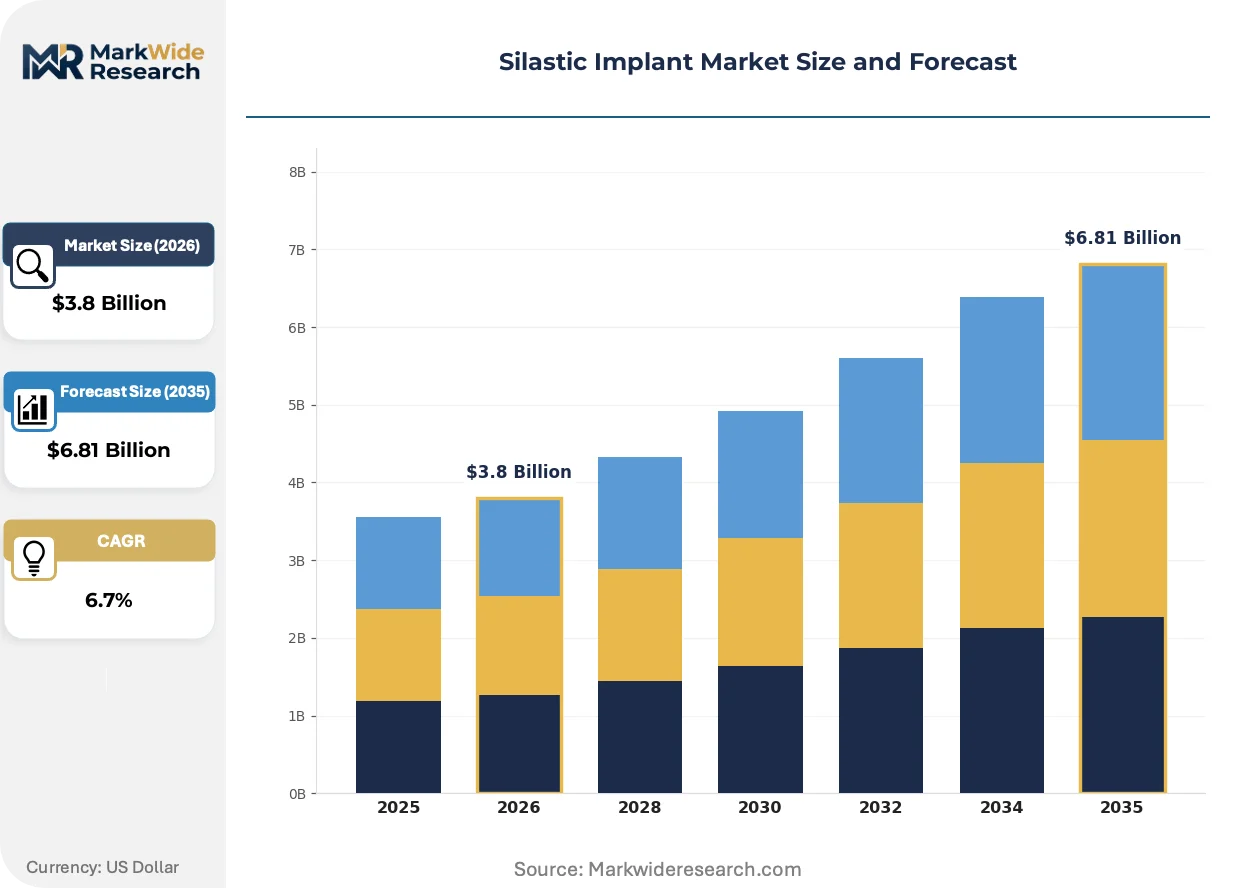
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breast Implants, Facial Implants, Testicular Implants, Penile Implants Implant Shape: Round, Teardrop, Custom, Textured Manufacturing Type: Injection Molding, Extrusion, Compression Molding, 3D Printing End User: Hospitals, Surgical Clinics, Specialty Clinics, Outpatient Centers |
| Companies Covered | Dow Inc, Momentive Performance Materials, Wacker Chemie AG, Shin-Etsu Chemical Co Ltd, Avantor Inc, Henkel AG and Co KGaA, Elkem ASA, China National Bluestar Group Co Ltd, Guangdong Polysil Technology Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silastic Implant Market Evolving Landscape
Digital manufacturing workflows and surface modification chemistry are redefining how silicone implants match patient anatomy and tissue integration performance.
Digital light processing of patient-specific molds is rendering obsolete the manual sculpting of wax patterns in craniofacial reconstruction. Academic medical centers in South Korea and Germany now adopt this workflow for 80% of custom orbital and mandibular cases. The technology compresses surgical planning from weeks to days while eliminating artisan-dependent variability.
The EU Medical Device Regulation's enhanced post-market surveillance requirements are reshaping clinical evidence obligations for silicone implant manufacturers. Notified bodies now mandate annual safety update reports and implant registries for all Class III devices. Breast implant producers face the steepest compliance burden, with several withdrawing economy-tier portfolios to concentrate resources on premium lines.
Hospital procurement departments are consolidating vendor lists around suppliers with dual FDA-MDR approval, displacing single-territory manufacturers from preferred supplier status. Group purchasing organizations in the United States now require ISO 13485 certification plus active PMA supplements as minimum qualification thresholds. This concentration is most visible in academic medical center networks, where reconstructive surgery departments halved their active silicone implant vendors between 2020 and 2024.
Silastic Implant Market Segmentation
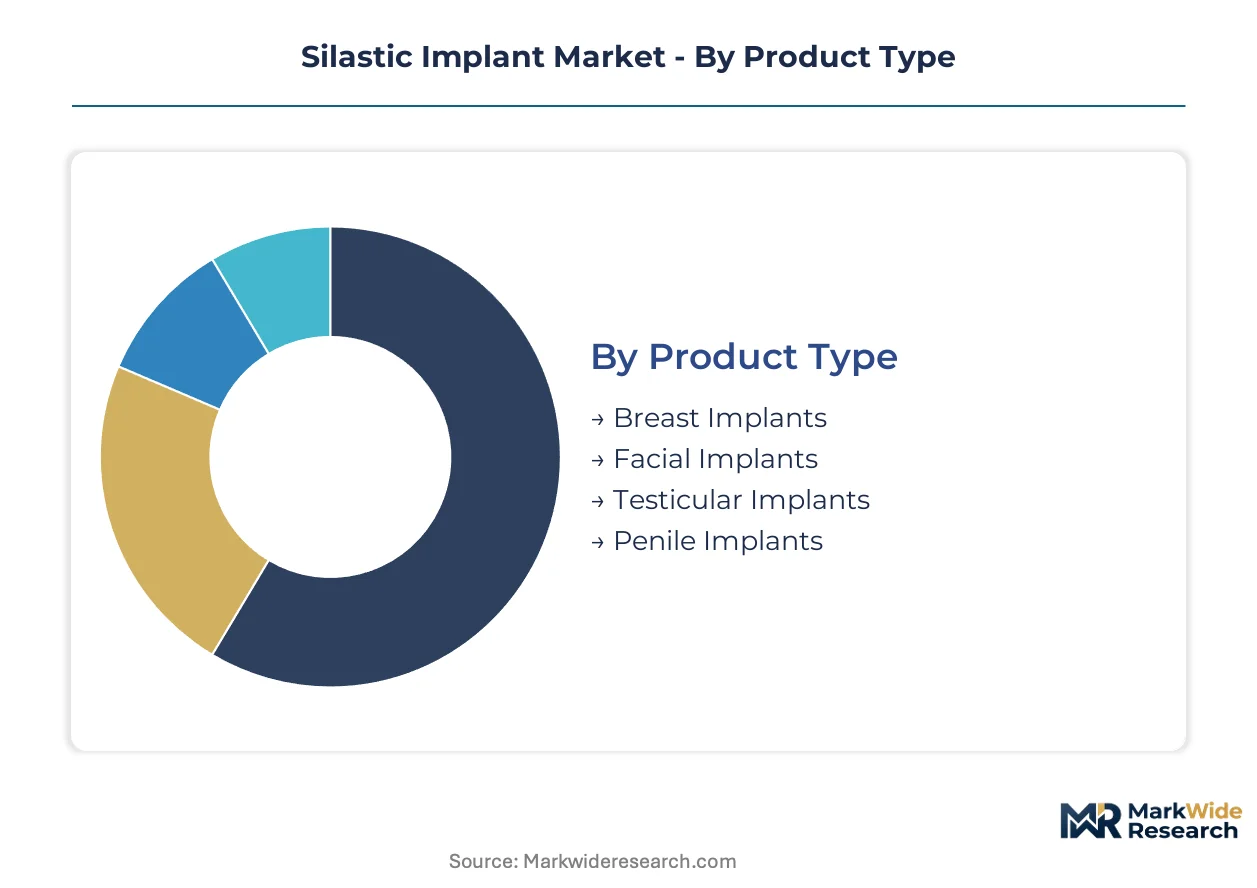
Silastic implant manufacturers configure service networks differently across product categories. Post-operative monitoring requirements for breast reconstruction create intensive follow-up obligations, while facial implant cases demand rapid revision logistics. These service intensity patterns directly shape how vendors structure regional distribution and technical support.
Product Type:
After-sales service intensity peaks with breast implants, where FDA-mandated post-market surveillance and long-term safety registries create sustained manufacturer-patient relationships spanning decades.
- Breast Implants:Cross-linked polydimethylsiloxane elastomer shells with saline or silicone gel fill, engineered for Shore A hardness between 20 and 40 to mimic mammary tissue compliance. Demand concentrates in United States hospital reconstructive surgery departments, driven by established insurance reimbursement for post-mastectomy reconstruction under federal mandate.
- Penile Implants:Cylindrical silicone elastomer reservoirs and inflatable cylinders, requiring platinum-catalyzed cure chemistry for flex-fatigue resistance exceeding 250,000 cycles. South Korean urology clinics and German academic medical centers report the steepest referral volume growth from diabetes-related erectile dysfunction.
- Facial Implants:Solid silicone elastomer malar, chin, and nasal dorsum constructs for aesthetic augmentation.
- Testicular Implants:Soft silicone gel-filled prostheses for cosmetic restoration following orchiectomy.
Breast implants hold the largest share; momentum sits with penile implants.
Implant Shape:
Cost tier differentiation separates premium custom geometries from standardized volume production, with textured surfaces commanding premium positioning amid safety scrutiny.
- Round:Symmetrical silicone elastomer shells with uniform projection profile, manufactured via rotational molding for cost-efficient high-volume output. Brazilian and South Korean cosmetic surgery clinics drive procurement for primary augmentation where rotation risk is acceptable.
- Teardrop:Anatomically contoured silicone constructs with tapered upper pole and fuller lower pole, requiring precise shell texturing to prevent malposition. United States academic medical centers prefer these for post-mastectomy reconstruction where natural slope restoration matters.
- Custom:Patient-specific geometries derived from CT imaging and milled silicone molds.
- Textured:Surface-modified shells with macroscopic pore architecture for tissue integration.
Round shapes dominate procedural volume; custom geometries gain share fastest in craniofacial applications.
Manufacturing Type:
Volume concentration in injection molding creates margin pressure, while 3D printing captures premium positioning through lot-size-one economics.
- Injection Molding:High-pressure silicone elastomer injection into precision steel molds for standardized breast and facial implant shells, achieving cycle times under 180 seconds per part. Dow Inc and Momentive Performance Materials supply medical-grade LSR compounds to dedicated cleanroom facilities in Germany and the United States.
- 3D Printing:Digital light processing of photocurable silicone resins for patient-specific craniofacial reconstruction molds, compressing surgical planning from weeks to days. South Korean maxillofacial surgery centers now deploy this workflow for 80% of custom orbital and mandibular cases.
- Extrusion:Continuous silicone profile production for penile implant tubing and reservoir components.
- Compression Molding:Heat-press vulcanization of pre-form silicone for low-volume specialty geometries.
Injection molding commands the largest installed base; 3D printing exhibits the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with hospital systems leveraging group purchasing organization scale against surgical clinic preference for vendor flexibility.
- Hospitals:Integrated health systems with reconstructive surgery departments, procuring silicone implants through consolidated vendor lists that demand dual FDA-MDR approval and active PMA supplements. United States academic medical center networks halved their active silicone implant vendors between 2020 and 2024.
- Surgical Clinics:Ambulatory facilities specializing in aesthetic procedures, prioritizing rapid inventory turnover and direct manufacturer relationships for revision case support.
- Specialty Clinics:Urology and gynecology-focused practices for penile and breast implant referral pathways.
- Outpatient Centers:Same-day surgical facilities for low-acuity implant procedures.
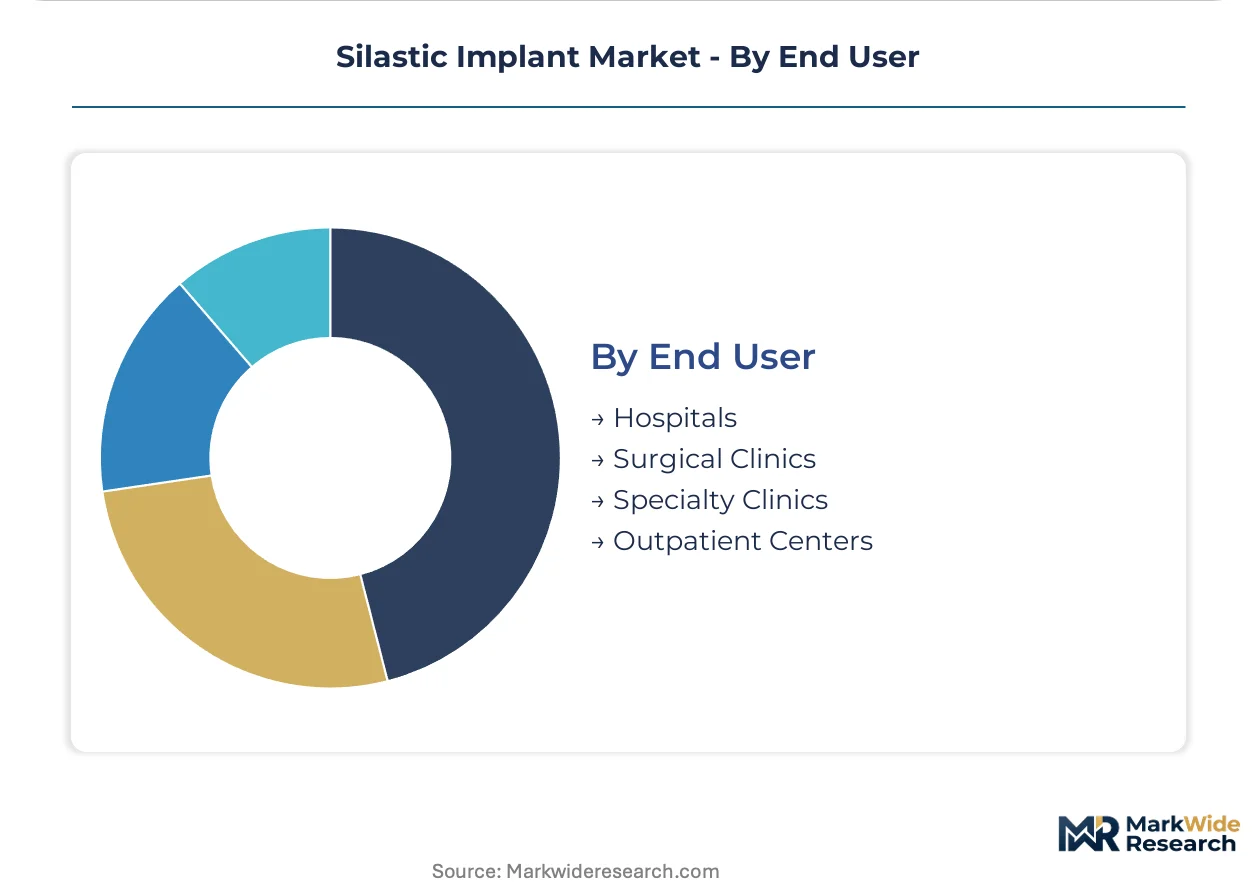
Hospitals represent the largest procurement volume; surgical clinics are expanding most quickly in Brazilian secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Brazil, and South Korea concentrate purchasing power for reconstructive surgery applications. Academic medical centers in these countries leverage group purchasing organization scale to consolidate vendor lists around dual FDA-MDR approved suppliers.
United States
Post-mastectomy reconstruction mandates under federal law drive hospital procurement of silicone breast implants at scale. FDA's 21 CFR 878 premarket approval pathway enforces rigorous clinical follow-up requirements spanning 5-7 years. Academic medical center networks in Boston and New York Metro halved their active silicone implant vendors between 2020 and 2024.
Brazil
Cosmetic surgery clinics in São Paulo and Rio de Janeiro generate concentrated demand for round-shaped breast implants. ANVISA regulates silicone-based medical devices under national health surveillance frameworks. Secondary cities in Minas Gerais and Paraná expand access through telemedicine-enabled pre-surgical consultation pathways.
South Korea
Urology clinics in Seoul Capital Area report accelerating referral volumes for diabetes-related erectile dysfunction cases requiring penile implants. MFDS enforces biocompatibility testing standards aligned with ISO 10993 series. Maxillofacial surgery centers in Busan-Ulsan deploy digital light processing for 80% of custom craniofacial reconstruction cases.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor European demand for patient-specific silicone geometries. EU Medical Device Regulation mandates notified body involvement and annual safety update reports for all Class III implantable devices. Wacker Chemie AG operates ISO 13485-certified manufacturing sites in the country.
China
Reconstructive surgery departments in Yangtze River Delta and Pearl River Delta cities drive adoption of domestically manufactured silicone implants. NMPA implements GB/T 16886 biocompatibility testing standards that govern market access. Guangdong-based compounders supply medical-grade silicone to regional device manufacturers.
Silastic Implant Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base concentrates around chemical conglomerates with captive siloxane monomer production and dedicated medical-grade compounding capabilities. Three archetypes dominate: upstream-integrated material suppliers, ISO 13485-certified device manufacturers, and regional compounders serving domestic hospital networks. Competitive moves center on backward integration into raw material purity control and consolidation of quality systems across aesthetic and reconstructive regulatory pathways.
Among upstream-integrated material suppliers, Dow Inc and Momentive Performance Materials occupy positions defined by captive polydimethylsiloxane feedstock control. Wacker Chemie AG represents the European anchor with certified manufacturing infrastructure. These three exemplify how raw material purity control and regulatory dossier depth determine preferred supplier status in consolidated hospital procurement channels.
| Leading Market Players |
|---|
| Dow Inc |
| Momentive Performance Materials |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co Ltd |
| Avantor Inc |
| Henkel AG and Co KGaA |
| Elkem ASA |
| China National Bluestar Group Co Ltd |
| Guangdong Polysil Technology Co Ltd |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Busan to Long Beach transmit siloxane monomer cost volatility directly into implant pricing tiers, amplifying the leverage of Dow Inc and Momentive Performance Materials while compressing margins for compounders serving cost-sensitive Brazilian cosmetic clinics.
Pricing Analysis
Cost-plus contracts with siloxane monomer indexation dominate procurement between upstream suppliers and medical-grade compounders. Three-tier pricing structure across premium, standard, and economy levels separates FDA-MDR dual-certified manufacturers from single-territory suppliers and uncertified regional players. Cost compression in economy-tier breast implants intensifies as Brazilian group purchasing organizations consolidate vendor lists. Hospital systems in the United States exhibit lowest price sensitivity due to established reimbursement pathways, while ambulatory surgical clinics in secondary Brazilian cities face acute margin pressure.
Supply Chain Analysis
Export-control restrictions on advanced silicone compounding equipment limit technology transfer to emerging manufacturers, reinforcing concentration. Siloxane monomer production centers on the United States, Germany, and Japan. Medical-grade polydimethylsiloxane feedstock, platinum catalyst systems, and precision molding equipment constitute critical input dependencies. Single-source vulnerability concentrates in platinum supply chains anchored in South Africa and Russia. Distribution runs through ISO 13485-certified cleanroom facilities in Germany and the United States before hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Silastic Implant Market functions as a service-attach opportunity where post-market surveillance registries and long-term safety monitoring generate recurring revenue streams expanding faster than hardware sales.
For Market Incumbents: Build regulatory dossier moats by deepening backward integration into siloxane monomer purification and unifying quality systems across aesthetic and reconstructive pathways. Saline implant substitution in cost-sensitive cosmetic segments threatens silicone volume. FDA 21 CFR 878 PMA supplement maintenance and EU MDR annual safety update report infrastructure constitute critical defensive investments. For New Entrants and Emerging Players: Build out patient-specific craniofacial reconstruction capabilities leveraging digital light processing workflows in South Korean and German maxillofacial surgery centers. Custom silicone geometries for orbital and mandibular cases represent the most penetrable white space. Direct technical partnerships with academic medical centers bypass consolidated group purchasing organization barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from chemical conglomerates seeking to divest non-core medical-grade silicone divisions amid portfolio rationalization pressures. Five-to-ten-year viability hinges on regulatory dossier depth rather than manufacturing scale alone. ISO 13485-certified compounding facilities with active FDA-MDR dual approvals signal acquisition quality. Watch for EU MDR notified body capacity expansion as inflection indicator for European market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Supplement Filing | Accelerates market access for next-generation breast implant geometries under 21 CFR 878. |
| EU MDR Notified Body Engagement | Secures CE marking pathway for Class III silicone implants amid certification bottlenecks. |
| Hospital System Partnership | Locks in preferred supplier status within consolidating academic medical center networks. |
| Software Companion Development | Enables remote patient monitoring for post-mastectomy reconstruction follow-up protocols. |
| Reimbursement Strategy | Expands insurance coverage for penile implants in diabetes-related erectile dysfunction pathways. |
Research Methodology
A standing panel of reconstructive surgeons, hospital procurement directors, biomedical engineers, and group purchasing organization contract managers provided ongoing calibration across the study period. Primary interviews with silicone implant manufacturers and regulatory affairs specialists combined with secondary validation from FDA 510(k) and PMA filings, EU MDR notified body documentation, and hospital procurement database extracts. Bottom-up demand modeling and top-down supply-side triangulation anchored volume and value estimates.
Scenario bracketing around regulatory approval timelines and reimbursement policy shifts structured the analytical framework across the projection horizon. Segmentation dimensions included product type, manufacturing technology, end-user channel, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to procedure volume forecasts and average selling price trajectories. Siloxane monomer price indices and notified body certification capacity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese compounders or accelerated EU MDR notified body recruitment would shift outcomes. Material shifts in FDA biocompatibility testing protocols or ANVISA regulatory harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Morcellators Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Artificial Implants Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Artificial Respirator Market
Medical Devices
Intravaginal Device Market
Medical Devices
Global Infusion Pumps and Accessories Market