
 Industrial X-Ray Machine Market | 2026-2036
Industrial X-Ray Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial X-Ray Machine Market Insights
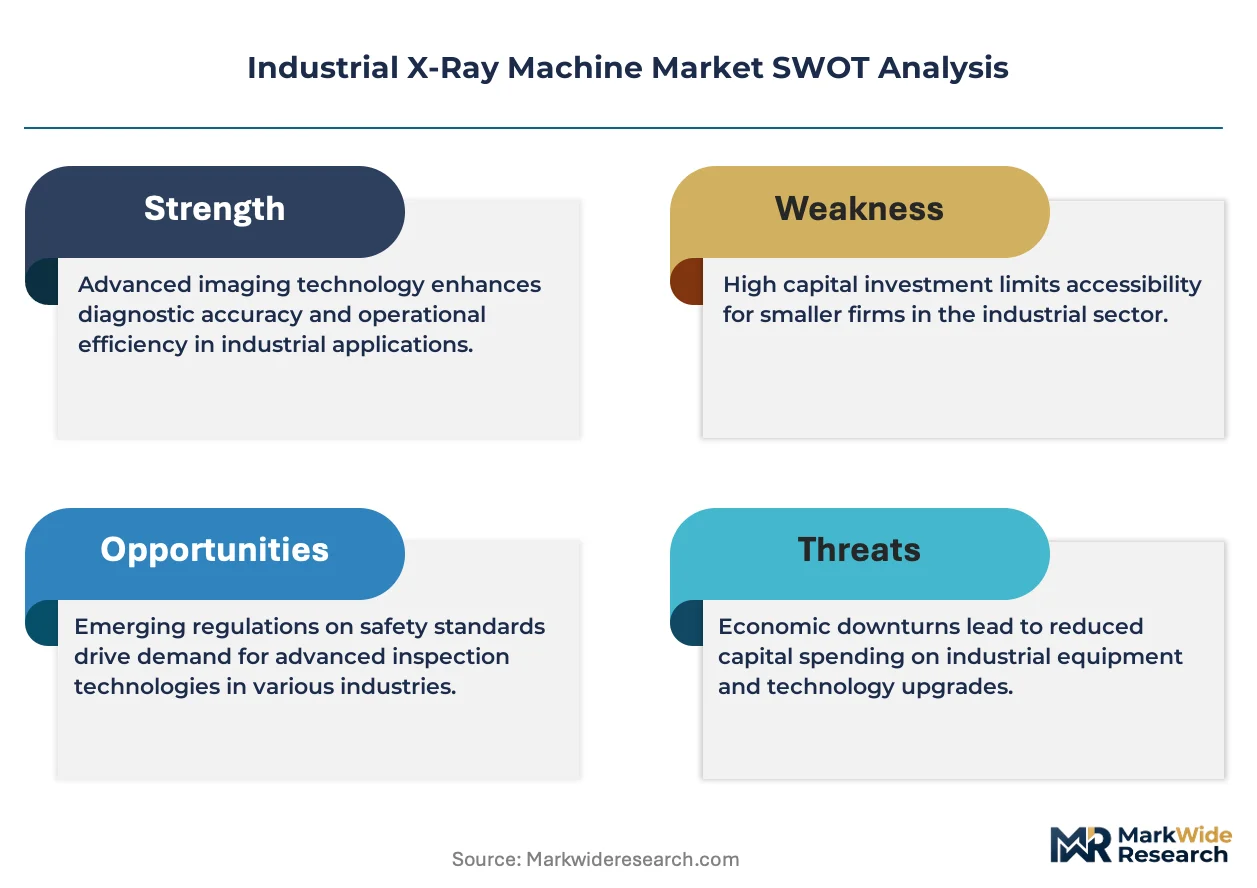
Germany's precision engineering base is fragmenting as industrial X-ray demand spreads from traditional automotive hubs into additive manufacturing and battery inspection. GE HealthCare Technologies Inc. leverages its medical imaging heritage to cross-sell into industrial computed tomography. Varex Imaging sustains a dominant position in X-ray tube supply for original equipment manufacturers across North America and Asia. ZEISS Group differentiates through metrology-integrated systems that combine optical and radiographic inspection in single platforms.
Industrial X-ray machines generate electromagnetic radiation in the keV to MeV range to penetrate metals, composites, and ceramics without destroying test specimens. Modern systems deploy flat-panel detectors with micrometer-level resolution to identify subsurface cracks, porosity, and inclusions in castings, welds, and printed components. Digital X-ray and computed radiography segments lead equipment revenue as film-based methods retreat to legacy defense and archival applications. Non-destructive testing and weld inspection applications capture the deepest inspection volumes, particularly where pipeline integrity and pressure vessel certification require documented radiographic records.
The US Nuclear Regulatory Commission governs radioactive source licensing for cobalt-60 systems, while the FDA regulates X-ray tube emissions under 21 CFR 1020.32 performance standards. In Europe, the EU Machinery Directive and ATEX directives mandate safety interlocks and explosion protection for oil and gas deployment environments. Germany's KBA enforces component traceability rules that drive automotive supplier investment in radiographic documentation systems. Stakeholders must monitor how evolving battery safety standards and hydrogen infrastructure codes expand inspection scope beyond traditional metal-heavy industries.
Market Dynamics
Digital radiography systems are compressing inspection cycle times from hours to minutes across automotive and aerospace supply chains, forcing equipment suppliers to reconfigure service models around throughput guarantees rather than hardware margins alone.
Growth Catalysts
- AS9100 Quality Mandates:Aerospace OEMs in North America and Europe now require documented radiographic traceability for flight-critical components, expanding non-destructive testing programs at tier-one suppliers.
- Automotive Battery Inspection:Solid-state and lithium-ion cell manufacturers deploy computed tomography to detect electrode delamination and separator defects before assembly into packs.
- Additive Manufacturing Qualification:Powder-bed fusion users in Germany rely on industrial X-ray to certify internal channel integrity in topology-optimized brackets and heat exchangers.
Market Restraints
- Flat-Panel Detector Supply Concentration:A single Japanese supplier controls critical amorphous silicon deposition capacity, creating 16-20 week lead times during demand surges.
- Cobalt-60 Licensing Friction:The US Nuclear Regulatory Commission's source security protocols add 8-14 months to gamma radiography system deployment schedules.
- High-Voltage Tube Replacement Cycles:Tungsten filament degradation in 450 kV systems requires $40,000-$70,000 cathode replacements every 3,000-5,000 operating hours.
Strategic Opportunities
- Hydrogen Infrastructure Inspection:ASME BPVC Section V code revisions for high-pressure hydrogen storage vessels create new radiographic documentation requirements at US and German certification bodies.
- In-Line CT Integration:Foundries combine automated handling robotics with sub-minute computed tomography cycles, enabling 100% inspection of aluminum transmission housings.
- India Manufacturing Incentives:PLI scheme allocations for automotive and electronics clusters drive first-time NDT equipment purchases at domestic casting and welding operations.
Industry Challenges
- Radiation Safety Officer Certification Bottlenecks:State-level licensing boards in the US and Germany cannot train qualified personnel fast enough to match equipment deployment rates.
- Legacy Film Archive Migration:Defense contractors and nuclear operators face multi-year digitization projects to convert decades of radiographic film records to DICONDE-compliant formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial X-Ray Machine Market |
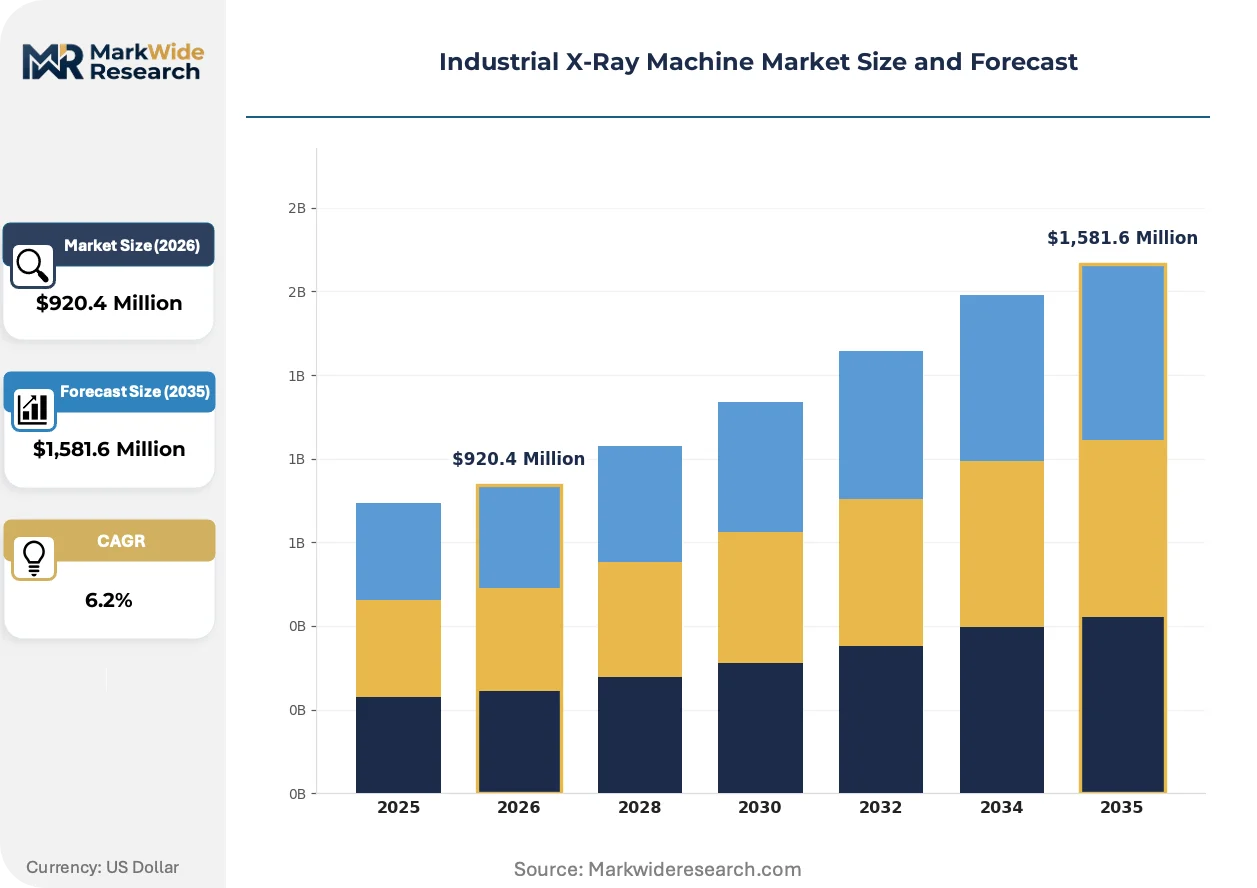
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $1,581.6 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital X-Ray, Computed Radiography, Film-Based X-Ray, Portable X-Ray End User: Manufacturing, Aerospace, Automotive, Oil & Gas Application: Non-Destructive Testing, Quality Control, Weld Inspection, Material Analysis Technology: Cobalt-60, X-Ray Tubes, Linear Accelerators, Photon Detection |
| Companies Covered | GE HealthCare Technologies Inc., Varex Imaging, FUJIFILM Corporation, ZEISS Group, Teledyne Digital Imaging Inc., Comet Group, Hamamatsu Photonics K.K., Rigaku Corporation, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial X-Ray Machine Market Trends and Innovations
Equipment architectures are converging around software-defined inspection workflows that separate hardware acquisition from algorithmic analysis, enabling subscription-based revenue models previously foreign to capital equipment markets.
Computed tomography reconstruction algorithms are migrating from filtered back-projection to deep learning-enhanced iterative methods, cutting scan times by 60-80% while maintaining ASTM E1695 measurement uncertainty standards. Medical imaging specialists at German university hospitals license neural network architectures to industrial OEMs, accelerating adoption at automotive powertrain foundries. This migration is compressing the performance gap between laboratory-grade metrology systems and shop-floor production inspection cells.
The EU Machinery Directive's 2023 amendment mandating cybersecurity-by-design for networked industrial equipment forces X-ray system builders to embed hardware security modules and encrypted firmware update channels. German notified bodies now require penetration testing documentation before CE marking authorization. North American exporters to European automotive supply chains must revalidate control software architectures to maintain market access.
Equipment-as-a-service contracts now bundle hardware, calibration, software updates, and radiographer training into per-inspection pricing at North American pipeline integrity firms. This unbundles capital expenditure into operational budgets, accelerating replacement of aging film-based systems at mid-size non-destructive testing contractors. The model is most advanced in Texas and Alberta oilfield service markets, where inspection volume volatility makes fixed asset ownership economically unattractive.
Industrial X-Ray Machine Market Segmentation
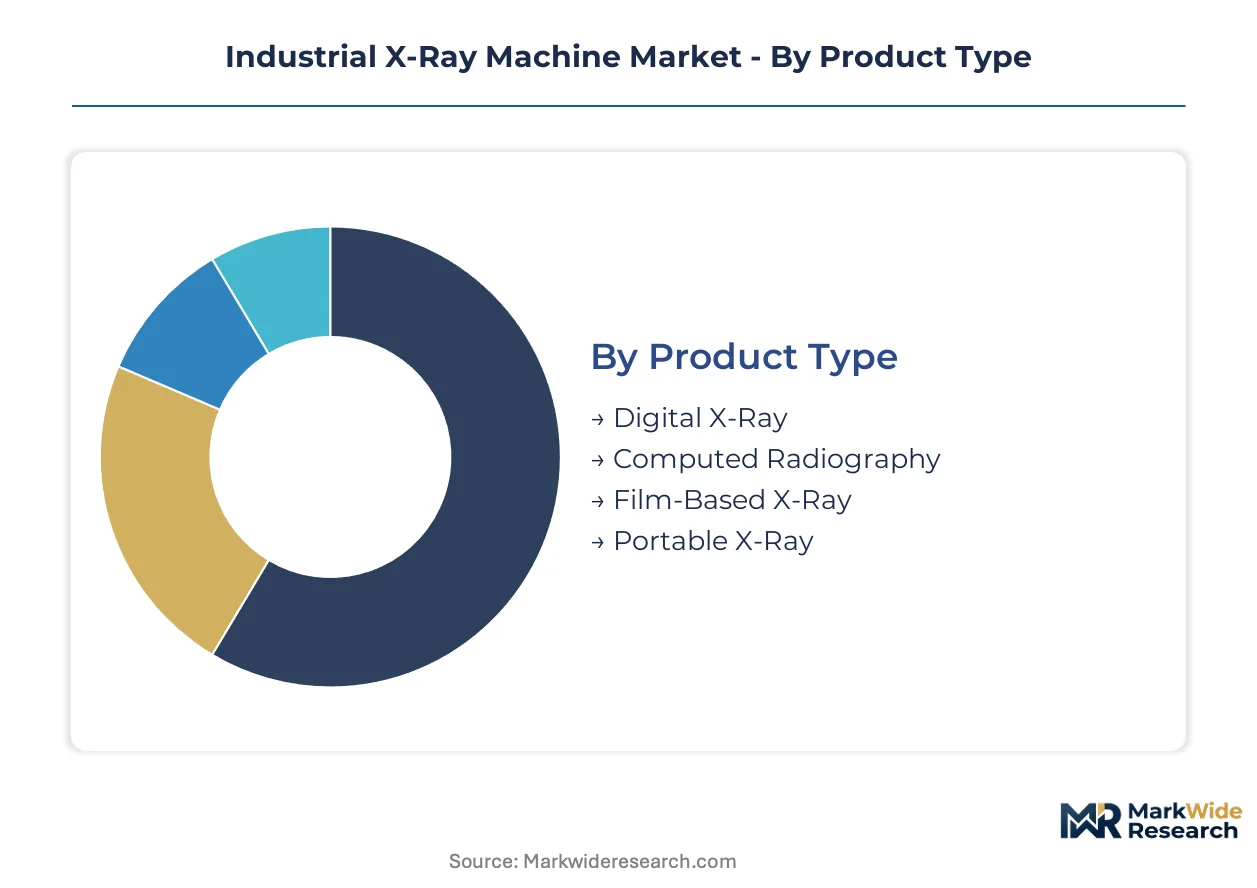
Equipment configuration in industrial radiography diverges sharply by inspection environment, with factory-floor throughput demands driving hardware selection differently than laboratory precision requirements. Segmentation reveals how technology maturity, end-use certification standards, and radiation source economics partition the vendor landscape into distinct competitive arenas.
Product Type:
Mature digital architectures now dominate capital deployment, while legacy film systems persist in regulated archival contexts.
- Digital X-Ray:Flat-panel detectors capture radiographic images in real time, eliminating chemical processing and enabling automated defect recognition algorithms. Automotive foundries in Germany and transmission suppliers in Michigan deploy these systems for 100% inline inspection of aluminum castings under AS9100 traceability mandates.
- Computed Radiography:Photostimulable phosphor plates bridge analog exposure and digital workflow, offering intermediate resolution at lower capital cost than direct digital. Pipeline integrity contractors across Texas and Alberta favor this technology for field weld documentation where power and portability constraints limit full digital deployment.
- Film-Based X-Ray:Silver-halide emulsion archives remain mandatory for nuclear pressure vessel certification in defense and energy sectors.
- Portable X-Ray:Battery-powered directional tubes enable radiographic access to in-service infrastructure without crane-mounted equipment.
Digital X-Ray handles the majority of throughput; Computed Radiography is the fastest mover on share.
End User:
Customer concentration patterns split between specification-driven OEMs and price-sensitive service contractors.
- Manufacturing:Foundries, forges, and metal fabricators operate the densest installed base, with tier-one automotive suppliers in Germany and Japan maintaining multi-shift inspection cells for powertrain components. Quality mandates from OEMs force radiographic documentation for every critical casting batch.
- Aerospace:Airframe manufacturers and engine OEMs impose the most stringent acceptance criteria, with titanium and nickel superalloy components requiring sub-50-micron resolution. North American and European suppliers face AS9100 audit requirements that mandate traceable radiographic records for flight-critical parts.
- Automotive:Battery cell manufacturers and EV powertrain suppliers represent emerging demand concentration for electrode and separator inspection.
- Oil & Gas:Pipeline operators and pressure vessel fabricators drive seasonal demand spikes tied to construction windows and regulatory recertification cycles.
Manufacturing absorbs the highest equipment volume; Aerospace commands the steepest expansion trajectory.
Application:
Functional purpose determines equipment specification more than hardware category alone.
- Non-Destructive Testing:Flaw detection in finished components without structural damage remains the core value proposition, with ultrasonic-radiographic hybrid systems gaining traction for thick-section steel. German automotive suppliers deploy NDT protocols for every safety-critical brake caliper and steering knuckle.
- Quality Control:Statistical process control applications integrate radiographic data directly into manufacturing execution systems, enabling real-time cavity rejection in die-cast aluminum.
- Weld Inspection:Radiographic documentation of pipeline girth welds and pressure vessel seams follows ASME BPVC Section V codes.
- Material Analysis:Computed tomography quantifies porosity distribution and fiber orientation in composite aerospace structures.
Non-Destructive Testing anchors equipment utilization; Quality Control is gaining share fastest.
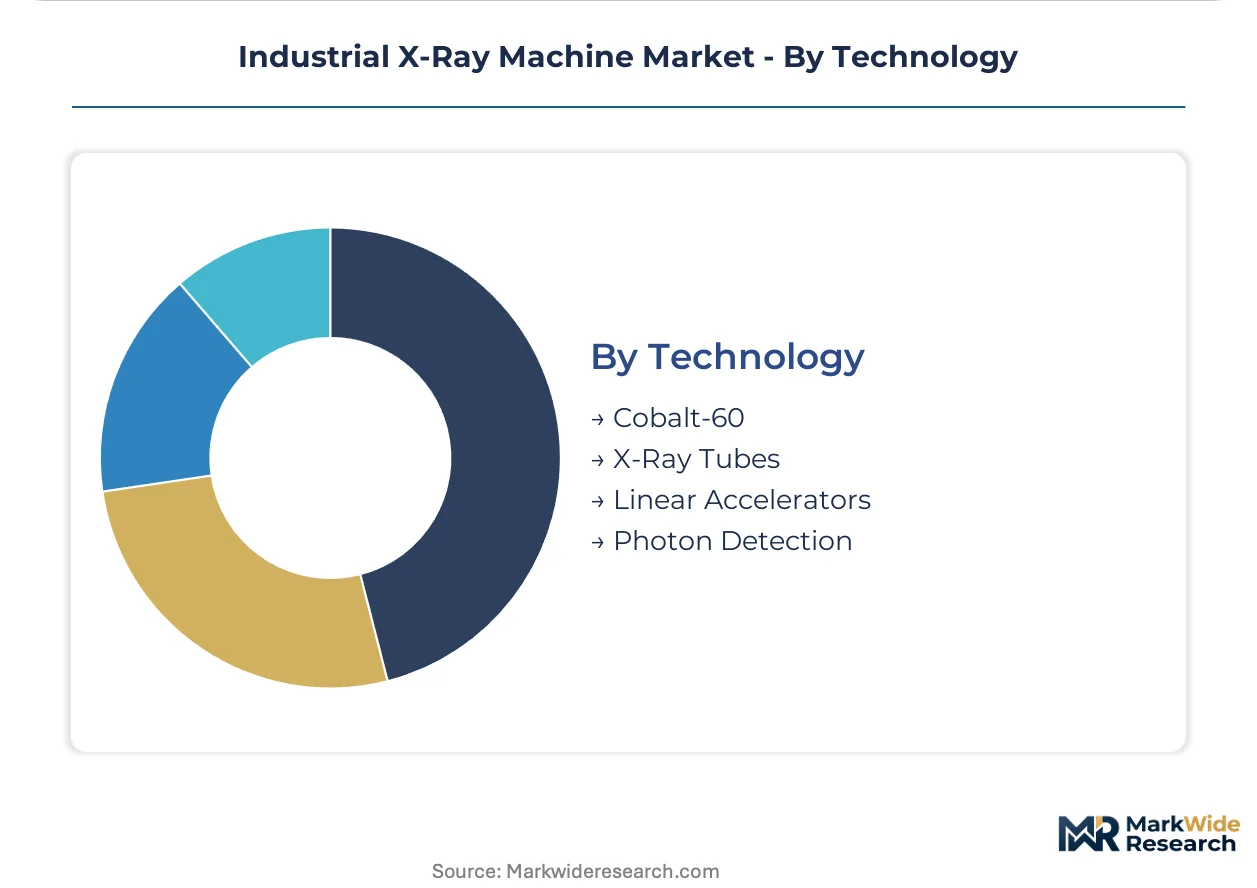
Technology:
Radiation source selection trades penetration depth against regulatory burden and operational flexibility.
- X-Ray Tubes:Electron-impact sources dominate industrial deployment, with tungsten anode tubes delivering 450 kV maximum energy for steel penetration up to 100 millimeters. Replacement filament economics and modular tube architectures dominate total cost of ownership calculations for North American foundries.
- Cobalt-60:Gamma radiography sources achieve superior penetration for thick-walled pressure vessels and concrete structures, but NRC licensing protocols in the US and comparable security frameworks in Germany impose 8-14 month deployment delays.
- Linear Accelerators:Electron linacs generate MeV-range X-rays for cargo screening and thick-section industrial inspection.
- Photon Detection:Scintillator and semiconductor detector architectures determine image resolution and dynamic range independently of source technology.
X-Ray Tubes carry the dominant installed base; Cobalt-60 is expanding most quickly in energy infrastructure applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
X-ray tube and detector manufacturing clusters in Germany, Japan, and the United States supply the majority of industrial radiography hardware. Equipment deployment patterns follow automotive, aerospace, and energy infrastructure investment cycles across these manufacturing centers.
United States
Aerospace OEMs in Washington State and Texas expand non-destructive testing cells to satisfy AS9100 documentation mandates for flight-critical titanium castings. The Nuclear Regulatory Commission enforces cobalt-60 source security protocols that extend gamma radiography system deployment timelines. Pipeline integrity contractors in Houston and Calgary service seasonal construction windows with portable digital radiography fleets.
Germany
Automotive powertrain foundries in Bavaria and Baden-Württemberg operate multi-shift inspection networks for aluminum transmission housings and brake calipers. The Kraftfahrt-Bundesamt enforces component traceability rules that mandate radiographic documentation across tier-one supplier networks. Additive manufacturing qualification labs in Munich deploy computed tomography for topology-optimized heat exchanger certification.
Japan
Flat-panel detector manufacturing concentrates around amorphous silicon deposition facilities serving global OEM demand. METI industrial technology roadmaps prioritize non-destructive testing automation for export-oriented machinery sectors. Automotive suppliers in Nagoya and Osaka integrate inline radiography for electric vehicle battery cell inspection.
China
Foundry modernization programs in the Yangtze River Delta accelerate digital radiography adoption for aluminum die-cast exports. GB standards for pressure vessel inspection align with ASME BPVC Section V protocols to facilitate international project participation. Welding contractors in Shenzhen and Guangzhou deploy portable X-ray systems for infrastructure and shipbuilding quality documentation.
India
Production-linked incentive scheme allocations for automotive and electronics clusters drive first-time NDT equipment purchases at domestic casting operations. The Bureau of Indian Standards develops radiographic testing protocols for pressure equipment certification. Manufacturing investments in Maharashtra and Tamil Nadu establish inspection capabilities for export-oriented component suppliers.
Industrial X-Ray Machine Market Competitive Landscape
Medical imaging heritage and industrial metrology specializations split the market between divergent capability foundations. Consolidation pressures concentrate around detector supply and software-defined inspection workflows. Diversified conglomerates with imaging divisions compete against pure-play radiography specialists and precision measurement houses. Strategic moves center on cross-selling medical technology into industrial applications and bundling hardware with subscription-based service contracts.
Among diversified technology conglomerates, GE HealthCare Technologies Inc. and FUJIFILM Corporation occupy positions that leverage medical imaging infrastructure for industrial computed tomography expansion. Varex Imaging exemplifies the component-specialist archetype through its concentration on X-ray tube supply for original equipment manufacturers. ZEISS Group anchors the metrology-integrated tier, combining optical and radiographic inspection architectures within single-platform systems. These three archetypes—conglomerate imaging divisions, component specialists, and precision measurement integrators—structure competitive positioning across automotive, aerospace, and energy end-use segments.
| Leading Market Players |
|---|
| GE HealthCare Technologies Inc. |
| Varex Imaging |
| FUJIFILM Corporation |
| ZEISS Group |
| Teledyne Digital Imaging Inc. |
| Comet Group |
| Hamamatsu Photonics K.K. |
| Rigaku Corporation |
| Shimadzu Corporation |
| Others |
Pricing and Supply Chain Analysis
Flat-panel detector supply concentration in Japan determines both pricing tier spreads and supply chain shape, forcing OEMs to absorb extended lead times or pay premiums for expedited delivery while reconfiguring inventory strategies around single-source amorphous silicon deposition capacity.
Pricing Analysis
AS9100 certification requirements dictate the pricing tier structure across aerospace supplier networks, separating metrology-integrated platforms from standard digital radiography units. Three-tier pricing structure across premium, standard, and economy levels reflects detector resolution grades, software analytics bundling, and aftermarket service commitments. Cost compression in the standard tier is intensifying because foundries in Germany and Michigan are consolidating procurement volumes to extract volume discounts. Tier-one automotive suppliers exhibit the highest price sensitivity due to OEM cost-down mandates, while battery cell manufacturers prioritize resolution specifications over upfront capital outlay.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for tube and detector assemblies, prompting OEMs to qualify alternative manufacturing sites in Mexico and Vietnam. Amorphous silicon deposition for flat-panel detectors, tungsten filament stock for high-voltage tubes, and precision scintillator crystals draw from concentrated Japanese and German supplier bases. Single-source vulnerability in detector manufacturing creates procurement bottlenecks during demand surges. Distribution runs through authorized service integrators who bundle installation, calibration, and training into turnkey contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial X-ray incumbents face substitution pressure from ultrasonic phased-array systems that achieve comparable defect detection in thick-section steel without radiation safety overhead, requiring defensive positioning around software-defined inspection workflows.
For Market Incumbents: Entrench through backward integration into detector module assembly and captive supply of X-ray tube subassemblies to insulate margin structures from Japanese supplier pricing power. Accelerate certification investment for hydrogen infrastructure inspection protocols before ASME BPVC Section V revisions finalize, locking in specification influence at German and US certification bodies. For New Entrants and Emerging Players: Build out service-centric business models targeting mid-size non-destructive testing contractors in Texas and Alberta oilfield markets where inspection volume volatility makes equipment-as-a-service contracts attractive. Focus initial penetration on computed radiography segments where capital barriers remain lower than full digital platforms, leveraging photostimulable phosphor plate technology as a bridge offering. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component specialists with detector supply relationships and software-defined inspection platforms over pure hardware manufacturers. Long-term viability hinges on recurring revenue attachment rates from analytics subscriptions and service contracts. Watch for inflection signals in battery cell manufacturer CT adoption curves, as electrode inspection volume thresholds will determine which platform architectures achieve production-scale validation.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Supply Agreement | Long-term amorphous silicon contracts with Japanese suppliers secure capacity allocation during demand surges. |
| Software-Defined Inspection Platform | Subscription analytics revenue from German automotive foundries reduces hardware margin dependence. |
| Hydrogen Infrastructure Certification | Early ASME BPVC Section V alignment positions systems for German KBA and US pipeline safety mandates. |
| Equipment-as-a-Service Launch | Per-inspection pricing converts Texas oilfield contractor capital expenditure into recurring operational budgets. |
| Metrology Integration Partnership | ZEISS-style optical-radiographic platforms capture aerospace OEM specification-setting authority. |
Research Methodology
Operator-level perspectives from maintenance directors at German automotive foundries, NDT service contractors in Texas and Alberta, OEM procurement teams at aerospace tier-one suppliers, and aftermarket service heads at detector manufacturers anchored the qualitative base. Primary interview findings triangulated against secondary sources including FDA 21 CFR 1020.32 filings, EU Machinery Directive amendment documentation, NRC licensing records, and customs trade data for X-ray tube and detector imports. Bottom-up equipment deployment estimates across end-use segments converged with top-down market sizing from supplier revenue disclosures.
Scenario-bracketing around cobalt-60 licensing timeline variations and flat-panel detector supply disruptions framed the projection range across the analysis window. Segmentation dimensions modeled include equipment configuration, radiation source technology, end-use industry concentration, application functional purpose, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, technology transition velocity in film-to-digital migration, and inspection volume growth at battery cell manufacturing facilities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese foundry equipment suppliers or medical imaging conglomerates cross-selling into industrial CT would shift outcomes beyond modeled boundaries. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market