
 Oral Screening Systems Market | 2026-2036
Oral Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Screening Systems Market Analytics
Multi-source procurement for optical sensors and CMOS detectors is rebalancing toward vertically integrated supply chains among tier-one manufacturers. Dentsply Sirona leverages its imaging software ecosystem to bundle screening analytics with chairside hardware. DenMat Holdings LLC anchors the North American fluorescence device segment through specialized distributor relationships. Apteryx Imaging competes on cloud-native architecture that reduces on-premise IT overhead for smaller practices.
Oral screening systems comprise diagnostic platforms that detect mucosal abnormalities through spectral analysis of tissue autofluorescence, typically operating at excitation wavelengths between 375-440 nanometers and capturing emission spectra above 500 nanometers for lesion discrimination. These systems serve commercial purpose by enabling non-invasive chairside identification of dysplastic tissue prior to histopathological confirmation. Digital imaging platforms currently lead installed base metrics across developed markets, while artificial intelligence integration represents the fastest-expanding technology dimension as machine learning classifiers improve sensitivity thresholds for cancer detection applications. Screening kits occupy the most price-sensitive tier, with margin pools concentrating in software solutions that command recurring subscription structures.
FDA software-as-a-medical-device guidance and the EU Medical Device Regulation shape product registration pathways, clinical evidence requirements, and post-market surveillance obligations for fluorescence and AI-enabled platforms. The EPA regulates disinfectant compatibility claims for reusable handheld device components, influencing material selection and coating durability specifications. Stakeholders must monitor evolving reimbursement coding for adjunctive screening procedures to determine whether device economics shift toward capital purchase or per-procedure leasing models.
Market Dynamics
AI-assisted fluorescence screening platforms are compressing the diagnostic pathway from chairside detection to histopathological referral, forcing hardware manufacturers to bundle software subscriptions into capital equipment contracts or risk margin erosion from standalone device commoditization.
Growth Catalysts
- FDA software-as-a-medical-device guidance:The framework accelerates 510(k) clearance timelines for machine learning classifiers embedded in oral screening platforms, reducing regulatory friction for developers.
- CMOS detector cost curves:Vertically integrated sensor fabrication in East Asian manufacturing clusters is lowering bill-of-materials thresholds for handheld fluorescence devices.
- German oral cancer screening protocols:Tightening reimbursement criteria for adjunctive screening procedures is mandating fluorescence-based documentation in dental clinic workflows.
Market Restraints
- Optical sensor supply concentration:Single-source dependency on Japanese precision optics manufacturers creates vulnerability to export licensing delays.
- EU Medical Device Regulation clinical evidence requirements:Post-market surveillance obligations for Class IIa fluorescence devices extend certification timelines and inflate regulatory compliance costs.
- White-light visual examination substitution:Conventional oral inspection without fluorescence augmentation retains dominance in price-sensitive public health screening programs.
Strategic Opportunities
- India tier-two dental clinic expansion:Underpenetrated secondary cities present white space for cloud-native screening platforms that bypass on-premise IT infrastructure requirements.
- Artificial intelligence and teledentistry convergence:Remote lesion triage workflows enable specialist network access for rural patient populations without capital-intensive hub-and-spoke hardware deployment.
- Japan METI medical device export promotion:Government incentives for PMDA-certified fluorescence systems create regulatory tailwinds for manufacturers targeting Southeast Asian markets.
Industry Challenges
- Machine learning validation specialist scarcity:Shortage of clinical data scientists with oral pathology domain expertise delays algorithm training dataset curation for regulatory submission.
- Legacy practice management system integration:Chairside fluorescence devices require custom HL7 FHIR interface development to synchronize with entrenched electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Screening Systems Market |
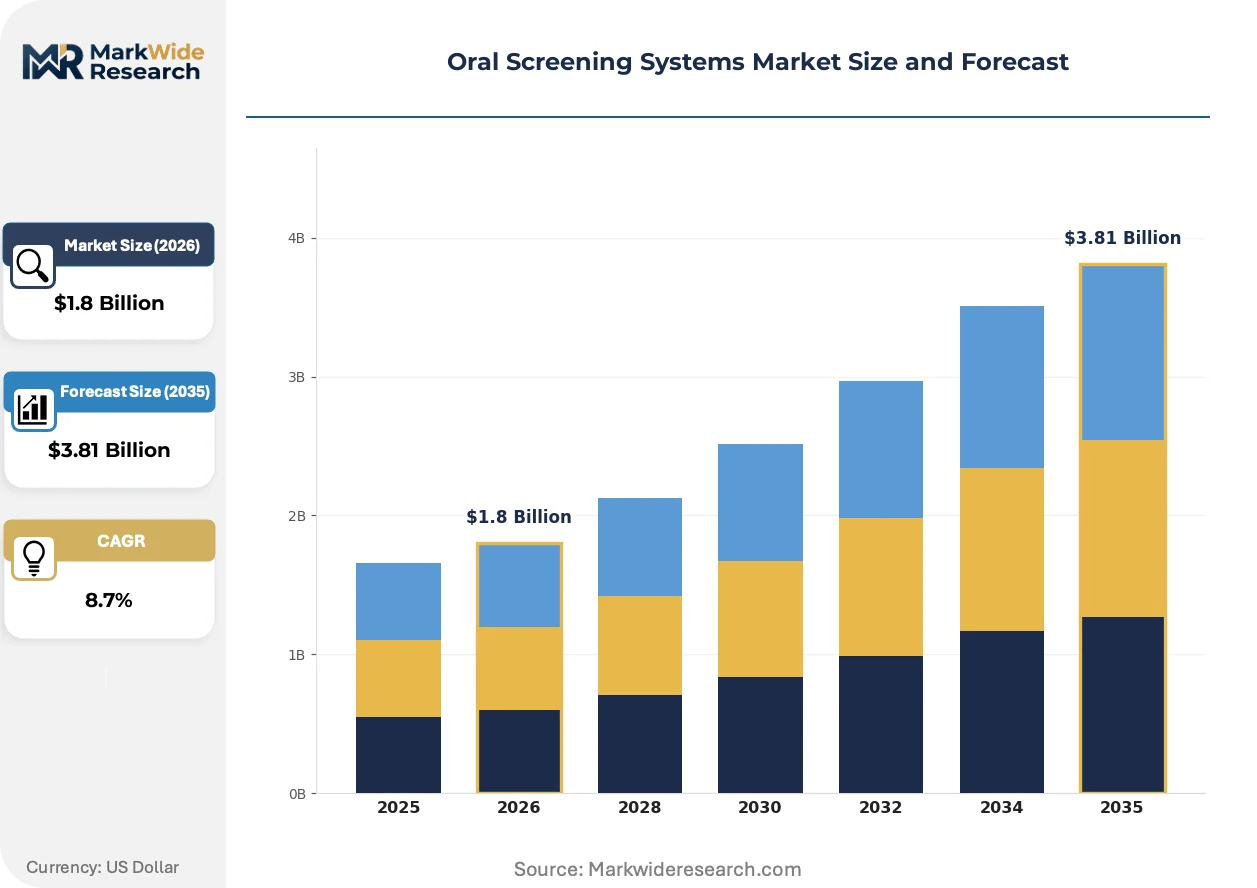
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Digital Imaging, Software Solutions, Screening Kits End User: Dental Clinics, Hospitals, Research Institutions, Home Care Technology: Fluorescence, Spectroscopy, Photodynamic Therapy, Artificial Intelligence Application: Cancer Detection, Oral Hygiene, Diagnostic Screening, Preventive Care |
| Companies Covered | Addent Inc, Dentilight Inc, PeriRX, DentalEZ, LED Denta, Zila, DenMat Holdings LLC, Apteryx Imaging, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Screening Systems Market Evolving Landscape
Fluorescence excitation source miniaturization and edge computing deployment are collapsing the form factor and latency constraints that previously tethered screening systems to dedicated imaging suites.
Multi-spectral LED arrays operating across 375-440 nanometer excitation bands are expanding into portable diagnostic wands that dental hygienists deploy during routine prophylaxis appointments. Solo and small-group practices in the United States are adopting these devices at accelerating clip rates to differentiate against corporate dental chains. The technology is expanding into subscription-based per-procedure leasing models that convert capital expenditure into predictable operating costs.
EU Medical Device Regulation post-market surveillance mandates now require fluorescence device manufacturers to submit periodic safety update reports and real-world performance data to notified bodies. This obligation forces software-enabled platforms to embed automated adverse event logging and cloud-based usage analytics. German and French dental distributors are responding by consolidating vendor relationships to reduce compliance documentation fragmentation across their product portfolios.
Hospital procurement departments are consolidating oral screening device purchasing through group purchasing organizations that negotiate enterprise-wide pricing and service level agreements. Independent dental clinics face exclusion from these contracts and are migrating toward manufacturer-direct digital commerce channels with transparent configuration tools. This channel rotation is most visible in the United Kingdom and Australia where dental corporate groups control substantial chairside equipment procurement volume.
Oral Screening Systems Market Segmentation
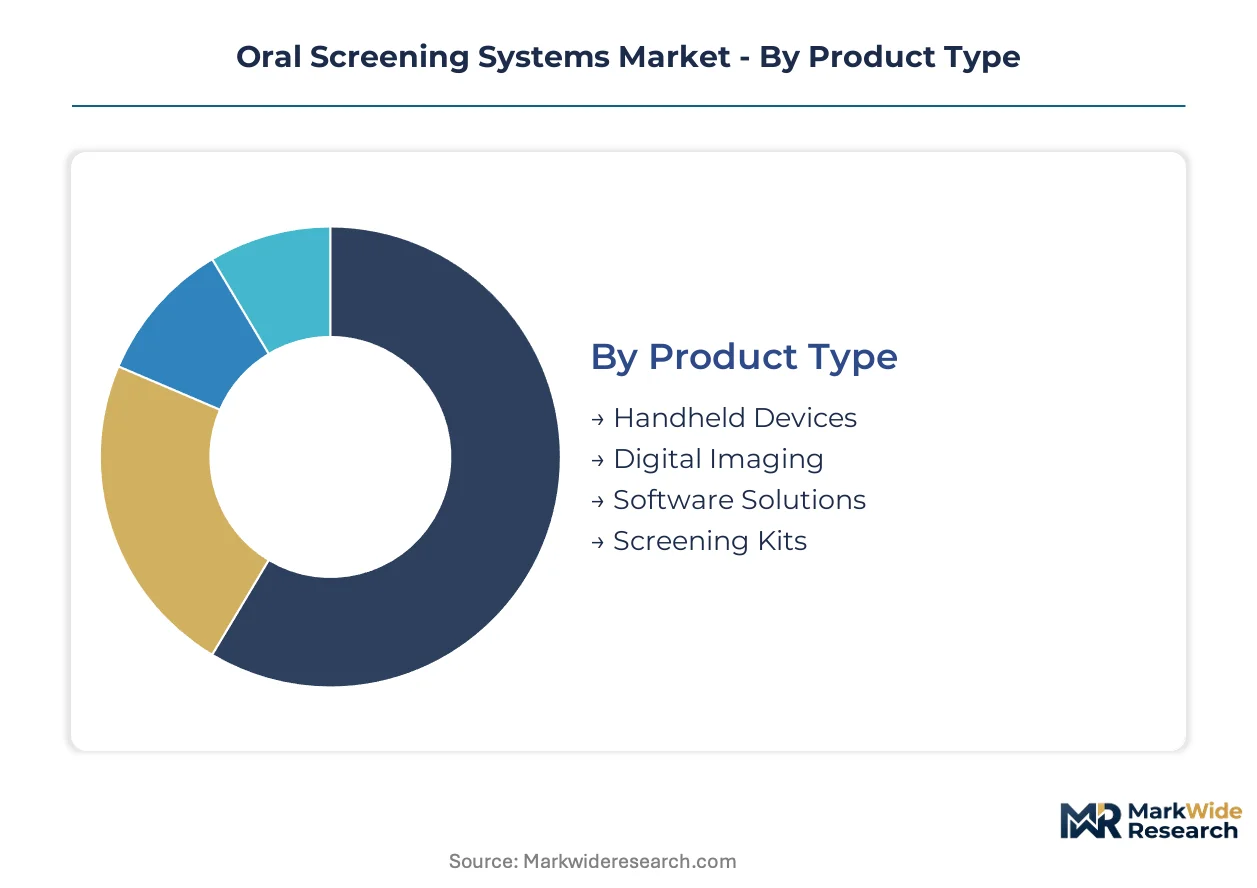
Segmentation in oral screening systems reveals divergent margin architectures across hardware, software, and consumable tiers. Product type and technology dimensions expose where capital expenditure concentrates versus where recurring revenue pools form.
Product Type:
Volume sales cluster in single-use screening kits, while premium economics accrue to software solutions with embedded AI classifiers.
- Handheld Devices:Portable fluorescence wands operating at 375-440 nanometer excitation wavelengths enable chairside deployment by dental hygienists during routine prophylaxis. Demand concentrates in Germany and Japan as national screening protocols mandate fluorescence documentation prior to specialist referral.
- Digital Imaging:CMOS detector-based platforms capture tissue autofluorescence across emission spectra above 500 nanometers for lesion discrimination. Dental clinics in the United States drive installed base expansion as FDA software-as-a-medical-device guidance accelerates 510(k) clearance for integrated imaging analytics.
- Software Solutions:Cloud-native platforms with machine learning classifiers reduce on-premise IT overhead for smaller practices.
- Screening Kits:Single-use consumables occupy the most price-sensitive tier with minimal differentiation.
Today's leader: Digital Imaging. Tomorrow's challenger: Software Solutions.
End User:
Procurement authority splits between corporate dental chains with centralized purchasing and independent clinics buying through manufacturer-direct channels.
- Dental Clinics:Solo and small-group practices in the United States adopt handheld fluorescence devices to differentiate service offerings against corporate chains. Subscription-based per-procedure leasing models convert capital expenditure into predictable operating costs for this fragmented customer base.
- Hospitals:Group purchasing organizations negotiate enterprise-wide pricing and service level agreements that consolidate procurement volume. Independent clinics face exclusion from these contracts and migrate toward transparent digital commerce configurations.
- Research Institutions:Academic medical centers source multi-spectral platforms for algorithm training dataset curation.
- Home Care:Direct-to-consumer screening remains nascent pending reimbursement coding clarity.
Procurement concentration favors Dental Clinics for unit volume; Hospitals command price leverage through scale aggregation.
Technology:
Established fluorescence platforms face margin pressure as artificial intelligence integration commands premium subscription structures.
- Fluorescence:LED excitation source miniaturization collapses form factor constraints that previously tethered systems to dedicated imaging suites. German and Japanese dental distributors consolidate vendor relationships to reduce EU Medical Device Regulation compliance documentation fragmentation.
- Artificial Intelligence:Machine learning classifiers embedded in screening platforms compress diagnostic pathways from chairside detection to histopathological referral. FDA software-as-a-medical-device guidance accelerates regulatory timelines for developers with clinical data science capabilities.
- Spectroscopy:Multi-spectral analysis expands beyond standard autofluorescence bands for enhanced tissue characterization.
- Photodynamic Therapy:Therapeutic applications remain adjunctive to diagnostic screening workflows.
Fluorescence anchors current installed base; artificial intelligence captures steepest expansion trajectory through recurring revenue conversion.
Application:
Cancer detection commands premium pricing while preventive care applications compete with conventional white-light visual examination.
- Cancer Detection:Adjunctive screening for oral squamous cell carcinoma drives fluorescence device adoption where reimbursement criteria tighten. PMDA-certified systems receive METI export promotion incentives targeting Southeast Asian market expansion.
- Preventive Care:Routine dysplasia identification during dental hygiene appointments expands addressable procedure volume. Solo practices in tier-two Indian cities present white space for cloud-native platforms bypassing on-premise infrastructure requirements.
- Diagnostic Screening:General mucosal abnormality detection supports broader clinical utility.
- Oral Hygiene:Basic plaque and inflammation assessment overlaps with existing dental equipment.
Cancer Detection commands margin premiums; Preventive Care scales through procedure volume expansion in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing oral screening system manufacturing toward jurisdictions with streamlined medical device pathways. FDA software-as-a-medical-device guidance in the United States accelerates 510(k) clearance timelines, while EU Medical Device Regulation compliance costs push some assembly operations toward East Asian manufacturing clusters with established CMOS detector supply chains.
United States
Solo dental practices and small-group clinics drive handheld fluorescence device adoption to differentiate against corporate chains. FDA software-as-a-medical-device guidance compresses regulatory timelines for machine learning classifiers embedded in screening platforms. Greater Boston and the San Francisco Bay Area concentrate venture-backed developers targeting AI-native diagnostic workflows.
Germany
Tightening reimbursement criteria for adjunctive oral cancer screening mandate fluorescence documentation prior to specialist referral. EU Medical Device Regulation post-market surveillance obligations extend certification timelines for Class IIa devices. The Munich-Stuttgart corridor hosts precision optics manufacturers supplying LED excitation components to tier-one device makers.
Japan
PMDA-certified fluorescence systems receive METI export promotion incentives targeting Southeast Asian market expansion. National screening protocol revisions are tightening documentation requirements for mucosal abnormality detection. The Kansai region around Osaka anchors domestic manufacturing of miniaturized LED excitation sources for portable diagnostic wands.
India
Tier-two dental clinic expansion in secondary cities creates white space for cloud-native screening platforms bypassing on-premise IT infrastructure. CDSCO medical device registration pathways are streamlining for software-as-a-medical-device categories. Bengaluru and Hyderabad concentrate telemedicine developers integrating AI-assisted screening with remote specialist triage workflows.
United Kingdom
Corporate dental groups controlling substantial chairside equipment procurement volume are consolidating purchasing through group buying organizations. Independent clinics excluded from these contracts migrate toward manufacturer-direct digital commerce channels. London and the Southeast concentrate distributor consolidation activity responding to EU Medical Device Regulation compliance documentation fragmentation.
Oral Screening Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native software subscriptions and cloud-native deployment models. The vendor base spans vertically integrated imaging conglomerates, specialized fluorescence device manufacturers, and venture-backed algorithm developers. Three archetypes dominate: hardware-software bundlers leveraging installed base relationships, standalone software platforms competing on IT overhead reduction, and component specialists controlling optical sensor supply. Competitive moves concentrate on strategic partnerships for algorithm training data access and geographic licensing agreements for regulatory pathway acceleration.
Within the imaging conglomerate tier, Dentsply Sirona and DenMat Holdings LLC exemplify contrasting approaches to market presence. Dentsply Sirona occupies a position among vertically integrated manufacturers leveraging software ecosystem bundling. DenMat Holdings LLC anchors specialized distributor relationships in the North American fluorescence segment. Apteryx Imaging represents the cloud-native archetype competing on reduced on-premise infrastructure requirements for smaller practices.
| Leading Market Players |
|---|
| Addent Inc |
| Dentilight Inc |
| PeriRX |
| DentalEZ |
| LED Denta |
| Zila |
| DenMat Holdings LLC |
| Apteryx Imaging |
| Dentsply Sirona |
| Others |
Value Network & Pricing Analysis
Backward integration into CMOS detector fabrication among tier-one manufacturers anchors both supply security and pricing power for fluorescence device producers. This captive production of optical sensors insulates Dentsply Sirona and DenMat Holdings LLC from Japanese precision optics export licensing delays while supporting subscription-based pricing models that bundle hardware with software analytics.
Pricing Analysis
Distributor margin compression in the North American fluorescence segment is forcing manufacturers toward direct digital commerce channels with transparent configuration tools. Three-tier pricing structure across premium AI-integrated platforms, standard fluorescence wands, and economy screening kits separates subscription SaaS tiers from per-unit transactional hardware sales. Cost compression in the kit tier intensifies because white-light visual examination substitutes retain dominance in public health programs. Corporate dental chains exhibit lowest price sensitivity through GPO-negotiated enterprise agreements; independent solo practices face highest sensitivity and migrate toward per-procedure leasing models.
Supply Chain Analysis
Freight cost volatility for precision optics shipments from Japan and Germany is accelerating regional assembly consolidation among device manufacturers. Manufacturing gravity centers on Japan, Germany, and the United States for LED excitation source miniaturization and CMOS detector integration. Component sourcing draws from East Asian manufacturing clusters for sensors, Munich-Stuttgart corridor for optical coatings, and Kansai region for portable wand assembly. Single-source dependency on Japanese precision optics manufacturers creates vulnerability to export licensing delays. Distribution runs through specialized dental distributors in Germany and France, manufacturer-direct digital channels for independent US clinics, and consolidated vendor relationships responding to EU MDR compliance documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage dynamics favor shifting software development to India and regulatory submissions to the United States, exploiting CDSCO pathway streamlining against EU MDR cost inflation.
For Market Incumbents: Hedge against standalone device commoditization by bundling AI classifiers into hardware contracts with mandatory subscription terms. Backward integration into CMOS detector supply secures margin control against Japanese optics export licensing volatility. DenMat Holdings LLC and Dentsply Sirona should consolidate distributor relationships to reduce EU MDR compliance documentation fragmentation across European portfolios. For New Entrants and Emerging Players: Cloud-native direct-to-clinic platforms bypass entrenched distributor networks and reduce on-premise IT overhead for tier-two Indian cities. White space concentrates in Bengaluru and Hyderabad telemedicine corridors integrating AI-assisted screening with remote specialist triage. Solo practices in secondary Indian cities present the most penetrable segment; manufacturer-direct digital commerce with transparent configuration tools offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native software platforms because dental clinic fragmentation creates distributed customer acquisition costs that centralized platforms amortize across recurring subscription revenue. Long-term viability hinges on FDA 510(k) clearance velocity and reimbursement coding clarity for adjunctive screening procedures. Acquisition targets should demonstrate clinical data science capabilities with oral pathology domain expertise; the signal to monitor is CDSCO software-as-a-medical-device registration acceleration for India market entry.| Strategic Initiative | Industry Significance |
|---|---|
| AI Classifier FDA Submission | Accelerates 510(k) clearance timelines under software-as-a-medical-device guidance for embedded screening analytics. |
| CMOS Detector Backward Integration | Captive sensor production insulates margin from Japanese precision optics supply concentration and export licensing delays. |
| Cloud-Native Platform Launch | Reduces on-premise IT overhead for tier-two Indian dental clinics bypassing infrastructure requirements. |
| Hospital System Partnership | GPO-negotiated enterprise agreements consolidate procurement volume and lock out independent clinic competitors. |
| Reimbursement Strategy Development | Adjunctive screening procedure coding clarity determines whether device economics shift toward capital purchase or per-procedure leasing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged dental clinic procurement managers, biomedical engineers at hospital purchasing committees, GPO contracts managers, fluorescence device distributors, and CDSCO regulatory affairs specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement coding records, and PMDA medical device registration filings. Bottom-up installed base estimates triangulated against top-down market sizing from capital equipment procurement surveys.
Segment-weighting approaches distributed value across hardware, software, and consumable tiers with technology adoption curves modeled for fluorescence, artificial intelligence, spectroscopy, and photodynamic therapy categories. Deployment mode, practice size, integration complexity, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from procedure volume elasticity to screening protocol mandates and sensor cost curve trajectories. Forecast inputs included CMOS detector fabrication scaling in East Asian manufacturing clusters and AI classifier sensitivity threshold improvements from machine learning training dataset expansion.
The model assumes a particular technology adoption path; alternative pathways for edge computing deployment in portable diagnostic wands would alter the outlook if latency constraints collapse faster than projected. Forecasts reflect assumptions about FDA software-as-a-medical-device guidance stability, EU MDR post-market surveillance cost trajectories, and METI export promotion incentive continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Protein Detection and Quantification Market