
 Bench-Top Dental Autoclaves Market | 2026-2036
Bench-Top Dental Autoclaves Market Size, Share, and Industry Trends Forecast 2026-2036
Bench-Top Dental Autoclaves Market Analysis
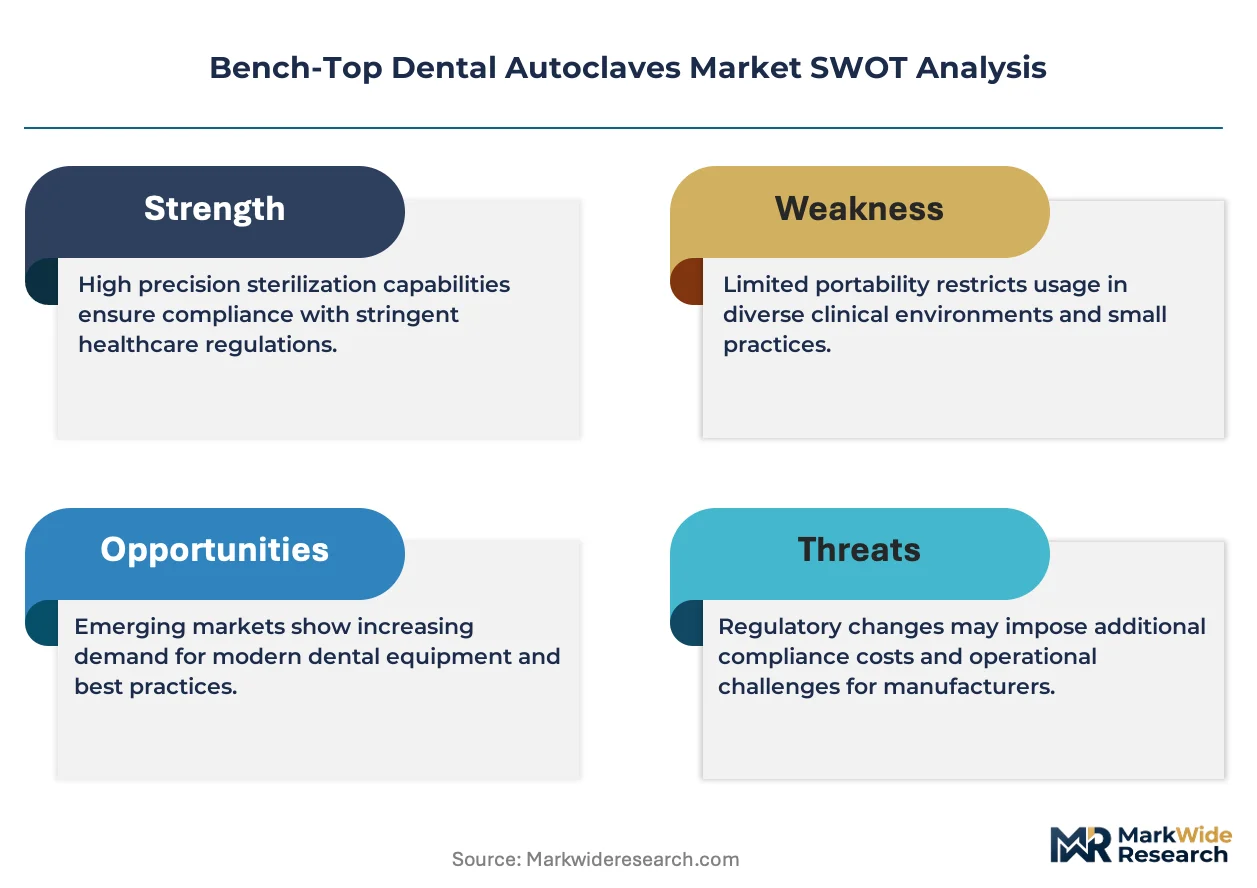
Equipment leasing and pay-per-cycle service contracts is reconfiguring competitive dynamics for smaller dental practices that previously deferred capital purchases. Tuttnauer leverages its installed base to sustain recurring revenue through validation and maintenance programs. MELAG Medizintechnik anchors premium positioning with German-engineered pre-vacuum systems. W&H Dentalwerk International differentiates through integrated workflow connectivity with its broader dental equipment portfolio.
Bench-top dental autoclaves are compact steam sterilization devices designed for point-of-care instrument reprocessing, typically operating at temperatures between 121°C and 134°C with chamber volumes under 25 liters to fit clinical countertops. Their primary purpose is to eliminate microbial contamination on reusable dental handpieces, burs, and procedural kits between patient appointments. Pre-vacuum technology commands the highest margin pool due to its superior air removal for hollow instrument loads, while gravity displacement units dominate unit volume in price-sensitive clinic segments. Touchscreen interfaces are gaining traction fastest among educational institutions and multi-chair practices seeking audit-ready cycle documentation.
FDA 510(k) clearance requirements and the European Union's MDR framework enforce bioburden validation and periodic performance qualification, directly shaping R&D priorities and aftermarket service intensity for manufacturers. ISO 17665 steam sterilization standards and national dental association guidelines in Germany, Italy, and Spain further stratify product certification tiers across regional procurement channels. Stakeholders must monitor how evolving sustainability mandates and energy efficiency labeling reshape total-cost-of-ownership calculations for clinic buyers weighing replacement cycles.
Market Dynamics
European MDR validation requirements for class IIa medical devices are compressing product development timelines while elevating aftermarket service intensity, forcing manufacturers to restructure revenue models around recurring compliance support rather than discrete equipment sales.
Growth Catalysts
- Pre-vacuum technology penetration:Hollow instrument loads in implantology and endodontics demand superior air removal, pulling clinics toward advanced sterilization systems that command premium positioning.
- Germany's dental manufacturing clusters:Concentrated instrument production in Biberach and Baden-Württemberg creates localized demand for validated reprocessing equipment with rapid technical support response.
- ISO 17665 standard harmonization:Unified steam sterilization benchmarks across EU member states reduce certification duplication costs, accelerating cross-border equipment procurement for multi-clinic dental groups.
Market Restraints
- Stainless steel and copper input volatility:Chamber fabrication depends on commodity metal pricing that fluctuates with energy costs, compressing margin predictability for manufacturers operating on fixed-price tenders.
- Gravity displacement saturation:Price-sensitive single-chair practices in Southern Europe delay replacement cycles, trapping volume in low-margin legacy technology segments with minimal upsell pathway.
- MDR notified body bottlenecks:Reduced EU certification capacity extends validation timelines, freezing new product introductions and forcing reliance on grandfathered legacy designs.
Strategic Opportunities
- Pay-per-cycle service contracts:Leasing models with bundled validation documentation unlock capital-constrained practices in Spain and Portugal that deferred purchases during prior investment cycles.
- Touchscreen audit integration:Educational institutions and multi-chair practices require cycle documentation connectivity, creating white space for workflow-integrated sterilization systems.
- Central European adjacent markets:Poland and Czech Republic dental clinic expansion outpaces domestic equipment manufacturing capacity, opening channels for German-engineered pre-vacuum system exports.
Industry Challenges
- Biomedical validation technician scarcity:Steam sterilization performance qualification requires specialized expertise that dental equipment distributors struggle to staff across fragmented regional service territories.
- Legacy handpiece compatibility:Older dental turbine designs lack standardized load configurations, forcing autoclave manufacturers to maintain extensive adapter libraries that complicate inventory and support logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bench-Top Dental Autoclaves Market |
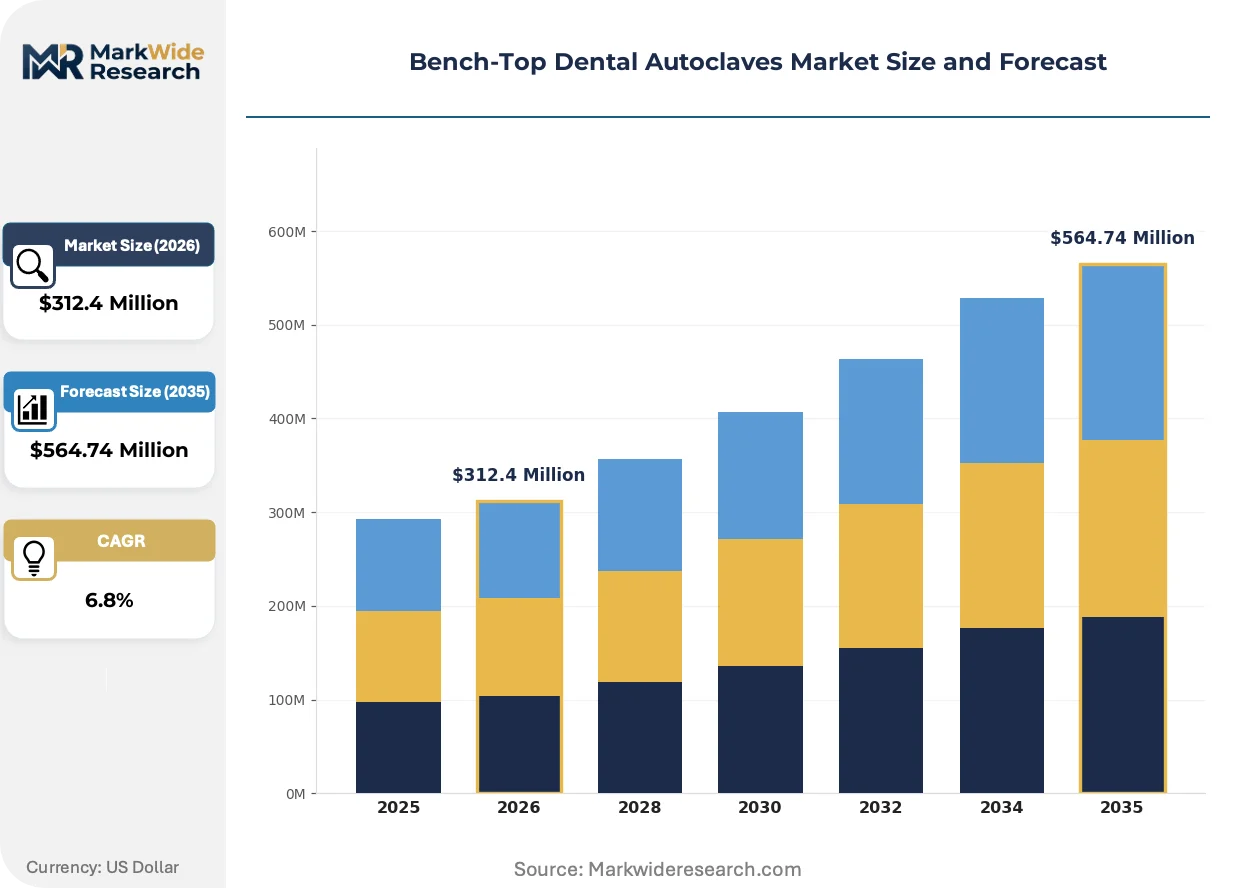
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Displacement, Pre-Vacuum, Steam, Cyclic Technology: Automatic, Manual, Hybrid, Touchscreen End User: Dental Clinics, Hospitals, Laboratories, Educational Institutions Capacity: 9 Liters, 12 Liters, 18 Liters, 23 Liters |
| Companies Covered | Tuttnauer, MELAG Medizintechnik, W&H Dentalwerk International, Fona Dental, Midmark Corporation, Antonio Matachana, Flight Dental Systems, Dentsply Sirona, RAYPA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bench-Top Dental Autoclaves Market Emerging Trajectories
Steam sterilization technology is compressing toward intelligent, connected systems that merge physical reprocessing with digital compliance documentation, reshaping how dental practices manage infection control workflows.
Pre-vacuum pulsing algorithms are collapsing cycle duration requirements for complex instrument loads. These advanced air removal sequences cut sterilization windows by eliminating residual steam barriers in hollow burs and handpieces. Multi-chair practices in Germany and Austria are adopting these systems fastest, compressing patient turnaround times while maintaining MDR-validated documentation trails.
EU MDR Article 10 post-market surveillance obligations are mandating systematic performance data collection from installed autoclave bases. Manufacturers must now maintain traceable sterilization records across device lifecycles, shifting competitive advantage toward vendors with embedded connectivity infrastructure. German dental associations are interpreting these requirements most strictly, driving regional procurement preference toward systems with native data logging capabilities.
Leasing structures with embedded maintenance are displacing outright purchase models among smaller dental practices. Capital constraints in Italy and Spain push clinic owners toward operational expenditure frameworks that bundle equipment, validation, and technical support. This behavioral shift concentrates buyer relationships with full-service providers capable of sustaining long-term compliance documentation rather than transactional equipment vendors.
Bench-Top Dental Autoclaves Market Segmentation
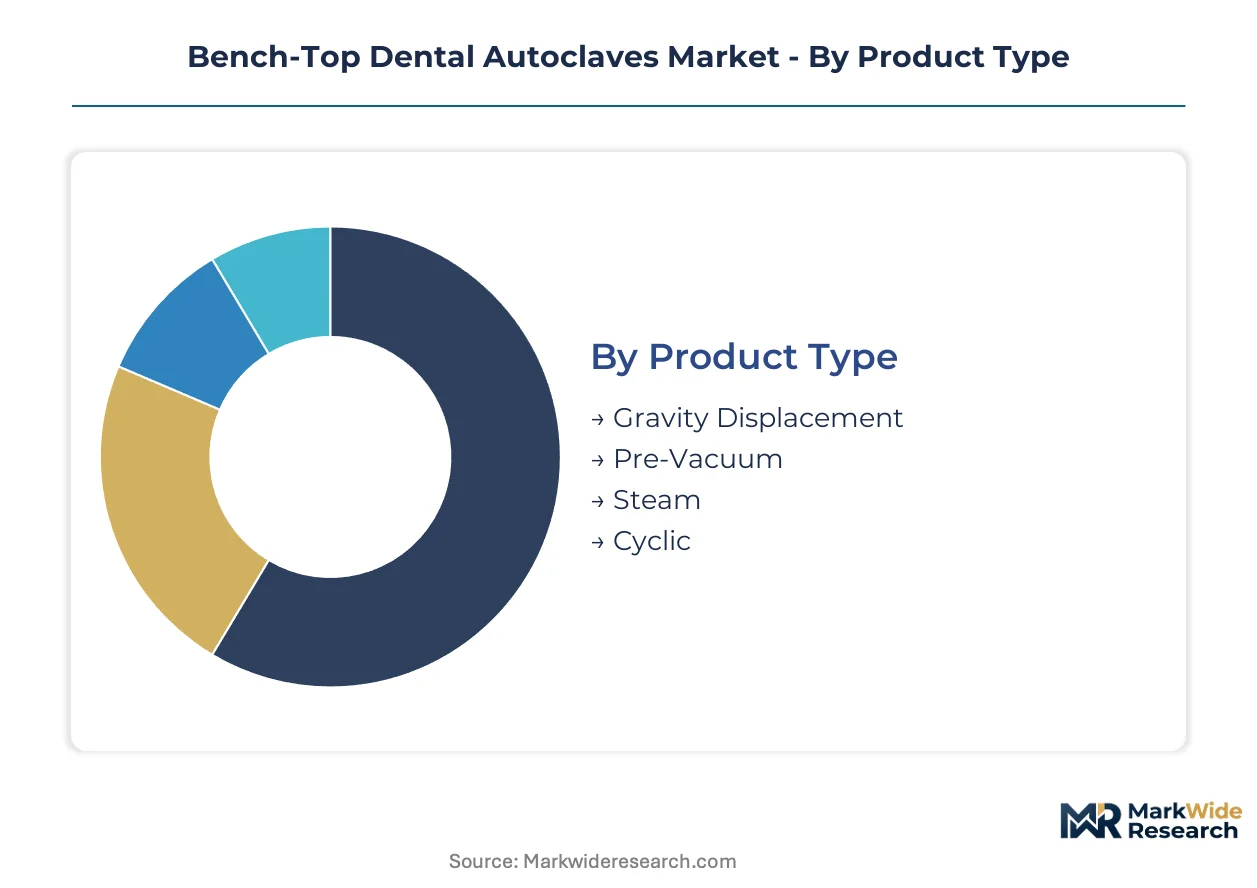
Segmentation in bench-top dental autoclaves reveals how sterilization technology stratifies across clinic operational models and regulatory compliance tiers. Each dimension—product type, technology interface, end-user scale, and chamber capacity—creates distinct procurement pathways and margin architectures for equipment vendors.
Product Type:
Mature gravity displacement systems anchor volume in cost-constrained installations, while pre-vacuum platforms command premium positioning in advanced reprocessing workflows.
- Gravity Displacement:These units rely on steam density differentials to displace ambient air from sterilization chambers, operating at lower capital cost but extended cycle durations. Southern European single-chair clinics defer replacement investments here, trapping procurement in low-margin tenders with minimal upsell conversion.
- Pre-Vacuum:Mechanical vacuum pumps extract air before steam injection, achieving rapid temperature penetration through hollow instrument lumens. Implantology and endodontics practices in Germany and Austria concentrate demand here, driven by MDR validation requirements for complex load configurations.
- Steam:Direct steam generation systems dominate laboratory and research sterilization protocols with precise temperature modulation.
- Cyclic:Programmable repeat-cycle units serve high-throughput educational institutions requiring batch consistency documentation.
Gravity displacement retains volume leadership; pre-vacuum holds the steepest expansion curve.
Technology:
Interface sophistication separates procurement tiers, with automated systems capturing compliance-driven replacement cycles and manual platforms persisting in legacy installations.
- Automatic:Microprocessor-controlled cycle management eliminates operator variability through pre-programmed steam parameters and integrated drying phases. Multi-chair dental groups in Central Europe standardize here to satisfy ISO 17665 documentation requirements with minimal technician training.
- Touchscreen:Capacitive interfaces with native data logging and network connectivity address EU MDR Article 10 surveillance obligations. German dental associations interpret post-market requirements most strictly, accelerating regional preference for audit-ready systems.
- Manual:Dial-based parameter selection persists in price-sensitive satellite clinics with low patient throughput.
- Hybrid:Semi-automated platforms blend manual load configuration with automated cycle execution for transitional upgrade paths.
Automatic platforms dominate replacement procurement; touchscreen interfaces are climbing the fastest.
End User:
Customer scale determines validation intensity and service contract attach rates, fragmenting vendor go-to-market strategies across fragmented practice structures.
- Dental Clinics:Private practice networks constitute the core installed base, with procurement decisions split between capital purchase and operational lease frameworks. Spain and Portugal show accelerating pay-per-cycle adoption among owners who deferred equipment investment through prior economic cycles.
- Hospitals:Central sterile supply departments integrate bench-top units as satellite reprocessing nodes, demanding enterprise-grade connectivity for inventory tracking.
- Laboratories:Research and quality control facilities prioritize cycle repeatability over speed, accepting extended processing windows for documentation precision.
- Educational Institutions:Dental schools require multi-user training protocols with tamper-proof cycle logging for competency certification.
Dental clinics anchor absolute volume; educational institutions are gaining share fastest.
Capacity:
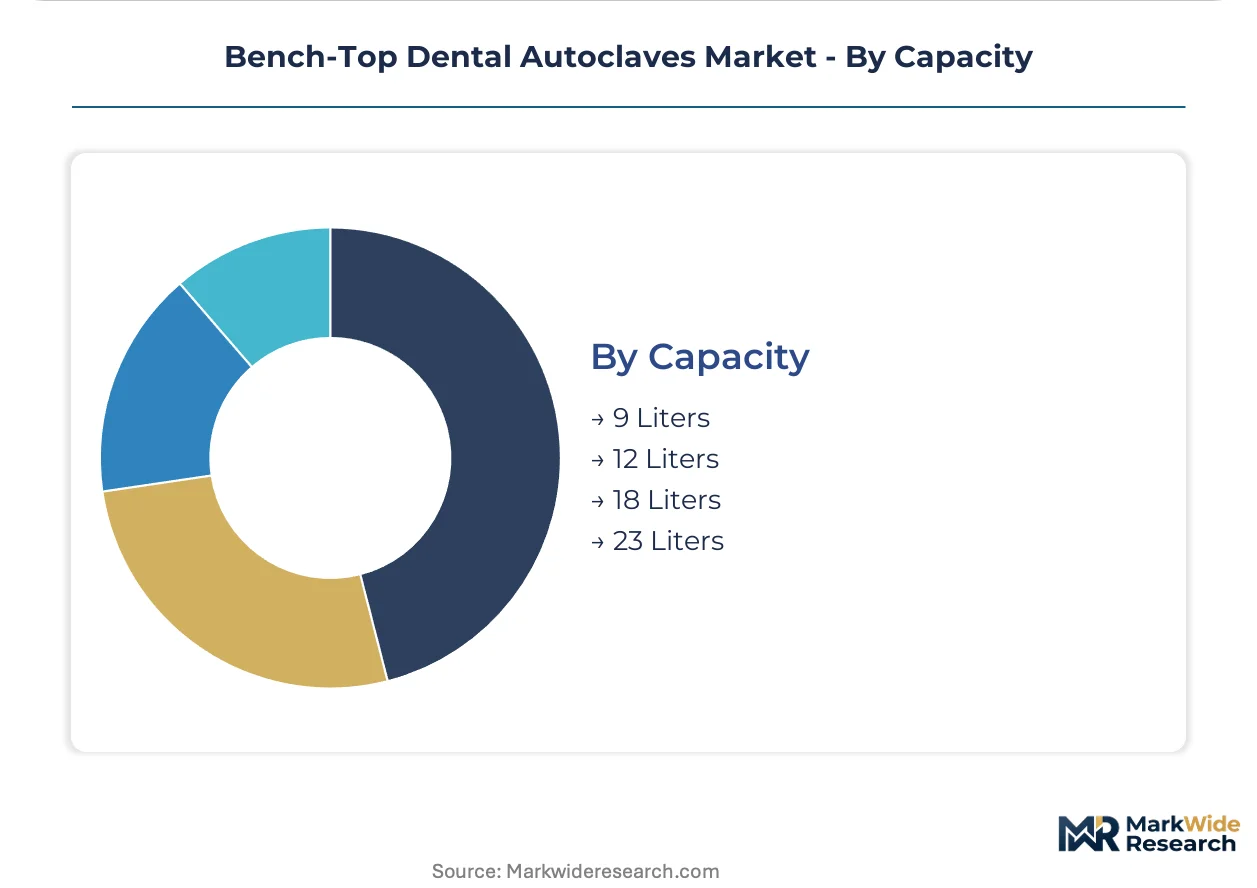
Chamber volume scales with patient throughput and instrument batch sizing, compressing footprint requirements against sterilization productivity tradeoffs.
- 18 Liters:Mid-range chambers accommodate standard procedural kits for two-to-three chair practices without countertop overflow. Poland and Czech Republic clinic expansions concentrate demand here, outpacing domestic manufacturing capacity and opening import channels.
- 23 Liters:Maximum compact footprints serve high-volume implantology centers processing extended instrument sets between appointments. German manufacturing clusters in Baden-Württemberg generate localized demand for rapid technical support response on these units.
- 9 Liters:Minimal footprint units occupy mobile dental vans and temporary field installations.
- 12 Liters:Entry-level capacity targets startup practices with predictable single-chair throughput.
Eighteen-liter chambers retain volume leadership; twenty-three-liter configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European Union MDR compliance deadlines are accelerating equipment replacement cycles across national dental markets, with sterilization validation requirements reshaping procurement priorities in Germany, Italy, Spain, Poland, and the United Kingdom.
Germany
Baden-Württemberg manufacturing clusters in Biberach generate concentrated demand for rapid-response technical support on pre-vacuum systems. The German Dental Association interprets EU MDR Article 10 surveillance obligations most strictly, driving preference toward audit-ready touchscreen interfaces. Multi-chair implantology practices in Stuttgart and Munich anchor premium-tier procurement volumes.
Italy
Capital-constrained single-chair practices in Southern regions defer replacement investments, trapping volume in gravity displacement segments. The National Institute of Health (Istituto Superiore di Sanità) enforces ISO 17665 documentation requirements for clinic accreditation. Pay-per-cycle leasing models gain traction in Rome and Milan metropolitan networks seeking operational expenditure frameworks.
Spain
Clinic expansion in Madrid and Barcelona outpaces domestic equipment manufacturing capacity, opening import channels for German-engineered systems. The Spanish Agency for Medicines and Health Products (AEMPS) mandates bioburden validation protocols under MDR transposition regulations. Educational institutions in Valencia and Seville concentrate demand for multi-user training protocols with tamper-proof cycle logging.
Poland
Dental clinic construction in Warsaw and Kraków exceeds local autoclave production capacity, creating white space for Central European equipment exports. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products enforces CE marking compliance for class IIa device market entry. Eighteen-liter chamber configurations dominate procurement for two-to-three chair practices in emerging urban centers.
United Kingdom
Post-Brexit regulatory divergence complicates cross-border equipment certification for Northern Irish clinics serving all-island dental networks. The Medicines and Healthcare products Regulatory Agency (MHRA) maintains MDR-aligned validation requirements pending permanent statute revision. London and Southeast England multi-practice groups standardize on automatic platforms to satisfy documentation requirements with minimal technician training.
Bench-Top Dental Autoclaves Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented national distribution territories. The vendor base stratifies into three tiers: full-service providers bundling equipment with validation documentation, technology-integrated dental equipment conglomerates, and regional fabrication specialists serving price-sensitive installations. Dominant competitive moves include portfolio diversification into workflow connectivity and geographic expansion through distributor acquisition in adjacent Central European markets.
Within the full-service provider tier, Tuttnauer leverages its installed base to sustain recurring revenue through validation and maintenance programs. MELAG Medizintechnik anchors premium positioning with German-engineered pre-vacuum systems. W&H Dentalwerk International occupies a position exemplifying technology-integrated workflow connectivity with broader dental equipment portfolios. These three entities represent distinct archetypes: the service-anchored incumbent, the engineering-specialist premium player, and the integrated equipment conglomerate.
| Leading Market Players |
|---|
| Tuttnauer |
| MELAG Medizintechnik |
| W&H Dentalwerk International |
| Fona Dental |
| Midmark Corporation |
| Antonio Matachana |
| Flight Dental Systems |
| Dentsply Sirona |
| RAYPA |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's concentrated pre-vacuum system manufacturing anchors premium margin pools in German-engineered chambers, while stainless steel and copper input volatility from Central European smelters compresses predictability for fixed-price tender participants.
Pricing Analysis
Certification level (MDR-class IIa/ISO 17665-grade) creates the primary spread between gravity displacement economy tiers and pre-vacuum premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation bundling and technical support attach rates. Cost compression in gravity displacement segments is intensifying because Southern European single-chair practices defer replacement investments. Price-sensitive clinic owners in Italy and Spain concentrate procurement in manual-interface legacy units, while German implantology practices absorb premium positioning for audit-ready touchscreen systems.
Supply Chain Analysis
EU dual-use export controls on precision vacuum pump technology limit component flows to non-CE-marking jurisdictions, constraining manufacturing expansion outside regulated trade zones. Chamber fabrication draws from German and Italian stainless steel rolling capacity, with copper heating elements sourced from Polish and Czech semi-finished metal processors. Single-source vulnerability concentrates in MDR-notified body certification capacity, freezing new product introductions when validation queues extend. Distribution runs through national dental equipment distributors with fragmented regional service territories, complicating aftermarket technical support scaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical validation technician scarcity constrains aftermarket service expansion, with specialized steam sterilization performance qualification expertise concentrated among legacy distributor workforces nearing retirement.
For Market Incumbents: Harden compliance documentation infrastructure against EU MDR Article 10 surveillance obligations by embedding native data logging capabilities across installed bases. Deepen backward integration into chamber fabrication to offset stainless steel input volatility from Central European smelters. Acquire distributor capabilities in Poland and Czech Republic to capture clinic construction outpacing domestic manufacturing capacity. For New Entrants and Emerging Players: Pursue pay-per-cycle service contract white space in Spain and Portugal where capital-constrained practice owners deferred equipment investment through prior economic cycles. Target educational institutions in Valencia and Seville requiring multi-user training protocols with tamper-proof cycle logging. Lead with touchscreen audit integration as the primary go-to-market wedge against legacy manual-interface installed bases. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental equipment conglomerates seeking exit liquidity from workflow connectivity platform investments. Five-to-ten year viability hinges on recurring revenue conversion from transactional equipment sales to validation and maintenance program bundling. Monitor MDR notified body capacity expansion as the critical inflection signal for new product introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Validation Documentation Bundling | EU Article 10 surveillance obligations force systematic performance data collection from installed autoclave bases. |
| Touchscreen Audit Integration Development | German dental associations interpret post-market requirements most strictly, accelerating regional procurement preference. |
| Central European Distributor Acquisition | Poland and Czech Republic clinic expansion outpaces domestic equipment manufacturing capacity. |
| Pre-Vacuum Pulsing Algorithm R&D | Multi-chair practices in Germany and Austria adopt advanced air removal sequences fastest. |
| Pay-per-Cycle Leasing Model Expansion | Spain and Portugal capital constraints push clinic owners toward operational expenditure frameworks. |
Methodological Framework
Cross-validation between primary interviews with dental equipment distributors and secondary validation through EU MDR transposition regulatory filings anchors the qualitative findings. Stakeholder consultations encompassed biomedical validation technicians, dental clinic procurement managers, GPO contracts managers, and aftermarket service heads. Secondary sources included CE marking databases, notified body capacity reports, ISO 17665 standard harmonization documentation, and national dental association accreditation guidelines. Bottom-up clinic installation counts and top-down equipment manufacturer revenue triangulation refined segment-level estimates.
Calibration against historical replacement cycle patterns and regulatory deadline acceleration effects shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass product type, technology interface, end-user scale, and chamber capacity, with regional regulatory cluster and MDR compliance tier as industry-specific overlays. CAGRs derived from equipment shipment trajectories and service contract attach rate evolution. Forecast inputs incorporated stainless steel price indices and notified body queue length projections.
Macroeconomic conditions sit as an overlay; deviation in Central European energy costs and dental clinic construction lending rates would shift the trajectory. Forecasts reflect documented assumptions on MDR enforcement uniformity and legacy handpiece adapter standardization timelines. Material shifts in EU MDR notified body capacity allocation or stainless steel export restriction regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
US Radiotherapy Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Refurbished MRI Systems Market