
 Robotic X-Ray Scanner Market | 2026-2036
Robotic X-Ray Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic X-Ray Scanner Market Outlook
High-resolution flat-panel detector specifications are redrawing competitive benchmarks in the Robotic X-Ray Scanner Market. Siemens Healthineers leverages in-house detector manufacturing to sustain premium positioning across European hospital networks. GE Healthcare anchors its portfolio through deep integration with surgical navigation ecosystems. Philips Healthcare differentiates via software-driven motion algorithms that reduce radiation exposure during cardiac catheterization procedures.
A robotic X-ray scanner consists of a motorized manipulator arm coupled to an X-ray source and digital detector array, typically operating at 80-150 kV tube potential with sub-millimeter spatial resolution for real-time anatomical imaging. Its primary commercial purpose is to enable hands-free positioning during interventional surgery, trauma response, and quality-critical industrial non-destructive testing. Fixed scanners dominate installed base value across hospital radiology departments, while portable configurations represent the fastest-expanding segment as ambulatory surgical centers seek flexible deployment without dedicated room infrastructure. Multi-modal scanners that fuse fluoroscopy with cone-beam CT command the strongest margin pools due to proprietary reconstruction software and specialized service contracts.
FDA 510(k) premarket notification requirements govern device safety and electromagnetic compatibility for systems sold into United States healthcare facilities, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE marking access across European member states. The International Electrotechnical Commission publishes IEC 60601-2-54 standards that define essential performance criteria for radiographic and radioscopic equipment, directly influencing manufacturer R&D allocation and test protocol design. Stakeholders must monitor evolving cybersecurity guidance from national regulators as network-connected robotic scanners face expanded scrutiny over data integrity and patient privacy controls.
Market Dynamics
Hybrid operating room construction is compressing deployment cycles for robotic X-ray scanners as hospitals consolidate imaging and surgical capabilities into single footprints. Siemens Healthineers and GE Healthcare are reallocating R&D toward autonomous positioning algorithms that eliminate manual C-arm repositioning during spine fusion procedures.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's abbreviated review track for predicate-based submissions is accelerating clearance timelines for manufacturers introducing iterative robotic positioning software. Device firms now file modular supplements rather than full premarket notifications for algorithm updates.
- Orthopedic surgical suite automation:Hospital systems in the United States are mandating hands-free fluoroscopy for complex trauma cases to reduce radiation exposure among operating room staff. Automated C-arm positioning is becoming a standard procurement specification in new construction.
- German university hospital procurement:Berlin and Munich medical centers are bundling robotic scanner purchases with ten-year service contracts, creating predictable revenue streams that justify premium hardware pricing.
Market Restraints
- Flat-panel detector supply concentration:Two Japanese suppliers control the majority of high-resolution amorphous silicon detector substrate production, creating vulnerability for scanner manufacturers dependent on sub-millimeter spatial resolution specifications.
- EU MDR clinical evidence requirements:The European Medical Device Regulation's expanded post-market surveillance mandates are extending CE marking timelines by 12-18 months for systems with autonomous navigation features.
- Fixed-room infrastructure requirements:Ceiling-mounted robotic arms require reinforced structural mounting points and specialized electrical grounding that retrofit installations cannot accommodate cost-effectively.
Strategic Opportunities
- Ambulatory surgical center portable deployment:Mobile robotic scanners with battery-powered positioning are penetrating outpatient facilities that lack dedicated radiology infrastructure, opening volume segments previously served by manual C-arm systems.
- IEC 60601-2-54 cybersecurity amendments:The International Electrotechnical Commission's pending network security standards for radiographic equipment are creating first-mover advantages for manufacturers with pre-integrated encryption and access control architectures.
- Cone-beam CT software convergence:Multi-modal systems combining fluoroscopy with volumetric reconstruction are commanding service contract premiums that offset hardware margin compression in standard radioscopic configurations.
Industry Challenges
- Robotics-mechanical engineering talent scarcity:Scanner manufacturers compete with automotive and aerospace sectors for engineers capable of integrating precision manipulator arms with real-time imaging feedback loops.
- Legacy PACS integration complexity:Hospital picture archiving and communication systems built on DICOM standards from the 1990s require custom middleware to accept positioning metadata from modern robotic scanners.
- Electromagnetic compatibility certification:IEC 60601-1-2 testing for immunity to surgical equipment interference consumes 8-10 months in accredited laboratories with limited global capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic X-Ray Scanner Market |
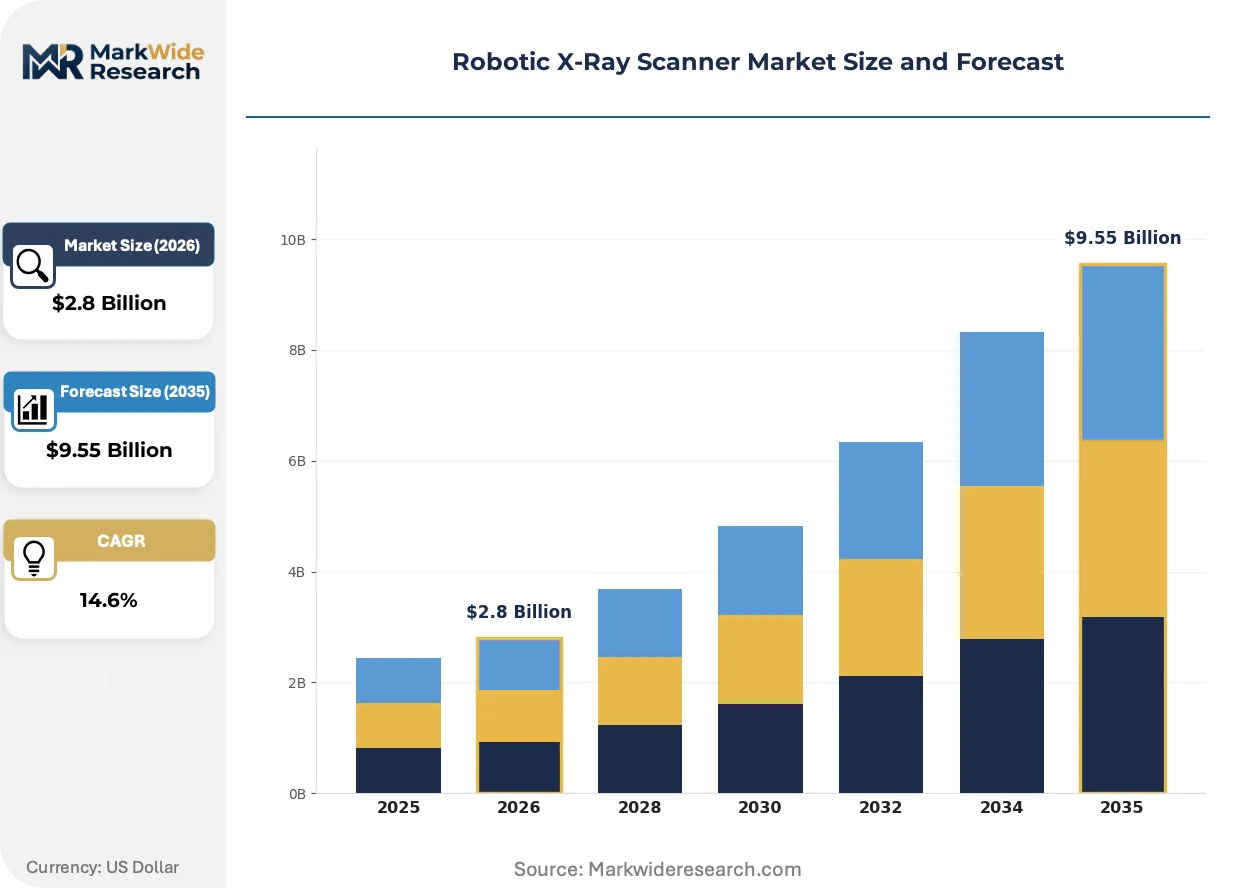
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Scanners, Fixed Scanners, Handheld Scanners, Multi-Modal Scanners End User: Hospitals, Clinics, Diagnostic Centers, Research Laboratories Technology: X-Ray Imaging, Computed Tomography, Fluoroscopy, Digital Radiography Application: Medical Imaging, Security Screening, Industrial Inspections, Veterinary Use |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Canon Medical Systems Corporation, Carestream Health, Shimadzu Corporation, Ziehm Imaging, Hologic, Hitachi Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic X-Ray Scanner Market Strategic Shifts
Artificial intelligence is embedding into scanner control architectures, shifting competitive advantage from hardware precision to predictive positioning algorithms that anticipate surgeon movement patterns.
Machine learning-based collision avoidance is displacing programmed safety envelopes in next-generation robotic C-arms. German university hospitals in Berlin and Munich are piloting these systems for complex spine procedures where patient positioning varies unpredictably. The technology is compressing setup times and reducing manual intervention requirements during lengthy operations.
The EU Medical Device Regulation's software-as-a-medical-device classification is forcing manufacturers to maintain clinical evidence libraries for algorithm updates. Scanner firms must now submit post-market performance data for each significant positioning software revision. Cardiac catheterization labs face the steepest compliance burden due to the frequency of algorithm updates in electrophysiology mapping integration.
Hospital procurement departments are unbundling hardware acquisition from service contracts, reversing the integrated pricing models that dominated the 2010s. Buyers now solicit competitive bids for preventive maintenance, software updates, and detector recalibration as separate line items. This shift is most pronounced in United States health systems with centralized supply chain functions, where category managers apply commodity purchasing disciplines to capital equipment.
Robotic X-Ray Scanner Market Segmentation
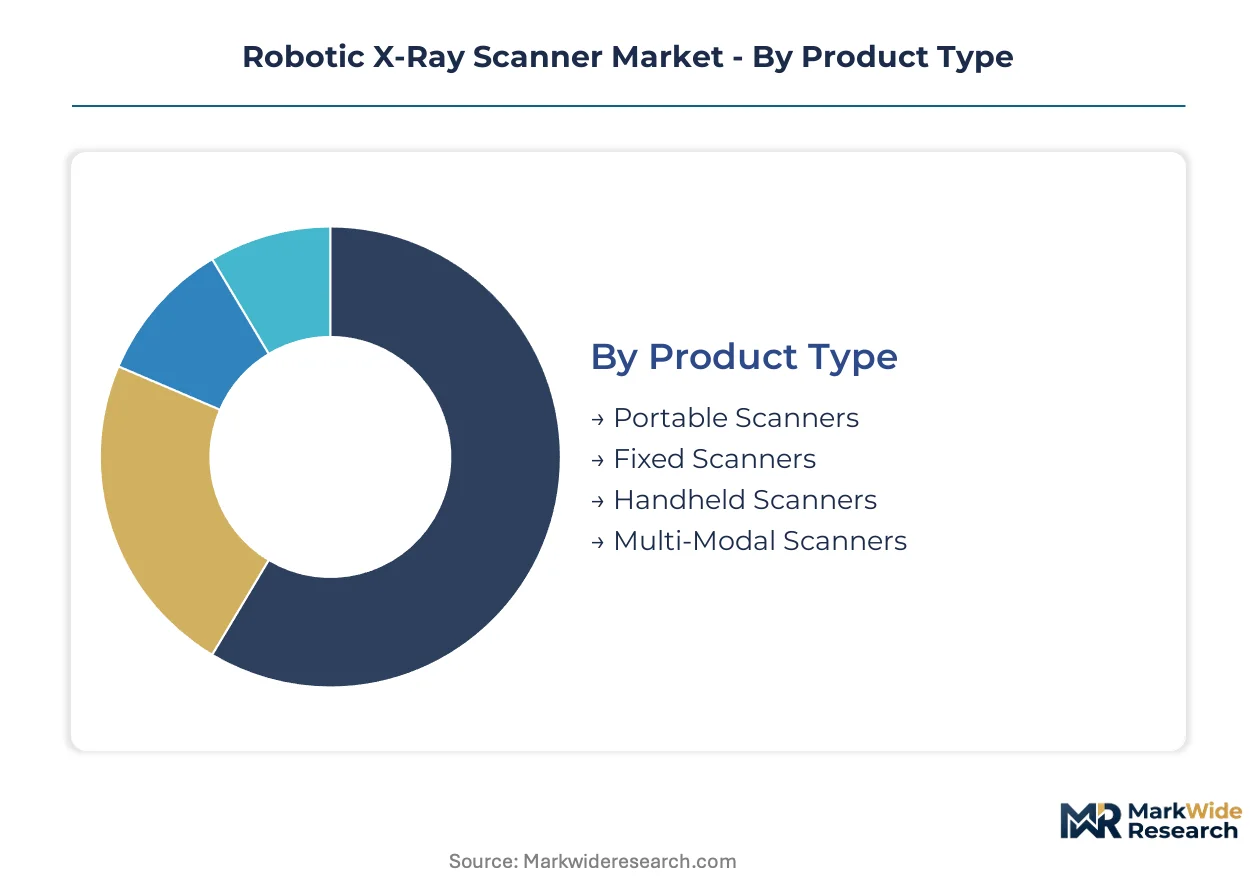
Margin concentration in robotic X-ray scanners varies sharply across hardware configurations, with multi-modal systems commanding service contract premiums while portable units unlock volume expansion in outpatient settings. Understanding segment-level profit pools reveals where manufacturers allocate R&D and which end-users drive procurement specifications.
Product Type:
Margin pools concentrate in multi-modal configurations where proprietary reconstruction software locks in recurring revenue, while portable systems compete on capital efficiency for budget-constrained buyers.
- Fixed Scanners:Ceiling-mounted robotic arms with motorized C-arm positioning dominate installed base value across hospital radiology departments. Hybrid operating room construction in Germany and the United States is mandating these systems for spine and trauma procedures, though reinforced structural requirements limit retrofit penetration.
- Multi-Modal Scanners:Systems fusing fluoroscopy with cone-beam CT reconstruction command the strongest margin pools through specialized service contracts and proprietary software licensing. University hospitals in Berlin and Munich are bundling ten-year service agreements with these purchases, creating predictable revenue streams.
- Portable Scanners:Battery-powered mobile units are penetrating ambulatory surgical centers lacking dedicated radiology infrastructure.
- Handheld Scanners:Compact motorized units serve point-of-care trauma response and field deployment scenarios.
The dominant share belongs to Fixed Scanners, while Portable Scanners are gaining share fastest through outpatient facility expansion.
End User:
Procurement authority and budget scale determine segment attractiveness, with hospital systems consolidating purchasing power while research laboratories demand specialized configurations.
- Hospitals:Academic medical centers and health systems in the United States are mandating hands-free fluoroscopy for complex trauma cases to reduce radiation exposure among operating room staff. FDA 510(k) pathway streamlining is accelerating deployment timelines for these high-volume purchasers.
- Diagnostic Centers:Outpatient imaging chains prioritize throughput optimization and standardized positioning protocols across multiple sites.
- Clinics:Smaller orthopedic and cardiology practices seek mobile configurations with flexible room requirements.
- Research Laboratories:Preclinical imaging facilities require sub-millimeter spatial resolution and customizable acquisition parameters.
Hospitals capture the dominant procurement volume, though Diagnostic Centers are expanding their installed base most aggressively.
Technology:
Regulatory classification intensity varies by modality, with fluoroscopy facing stricter clinical evidence requirements under EU MDR software-as-a-device frameworks.
- Fluoroscopy:Real-time X-ray imaging with continuous radiation output enables interventional guidance during cardiac catheterization and electrophysiology procedures. Cardiac catheterization labs face steep compliance burdens under EU MDR due to frequent algorithm updates in navigation integration.
- Digital Radiography:Static image capture with flat-panel detectors serves general radiography and trauma screening workflows.
- Computed Tomography:Volumetric reconstruction capabilities are converging with robotic positioning for intraoperative navigation.
- X-Ray Imaging:Conventional radiographic systems remain the baseline configuration for cost-sensitive purchasers.
Fluoroscopy retains the dominant technology share, while Digital Radiography is climbing the fastest through outpatient workflow optimization.
Application:
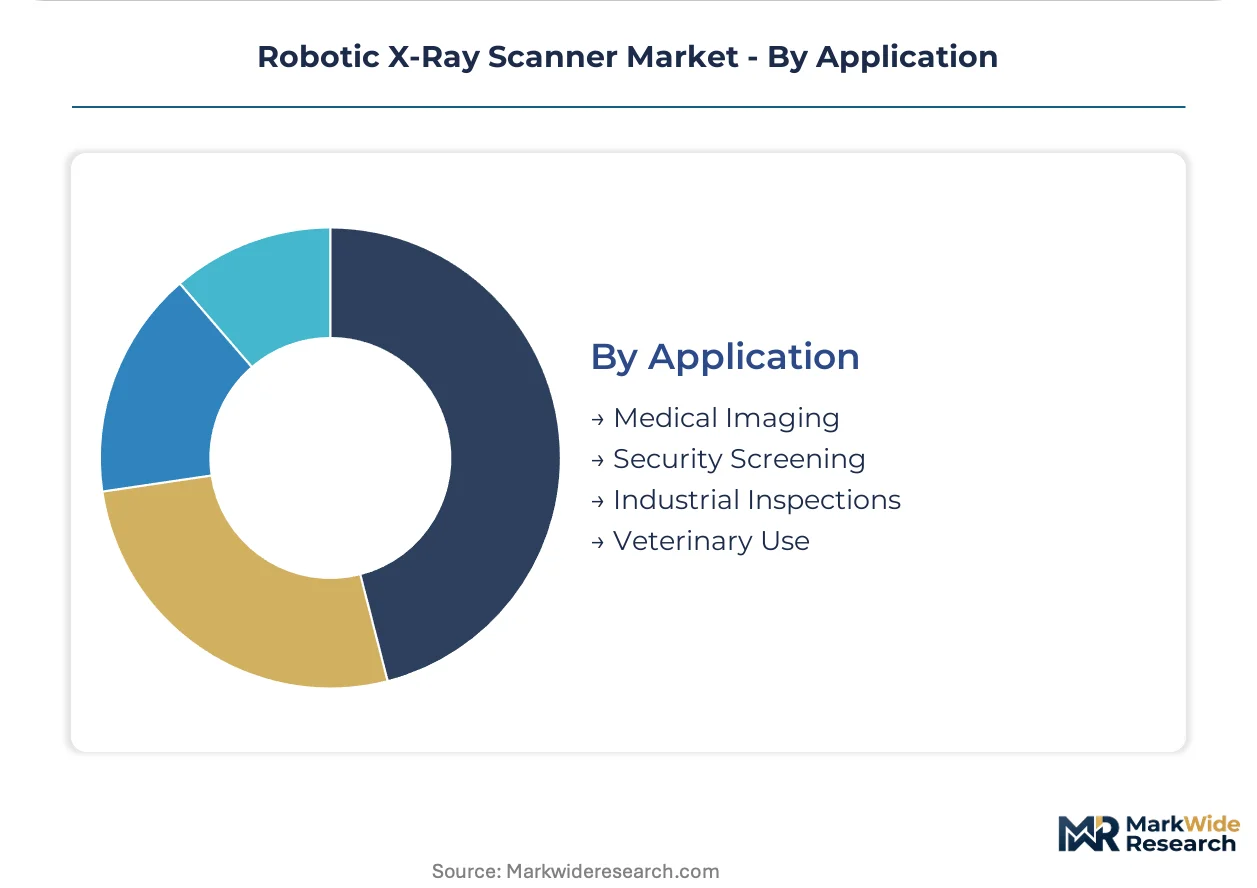
End-use diversification exposes manufacturers to distinct regulatory regimes and purchasing cycles, with medical imaging commanding premium pricing and industrial inspection driving volume scale.
- Medical Imaging:Surgical navigation, diagnostic radiology, and interventional procedures constitute the core revenue base. Orthopedic surgical suite automation in the United States is mandating hands-free positioning for complex spine fusion procedures.
- Security Screening:Border control and critical infrastructure inspection applications demand ruggedized mechanical designs.
- Industrial Inspections:Non-destructive testing for aerospace and energy sectors prioritizes sub-millimeter defect detection.
- Veterinary Use:Animal health clinics require compact footprints and species-agnostic positioning algorithms.
Medical Imaging commands the dominant application share, while Industrial Inspections are expanding most quickly through quality-critical manufacturing mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-resolution detector manufacturing concentrates in Japan and Germany, while scanner assembly and system integration gravitate toward the United States and European hospital procurement clusters. This geographic specialization shapes regulatory compliance priorities and installation infrastructure requirements across major demand centers.
United States
FDA 510(k) pathway streamlining accelerates deployment of autonomous positioning systems in orthopedic surgical suites across academic medical centers. The agency's modular supplement process for algorithm updates compresses clearance timelines for iterative software releases. Texas Medical Center in Houston and Mayo Clinic in Minnesota are mandating hands-free fluoroscopy for complex spine fusion procedures.
Germany
University hospitals in Berlin and Munich bundle robotic scanner purchases with decade-long service contracts, creating predictable revenue streams for manufacturers. EU MDR clinical evidence requirements extend CE marking timelines for systems with autonomous navigation features. The Bavarian medical technology cluster around Munich drives adoption of hybrid operating room configurations with integrated C-arm positioning.
Japan
METI industrial policy supports domestic production of amorphous silicon flat-panel detectors that supply global scanner manufacturers. PMDA regulatory frameworks align with IEC 60601 standards for electromagnetic compatibility certification. Tokyo and Osaka metropolitan hospital networks prioritize cone-beam CT integration for cardiac catheterization labs.
China
NMPA medical device registration requirements are harmonizing with international standards to accelerate market access for imported robotic imaging systems. The country's dual carbon goals are driving hospital procurement toward energy-efficient fluoroscopy configurations. Shanghai and Beijing tertiary hospitals are deploying multi-modal scanners for interventional radiology departments.
United Kingdom
NHS England capital investment frameworks prioritize standardized positioning protocols across regional hospital networks to reduce radiation exposure among operating room staff. MHRA post-market surveillance aligns with EU MDR transition timelines for existing CE-marked devices. London teaching hospitals and the Cambridge biomedical cluster are piloting machine learning-based collision avoidance systems.
Robotic X-Ray Scanner Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with premium-tier manufacturers commanding service contract premiums while mid-tier competitors penetrate outpatient facilities through portable configurations. The market structure consolidates around diversified medical technology conglomerates with in-house detector manufacturing capabilities and specialized surgical imaging firms with deep navigation software expertise. Three archetypes dominate: integrated healthcare technology giants with full-stack imaging portfolios, precision robotics specialists with surgical navigation partnerships, and regional equipment manufacturers with cost-optimized mobile systems. Competitive intensity centers on strategic partnerships with surgical navigation ecosystem providers and backward integration into flat-panel detector supply chains.
Among diversified healthcare technology conglomerates, Siemens Healthineers AG and GE Healthcare occupy positions exemplifying integrated imaging-to-surgery workflow control, while Philips Healthcare represents the software-driven radiation reduction archetype. These three anchors demonstrate how proprietary reconstruction algorithms and captive detector supply create defensive moats in multi-modal system segments. Ziehm Imaging GmbH sits within the specialized surgical C-arm tier, illustrating focused portfolio strategies that compete on procedure-specific positioning precision rather than breadth of imaging modalities.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Carestream Health |
| Shimadzu Corporation |
| Ziehm Imaging |
| Hologic |
| Hitachi Healthcare |
| Others |
Value Chain & Pricing Dynamics
Decade-long service bundling with university hospitals in Germany locks in both supply access and price visibility for manufacturers of multi-modal robotic X-ray systems. This contract structure insulates premium hardware margins from spot-market volatility in flat-panel detector substrates.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across the United States market, separating predicate-based submissions from de novo pathways. Three-tier pricing structure across premium, standard, and economy levels reflects detector resolution grades and autonomous navigation certification levels. Cost compression in portable configurations is intensifying because ambulatory surgical centers now solicit unbundled maintenance bids. Diagnostic centers exhibit the highest price sensitivity, while academic medical centers prioritize radiation reduction algorithms over capital cost.
Supply Chain Analysis
Amorphous silicon flat-panel detector substrate manufacturing concentrates in Japan underwrites the upstream bottleneck for global scanner production. Germany and the United States anchor final system assembly and surgical navigation software integration. Supply chains draw from high-purity silicon wafers, precision servo motors, and tungsten X-ray tube anodes. Single-source vulnerability concentrates in Japanese detector substrate suppliers. Distribution runs through hospital GPO contracts and direct university hospital procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution pressure from AI-native imaging startups offering software-only navigation layers that retrofit existing C-arm infrastructure.
For Market Incumbents: Fortify captive detector supply through backward integration into amorphous silicon substrate partnerships with Japanese suppliers. Deepen surgical navigation ecosystem control by embedding proprietary positioning algorithms into orthopedic OEM instrument trays. The threat of software-only navigation overlays demands hardware-software bundling discipline. For New Entrants and Emerging Players: FDA 510(k) abbreviated review fast-tracks predicate-based positioning software submissions, opening white-space in portable scanner segments for ambulatory surgical centers. Target battery-powered mobile configurations with flexible room requirements. Penetrate through unbundled service pricing that undercuts decade-long hospital contracts. For Investors and Strategic Acquirers: Capital is best deployed toward precision robotics specialists with surgical navigation partnerships and proprietary collision avoidance algorithms. Long-term viability hinges on software-as-a-medical-device revenue streams recurring across hardware replacement cycles. Watch FDA modular supplement filing volumes as inflection indicator for algorithm update velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Modular Supplement Pathway | Accelerates clearance timelines for iterative positioning software updates in United States orthopedic suites. |
| EU MDR Clinical Evidence Library | Mandates post-market surveillance data for each autonomous navigation algorithm revision. |
| Flat-Panel Detector Backward Integration | Secures supply of sub-millimeter resolution substrates from Japanese manufacturing clusters. |
| Hybrid Operating Room Partnership | Bundles robotic scanner procurement with decade-long service contracts at German university hospitals. |
| Cone-Beam CT Software Convergence | Commands service contract premiums through proprietary volumetric reconstruction licensing. |
Study Parameters
A standing panel of orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR CE marking registries, hospital procurement contract disclosures, and IEC 60601 standards documentation. Bottom-up unit economics triangulated against top-down healthcare capital expenditure flows.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled product type, end user, technology, and application dimensions alongside regional regulatory cluster intensity. CAGRs derived from procedure volume growth trajectories and capital replacement cycle timing. Forecast inputs incorporated hybrid operating room construction pipelines and ambulatory surgical center expansion rates.
Underlying assumptions cover FDA pathway streamlining continuity and EU MDR transition stability, with deviation risk concentrated in flat-panel detector supply disruptions and cybersecurity standard amendments. Practitioners should keep alternative scenarios live as IEC 60601-2-54 network security requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Ultrasound Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
UK Digital Radiology Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Open System MRI Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Neurophotonics Market