
 Bioactive Wound Management Market | 2026-2036
Bioactive Wound Management Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Wound Management Market Analysis
Hospital procurement consolidation is hardening purchasing power among large health systems, forcing suppliers to demonstrate superior clinical economics. Smith & Nephew leverages its integrated wound care portfolio to secure multi-year contracts with consolidated buyers. Mölnlycke Health Care AB anchors its position through proprietary silicone adhesive technology and direct hospital channel control. Organogenesis Inc. differentiates by specializing in living cell-based therapies for recalcitrant wounds.
Bioactive wound management encompasses dressings and devices engineered with biologically active components—antimicrobial agents, growth factors, or living cells—to modulate the wound healing cascade and promote tissue regeneration. These products typically incorporate collagen matrices, hyaluronic acid, or silver compounds delivered via sustained-release foam or hydrogel substrates, functioning to maintain moist wound environments while actively stimulating re-epithelialization and angiogenesis. Antimicrobial dressings capture premium pricing due to infection prevention mandates in surgical and chronic wound protocols, while foam dressings dominate volume through versatility across exuding wound types. Chronic wounds represent the fastest-expanding application segment as population aging and diabetes prevalence expand the addressable patient pool beyond acute care settings.
The FDA's 510(k) and PMA pathways govern bioactive product clearance in the United States, with escalating evidentiary requirements for biologic-containing devices extending development timelines and capital needs. The EU Medical Device Regulation (MDR) and REACH chemical safety standards impose additional conformity burdens on manufacturers seeking European market access, particularly for silver-releasing and collagen-derived formulations. Stakeholders must monitor evolving reimbursement coding for bioactive products versus standard of care, as payor coverage determinations increasingly dictate commercial viability irrespective of clinical efficacy profiles.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously elevating clinical evidence requirements for contract eligibility. Large integrated delivery networks now demand real-world healing outcomes data before granting formulary access to bioactive dressings.
Growth Catalysts
- Diabetic foot ulcer protocols:CMS reimbursement expansion for cellular and tissue-based products in outpatient settings accelerates clinician adoption of living cell therapies for limb salvage.
- Antimicrobial stewardship mandates:Joint Commission infection prevention standards drive substitution of systemic antibiotics with silver-releasing and PHMB-impregnated dressings in surgical site management.
- Collagen matrix innovation:Recombinant human collagen production methods reduce immunogenicity risks and raw material dependency on bovine and porcine sources.
Market Restraints
- Biologic raw material volatility:Porcine-derived collagen supply chains face disruption from African swine fever outbreaks in Southeast Asian farming regions.
- EU MDR conformity costs:Reclassification of absorbable wound dressings under Annex VIII rules extends technical documentation requirements and notified body review timelines.
- Autologous skin graft substitution:Split-thickness skin grafting remains the cost-minimizing default for large surface area burns in resource-constrained healthcare systems.
Strategic Opportunities
- Home-based chronic wound care:Remote patient monitoring integration creates channel access for advanced dressing systems outside traditional hospital settings.
- Japan's regenerative medicine framework:Conditional early approval pathways under PMDA guidelines accelerate market entry for cell-based wound healing products.
- 3D bioprinting convergence:Layered deposition of living keratinocytes and fibroblasts onto hydrogel scaffolds enables patient-specific graft geometry for complex wound beds.
Industry Challenges
- Clinical evidence generation timelines:Randomized controlled trials for chronic wound healing require 12-24 month follow-up periods, delaying PMA submissions for novel biologics.
- Reimbursement coding fragmentation:Inconsistent HCPCS Level II assignments across Medicare Administrative Contractors create prior authorization denials and payment uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Wound Management Market |
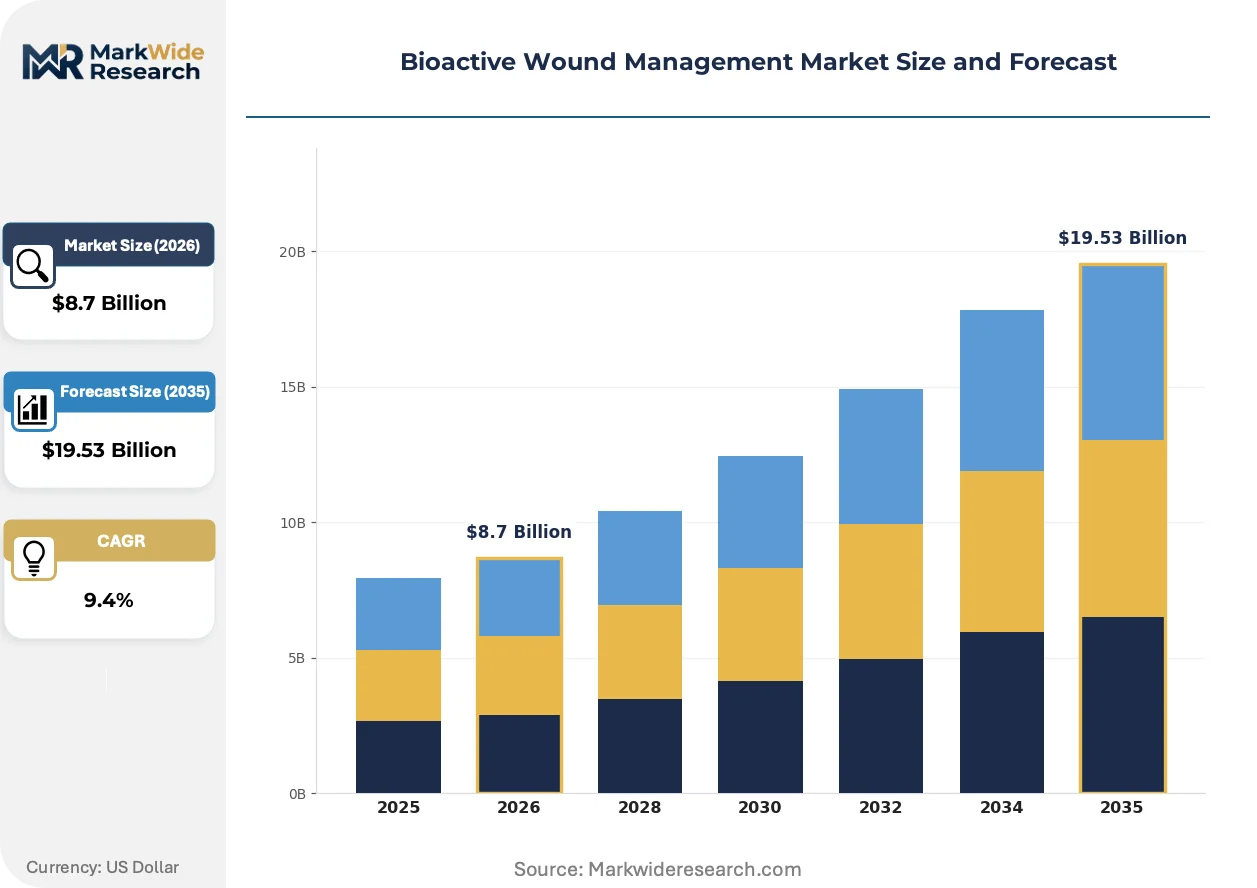
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Dressings, Hydrocolloid Dressings, Alginates, Antimicrobial Dressings Application: Chronic Wounds, Surgical Wounds, Traumatic Injuries, Burn Wounds End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Distribution Channel: Retail Pharmacies, Online Stores, Direct Sales, Wholesalers |
| Companies Covered | Smith & Nephew, 3M, B. Braun SE, Mölnlycke Health Care AB, ConvaTec Group PLC, Integra LifeSciences Corporation, Essity Health & Medical, Organogenesis Inc., Covalon Technologies Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Wound Management Market Emerging Trajectories
Bioactive wound management is pivoting from passive moisture retention to active cellular signaling. Manufacturers now engineer dressings that release growth factors in response to wound pH and enzymatic activity.
Electrospun nanofiber dressings loaded with sustained-release epidermal growth factor are rewriting healing expectations for partial-thickness burns. Burn centers in the United States and Germany are adopting these systems for pediatric scalds where grafting carries cosmetic liability. The technology is compressing time-to-complete re-epithelialization from three weeks to under ten days in superficial dermal injuries.
REACH authorization requirements for silver nanoparticles are forcing reformulation of antimicrobial dressings across European manufacturing. ECHA substance evaluation dossiers now demand ecotoxicity data for silver release into wastewater streams. German and French wound care suppliers are accelerating ionic silver alternatives and copper-based antimicrobial compounds to maintain European market access.
Integrated delivery networks are consolidating vendor contracts around total cost-of-care guarantees rather than unit price discounts. Hospital supply chain directors in Texas and Florida health systems now require wound healing outcome data tied to readmission reduction. This behavior concentrates purchasing power among three to five national distributors capable of delivering analytics infrastructure alongside product supply.
Bioactive Wound Management Market Segmentation
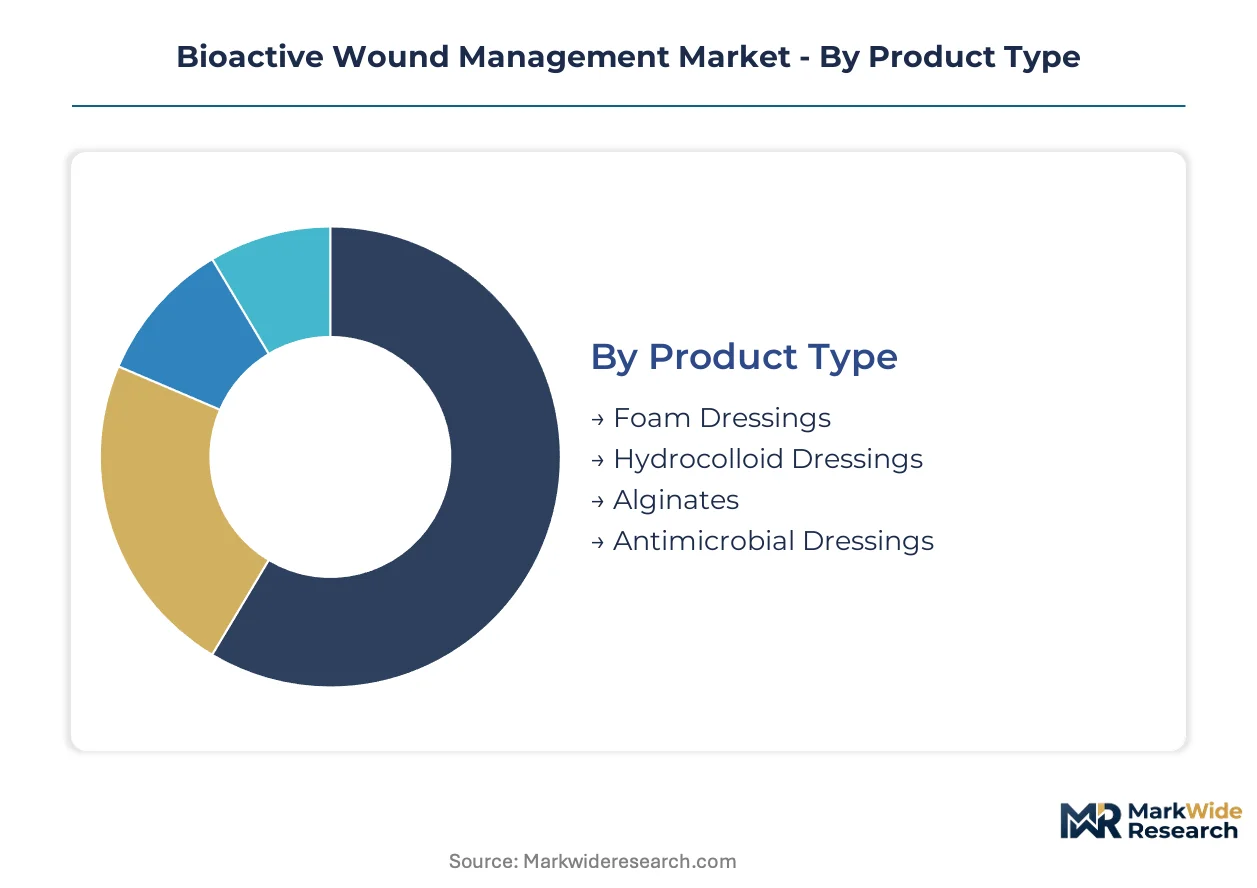
Segmentation in bioactive wound management reveals divergent margin profiles across product technologies and care settings. Foam and antimicrobial dressings command distinct pricing architectures, while chronic versus acute applications drive fundamentally different evidence requirements and procurement pathways.
Product Type:
Volume concentrates in moisture-retentive substrates, while premium pricing attaches to infection control and biologic-active formats.
- Foam Dressings:Hydrophilic polyurethane matrices absorb moderate-to-heavy exudate while maintaining moist wound interfaces. Demand clusters in post-operative surgical wards across Germany and the United States, where exudate management protocols standardize on foam as the default substrate. Hospital procurement consolidation favors foam suppliers capable of volume guarantees across multi-year contracts.
- Antimicrobial Dressings:Silver-ion, PHMB, or iodine-impregnated substrates deliver sustained antimicrobial release for infected or colonized wounds. Burn centers in Texas and Florida health systems specify these for partial-thickness thermal injuries where infection prevention supersedes cost minimization. FDA 510(k) clearance timelines for novel antimicrobial agents extend development cycles.
- Hydrocolloid Dressings:Carboxymethylcellulose-based wafers form gel matrices upon exudate contact, enabling autolytic debridement of necrotic tissue. Home healthcare nurses in Japan deploy these for pressure ulcer management where patient mobility limits dressing change frequency.
- Alginates:Calcium-sodium alginate fibers derived from brown seaweed convert to hydrogel upon fluid contact, supporting hemostasis in heavily exuding wounds. British community nursing services favor alginates for venous leg ulcer protocols.
Mature deployment sits with foam dressings. Newer deployment is concentrated in antimicrobial formats responding to stewardship mandates.
Application:
Chronic wound protocols generate recurring revenue streams, while acute applications concentrate volume in episodic purchasing patterns.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries require sustained intervention over months. CMS reimbursement expansion for cellular products in United States outpatient settings accelerates adoption of living cell therapies for limb salvage. Population aging across Italy and Spain expands the addressable patient pool beyond hospital settings.
- Surgical Wounds:Incisional and excisional wound management follows standardized protocols with defined endpoints. Antimicrobial stewardship requirements from Joint Commission standards drive substitution of systemic antibiotics with topical silver in United States surgical suites. Procurement consolidation compresses margins for standard dressings.
- Traumatic Injuries:Acute mechanical wounds from accidents or combat require rapid hemostasis and infection control. Military medical services in Israel and South Korea specify hemostatic dressings for field trauma kits.
- Burn Wounds:Partial and full-thickness thermal injuries demand specialized moisture balance and pain management. German pediatric burn centers adopt electrospun growth factor dressings for superficial dermal injuries where grafting carries cosmetic liability.
Revenue concentration favors chronic wound management. Volume throughput peaks in surgical wound protocols.
End User:
Institutional buyers leverage scale for price compression, while home settings command premium pricing for convenience and reduced clinical supervision.
- Hospitals:Integrated delivery networks negotiate enterprise contracts tying formulary access to real-world outcome data. Texas and Florida health systems require wound healing metrics tied to readmission reduction before granting vendor access.
- Home Healthcare:Remote patient monitoring integration creates channel access for advanced dressing systems outside traditional facilities. Japanese home nursing agencies specify hydrocolloids for pressure ulcer prevention in aging-in-place populations.
- Clinics:Outpatient wound care centers in the United States specialize in diabetic foot ulcer management under expanded CMS reimbursement for cellular products.
- Long-term Care Facilities:Nursing homes across France and Belgium face regulatory pressure for pressure ulcer prevention, driving standardized dressing protocols.
Procurement sophistication concentrates in hospital systems. Growth velocity is climbing fastest in home healthcare channels.
Distribution Channel:
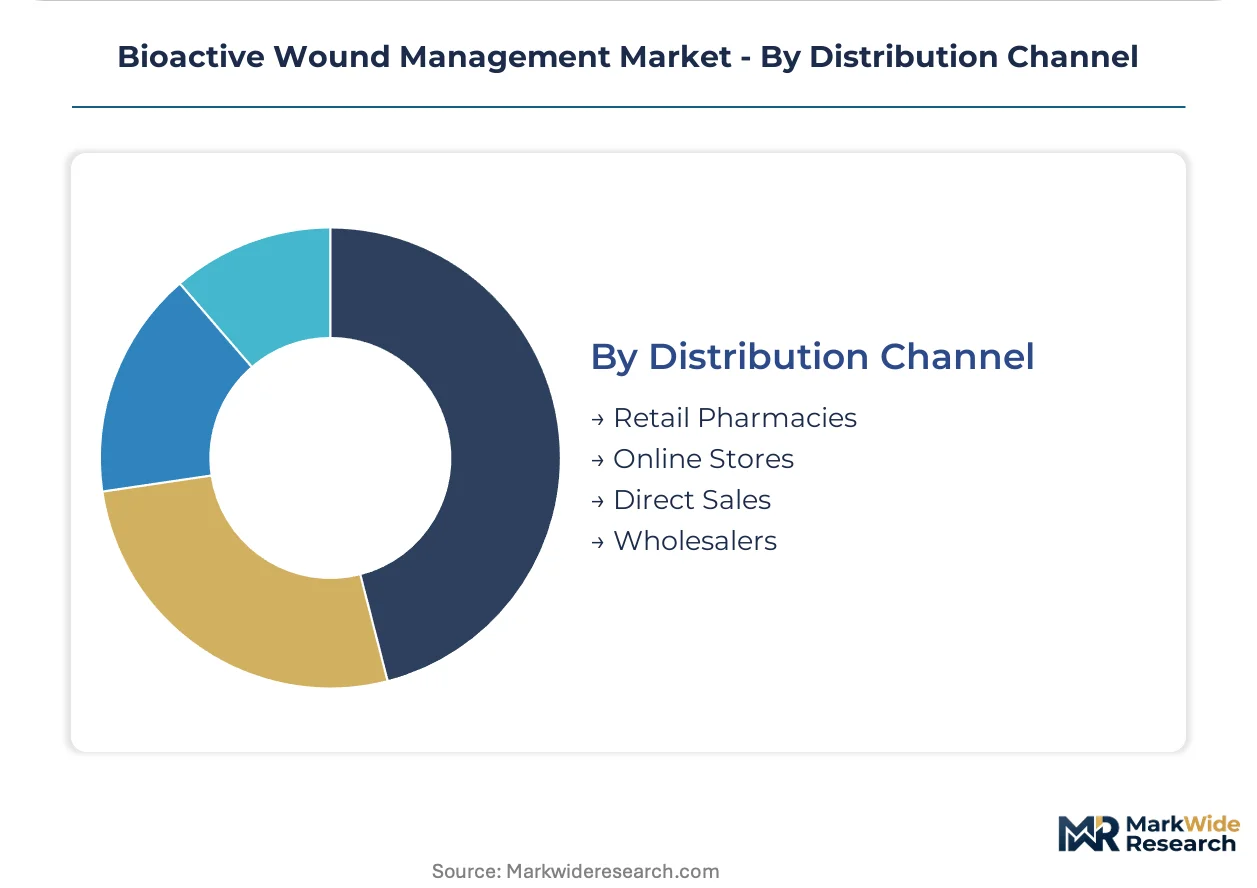
Direct sales relationships capture high-value institutional contracts, while retail and digital channels fragment pricing power.
- Direct Sales:Manufacturer field forces secure multi-year agreements with consolidated health systems, embedding clinical specialists within customer organizations. Smith & Nephew and Mölnlycke anchor positions through dedicated hospital channel control.
- Wholesalers:Cardinal Health and McKesson aggregate demand across fragmented clinic and long-term care segments, extracting distribution margins without clinical value-add.
- Retail Pharmacies:CVS and Walgreens stock consumer-oriented hydrocolloids and foam dressings for self-pay chronic wound patients.
- Online Stores:Amazon and specialized medical supply platforms enable price comparison for home healthcare purchasers, compressing brand premiums.
Margin protection relies on direct sales. Channel expansion is concentrating in digital platforms serving home-based patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porcine-derived collagen supply chains anchor Southeast Asian production networks, while FDA-cleared manufacturing clusters concentrate in Massachusetts and North Carolina. Reimbursement density and regulatory sophistication determine commercial prioritization across national markets.
United States
Diabetic foot ulcer incidence drives sustained clinical adoption of cellular and tissue-based products across Texas and Florida health systems. CMS reimbursement expansion for outpatient biologics accelerates clinician uptake of living cell therapies for limb salvage. The Research Triangle Park corridor in North Carolina hosts concentrated manufacturing capacity for collagen matrix production.
Germany
Pediatric burn centers in Bavaria and Baden-Württemberg specify electrospun growth factor dressings for superficial dermal injuries where grafting carries cosmetic liability. ECHA REACH authorization requirements for silver nanoparticles force reformulation of antimicrobial dressings across domestic manufacturing. The Munich-Stuttgart industrial corridor anchors European headquarters operations for major wound care suppliers.
Japan
Aging-in-place populations expand home healthcare nursing demand for hydrocolloid dressings in pressure ulcer prevention protocols. PMDA conditional early approval pathways under the regenerative medicine framework accelerate market entry for cell-based wound healing products. The Kansai region around Osaka hosts specialized manufacturing clusters for hyaluronic acid-derived wound substrates.
United Kingdom
Community nursing services favor alginates for venous leg ulcer protocols across England and Scotland. The Medicines and Healthcare products Regulatory Agency enforces EU MDR-aligned conformity assessment for absorbable wound dressings post-Brexit transition. The Cambridge-Oxford life sciences corridor attracts biologic wound care R&D investment from international manufacturers.
Australia
Rural and remote healthcare networks drive demand for extended-wear antimicrobial dressings where clinical access is limited. The Therapeutic Goods Administration aligns medical device classification with EU MDR standards for collagen-containing products. Sydney and Melbourne host distribution hubs serving Pacific Island tertiary referral pathways for complex chronic wound management.
Bioactive Wound Management Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue living cell therapy specialization and 3D bioprinting convergence. The vendor base stratifies across integrated multinationals with hospital channel control, mid-scale specialists in silicone adhesive or collagen matrix technologies, and venture-backed biologics developers. Dominant competitive moves include procurement consolidation response through real-world outcome data partnerships, and geographic expansion via Japan's PMDA early approval pathways.
Among UK and Swedish integrated manufacturers, Smith & Nephew and Mölnlycke Health Care AB exemplify the channel-anchored archetype through direct hospital relationship control. Organogenesis Inc. occupies a position within the living cell therapy specialist tier, representing the biologics-focused competitive vector. These three entities illustrate the strategic divergence between scale-driven portfolio breadth and concentrated therapeutic specialization.
| Leading Market Players |
|---|
| Smith & Nephew |
| 3M |
| B. Braun SE |
| Mölnlycke Health Care AB |
| ConvaTec Group PLC |
| Integra LifeSciences Corporation |
| Essity Health & Medical |
| Organogenesis Inc. |
| Covalon Technologies Ltd |
| Others |
Supply Flow & Price Mechanics
Porcine-derived collagen feedstock costs cascade through three pricing tiers for finished dressings, with bovine alternatives commanding premiums where African swine fever disrupts Southeast Asian farming networks. Hospital procurement consolidation in Texas and Florida health systems extracts volume discounts that compress margins for standard foam substrates while preserving premiums for living cell therapies.
Pricing Analysis
Service bundling separates vendors supplying clinical outcome analytics from commodity suppliers offering bare product. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier, with 510(k) pathways supporting mid-tier positioning and PMA-tracked biologics capturing top-tier rates. Cost compression in standard foam dressings is intensifying because integrated delivery networks demand real-world healing data before formulary access. Home healthcare channels show lowest price sensitivity due to convenience premiums and reduced clinical supervision requirements.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian porcine farming regions supplying collagen raw materials for matrix production. Manufacturing capacity concentrates in the United States, Germany, and Japan, with the Research Triangle Park corridor anchoring North American biologic output. Raw material dependencies encompass porcine and bovine collagen, hyaluronic acid from Kansai-region fermentation facilities, and silver compounds subject to ECHA REACH authorization. Tariff exposure on Chinese-sourced alginate fibers threatens alginate dressing cost structures. Distribution runs through direct sales teams for hospital systems and wholesale aggregators for fragmented clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Living cell therapy manufacturing capacity constraints prop pricing power for qualified suppliers, as PMDA and FDA evidentiary requirements limit rapid scale-up. This supply-constrained dynamic favors incumbents with validated production infrastructure.
For Market Incumbents: Extend real-world outcome data partnerships with consolidated health systems to secure multi-year formulary lock-in against emerging biologics developers. Deepen backward integration into recombinant human collagen production to reduce dependency on volatile porcine supply chains. Anchor hospital channel control through embedded clinical specialist teams that emerging entrants cannot replicate.
For New Entrants and Emerging Players: Begin with Japan's PMDA conditional early approval pathway for cell-based wound healing products, where regulatory frameworks accelerate market entry ahead of FDA timelines. Target home healthcare channels for remote patient monitoring-integrated dressing systems, the segment showing fastest growth velocity and lowest incumbent saturation. Pursue reimbursement strategy partnerships with outpatient wound care clinics ahead of manufacturing scale-up.
For Investors and Strategic Acquirers: CMS reimbursement expansion for cellular products in outpatient settings is the leading indicator that living cell therapy specialists will command sustained valuation premiums over commodity dressing manufacturers. Acquisition focus should center on biologics developers with validated PMA-tracked pipelines and established clinician adoption in diabetic foot ulcer protocols. Watch for FDA 510(k) clearance accelerations for novel antimicrobial agents as signals of competitive inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures multi-year formulary access through real-world outcome data commitments in Texas and Florida health systems. |
| FDA PMA Submission | Unlocks premium pricing tier for living cell therapies in diabetic foot ulcer limb salvage protocols. |
| Reimbursement Strategy | Aligns product coding with CMS coverage determinations that dictate commercial viability irrespective of clinical efficacy. |
| Backward Integration | Captures recombinant human collagen production to insulate margins from African swine fever supply disruptions. |
| PMDA Early Approval Pathway | Accelerates market entry for cell-based products under Japan's regenerative medicine conditional framework. |
Methodological Framework
Document review covered FDA 510(k) and PMA filings, CMS reimbursement coding databases, ECHA REACH substance evaluation dossiers, and EU MDR technical documentation requirements, complemented by interviews with hospital procurement directors, wound care clinicians, GPO contracts managers, and regulatory affairs leads at biologics developers. Secondary validation drew from hospital procurement databases, GPO contract repositories, and Medicare claims data. Bottom-up demand modeling across product types and care settings was cross-checked against top-down market sizing.
Segment-level projections across foam, antimicrobial, hydrocolloid, and alginate formats were generated through the analysis window, with chronic versus acute application splits and institutional versus home care end-user disaggregation. CAGRs were derived from regression analysis against diabetic foot ulcer incidence trajectories, antimicrobial stewardship mandate adoption curves, and reimbursement expansion timelines. Industry-specific inputs encompassed porcine collagen supply volatility indices and PMDA conditional approval velocity metrics.
Underlying measurement precision varies by segment; mature foam dressing categories carry tighter precision than emerging electrospun nanofiber formats where clinical adoption curves remain unsettled. Forecasts reflect assumptions around regulatory pathway timelines and reimbursement coding stability that African swine fever outbreaks or EU MDR reclassification could materially revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Europe Advanced Wound Care Market
Wound Care
Global Compression Bandages Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Wound Care Centers Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Acute Wound Care Market
Wound Care
Maggot Debridement Market
Wound Care
Venous Ulcer Treatment Market
Wound Care
Chronic Wound Care Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Biopatches Market