
 Global Silver Wound Dressing Market | 2026-2036
Global Silver Wound Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silver Wound Dressing Market Foresight
The EU Medical Device Regulation is broadening the cost-of-entry calculus for silver wound dressing manufacturers seeking CE marking. Smith & Nephew plc leverages its clinical evidence portfolio to navigate expanded notified body requirements. Mölnlycke Health Care AB anchors its position through integrated manufacturing of absorbent foam substrates with ionic silver.
Silver wound dressings are advanced antimicrobial barriers comprising silver sulfadiazine, nanocrystalline silver, or ionic silver embedded in substrates such as hydrofiber, foam, or alginate, designed to manage exudate while suppressing bacterial bioburden in moist wound environments. Foam dressings with silver additives command margin pools due to superior exudate handling in surgical and chronic wound protocols. Hydrogel dressings with silver represent the fastest-expanding product configuration, driven by applicability to dry necrotic wounds and burn care where rehydration accelerates autolytic debridement.
The FDA governs silver dressings as Class II medical devices requiring 510(k) clearance with antimicrobial efficacy claims, while the EMA coordinates post-market surveillance through the Eudamed database under MDR traceability mandates. Japan's PMDA imposes additional silver ion release profiling for device approvals, creating distinct formulation requirements across regulatory zones. Stakeholders must monitor evolving biocompatibility testing standards and antimicrobial resistance surveillance data to align R&D pipelines with shifting clinical acceptance thresholds.
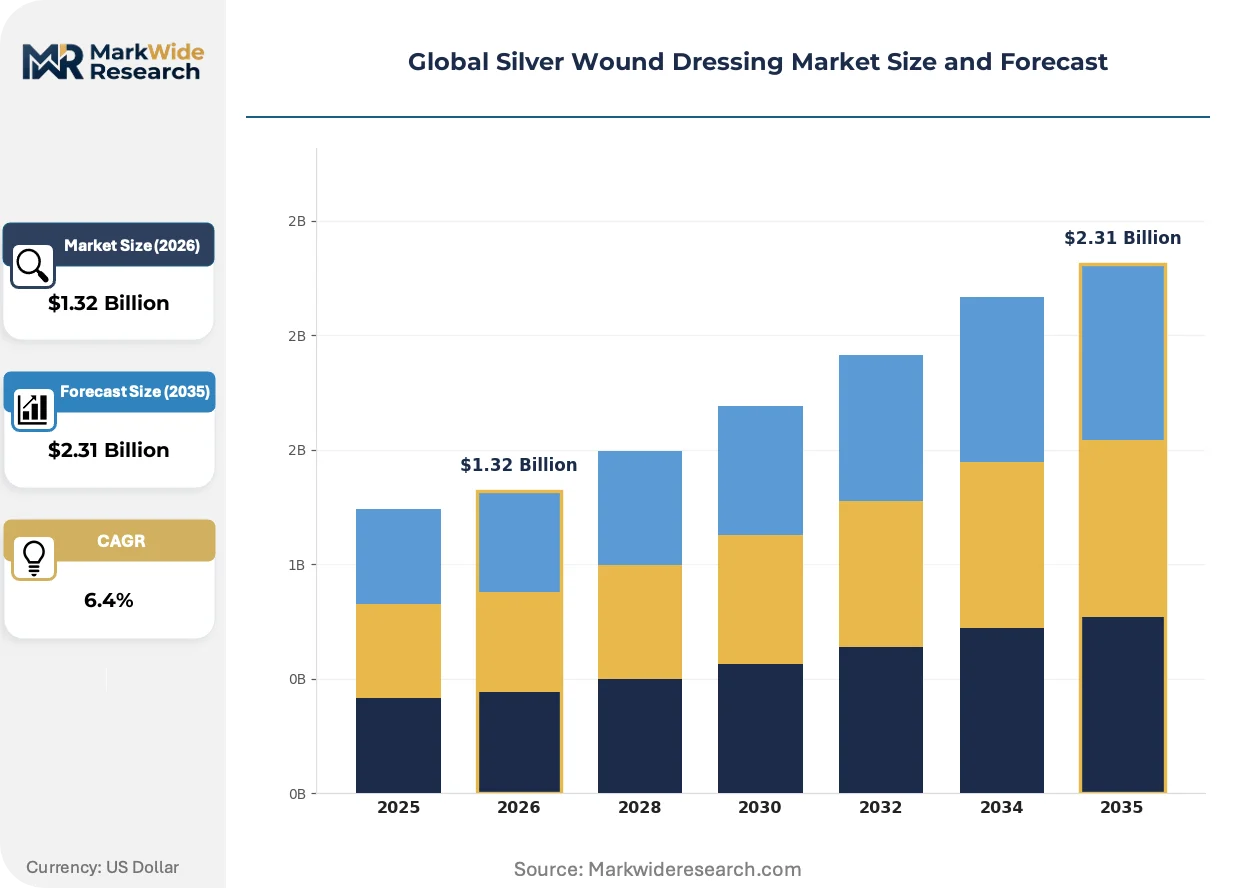
Market Dynamics
The EU Medical Device Regulation is compressing market entry timelines for silver wound dressing manufacturers, forcing portfolio rationalization and accelerated clinical evidence generation ahead of 2027 recertification deadlines.
Growth Catalysts
- Post-acute care protocol tightening:Hospital systems in the United States are mandating antimicrobial dressings for surgical site infection prevention, expanding formulary inclusion of silver-embedded substrates.
- Japan's PMDA silver ion release profiling:This requirement has formalized quality benchmarks that premium manufacturers leverage to differentiate against unverified imports.
- Nanocrystalline silver manufacturing scale-up:Ionic silver integration into hydrofiber substrates is reducing unit costs for chronic wound management applications.
Market Restraints
- Silver price volatility:Industrial metal commodity swings directly compress margin pools for ionic silver and silver sulfadiazine formulations.
- EU MDR notified body capacity constraints:Extended conformity assessment queues are delaying CE marking renewals and freezing new product introductions.
- Antimicrobial resistance surveillance:EMA-coordinated bioburden tracking is raising clinical evidence thresholds for sustained efficacy claims.
Strategic Opportunities
- Home healthcare channel expansion:Reimbursement alignment for outpatient chronic wound care in Germany is opening direct-to-patient distribution models.
- Hydrogel-silver convergence:Rehydration capabilities for dry necrotic wounds and burn care are penetrating underaddressed segments in Japan's aging population centers.
- FDA 510(k) antimicrobial efficacy pathway:Streamlined clearance for ionic silver foam dressings is enabling faster US market access versus EU regulatory timelines.
Industry Challenges
- Biocompatibility testing standard evolution:ISO 10993 updates are forcing reformulation cycles and extended validation timelines for existing product lines.
- Notified body audit intensity:Expanded MDR technical documentation requirements are consuming regulatory affairs bandwidth and delaying pipeline prioritization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silver Wound Dressing Market |
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Adherent Dressings, Hydrogel Dressings, Alginate Dressings, Foam Dressings End User: Hospitals, Home Healthcare, Clinics, Long-Term Care Facilities Distribution Channel: Online Retail, Pharmacy Retail, Direct Sales, Institutional Sales Application: Burns, Surgical Wounds, Chronic Wounds, Ulcers |
| Companies Covered | 3M Company, B. Braun Melsungen AG, Smith & Nephew plc, Cardinal Health Inc., Medline Industries LP, ConvaTec Group plc, Coloplast A/S, Hollister Incorporated, Mölnlycke Health Care AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silver Wound Dressing Market Shifts & Advancements
Silver wound dressing development is pivoting toward substrate-integrated ionic release mechanisms that balance antimicrobial potency against cytotoxicity thresholds, with regulatory compliance emerging as the primary competitive differentiator.
Nanocrystalline silver embedded in hydrofiber matrices is absorbing excess exudate while maintaining sustained ionic release profiles. Burn centers and chronic wound clinics in the United States are adopting these configurations for moist wound healing protocols. This absorption capacity is compressing dressing change frequencies and reducing total cost-of-care calculations against traditional gauze alternatives.
Japan's PMDA silver ion release profiling mandate is reshaping formulation specifications for manufacturers seeking device approval. The requirement for documented release kinetics over 72-hour wear periods is filtering out inconsistent suppliers. Ionic silver foam dressings with verified release curves are capturing preference share in Japanese hospital procurement tenders.
Hospital procurement committees are consolidating vendor relationships around full-line suppliers with integrated manufacturing capabilities. Single-source contracting for antimicrobial dressings is displacing fragmented multi-vendor purchasing in German and US health systems. This concentration is most visible in academic medical centers where supply chain rationalization targets 20-30% SKU reduction.
Global Silver Wound Dressing Market Segmentation
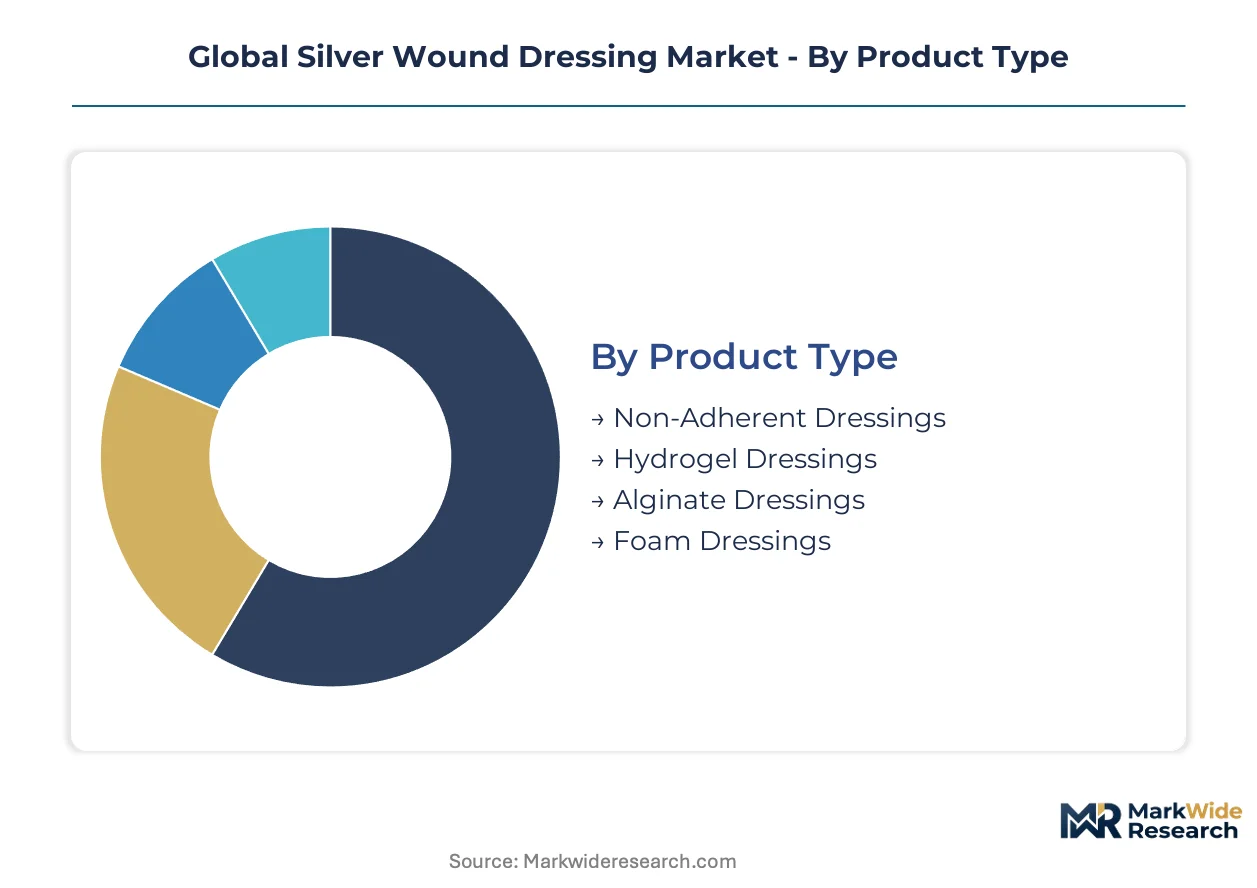
Silver wound dressing segmentation reveals distinct margin profiles across substrate technologies and procurement channels. Hospital formulary decisions increasingly favor integrated foam-hydrogel systems over standalone gauze alternatives, reshaping manufacturer portfolio priorities.
Product Type:
Standalone silver dressings dominate acute care protocols, while embedded ionic systems penetrate outpatient chronic wound management.
- Foam Dressings:Absorbent polyurethane substrates with ionic silver integration handle heavy exudate in surgical and pressure ulcer protocols. Demand concentrates in United States academic medical centers where reduced dressing change frequency justifies premium procurement.
- Hydrogel Dressings:Cross-linked polymer matrices with nanocrystalline silver deliver rehydration for dry necrotic wounds and partial-thickness burns. Japanese burn centers in Osaka and Tokyo are adopting these configurations fastest as PMDA release profiling validates sustained antimicrobial efficacy.
- Alginate Dressings:Calcium-sodium alginate fibers with silver sulfadiazine suit moderate-to-heavy exudate in cavity wounds.
- Non-Adherent Dressings:Silver-impregnated mesh substrates minimize trauma during removal for fragile peri-wound skin.
Volume placements concentrate in Foam Dressings; the faster expansion belongs to Hydrogel Dressings.
End User:
Procurement authority shifts from centralized hospital purchasing toward distributed home health reimbursement systems.
- Hospitals:Inpatient surgical services and wound care centers drive formulary standardization around antimicrobial dressings. German DRG reimbursement adjustments are expanding silver dressing coverage for diabetic foot infections.
- Home Healthcare:Skilled nursing visits for chronic wound management create direct-to-patient distribution opportunities. United States Medicare Advantage plans in Florida and Arizona are piloting remote monitoring bundles with silver dressing shipments.
- Long-Term Care Facilities:Pressure ulcer prevention protocols in nursing homes generate recurring demand for cost-optimized silver foam.
- Clinics:Outpatient wound centers favor rapid-turnover dressing configurations for high patient throughput.
Revenue concentration sits with Hospitals; Home Healthcare is climbing the fastest as reimbursement alignment matures.
Distribution Channel:
Channel selection correlates with end-user scale and regulatory documentation requirements for antimicrobial claims.
- Institutional Sales:Direct contracting with hospital systems enables volume pricing and compliance documentation. United States GPOs are consolidating silver dressing contracts around three preferred suppliers.
- Direct Sales:Manufacturer field representatives serve academic medical centers with complex protocol customization needs.
- Pharmacy Retail:Community and hospital outpatient pharmacies handle post-discharge dressing prescriptions.
- Online Retail:E-commerce platforms penetrate home healthcare segments with subscription replenishment models.
Contract value pools in Institutional Sales; Online Retail is gaining share fastest through chronic patient subscription models.
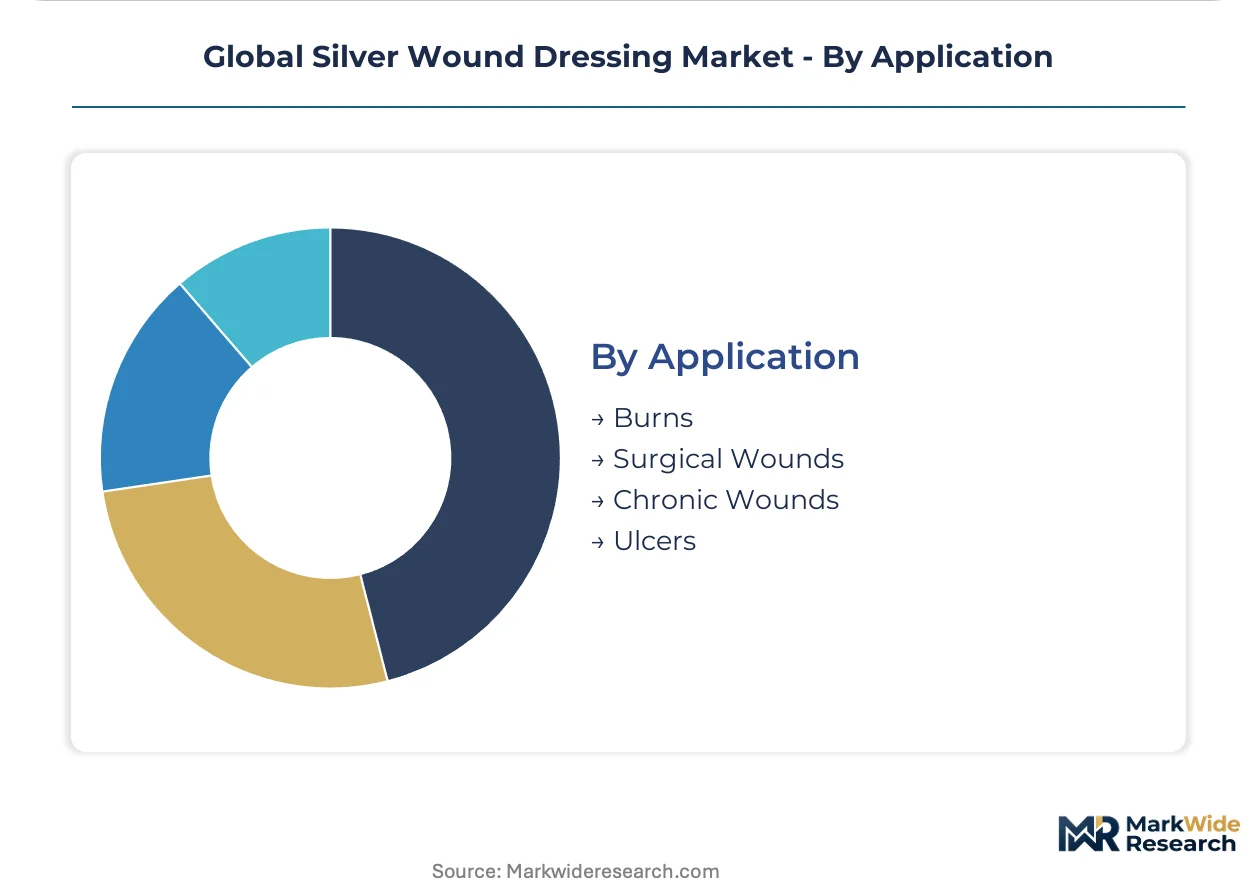
Application:
Wound etiology determines silver ion concentration requirements and substrate selection for exudate management.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers require sustained antimicrobial barriers against polymicrobial bioburden. German outpatient clinics are standardizing silver alginate protocols for Wagner Grade 2-3 lesions.
- Burns:Partial-thickness thermal injuries demand hydrogel silver for rehydration and eschar management. Japanese emergency departments prioritize PMDA-verified release kinetics for pediatric scald injuries.
- Surgical Wounds:Post-operative incision sites utilize silver foam for infection prophylaxis in high-risk patients.
- Ulcers:Pressure ulcers in immobile populations drive institutional procurement of high-absorbency configurations.
Patient volume loads heaviest into Chronic Wounds; Burns application shows steepest expansion trajectory as hydrogel technology advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Ireland and Singapore concentrate silver wound dressing manufacturing through tax-advantaged pharmaceutical device production. Hospital procurement centralization and chronic wound prevalence patterns distribute demand across mature healthcare systems.
United States
Medicare Advantage expansion in Florida and Arizona drives home healthcare silver dressing consumption. FDA 510(k) antimicrobial efficacy pathways accelerate clearance timelines versus EU counterparts. Boston academic medical centers standardize nanocrystalline silver protocols for surgical site infection prevention.
Germany
Diabetic foot ulcer prevalence in North Rhine-Westphalia sustains alginate silver demand. DRG reimbursement adjustments expand silver dressing coverage for Wagner Grade 2-3 lesions. Munich hospital procurement committees consolidate vendor relationships around full-line suppliers.
Japan
Aging population centers in Osaka and Tokyo generate hydrogel silver uptake for pressure ulcer management. PMDA silver ion release profiling mandates filter inconsistent suppliers from procurement tenders. Nagoya burn centers prioritize verified 72-hour release kinetics for pediatric applications.
United Kingdom
NHS supply chain rationalization targets antimicrobial dressing SKU reduction of 20-30%. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR traceability standards. London wound care clinics adopt subscription replenishment models for outpatient chronic management.
Global Silver Wound Dressing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate technology tiers. Market structure consolidates around integrated manufacturers with captive foam and hydrofiber production capabilities. Three archetypes dominate: diversified medical device conglomerates with wound care divisions, pure-play advanced dressing specialists, and contract manufacturers serving private-label brands. Competitive moves center on M&A for substrate technology access and strategic partnerships with hospital GPOs for formulary lock-in.
Among diversified conglomerates, 3M Company and Cardinal Health Inc. occupy positions spanning institutional sales through retail pharmacy channels. Smith & Nephew plc exemplifies the specialist archetype through clinical evidence portfolios navigating expanded notified body requirements. Mölnlycke Health Care AB anchors integrated manufacturing capabilities combining absorbent foam substrates with ionic silver integration.
| Leading Market Players |
|---|
| 3M Company |
| B. Braun Melsungen AG |
| Smith & Nephew plc |
| Cardinal Health Inc. |
| Medline Industries LP |
| ConvaTec Group plc |
| Coloplast A/S |
| Hollister Incorporated |
| Mölnlycke Health Care AB |
| Others |
Supply & Pricing Matrix
Silver metal commodity swings cascade through ionic silver formulation costs into hospital procurement tiers, compressing margins for silver sulfadiazine manufacturers while rewarding foam substrate producers with captive polymer supply.
Pricing Analysis
Short lead-time premiums command 15-25% markups over contract-scheduled deliveries in acute care procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-verified release profiles from unvalidated imports and commodity gauze alternatives. Cost compression in economy alginate tiers is intensifying because Indian API suppliers are expanding silver sulfadiazine output. Home healthcare channels exhibit highest price sensitivity; academic medical centers with GPO contracts show least.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese hydrofiber substrate producers supplying Smith & Nephew and Mölnlycke assembly lines. Manufacturing gravity centers on Ireland, Singapore, and Germany for tax-advantaged pharmaceutical device production. Raw material flows draw from Mexican silver mining concentrates, Indian sulfadiazine API synthesis, and German polyurethane foam chemistry. Tariff exposure on Chinese alginate fiber imports threatens alginate dressing cost structures. Distribution runs through institutional sales direct to hospital GPOs, with pharmacy retail handling post-discharge replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silver wound dressing manufacturing is becoming a vertical-integration race as substrate technology and ionic release profiling determine regulatory approval speed and procurement preference.
For Market Incumbents: To counter EU MDR notified body capacity constraints compressing recertification timelines, Smith & Nephew and Mölnlycke should deepen backward integration into hydrofiber substrate production and accelerate clinical evidence generation for expanded antimicrobial claims. Captive foam manufacturing insulates margin pools from polymer price volatility while accelerating 510(k) submission timelines. For New Entrants and Emerging Players: Skilled nursing facilities in United States Medicare Advantage pilot regions represent the most penetrable buyer archetype for subscription-based silver dressing replenishment. Hydrogel-silver configurations for dry necrotic wounds in Japan's aging population centers offer second white-space target. Direct-to-patient e-commerce with remote monitoring bundles bypasses entrenched GPO contracting. For Investors and Strategic Acquirers: PMDA silver ion release profiling mandate enforcement is the leading indicator that formulation verification capabilities will separate acquireable specialists from stranded commodity players. Five-to-ten year viability favors targets with integrated foam-hydrofiber manufacturing and verified 72-hour release kinetics documentation. Watch for notified body audit backlog clearance rates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR technical documentation investment separates compliant suppliers from frozen competitors in German tenders. |
| Backward Integration into Hydrofiber | Captive substrate production insulates margin pools from Taiwanese supply concentration risk. |
| Hospital System Partnership | GPO formulary lock-in with United States academic medical centers secures volume offtake against fragmented rivals. |
| Reimbursement Strategy | Medicare Advantage alignment in Florida and Arizona unlocks home healthcare subscription revenue streams. |
| FDA 510(k) Antimicrobial Efficacy Submission | Streamlined clearance pathway accelerates United States market access versus EU regulatory queues. |
Research Methodology
Independent corroboration across wound care clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA MDR submission databases, Japanese PMDA approval records, and hospital procurement contract repositories. Bottom-up demand modeling triangulates against top-down market sizing across substrate technology tiers.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include substrate type, end-user channel, wound etiology, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for MDR recertification deadline impacts and PMDA release profiling enforcement intensity. Forecast inputs incorporate silver commodity price trajectory assumptions and notified body capacity expansion timelines.
Revisions become necessary when EU MDR implementation delays extend beyond modeled scenarios or when antimicrobial resistance surveillance triggers clinical evidence threshold elevation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
North America Advanced Wound Care Market
Wound Care
Global Active Wound Care Market
Wound Care
Wound Debridement Products Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Philippines Wound Care Market
Wound Care
Alginate Dressing Market
Wound Care
Wound Closure Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Surgical Dressing Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Advanced Wound Management Market
Wound Care
Dental Wound Dressings Market